
Q3 delivered the widely expected PC downturn, with supply constraints, high price points, and logistical disruption eroding the usual seasonal lift
BOSTON, October 8, 2026 –Worldwide PC shipments fell 20.1% year over year in Q3 2026 to 62.7 million units, according to preliminary results from IDC Research (IDC), the second consecutive decline and a deeper one than the 3.8% drop in Q2. Shipments also slipped 9.1% sequentially, upending the usual pattern in which Q3 outpaces Q2. Continued supply constraints and the inventory pull-in earlier in the year, as vendors and channels rushed to stock up ahead of memory-driven price hikes, left the quarter with little demand to draw on.
What happened in the worldwide PC market during Q3 2026?
During the quarter the channel worked to move through the large volume of PCs shipped in during the previous quarter. As a result, we didn’t see the typical third-quarter seasonal lift in shipment volumes.
“What we’re seeing is the result of the strong first half pull-in. Vendors and channels loaded up on inventory early in the year to get ahead of price hikes, and that has thrown off the usual seasonality, where Q3 is typically larger than Q2,” said Jitesh Ubrani, research director for consumer devices at IDC. “Channels are now worried about carrying too much inventory into a market where high prices are suppressing demand. That could translate into promotions and some short-term relief for consumers, but we don’t expect pricing anywhere near what it was a year ago. Prices will remain elevated. With macro conditions worsening, the risk is that the outlook for the next few quarters gets worse before it gets better.”
Worldwide PC Market at a Glance: Q3 2026
- Total shipments: 62.7 million units (-20.1% year over year, -9.1% from Q2 2026)
- Primary drivers of the decline: Strategic inventory pull-in across the entire industry as a result of on-going supply constraints and higher price points driven by AI data center build out
- Key constraints: Supply issues, elevated prices, worsening macro conditions
- Leading vendors: Lenovo, HP Inc, Dell Technologies, Apple, ASUS
Why did the market change?
The earlier pull-in borrowed volume from the second half. Vendors and channels bought ahead of price hikes, which inflated early year shipments and left Q3 starved of demand. The result is a broken seasonal pattern: the third quarter is normally larger than the second, and this year it fell short.
What is IDC’s outlook?
Channel concern over high inventory and soft demand at elevated prices could bring promotions in the near term, but pricing will stay well above year-ago levels. The bigger risk is macro: conditions have worsened since last quarter, and a weaker economic backdrop could push demand lower and darken the outlook for the remainder of 2026 and into 2027.
Vendor Rankings and Market Share
The pain was not evenly shared. Lenovo, HP Inc, and Dell Technologies all fell faster than the market and together ceded 4.2 points of share as they were likely facing the effects of pull-in from earlier in the year.
| Company | 3Q26 Shipments | 3Q26 Market Share | 3Q25 Shipments | 3Q25 Market Share | 3Q26/3Q25 Growth |
| 1. Lenovo | 14.9 | 23.8% | 19.3 | 24.6% | -22.6% |
| 2. HP Inc | 10.3 | 16.5% | 15.0 | 19.1% | -30.9% |
| 3. Dell Technologies | 7.6 | 12.1% | 10.1 | 12.9% | -25.0% |
| 4. Apple | 5.9 | 9.5% | 6.7 | 8.5% | -11.3% |
| 5. ASUS | 5.5 | 8.7% | 6.0 | 7.6% | -8.6% |
| Others | 18.4 | 29.4% | 21.4 | 27.3% | -14.0% |
| Total | 62.7 | 100.0% | 78.5 | 100.0% | -20.1% |
| Source: IDC Quarterly Personal Computing Device Tracker, October 8, 2026 | |||||
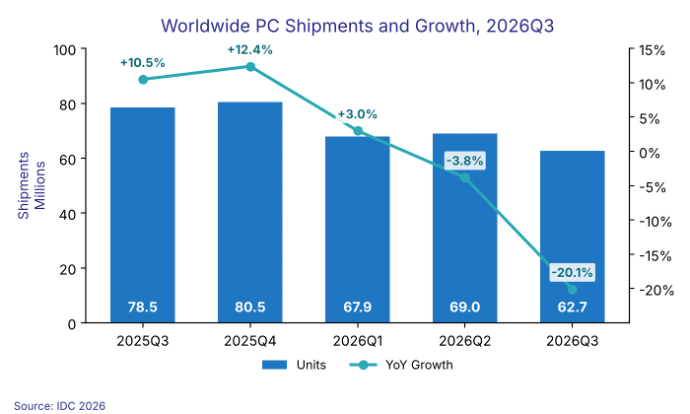
Figure 1. Worldwide PC shipments (millions of units) and year-over-year growth, 2025Q3 to 2026Q3. Source: IDC Quarterly Personal Computing Device Tracker.
Frequently Asked Questions
Why did PC shipments fall in a quarter that is normally stronger?
Vendors and channels bought inventory earlier in the year ahead of price hikes, pulling demand out of Q3. Combined with continued supply constraints, that left the quarter without its usual seasonal lift and pushed shipments below both Q2 and last year.
Will PC prices come down?
Only modestly and briefly. Channels are concerned about high inventory and low demand, so promotions are possible. However, prices are expected to remain elevated and well above where they were at the same time last year.
What risks could impact the market next?
Worsening macro conditions are the main concern. A weaker economy could soften demand further, and with prices still high and supply constrained, the outlook for the remainder of 2026 and going into 2027 could deteriorate.
Notes:
- IDC declares a statistical tie in the Personal Computing Device market when there is a difference of one-tenth of one percent (0.1%) or less in the shipment of shares among two or more vendors. Traditional PCs include Desktops, Notebooks, and Workstations, and do not include Tablets or x86 Servers. Detachable Tablets and Slate Tablets are part of the Personal Computing Device Tracker but are not addressed in this press release.
- Shipments include shipments to distribution channels or end users. OEM sales are counted under the company/brand under which they are sold.
- Numbers are rounded so totals may not equal the sum of the components
IDC’s Worldwide Quarterly Personal Computing Device Tracker gathers detailed market data in over 90 countries. The research includes historical and forecast trend analysis, among other data. For more information or to subscribe to the research, visit https://www.idc.com/data-analytics/tracker/.
About IDC
IDC Research (IDC) is the technology intelligence layer of the AI economy. A global leader in research and data for more than 60 years, IDC’s expert analysts, proprietary datasets, and rigorous methodologies are trusted by business and IT leaders to guide critical business strategies and IT investments. Today, that intelligence is built into the tools and workflows where work gets done with IDC Quanta, making work sharper, teams faster, and businesses harder to beat.
Visit www.idc.com, subscribe to the IDC blog, or follow IDC on X and LinkedIn for the latest industry insights.
-###-
All product and company names may be trademarks or registered trademarks of their respective holders.