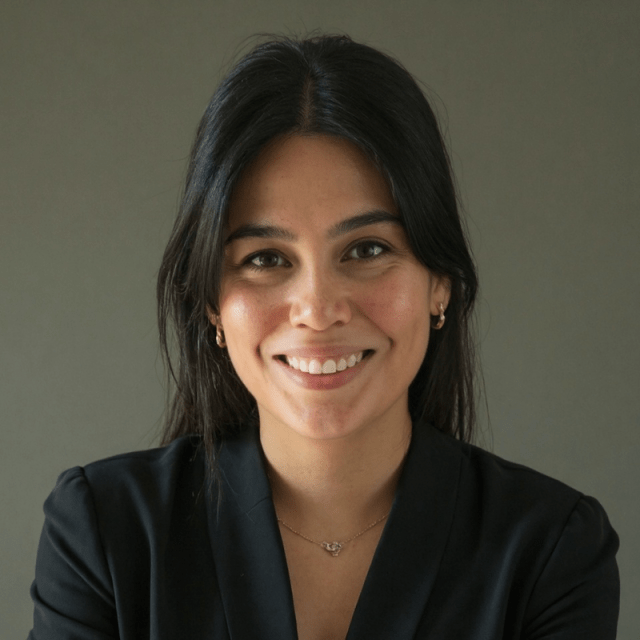
In October 2024, IDC’s FutureScape: Worldwide Cloud 2025 Predictions forecast that by 2026, 75% of organizations would use specialized accelerated cloud computing services to speed up deployment and scale their AI and other accelerated applications. Two years later, Dave McCarthy, Group Vice President of Cloud and Data Center Infrastructure at IDC, says the number still holds and may run a little low.
He reads the 75% as organizations that are somewhere on their AI journey. Two things shifted along the way: some AI work went to private cloud, and the field of providers widened beyond the three hyperscalers.
Watch the full conversation with IDC’s Dave McCarthy below, or keep reading for the highlights.
Why did IDC put a 75% number on it?
McCarthy points to three forces that gave the team confidence.
The first was application modernization. After years in the cloud, companies are revisiting decisions they made inside it, and that now counts as modernization alongside moving a legacy app out of a datacenter.
The second was AI. As McCarthy puts it, “the type of services that you would use for an AI application look very different than the ones that you would use for a more traditional general purpose workload.”
The third was who organizations trusted. When IDC asked which partners were most strategic for AI services, cloud providers typically ranked first.
What played out differently than expected?
Because IDC’s prediction did not specify a type of cloud, it left room for a shift McCarthy describes. Public cloud still appears to be a primary destination because providers make it easy to start and carry the latest hardware and software. Concerns about data privacy and corporate information also drove some AI work into private cloud.
More companies have entered the market, and McCarthy says, “It’s not just the three hyperscalers anymore.” IDC already knew a new class of specialized cloud provider was arriving, he says, but two years ago many of them were bare-bones, handing over hardware to customers with the expertise to use it. IDC did not expect much enterprise adoption outside the big AI labs. Since then, those providers have been building the tooling and support that enterprise workloads need. Capacity pressure adds to the pull: some customers who prefer their usual hyperscaler struggle to get the capacity they want when they want it, and that gives other providers room to fill the gap.
Recent IDC research on specialized cloud services, often called neoclouds, covers one slice of the prediction, since the major hyperscalers also sell GPU-enabled cloud servers. It shows both the pull and the limits:
- In IDC’s AI Tech Trends Survey (July 2026, n=493 in Europe), high performance for specialized workloads was the top reason for using or considering neocloud services, cited by 42% of respondents
- In IDC’s Cloud Pulse Survey, neocloud providers such as CoreWeave, Nebius, Vultr, Lambda, and Crusoe each landed in the middle single digits when organizations named providers important to their cloud strategy over the next two years. The established hyperscalers dominated those road maps.
- IDC’s June 2026 guidance on the neocloud decision advises weighing more than price. Neoclouds generally offer lower GPU pricing, but they typically have fewer datacenter locations and are a poor fit for generic IT workloads.
Does 75% still hold?
McCarthy stands by the number: “I still feel the number is fairly confident… maybe it’s a little bit low in some ways.”
The figure does not mean companies have moved 75% of their workloads to AI. Many organizations reach accelerated compute indirectly, through managed services and tools that run on it behind the scenes, rather than by buying GPU services directly.
IDC’s public cloud IaaS market share research (September 2026) found that the overall market grew 24.6% to $172 billion in 2025, as AI workloads reached production and drove demand for scalable and specialized infrastructure.
What should enterprises watch next?
McCarthy sees the first wave of AI as focused on training. That is changing. “When you hear about AI agents, that’s all inference,” he says, meaning the work of putting existing models into operation.
Inference follows a different deployment pattern than training: it favors infrastructure distributed closer to users and to where data is created. McCarthy notes that some companies once seen as content delivery networks are now retooling themselves as AI inference clouds. The same IDC market share research identifies inference as a growing infrastructure investment area. As enterprises weigh latency, utilization, and cost per inference, that is driving spending on inference-optimized chips and distributed infrastructure.
Whether driven by regulation or corporate governance, McCarthy says, organizations want more control and more specificity about where their AI runs. Two other predictions in the same FutureScape point the same way. IDC expected 50% of organizations to look for network infrastructure providers with sovereign controls by 2026, and 80% of CIOs to rely on cloud providers’ edge services for GenAI inferencing by 2027.
The takeaway: keep your options open
Things are moving fast, McCarthy says, and the cloud choices companies made five or six years ago may look very different today. His advice is to “design for flexibility” and review the options available, because what works best depends on each company’s needs.