国内AIインフラ市場は、いま大きな転換点を迎えています。これまで市場の成長を牽引してきたのは、AIモデルの「学習」を支えるAIインフラ投資でした。しかし今後は、推論を軸とした社会実装フェーズへの移行が進むとIDCではみています。AI活用がPoC(概念実証)から本番運用へと広がる中で、AIインフラの役割や求められる要件も大きく変化しつつあります。IDCでは、2026年を学習から推論への転換点と位置づけています。

1. 急成長する国内AIインフラ市場と「学習中心」からの転換

ここ数年、国内AIインフラ市場は急速な拡大を遂げました。ハイパースケーラーや国内クラウド事業者による大規模投資を背景に、2023年、2024年は共に前年比100%以上の成長を記録し、市場規模は2年連続で倍増以上となりました。国内AIインフラ市場の支出額は2025年には6,946億円に達し、今後は年間平均成長率(CAGR:Compound Annual Growth Rate)7.3%で成長し、2030年には約1兆円規模に迫るとIDCでは予測しています。

一方で、今後の成長を牽引する要因は大きく変化します。これまで中心だった学習用途に加え、業務の中で継続的にAIを活用する推論需要が拡大し、市場の主軸が移行していきます。IDCでは、2027年には国内AIサーバー市場において推論向けの支出が学習向けを上回ると予測しています。また、2025年から2030年のCAGRは推論向けが学習向けを10ポイント以上も上回る予測です。

2. 推論の拡大がもたらすAIインフラ利用の変化

IDCによる最新の調査「Japan Digital and AI Infrastructure Strategies and Investment Survey 2026」では、推論用途で利用予定のAIインフラはパブリッククラウドが過半を占める一方で、専有型インフラやエッジ環境といった「プライベートAIインフラ」も20~30%台に達しています。

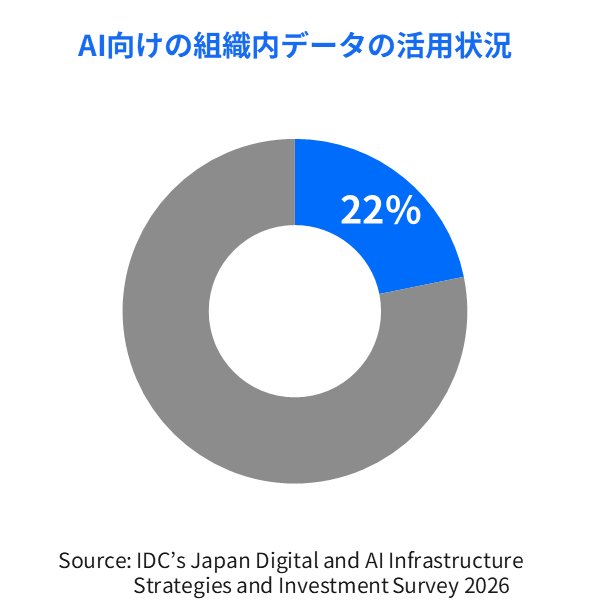
一方で、AI向けに組織内データを本格的もしくは高度に活用している企業は22%にとどまっています。現在は先行企業が中心となって、機密情報や個人情報を含む組織内データの AI での活用に取り組み始めている段階にあることを示しています。

IDCの調査では、こうした先行企業は今後、プライベートAIインフラを利用する意向が強くなっています。その背景には、自社のニーズに最適な構成の採用や、可用性やコストの予測可能性の高さ、さらに、法規制やソブリンAIへの対応を重視していることがあります。事業の安定的な継続性を考慮したうえで、コスト競争力と信頼性の高いAI基盤の整備を進めています。

  • AI向けに組織内データを本格的もしくは高度に活用している企業は22%にとどまっている。
  • 組織内データ活用の先行企業は、コストの競争力と予測可能性を向上し、ソブリンAIも考慮した信頼性の高いAI基盤の整備を進めるために、今後、プライベートAIインフラを利用する意向が強い。

AIインフラが国家戦略や企業競争力にも直結する基盤となるにつれて、ソブリンAIやデータ主権への対応も重要視されます。データの保護や所在管理、地政学リスクへの備えといった観点から、専有環境やソブリンクラウドの活用も拡大する見通しです。

3. AIインフラ向けサービス市場の拡大と競争軸の変化

AIインフラの導入拡大に伴って、構築・運用・保守を担うITインフラサービス市場も急成長しています。国内AI向けITインフラサービス市場は2025年の957億円から2030年には2,320億円へと拡大し、CAGRは19.4%に達する見込みです。AIインフラは設計や運用が高度化しており、液冷対応やデータセンター設備を含めた専門的な対応が求められることが、サービス需要を押し上げています。

市場の競争軸は、従来のハードウェア性能中心から、柔軟なインフラ選択やサービス提供能力、AIの本番実装を支援する総合力へとシフトしています。これまでは高性能GPUを軸としたAIインフラ製品や構築・運用サービスで先行したベンダーが市場を牽引してきましたが、今後はAI導入からアプリケーション開発、ハイブリッド環境の構築・運用、さらにはソブリンAI対応までを包括的に支援できる企業が競争優位を確立するとIDCはみています。

IDCが提供するレポートのご紹介

IDCでは、国内AIインフラ市場の変化を詳細に分析したレポートを発行しています。

本調査レポートでは、国内AIインフラ市場の構造変化を把握するため、2025年から2030年の市場予測をセグメント別に分析しています。サーバー/ストレージ別、サービスプロバイダー/エンタープライズ別、配備モデル別、産業分野別に加え、AIサーバー市場について、学習/推論別やアクセラレーテッド/ノンアクセラレーテッド別に予測しています。

また、国内AI向けITインフラサービス市場についても、顧客タイプ別およびサービスタイプ別に予測しています。さらに、AIインフラ需要の変化や主要ベンダーの動向も整理しており、今後の市場機会や競争環境の変化を明らかにしています。

これらの分析によって、学習から推論へのシフトに伴うAIインフラの需要構造の変化や、サービスプロバイダーとエンタープライズの投資動向の違い、今後拡大するサービス市場の機会を包括的に把握できます。

関連する調査やご相談について

より詳細なインサイトや市場動向については、当社アナリストへお気軽にご相談ください。

Yukihisa Hode - Research Manager, Infrastructure & Devices, Research, IDC Japan - IDC Japan

Yukihisa Hode is a research manager covering digital infrastructure strategies as well as AI infrastructure, IT infrastructure services, IT operations, hybrid/multicloud and hyperconverged infrastructure (HCI). He leads the research program on digital infrastructure strategies, providing insight and advice on the digital infrastructure through research reports, marketing content, and presentations to support IT and digital decision-making.

近两年,具身智能正成为人工智能领域的重要发展方向,并推动机器人产业进入新一轮创新周期。从技术探索走向商业落地,越来越多企业开始关注具身智能机器人。然而,在产业热度持续升温的同时,一个更为关键的问题也逐渐凸显:企业用户真正需要什么样的机器人?

为了更好理解市场需求,IDC对中国企业用户进行了专项调研,从企业认知、应用需求、采购意愿和落地挑战等多个维度进行分析。总体来看,中国企业用户对具身智能机器人与人形机器人等新兴方向保持较高关注,并已开展试点探索,普遍看好其在中长期通过灵活协作和高场景适应性释放应用价值。

企业整体态度偏积极,正从关注走向探索

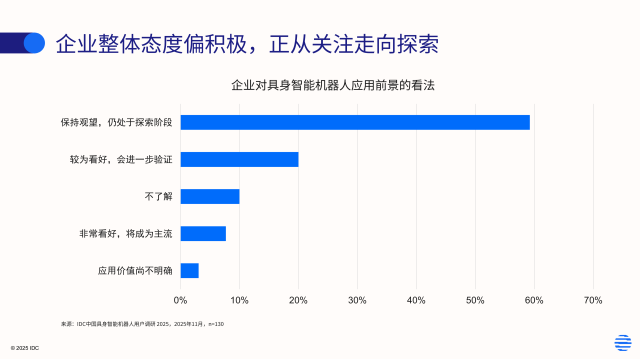
从企业整体态度来看,当前市场呈现出以“关注与探索”为主的结构。约27.7%的企业已表达出明确的积极态度,超过一半的企业虽仍处于观望阶段,但已开始关注并评估相关技术。

这一结构符合新技术商业化早期特征:少数企业率先布局,更多企业处于验证与观望阶段。随着技术成熟度提升及应用案例的不断积累,企业对具身智能机器人的接受度有望进一步提升。

感知能力优先提升,执行与安全能力成为关键支撑

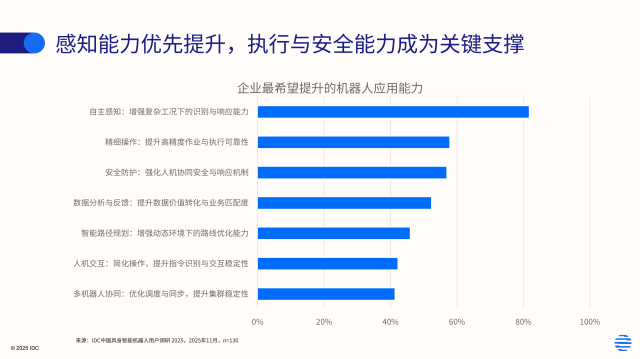
在能力需求方面,企业对具身智能机器人的优化方向呈现出明显的递进结构:首先是环境感知能力,以实现“看得清、反应快”;其次是执行与安全能力,确保“做得准、运行稳”;在此基础上,再逐步向决策与协同能力升级,推动机器人向更高水平的智能化发展。

这一趋势表明,具身智能机器人的能力演进正从单点能力优化,走向“感知—执行—决策”一体化能力体系。

企业选型更加理性:可靠性、ROI与生态能力成为核心

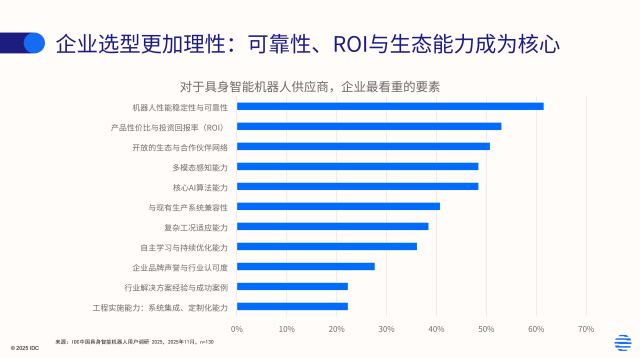
在具身智能机器人供应商选择方面,企业最看重的三大因素分别是:设备稳定性与可靠性(61.5%)、产品性价比与投资回报率(53.1%)以及生态与合作伙伴网络(50.8%)。

与此同时,具身智能相关技术能力同样受到高度关注。约48.5%的企业关注核心AI算法能力与多模态感知能力,说明企业在关注硬件性能的同时,也 持续重视机器人在感知、决策与协作方面的智能化水平。

与此同时,企业对具身智能技术能力关注度持续提升。近半数企业看重核心AI算法与多模态感知能力,表明其在关注硬件性能的同时,也重视机器人在感知、决策与协作方面的智能化水平。

整体来看,企业在评估具身智能机器人供应商时,正在从单纯的硬件性能评估,逐步转向综合能力评估,包括设备可靠性、投资回报、智能化能力以及生态协同能力等多个维度。这一结果表明,当前企业在选择具身智能机器人供应商时呈现出 “可靠性优先、经济性驱动、智能化能力并重” 的特点。

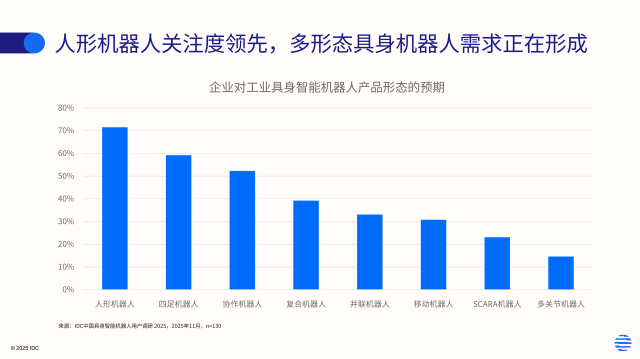
人形机器人关注度领先,多形态机器人需求正在形成

从期望形态来看,人形机器人获得了最高关注度。用户对引入人形机器人的核心期望集中在仓储物流(76%)、生产制造(68%)、安防巡检(51%)等对人力依赖度高、任务标准化程度强的领域,期望其通过承担重复性、高强度或高风险工作,释放人力资源并提升整体运营效率。

同时,中国工业企业用户对具身智能机器人载体形态的需求正呈现出多样化趋势。除人形机器人外,四足机器人与协作机器人等在特定场景中同样具备较高应用价值。未来,多形态并行发展有望成为具身智能机器人市场的重要特征。

资产化采购仍占主导,RaaS模式加速渗透

从采购模式来看,直接购置仍是主流方式(54.6%),多数企业仍将机器人作为固定资产进行投资与管理。

分企业规模来看,小型企业更倾向于一次性购置,而中大型企业对融资租赁的接受度更高(39.4%),体现出其在资本支出上的灵活性与金融工具应用能力。

相比之下,RaaS模式正处于加速发展阶段(12.3%),较2024年的6%实现显著提升。尽管整体渗透率仍有提升空间,但企业已开始逐步接受按使用付费的模式,随着服务体系、计费模式及运维能力的持续完善,RaaS有望进一步加快普及。

三个值得关注的产业趋势

趋势一:工业率先验证规模化路径,多场景应用同步推进

具身智能机器人的商业化落地将呈现“分场景推进”的特征。其中,制造与物流等工业场景由于具备更强的标准化程度与明确的投资回报,更有可能率先跑通规模化应用路径。

与此同时,服务类场景(如导览迎宾、康养服务等)也在持续推进,但更依赖交互体验与场景适配能力,其落地节奏与路径将有所不同。

趋势二:多任务能力成为具身智能机器人规模化应用的关键门槛

机器人竞争正在从“能否完成单一任务”,转向“能否适应多任务与复杂环境”。单点能力已难以支撑企业长期投入,企业更关注机器人在不同任务与场景间的复用能力。

趋势三:产业竞争向生态迁移,体系化能力成为核心竞争力

随着应用复杂度提升,机器人已不再是单一硬件产品,而是融合AI模型、软件平台与系统集成的综合解决方案。企业对生态能力的重视,意味着厂商竞争正从“产品”走向“体系”。

整体来看,具身智能机器人正进入从“技术验证”走向“规模落地”的关键阶段,场景突破、能力升级与生态构建将成为产业演进的三大主线。

本文核心观点来源:

 《具身智能与人形机器人:中国工业落地新机遇》(Doc# CHC53325326,2026年2月)

《中国具身智能机器人应用市场分析与典型应用实践,2025》(Doc# CHC53183625,2025年12月)

具身智能机器人正从技术探索迈向商业落地,中国企业在认知、需求与采购模式上的变化,正在深刻影响这一新兴市场的演进方向。IDC将持续追踪具身智能及机器人领域的最新动态,深入洞察用户需求变化与产业趋势。如需获取更多报告详情、数据洞察或安排分析师访谈,欢迎随时与我们联系。

如需进一步了解与研究相关内容或咨询 IDC其他相关研究,请点击此处与我们联系。

Geopolitical crises rarely arrive with clear warning. When they do, the pressure on digital infrastructure, supply chains, and technology operations becomes immediate. 

The war in the Middle East is a structural stress test for the modern digital economy and for the CIOs responsible for keeping businesses running through disruption. 

Unlike earlier periods of conflict, today’s enterprise IT environment depends heavily on cloud infrastructure, subscription-based services, and globally interconnected supply chains. Disruption is no longer contained. It can extend quickly across regions, systems, and partners. 

For CIOs, the challenge is not only managing risk. It is sustaining operations while adapting to changing conditions and maintaining the ability to support the business.

IDC Perspective: From Conflict to Continuity: How CIOs Can Respond to Disruption from the Middle East War.

Why this crisis is different for CIOs 

Enterprise IT has shifted from internally controlled environments to highly distributed ecosystems. 

Organizations now depend on: 

  • Cloud providers and platform services  
  • Distributed infrastructure and operations  
  • Global supply chains for technology components and delivery  

This dependency introduces new forms of exposure. 

Regional instability can affect: 

  • Application availability and performance  
  • Hardware deployment timelines  
  • Cyber threat activity  
  • Infrastructure and energy costs  

These pressures are already testing the assumptions built into many digital strategies. 

The priority for CIOs is to understand where exposure exists and how it could affect operations. 

Start with exposure mapping and scenario planning 

The first step is to identify where the organization is most exposed. 

CIOs should map dependencies across four dimensions: 

  • Employees and contractors located in or near affected regions  
  • Customers and revenue streams tied to impacted markets  
  • Suppliers and logistics routes connected to disrupted corridors  
  • Applications, data, and support operations dependent on regional infrastructure  

This exposure map becomes the foundation for decision making. 

Scenario planning builds on that foundation. It provides a structured way to prepare for multiple outcomes rather than relying on a single forecast. 

IDC outlines two scenarios that CIOs should actively consider: 

  • A period of sustained regional instability  
  • A broader escalation that introduces energy and cyber shocks  

Each scenario changes how organizations prioritize resilience, security, and investment decisions. 

See how the Middle East conflict is reshaping global IT spending.

What CIOs should prioritize now 

CIOs should focus on five immediate priorities. 

Revalidate cloud and infrastructure resilience 
Assess dependency on single regions or providers and identify gaps in failover readiness. 

Strengthen cyber readiness 
Expect increased threat activity and reinforce detection, response, and recovery capabilities. 

Diversify technology supply chains 
Identify potential points of disruption and reduce reliance on single suppliers or routes. 

Review data sovereignty and compliance exposure 
Geopolitical tension often accelerates data localization and regulatory requirements. 

Prepare workforce continuity plans 
Ensure employees and teams can continue operating under disrupted conditions, including remote work and alternative communication channels. 

These priorities are not new. What is changing is the need to address them simultaneously and at speed. 

Leading through disruption 

Resilience is not only a technical challenge. It is a leadership challenge. 

CIOs must provide clarity and direction during periods of uncertainty. The organizations that respond most effectively are those where teams understand the mission and are able to act quickly. 

Effective leadership actions include: 

  • Establishing a clear operational focus on protecting critical systems  
  • Enabling faster decision making across teams  
  • Breaking large challenges into manageable objectives  
  • Identifying opportunities to simplify and strengthen existing environments  

Periods of disruption often accelerate changes that were already needed. They expose technical debt, operational inefficiencies, and gaps in resilience. 

The organizations that make progress during these moments treat disruption as a point of action rather than a pause. 

Explore the Middle East conflict resource center.

From disruption to operational readiness 

The current environment reflects a broader shift in how geopolitical events interact with digital operations. 

CIOs are no longer preparing for isolated incidents. They are operating in conditions where disruption can affect multiple parts of the enterprise at the same time. 

This requires a more continuous approach to resilience: 

  • Ongoing visibility into dependencies and risk exposure  
  • Planning that accounts for multiple possible outcomes  
  • Integration of resilience into everyday operations  

Organizations that build this capability will be better positioned to sustain performance through uncertainty. 

Explore the full scenario framework 

Understanding exposure is the starting point. Acting on it requires a structured approach. 

The IDC Perspective expands on these scenarios and outlines how CIOs can translate them into operational decisions, including: 

  • Scenario-specific implications for IT spending and AI investment  
  • Infrastructure, cybersecurity, and workforce continuity considerations  
  • Key risk signals to monitor as conditions evolve  

Want deeper insight into how these shifts are affecting technology investment? Watch how the Middle East conflict is reshaping global IT spending.

Rick Villars - Group VP, Worldwide Research - IDC

Rick is IDC's chief analyst guiding research on the future of the IT Industry. He coordinates all IDC research related to the impact of Cloud and the shift to digital business models across infrastructure, platforms, software, and services. He helps enterprises develop effective strategies for using their diverse portfolio of cloud investments and applications. He supplies early guidance on implications of critical innovations such as the shift to cloud-based control platforms for deploying/managing infrastructure, data, and code delivery as well as the emergence of AI as a critical IT workload and part of all IT products/services.

Daniel Saroff - GVP, Consulting and Research Services - IDC

Daniel Saroff is Group Vice President of Consulting and Research at IDC, where he is a senior practitioner in the end-user consulting practice. This practice provides support to boards, business leaders, and technology executives in their efforts to architect, benchmark, and optimize their organization's information technology. IDC's end-user consulting practice utilizes our extensive international IT data library, robust research base, and tailored consulting solutions to deliver unique business value through IT acceleration, performance management, cost optimization, and contextualized benchmarking capabilities.

Lars Goransson - Vice President, Research, Worldwide Services - IDC

Lars Goransson is Vice President of Research, Worldwide Services at IDC. He leads IDC’s global research and advisory for IT and business services, focusing on how technology suppliers and buyers can navigate market shifts, innovation, and business transformation. Lars’s research explores the evolving dynamics of the worldwide services landscape, providing clients with trusted tech intelligence and evidence-based insight to make confident decisions in a fast-changing digital economy. His work illuminates the path forward for organizations seeking to anticipate demand, validate investments, and seize new opportunities.

Linus Lai - Group Vice President, Research - IDC

Linus Lai is a distinguished member at IDC Asia/Pacific, in which he spearheads research in digital business, trust, infrastructure, and services. With over 25 years of industry experience, Linus is based in Sydney and serves as the chief analyst for Australia and New Zealand (ANZ). He is a founding member of IDC's Emerging Technology Advisory Council and a respected senior member of the region's CIO100, CSO, and Future Enterprise awards. In his role, Linus provides strategic insights for digital leaders and the technology sector, focusing on sourcing strategies and emerging technology across Asia/Pacific. His expertise has earned him numerous accolades for his contributions to country, regional, and quality research. Previously, as the head of research in Southeast Asia, Linus was instrumental in expanding IDC's presence and influence in the region. His thought leadership is frequently sought after through regular features in various publications and media outlets. He is also a prominent speaker at industry forums, keynote events, and strategy workshops. Before joining IDC, Linus worked with a leading outsourcing service provider with a digital banking focus. He holds a Master of Science degree from the University of Lincoln, United Kingdom.

Mary Johnston Turner - Research VP - IDC

Mary Johnston Turner is Research Vice President within IDC's worldwide infrastructure research organization and global research lead the Digital Infrastructure Strategies practice. Mary's coverage tracks enterprise tech buyer sentiment related to compute, storage, edge, operations and cloud platforms and deployment models. Current research priorities emphasize the impact of rising requirements for data-driven AI-Ready Infrastructure, Fit-for-Purpose Hybrid and Multicloud Architectures, Autonomous Operations, Edge Integration, and collaborative business and IT governance. Her practice emphasizes the voice of the enterprise customer, based on surveys and in-depth analysis of best practices and infrastructure investment priorities. Mary's research emphasizes consideration of topics related to AI-ready infrastructure, tech debt avoidance, data center modernization, mainframe modernization, infrastructure governance, staffing and skills priorities, and infrastructure operating models. Within the infrastructure research organization, Mary collaborates with other practice leads to ensure coherency and alignment of insights and published research.

Laurie Buczek - GVP, Research - IDC

Laurie Buczek is the Group Vice President of Executive Insights at IDC, where she spearheads the global research initiatives that shape the industry's understanding of digital business transformation, evolving buying behaviors, and technology investments. She leads IDC's premier research practices, including the CMO Advisory Practice, C-Suite Tech Agenda, and Digital to AI Business Transformation. As the principal analyst for the CMO Advisory Practice, Laurie advises senior marketing leaders on driving business growth through deeper customer connections and the strategic evolution of the marketing function, with a keen focus on AI's transformative impact. Her expertise and thought leadership empower executives to navigate the intersection of technology, business strategy, and customer engagement in today's dynamic digital landscape.

Michelle Abraham - Sr. Director, Research Cybersecurity - IDC

Michelle Abraham is a Senior Research Director in IDC's Security and Trust Group responsible for the Security Information and Event Management (SIEM), Exposure Management and Related Artificial Intelligence Technologies practice. Ms. Abraham's core research coverage includes SIEM platforms, exposure management platforms, attack surface management, breach and attack simulation, cybersecurity asset management, and device vulnerability management alongside AI-related security topics.

Craig Robinson - Research Vice President , Security Services - IDC

Craig Robinson is a Research Vice President within IDC’s Security Services research practice, focusing on managed services, consulting, and integration. Coverage areas include Managed Detection and Response services, Cyber Resilience, and Incident Readiness & Response services.

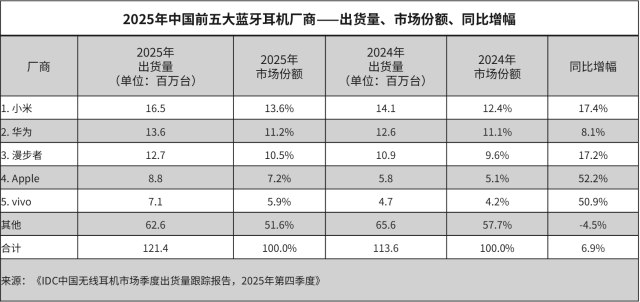
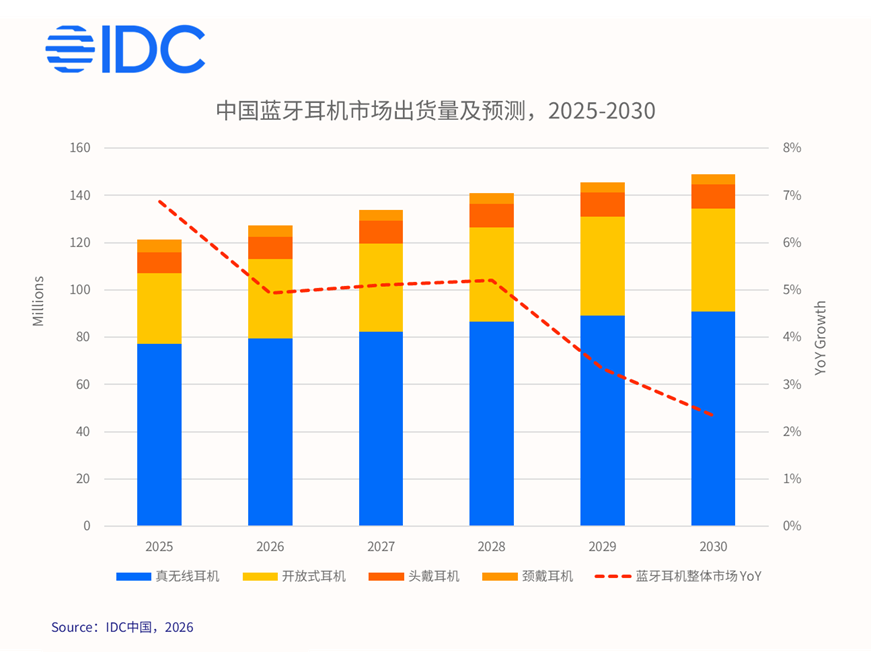
近年来,中国蓝牙耳机市场在经历高速增长后逐步进入结构调整阶段。国际数据公司(IDC)最新发布的《中国无线耳机市场季度出货量跟踪报告,2025年第四季度》显示,2025年,市场出货量达到12,137万台,同比增长6.9%。在整体温和增长的表象之下,产品形态、竞争主体与用户需求正同步发生深层次变化,行业正从规模扩张转向结构优化与价值重塑。

从竞争格局来看,生态协同能力持续强化,手机厂商进一步巩固主导地位;从产品演进来看,开放式耳机在经历高速增长后进入分化发展阶段,增速放缓,同时耳机行业的场景细分化趋势进一步深化;与此同时,AI技术加速渗透,虽仍处于早期探索阶段,但已成为厂商布局差异化的重要方向。基于IDC最新数据与市场观察,本文将对当前市场变化进行解读,并对未来发展趋势与厂商策略提出洞察与建议。

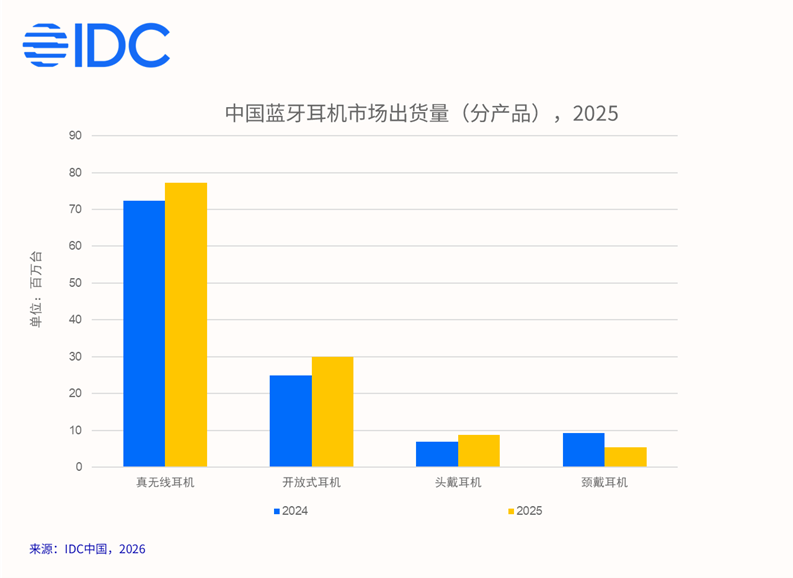
2025年中国蓝牙耳机市场,真无线产品出货7,721万台,同比增长6.7%,入门级产品及与手机绑定的出货政策带动增长。开放式产品出货2,996万台,同比增长20.2%,开放式已从快速爆发阶段逐步转向稳健增长阶段,其中细分市场呈现出不同的发展结构。头戴产品出货878万台,同比增长26.3%,电竞,学习等场景带动入门级市场增长。颈戴产品继续下滑,厂商资源收缩,叠加使用场景被替代。

2025年中国蓝牙耳机市场Top 5厂商表现

小米

25年小米蓝牙耳机出货量位居中国市场首位。厂商持续深耕真无线入门级市场,Redmi系列产品形态丰富,迭代节奏稳定,依托高性价比优势与手机生态协同效应,实现了强劲的业务增长。

华为

华为发力布局开放式赛道,拓展耳挂形态并推出耳夹迭代机型,25年其开放式耳机在内部出货份额中提升10个百分点。FreeClip耳夹系列将时尚饰品属性与音频功能结合,在佩戴体验与使用场景上实现创新突破。同时,真无线SE系列持续夯实品牌在入门级市场的竞争力。

漫步者

漫步者依托多子品牌矩阵,在时尚,电竞,性价比等细分赛道实现多系列产品并行布局与快速迭代,覆盖多元消费场景。头戴耳机作为漫步者传统优势品类,25年持续发力,同时通过子品牌快速布局开放式耳夹,耳挂产品。

Apple

Apple推出AirPods 4双版本产品矩阵,有效拉动整体出货量增长,且助力半入耳主动降噪市场增长。9月AirPods Pro 3 上市完成旗舰迭代,进一步巩固其在真无线高端市场的领先优势。

vivo

25年vivo在真无线市场持续推进双品牌差异化布局,vivo耳机聚焦全场景综合体验,iQOO耳机主打电竞性能与高性价比,厂商整体出货量实现稳步增长。其中,vivo TWS A4 依托手机核心渠道优势,出货量实现显著提升。

从头部厂商表现和数据看洞察:2025年中国蓝牙耳机市场三个核心洞察

洞察一:生态协同成核心竞争力,手机厂商主导地位持续巩固

2025年手机厂商在中国蓝牙耳机市场的出货份额占比达48%,较2024年提升7个百分点。其中,中国手机厂商借助与手机的捆绑销售,礼盒赠送等营销模式,依托自身成熟的手机渠道体系,实现蓝牙耳机出货量的显著增长,进一步巩固其市场地位。

洞察二:开放式耳机步入结构分化阶段,增速趋缓但格局重构

2025年开放式耳机出货量同比增长20.2%,其中耳夹增速领先,同比增长51.0%,耳挂同比增长12.3%。耳夹在华为,韶音等头部品牌引领下推进高端化升级,同时通过更新配色,推出联名耳饰等方式,持续强化其时尚饰品属性。耳挂此前受电商低价产品冲击,高端化发展承压。2025年随着手机品牌入局且聚焦中高端市场,行业格局迎来优化调整,当前耳挂产品仍以运动场景为核心定位。

洞察三:AI概念热度攀升,厂商跟风搭载AI相关能力

随着AI概念升温,耳机厂商纷纷将AI能力作为产品差异化卖点加速布局。其中,传统音频硬件厂商受自身研发实力限制,多通过与第三方大模型合作落地AI功能。从应用场景来看,当前AI功能布局较为单一,主要集中在翻译,会议记录等工作场景,AI整体应用仍处于浅层阶段。

2026年中国蓝牙耳机发展趋势展望

趋势一:场景化深度细分,耳机从通用产品转向专属化工具

预计26年蓝牙耳机市场竞争核心由参数硬件比拼,转向用户场景需求的精准满足。在运动,睡眠,办公,游戏等主流场景基础上,细分需求持续扩容,产品将针对不同场景,打造高度专业化的形态与功能,并进一步推动一人多机的消费趋势。

趋势二:悦己消费与她经济驱动产品美学与情感化体验升级

悦己消费趋势凸显,女性消费群体成为蓝牙耳机市场的核心增长动力之一,颜值与使用体验并重的需求逐步取代基础音频功能,成为她经济下的重要消费特征。品牌加速打破电子产品中性化刻板印象,聚焦情感化设计与佩戴体验。随着耳机使用场景与时长持续拓展,产品价值由实用功能,延伸至情感陪伴与生活方式表达。

趋势三:技术迭代推动蓝牙耳机向智能硬件加速演进

未来随着AI,连接与低功耗技术持续升级,蓝牙耳机将逐步搭载更高算力芯片与轻量化智能系统,向具备本地AI能力,部分场景独立交互的智能硬件方向靠拢,减少对手机的依赖。当前芯片算力,电池续航与功耗仍是行业需持续突破的瓶颈。与此同时,开放式耳机凭借舒适,可长时间佩戴的特性,有望成为AI智能硬件的重要载体之一。

结合蓝牙耳机市场2025年的市场洞察与2026年的市场趋势,IDC为行业参与者提出以下三点建议:

建议一:突破技术同质化,构建差异化核心竞争力

摆脱单纯比拼硬件参数与价格竞争,推动技术研发从参数竞争转向场景定义。聚焦自身优势细分领域,强化用户体验感知。同时,摒弃单一产品思维,构建覆盖不同需求的产品矩阵,兼顾性价比与情价比,形成独特的品牌竞争壁垒,规避同质化竞争风险。

建议二:融合渠道体验,实现分平台精准触达

线上依托内容电商与直播带货,强化场景化内容传播,利用大数据实现用户精准匹配。线下深化与运营商,潮品店及品牌体验店的合作,构建沉浸式体验场景,提升实操感知与品牌认知。针对悦己消费与她经济趋势,在年轻化平台开展差异化沟通与场景营销,精准覆盖目标用户群体。

建议三:深耕AI功能融合,打造场景化智能体验优势

把握AI技术与蓝牙耳机产业深度融合的行业趋势,摒弃将AI功能作为营销噱头的功利化发展模式,推动AI功能从基础交互层面向场景化赋能方向升级,聚焦用户核心使用需求,让AI技术真正落地到实际应用场景中。

分析师观点

IDC中国研究经理戴翘楚认为,2025年蓝牙耳机市场已显现出生态协同与AI概念驱动的竞争格局,手机厂商主导地位强化。展望2026年,市场将加速向场景化细分和情感化体验转型。厂商需摆脱同质化竞争,通过技术深耕与渠道融合,将AI能力转化为真正的场景化智能优势,把握行业发展机遇。

IDC将持续跟踪中国蓝牙耳机市场及相关技术演进,提供数据支持与前瞻洞察,助力企业制定更具针对性的产品与市场策略。如您希望进一步了解市场数据、竞争格局或定制化研究服务,欢迎随时与IDC保持联系。

如需进一步了解与研究相关内容或咨询 IDC其他相关研究,请点击此处与我们联系。

IDC’s Smart City North America Awards program has recognized public safety innovation since its inception, and this year’s competition brought in some of the strongest entries yet. Across the public safety category, five cities and one regional airport demonstrated how they built operational capability around constrained budgets, growing service demands, and the evolving capabilities of artificial intelligence and unmanned systems.

AI adoption challenges in public safety

Given the focus on AI in many of the award nominations, the following data points from IDC’s U.S. Government Buyer Intelligence survey provide important context for the city summaries below:

  • First, data privacy and security concerns ranked highest, with 52% of respondents citing them as a central issue. Budget constraints and digital infrastructure gaps tied for second, each noted by 44% of public safety respondents—significantly higher than the rest of government. Half of public safety agencies allocate just 6–10% of total IT spend to AI, leaving little room for expansion. This makes integration both more critical and more difficult to fund.
  • Second, 48% of public safety agencies name data privacy and security as their top AI security priority, compared with 39% across the rest of government—a 9-point gap. AI-generated misinformation (44%) and audit and accountability (42%) round out the top concerns. Agencies that produce evidence for legal proceedings and operate under civil rights oversight are right to prioritize data privacy and security.
  • Third, public safety agencies are struggling to scale. Eighteen percent have not attempted to scale any AI initiative—almost four times the rate of other government agencies.

Against that backdrop, this year’s winners did what our survey data confirms is rare: they integrated next-generation technologies across systems most agencies leave disconnected, governed them with genuine accountability structures, and measured results against operational outcomes that justified the investment. Drumroll, please…

The 2026 award entries

The headline this year belongs to Scottsdale, Arizona, which took home the Overall Winner award—the top distinction across all categories—for its AI-Powered Real-Time Crime Center with Drone-as-First-Responder program.

The program’s strength is integration: Scottsdale’s Real-Time Crime Center brings together more than 5,800 cameras, citywide license plate recognition, gunshot detection, body-worn cameras, and drone-as-first-responder capabilities into a unified intelligence platform. When a 911 call comes in, drones deploy first, delivering aerial and thermal imagery to officers before they arrive on scene. The system has logged more than 70 drone missions and supports thousands of incidents annually.

Equally notable is the governance model: the system activates only on verified incidents, with no blanket surveillance and full audit trails.

The Public Safety category winner was the Phoenix Police Department, recognized for its Unmanned Aerial Systems Program—a methodical, department-wide buildout that has grown from 11 pilots at launch in 2022 to a fully staffed unit in 2026.

PPD flew more than 12,500 missions in its first two years, covering everything from search warrant service and surveillance of violent offenders to crime scene documentation and major event overwatch. The program began as a collateral-duty assignment and matured into an embedded patrol capability, with 24/7 coverage launched in late 2025 and beyond-visual-line-of-sight operations planned for 2026. The department made a clear case for cost-effectiveness: fewer officers managing more complex situations more safely, with measurable reductions in overtime reliance.

Scalable innovation in practice

The finalists round out a strong field. Phoenix also entered its Real-Time Operations Centers—two precinct-based intelligence hubs established in 2023 that support patrol officers with live camera feeds, gunshot detection analysis, license plate data, and rapid criminal history checks. From January 2024 through mid-2025, the RTOCs helped recover 369 stolen vehicles, recover 191 firearms, and process more than 7,900 intelligence requests.

Mesa’s Police Department took a different angle on the AI question, applying it to the unglamorous (but consequential) work of crime classification. Mesa processes more than 66,000 incident reports annually for federal NIBRS (National Incident-Based Reporting System) compliance—work that previously required an 11-person team and still produced a chronic two-week backlog.

A proof-of-concept AI classification system processed 60,000 historical cases and achieved roughly 90% consistency with human analysts, with full audit trails on every decision. Mesa projects saving 15,000 analyst hours annually. The system also helped leadership identify an anomaly in aggravated assault data that turned out to be a reporting methodology artifact, not a real crime trend.

Midland, Texas, addressed an older but equally critical problem: the Permian Basin region’s four major public safety agencies could not reliably communicate during major incidents. The city’s transition to a P25 simulcast platform aligned Midland’s infrastructure with Odessa, Midland County, and Ector County, creating shared talkgroup templates and joint governance. The 2019 Midland-Odessa mass shooting had exposed the fragility of the region’s communications posture. The interoperable system went live in September 2025 across 4,312 total subscribers.

Finally, Cincinnati/Northern Kentucky International Airport (CVG) demonstrated that the public safety challenge is not unique to law enforcement. CVG deployed a Bluetooth-based micro-location platform across its 7,700-acre campus to address a straightforward but underserved problem: where workers and assets are in real time—without GPS dead zones and without surveillance overreach.

The result has been measurable improvements in asset visibility and lone-worker safety, with emergency alerts now reaching personnel who previously had no radio access.

What sets leaders apart

The pattern across all entries is clear: the most effective deployments paired operational rigor with clear outcome measurement. Just as importantly, the cities that built governance frameworks alongside their technology investments achieved the most durable results.

Alison Brooks - Research Vice President, Smart Cities Strategies, Public Safety - IDC

As Research Vice President for IDC's Worldwide and US Public Safety practice, Dr. Alison Brooks focuses on public safety and first responder research and advisory services, with a specialization in Smart Cities and Communities. Dr. Brooks' research provides detailed analysis on the digital transformation of public safety and first responders, covering topics such as digital evidence management, integrated physical security solutions, intelligence-led policing, advanced analytics, video surveillance and visualization, first responder communications and alternative policing frameworks. Dr. Brooks has held a number of positions with IDC over the past 15 years, previously working as IDC Canada's Director of public sector research.

Ruthbea Yesner - Program VP - IDC

Ruthbea Yesner is the Vice President of Government Insights at IDC. In this practice, Ms. Yesner manages the US Federal Government, Education, and the Worldwide Smart Cities and Communities Global practices. Ms. Yesner's research discusses the strategies and execution of relevant technologies and best practice areas, such as governance, innovation, partnerships and business models, essential for government and education transformation. Ms. Yesner's research includes analytics, artificial intelligence, Open data and data exchanges, digital twins, artificial intelligence, the Internet of Things, cloud computing, and mobile solutions in the areas of economic development and civic engagement, urban planning and administration, smart campus, transportation, and energy and infrastructure. Ms. Yesner contributes to consulting engagements to support K-12 and higher education institutions, state and local governments and IT vendors' overall Smart City market strategies.

Each year, IDC’s Smart Cities North America Awards provide a unique window into how cities are evolving—not just in ambition, but in execution. This year’s entries, finalists, and winners tell a clear and compelling story: Smart Cities are no longer conceptual. They are operational, integrated, and delivering measurable impact in communities of all sizes.

At their core, Smart Cities have always been about using technology to improve the quality of life for residents, businesses, and visitors. What stands out in 2026 is how firmly that vision has translated into action.

From experimentation to execution

One of the most striking trends across this year’s submissions is the level of operational maturity. Projects are no longer exploratory pilots or isolated proofs of concept. Instead, they are focused on execution and performance.

We saw widespread adoption of technologies that enable cities to function more effectively every day, including digital procurement and workflow automation, GIS and data integration, real-time monitoring and dashboards, and AI-enabled analytics. These capabilities are not just enhancing services—they are transforming how cities operate at a foundational level, particularly in critical systems such as public safety, fire response, and water management.

Another notable trend is the growing—but pragmatic—use of AI. Rather than being positioned as a standalone innovation, AI capabilities are embedded within broader solutions to analyze data, support decision-making, automate workflows, and improve service delivery. We saw this in projects focused on procurement automation, real-time analytics, and operational intelligence, as well as in Scottsdale’s AI-powered real-time crime center.

AI in Smart Cities is not experimental or abstract—it is being applied in targeted ways to solve specific problems and deliver measurable outcomes. This was also reflected in the many panels at the Smart Cities Connect conference, which showcased how cities are using AI in defined use cases to achieve concrete results.

This shift signals an important milestone: Smart Cities have moved beyond experimentation and into sustained, real-world delivery.

Breaking down silos: The rise of systems thinking

Another defining characteristic of the 2026 entries is the move toward integrated, multi-domain approaches. Cities are increasingly designing solutions that cut across traditional silos, embracing systems-thinking models rather than isolated implementations.

Many of this year’s projects span multiple functional areas or departments, with common combinations including public safety, infrastructure, and transportation; administration, civic engagement, and digital equity; and urban planning paired with resiliency initiatives.

This evolution reflects a growing ability to collaborate across departments and address challenges in an interconnected way, using coordinated solutions that bring together data, technology, and stakeholders. Key to this shift is the increasing influence of innovation teams, leaders, and smart city directors acting as city-wide coordinators.

Technology in service of community priorities

Across all categories, one theme was consistent: technology is being applied to clearly defined community needs.

Projects focused heavily on areas such as flood mitigation and environmental monitoring, community resiliency, accessibility and digital inclusion, and public safety innovation. Many also emphasized strong cross-sector partnerships, bringing together government agencies, private sector partners, nonprofits, and academic institutions.

This alignment between technology and community priorities reinforces a critical principle of Smart Cities: technology is not the goal—it is the enabler. The most impactful projects start with a clear understanding of local challenges and apply technology deliberately to address them.

Innovation that is scalable, agile, and inclusive

Another encouraging finding from this year’s awards is how accessible Smart City innovation has become.

A significant number of projects were delivered with relatively modest budgets, with 37 initiatives under $100,000 and only a handful exceeding $10 million. At the same time, most projects were implemented in less than two years.

This demonstrates that meaningful innovation does not require massive, multi-year capital investments. Instead, cities are embracing modular, agile approaches that allow them to move quickly, scale solutions, and deliver results.

Equally important, innovation is no longer concentrated in large metropolitan areas. This year’s submissions highlight strong participation from mid-sized cities and regional communities, underscoring that Smart City capability is widely distributed across North America.

Celebrating the 2026 finalists and winners

At the heart of the Smart Cities Awards is the recognition of the cities and partners leading this transformation.

This year’s awards highlight the breadth of innovation happening across North America. The finalists and winners exemplify what is possible when vision meets execution and demonstrate the diversity of approaches organizations are taking. A few examples include:

  • The City of Boston, advancing both digital equity and operational efficiency through initiatives such as Green Light for Education, which addresses student access and transportation challenges, and BidBot, an AI-enabled tool transforming municipal procurement.
  • The City of Pittsburgh, driving climate-focused urban planning through initiatives like Planting with Purpose, using data and partnerships to strengthen community resiliency and guide sustainable development.
  • Austin Water, modernizing infrastructure through advanced metering initiatives that improve water management, operational visibility, and customer service.
  • New Jersey Transit, enhancing resiliency and infrastructure intelligence with its Storm Surge Early Warning System, using real-time data to anticipate and respond to flooding risks.
  • The City of Phoenix, pushing innovation across multiple fronts, particularly in public safety—from its Unmanned Aerial Systems (UAS) program to broader efforts in real-time operations and community engagement.
  • The City of Scottsdale, recognized as the overall winner for its AI-powered real-time crime center and drone-as-first-responder program, highlighting the power of integrated, data-driven approaches.

Each finalist and winner represents not just a successful project, but a model for others to learn from and build upon.

Looking ahead

One of the most compelling aspects of Smart Cities is that while the definition continues to evolve, the purpose remains constant: improving communities and addressing complex urban challenges through technology.

Today’s Smart Cities are practical, multi-domain, partnership-driven, and deeply focused on outcomes. They are powered by technology, but centered on people—the practitioners, innovators, and leaders working every day to make their communities better.

As we celebrate this year’s winners and finalists, we are also recognizing a broader movement—one that is steadily transforming how cities operate and how they serve their residents.

Ruthbea Yesner - Program VP - IDC

Ruthbea Yesner is the Vice President of Government Insights at IDC. In this practice, Ms. Yesner manages the US Federal Government, Education, and the Worldwide Smart Cities and Communities Global practices. Ms. Yesner's research discusses the strategies and execution of relevant technologies and best practice areas, such as governance, innovation, partnerships and business models, essential for government and education transformation. Ms. Yesner's research includes analytics, artificial intelligence, Open data and data exchanges, digital twins, artificial intelligence, the Internet of Things, cloud computing, and mobile solutions in the areas of economic development and civic engagement, urban planning and administration, smart campus, transportation, and energy and infrastructure. Ms. Yesner contributes to consulting engagements to support K-12 and higher education institutions, state and local governments and IT vendors' overall Smart City market strategies.

Alison Brooks - Research Vice President, Smart Cities Strategies, Public Safety - IDC

As Research Vice President for IDC's Worldwide and US Public Safety practice, Dr. Alison Brooks focuses on public safety and first responder research and advisory services, with a specialization in Smart Cities and Communities. Dr. Brooks' research provides detailed analysis on the digital transformation of public safety and first responders, covering topics such as digital evidence management, integrated physical security solutions, intelligence-led policing, advanced analytics, video surveillance and visualization, first responder communications and alternative policing frameworks. Dr. Brooks has held a number of positions with IDC over the past 15 years, previously working as IDC Canada's Director of public sector research.

Over the years, smartphone makers have been “selling us” the need for better cameras, more power, longer battery life, and improved displays. In the last couple of years, the conversation began to shift toward intelligence, but very little was shown about the future of truly intelligent devices. This year in Barcelona, that story changed.

The most important announcements were not about hardware specifications, but about how devices interpret, anticipate, and act on behalf of the user. What we witnessed at Mobile World Congress 2026 was not another cycle of AI promises—it was execution. Devices are now designed with AI from the ground up and are able to interpret context, anticipate needs, and act on behalf of the user, significantly improving the user experience.

From AI as a feature to AI as the foundation

Until recently, AI in smartphones was largely an add-on layered on top of core features. It enhanced photography, powered voice assistants, or enabled isolated capabilities. At MWC 2026, AI has moved into the core architecture of the device.

Samsung provided one of the clearest demonstrations of this transition with the Galaxy S26 and the broader Galaxy AI ecosystem. The focus is no longer on responding to commands, but on enabling systems that operate with a degree of autonomy.

Samsung demonstrated systems capable of:

  • Understanding context across multiple apps – Devices such as the Samsung Galaxy S26 are beginning to interpret user intent by linking activity across applications (e.g., recognizing a travel confirmation in an email and cross-referencing it with calendar availability).
  • Aggregating personal data into actionable insights – Devices can consolidate data streams to generate meaningful recommendations (e.g., Samsung demonstrated how intelligence improves when devices work together).
  • Acting autonomously to complete tasks on behalf of users – The most advanced demos focused on autonomous execution. Samsung positioned the S26 as a device that “anticipates intent and takes action” ahead of the user.

Samsung exemplified this transition with its expansion of Galaxy AI across smartphones, PCs, tablets, and wearables, anchored around agent-based experiences that execute tasks rather than simply respond to commands. Similarly, Xiaomi’s focus on computational photography and intelligent imaging reflects how AI is redefining even mature use cases like the camera.

The industry is converging toward devices that function as orchestrators within a wider ecosystem, rather than standalone endpoints.

Intelligence extends beyond the smartphone

Another important takeaway from MWC 2026 is that this shift is not limited to smartphones.

Lenovo’s presence highlighted how AI is being embedded across PCs and emerging form factors. Concepts such as modular AI PCs, foldable gaming devices, and glasses-free 3D laptops point to a future where intelligence provides continuity across devices, adapting dynamically to user behavior.

TECNO, on the other hand, focused on accessibility. Its approach centers on bringing AI capabilities to more affordable segments while tailoring experiences to local environments. The example of noise cancellation optimized for high-noise regions is particularly relevant, as it shows how AI can be applied in a highly contextual and differentiated way.

At the silicon level, Qualcomm’s announcements confirm that this transition is being enabled from the ground up. Advances in AI-capable chipsets, combined with next-generation connectivity such as 5G Advanced and emerging Wi-Fi standards, are making on-device intelligence both scalable and efficient.

In effect, intelligence is becoming pervasive, embedded across the entire technology stack—from components to services.

New device categories signal behavioral change

Several key announcements highlighted how intelligence is reshaping device categories themselves.

Honor’s “Robot Phone” is perhaps the most relevant example. Built around a gimbal-mounted camera system, the device can physically track users, follow movement, and interact in a more human-like manner—blurring the line between smartphone and personal assistant and taking AI beyond software into hardware.

Motorola’s Razr Fold reflects another trend: premium form factors combined with productivity features such as stylus support and multitasking, targeting higher-value segments where intelligence enhances utility rather than novelty.

Meanwhile, TECNO’s modular concept introduces a different dimension of innovation. By enabling interchangeable hardware modules, it suggests a future where devices evolve over time, potentially reducing replacement cycles and aligning with sustainability pressures.

Even in the midrange, innovation is being redefined. The Nothing Phone 4(a) generated significant attention not because of raw specifications, but because of how it uses AI to extract, organize, and operationalize personal information—turning passive data into active utility.

Ecosystems are becoming the new battleground

A strong theme at MWC 2026 is the shift from devices to ecosystems. Xiaomi’s broad portfolio illustrates a strategy focused on scale and integration. The device is no longer the product; it is the entry point into a connected environment.

This was echoed across vendors. Samsung is extending AI across its entire Galaxy portfolio. Lenovo is aligning PCs and peripherals into unified AI systems. Telecom operators are introducing AI-driven services such as real-time call assistance.

Competition is no longer defined solely by device specifications. It is increasingly about how effectively companies connect devices, data, and services into a seamless experience.

A market under pressure: The memory constraint

Despite the optimism around AI execution, a structural risk dominated executive conversations: the emerging memory shortage.

From an IDC perspective, this is not a marginal issue. The industry is entering a period where demand for AI-capable devices is rising, but supply-side pressures are intensifying. IDC expects global smartphone shipments to decline by approximately 13% in 2026, with PC shipments projected to contract by around 11%. This reflects a combination of macroeconomic softness and component constraints, including memory availability and cost volatility.

This introduces a paradox. Just as demand for AI-capable devices accelerates, the industry faces constraints that could limit supply and compress margins. The result is likely to be increased cost pressure, tighter margins, and more selective innovation cycles.

What this means for the industry

MWC 2026 will likely be remembered as a turning point where AI moved from narrative to reality.

First, differentiation is shifting from hardware to intelligence. Performance still matters, but experience is becoming the primary driver of value.

Second, the center of gravity is moving from standalone devices to ecosystems. The winners will be those who can orchestrate seamless interactions across multiple devices and services.

Third, interaction models are evolving from user-driven to agent-driven. Devices are beginning to take initiative, reducing friction and redefining how users engage with technology.

For vendors, competing on hardware alone is no longer sufficient. The ability to integrate intelligence deeply across software, services, and ecosystems will define the next phase of the market.

The industry has spent years talking about AI. In Barcelona this year, it finally started delivering.

Francisco Jeronimo - Vice President, Data & Analytics - Devices - IDC

Francisco Jeronimo is VP for Data and Analytics at IDC EMEA. Based in London, he leads the research that covers mobile devices, personal computing devices, emerging technologies and the circular economy trends across EMEA. His team delivers data on personal computers, tablets, smartphones, wearables, PC monitors, PC gaming, enterprise Thin Client devices, smart home, augmented reality and virtual reality, and sales of used devices. He provides in-depth analysis of the strategies and performance of the key industry players.

Agentic AI is moving from experimentation toward enterprise orchestration. Early deployments emphasized efficiency. As systems scale, the more significant shift lies in how enterprises redesign value creation, capture, and long-term advantage.

IDC’s FutureScape 2026 predictions identifies this transition as one of four strategic imperatives shaping the agentic future. Unlocking innovation beyond productivity defines how organizations translate AI maturity into new business models, revenue streams, and sustained competitive position.

Innovation beyond productivity refers to the structural redesign of business models, industry boundaries, and economic logic enabled by agentic AI operating across enterprise portfolios and ecosystems. It reflects how organizations convert AI maturity into scalable growth, differentiated customer value, and durable competitive advantage.

This is the focus of Pillar 4 within FutureScape 2026.

The productivity plateau

The first wave of AI delivered measurable gains. Contact centers reduced handle times. Back-office operations automated repetitive tasks. Sales and marketing teams improved throughput. These gains were important because they made AI investment tangible.

However, efficiency advantages diffuse quickly. What creates competitive differentiation in one quarter becomes standard capability the next. Productivity improvements, when layered onto existing operating models, eventually reach saturation.

Productivity-first strategies constrain long-term impact in three ways:

  1. They reinforce functional silos. AI is deployed by department, and each team optimizes local objectives.
  2. They lock in current assumptions. Optimization strengthens workflows designed for earlier market conditions.
  3. They produce linear gains. Efficiency improvements reach saturation when underlying structures remain unchanged.

The constraint is not AI capability. The constraint is operating design. When AI is layered onto legacy structures without structural redesign, outcomes remain incremental.

Innovation as the structural payoff of agentic AI

Innovation occurs when AI reshapes enterprise structure rather than simply accelerating task execution. Agentic AI enables coordinated decision-making across marketing, supply chain, finance, service, and ecosystem partners. Systems move from isolated automation toward orchestration embedded in enterprise operating models.

Innovation beyond productivity highlights three requirements for structural innovation in the agentic era:

  • Redefined industry boundaries. Agentic AI facilitates collaboration between domains that previously operated independently, reshaping competitive landscapes.
  • New economic logic. When agents operate autonomously at scale, assumptions about capacity, cost, and output change. Business cases designed for linear improvement do not capture compounding value created through coordination.
  • Governance as infrastructure. Governance must support cross-domain orchestration while embedding accountability into operating design.

Where value models are being rebuilt

FutureScape research identifies structural pressure points where value creation is already evolving. These signals reflect changes in pricing structures, industry organization, and coordinated delivery models.

Pricing model evolution
Traditional pricing frameworks were built around human labor and seat-based licensing. As agent interactions increase, value shifts from access to measurable outcomes. Enterprises and providers are redesigning pricing logic to reflect agent-mediated execution and results. This indicates a change in value capture, not simply a change in delivery.

Life sciences reinvention
Agentic AI is transforming pharmaceutical research and development. By 2030, 80 percent of pharmaceutical companies are projected to partner with TechBios, leveraging agentic AI and quantum computing to reduce R&D costs and failure rates. This signals new industry architectures built on coordinated discovery and ecosystem collaboration.

Healthcare system coordination
Healthcare has traditionally operated through linear care pathways. Agentic AI enables continuous orchestration across diagnosis, treatment, monitoring, and escalation. By 2030, one in three top-tier hospitals is expected to deploy AI agents delivering real-time decision support and autonomous workflows with high levels of accuracy. Clinical value becomes embedded in system coordination rather than isolated interventions.

Consumer ecosystem realignment
Immersive digital environments and gaming platforms are evolving into coordinated ecosystems for engagement and commerce. By 2026, two-thirds of Gen Z and Gen Alpha are projected to spend more time gaming than on social media. This signals movement toward platforms designed for persistent interaction and orchestrated value creation.

Rethinking AI ROI

As AI becomes integral to enterprise operating logic, traditional ROI metrics require reassessment. Leaders must reconsider three assumptions:

  • Short-term cost savings do not define strategic value.
  • Pilot programs do not create durable advantage without integration.
  • Model accuracy does not guarantee enterprise impact if objectives remain unchanged.

Legacy metrics focus on time saved and expenses reduced. Structural innovation requires evaluation of adaptability, cross-functional coordination, and long-term growth potential.

This shift aligns AI outcomes with enterprise design and economic logic, not isolated task performance.

Innovation as portfolio and ecosystem strategy

Agentic AI generates the greatest impact when managed as a coordinated portfolio rather than discrete initiatives. Each deployment should strengthen enterprise adaptability, improve cross-functional coordination, and expand future strategic options.

Unified governance frameworks support this model by embedding oversight into operating systems and enabling autonomous action within defined boundaries.

As agents operate across organizational and ecosystem boundaries, value creation becomes interdependent. Competitive advantage becomes systemic and embedded within enterprise design.

Defining the next horizon

Productivity remains necessary. Structural innovation determines sustained advantage.

The transition highlights a pivotal transition within the agentic journey. Agentic AI is redefining economic models, industry boundaries, and enterprise architecture. Organizations that redesign for orchestration, portfolio coordination, and ecosystem alignment position themselves for long-term growth in the AI-fueled economy.

Explore innovation beyond productivity in depth

FutureScape 2026 includes detailed research, analyst perspectives, and events that expand on the innovation beyond productivity theme.

Core Research

Analyst perspectives

On-demand webinars

IDC - -

International Data Corporation (IDC) is the premier global market intelligence, data, and events provider for the information technology, telecommunications, and consumer technology markets. With more than 1,300 analysts worldwide, IDC offers global, regional, and local expertise on technology and industry opportunities and trends in over 110 countries. IDC’s analysis and insight help IT professionals, business executives, and the investment community make fact-based technology decisions and achieve their key business objectives.

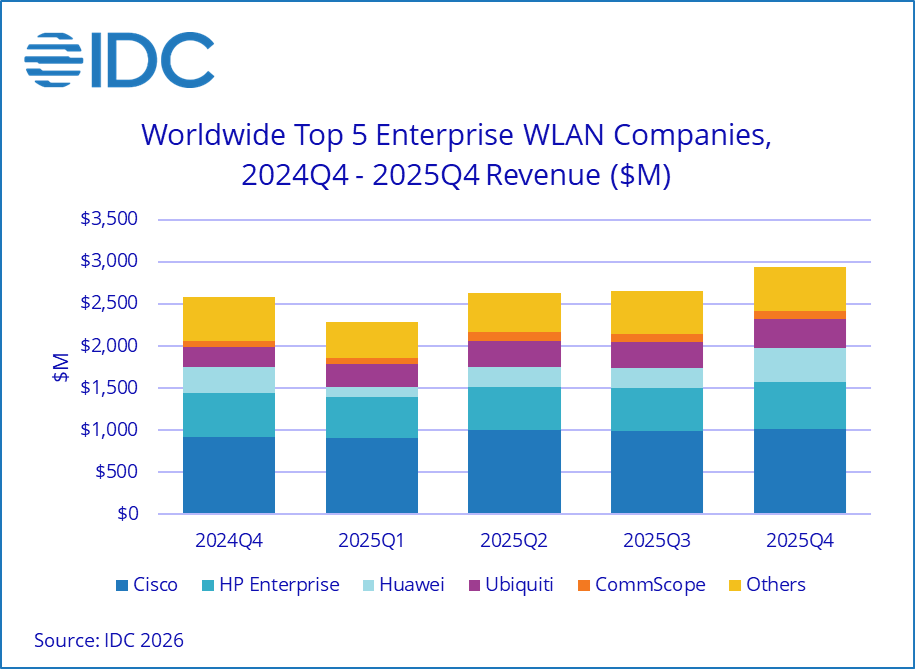
In the fourth quarter of 2025 (4Q25), the worldwide enterprise WLAN market reached $2.9B, growing 13.9% year over year. The primary driver was the rapid adoption of Wi-Fi 7, which accounted for 39.7% of dependent access point segment revenue, up from 10.25% a year earlier. For full-year 2025, the market totaled $10.5B, with 11.4% annual growth, reflecting ongoing demand for advanced wireless standards.

Why enterprise WLAN matters in the AI era

In the AI era, connectivity is no longer just infrastructure—it is a strategic foundation for digital business. Enterprise WLAN plays a critical role in delivering secure, reliable, and high-performance connectivity across enterprise campuses, branches, and edge environments. At the same time, AI-driven applications, video traffic, and the rapid growth of IoT devices are placing unprecedented demands on network capacity, latency, and efficiency, pushing organizations to rethink and modernize their wireless networks.

IDC’s 4Q25 WLAN Tracker highlights a clear inflection point: 60% of global enterprise WLAN spending is now directed toward Wi-Fi 6E and Wi-Fi 7. This shift reflects a move from early adoption to mainstream deployment, as enterprises invest in next-generation WLAN technologies to support higher performance requirements and enable emerging AI-driven and distributed business models.

Market dynamics: WiFi 7 and AI drive upgrades

The enterprise WLAN market is being shaped by continued innovation, evolving architectures, and the growing influence of AI. The expansion of 6GHz spectrum with Wi-Fi 6E and the accelerating adoption of Wi-Fi 7 are driving a new wave of upgrades.

At the same time, AI is improving how WLANs are designed and operated through greater automation and optimization, while enterprises adopt platform-based approaches that integrate WLAN with broader networking, security, and observability tools. Combined, these trends are driving strong growth in the enterprise WLAN market, both in 4Q25 and for full-year 2025.

From a geographic perspective, in 4Q25, the Americas saw a 13.9% year-over-year increase, while Europe, the Middle East & Africa experienced robust growth of 25.2% YoY. In contrast, the Asia Pacific region saw a slight revenue decline of 0.9% YoY, highlighting regional disparities in technology adoption and investment priorities.

Vendor performance: Cisco leads as growth accelerates

Cisco maintained its leadership in the enterprise WLAN market, with revenue rising 10.8% year over year to $1.0B and a market share of 34.6% in 4Q25. For the full year, Cisco’s revenue increased 4.9% to $3.9B, giving the company a market share of 37.2% at year-end.

HPE, now including Juniper following its July 2025 acquisition, grew 4.7% YoY to $552.8M, capturing 18.8% of the market in 4Q25. For the full year, HPE’s revenue increased 7.6% to $2.0B, giving the company a market share of 19.7% at year-end.

Ubiquiti saw the highest growth among major vendors, increasing 49.0% YoY to $344.5M and holding 11.7% market share in 4Q25. For the full year, the company’s revenue grew 53.1% to $1.2B, maintaining an 11.7% share in 2025.

Huawei posted strong growth, up 32.1% YoY to $409.8M, with a 14.0% share in 4Q25. For the full year, revenue rose 18.4% to $1.0B, giving the company a 9.6% share.

CommScope (Ruckus Networks) grew 13.4% YoY to $88.8M, representing 3.0% of the market in 4Q25. For the full year, revenue rose 26.0%, giving the company a 3.4% share.

Outlook: Wi-Fi 7 momentum and AI-driven networks

IDC expects continued momentum in enterprise WLAN upgrades as organizations pursue higher performance, greater automation, and tighter integration with AI-driven and distributed workloads. Wi-Fi 7 adoption is likely to accelerate further—alongside increased deployment of tri-band APs—particularly in regions with strong digital transformation initiatives.

Growth will also be supported by rising adoption of AI-driven network operations, platform-based networking approaches, and cloud-managed architectures, as enterprises seek more scalable and flexible environments. At the same time, evolving security requirements, including zero trust frameworks, will remain a key driver, while supply chain constraints or macroeconomic headwinds may temper growth in certain regions. Watch for continued innovation in AI capabilities, architectural models, and vendor strategies in the coming quarters.

For deeper analysis and IDC research on enterprise WLAN trends, visit IDC’s Worldwide Quarterly WLAN Tracker or contact IDC for the latest market insights.

Brandon Butler - Sr. Research Manager - IDC

Brandon Butler is a Senior Research Manager with IDC's Network Infrastructure group covering Enterprise Networks. His research focuses on market and technology trends, forecasts and competitive analysis in enterprise campus and branch networks. His coverage includes technologies used in local and wide area networking such as Ethernet switching, routing/SD-WAN, wireless LAN, and enterprise network management platforms. While contributing to ongoing forecast and market share updates, he also assists in end-user surveys, interviews and advisory services and contributes to custom projects for IDC's Consulting and Go-To-Market Services practices.

Petr Jirovsky - Senior Research Director, Network Infrastructure and Services - IDC

Petr Jirovsky is a Senior Research Director within IDC's Enterprise Infrastructure global research domain. He provides quantitative insights on network infrastructure for the datacenter, cloud, and campus/branch environments as part of the Network Infrastructure and Services subdomain. Petr serves as the global lead for IDC's Network Infrastructure Trackers, which track Ethernet switches, routers, wireless equipment, and application delivery appliances and services. He also contributes to numerous custom data projects and supports the publication of market share and forecast documents for the subdomain.

Diego Anesini - VP D&A, LatAm & Director Enterprise and Telecom - IDC

Diego Anesini serves as Research Vice-President, Data & Analytics for IDC Latin America, overseeing all the Information and Communications Technologies. Prior to this position, Diego held various roles in the company. The most recent was Enterprise Infrastructure and Telecom Director for Latin America. He has extensive experience in the Telecom and IT markets, due to his more than 25 years in the industry.

在刚刚落幕的英伟达GTC大会和阿里巴巴组织架构调整的双重催化下,“AI Token预算”已从科技圈的前沿话题,迅速演变为企业管理层案头的必答题。随着AI智能体(Agent)开始替代传统软件执行复杂任务,Token不再仅仅是技术计价单位,而是企业参与未来竞争的“数字石油”。

IDC最新研究显示,2025年中国AI相关IT支出预计将达到约380亿美元,并将在2027年前保持超过25%的年复合增长率,其中生成式AI推理相关支出占比快速提升,成为企业数字化投资中增长最快的子项之一。这一趋势表明,Token作为AI消费的核心计量单位,正在从“技术指标”转变为“财务指标”。

对于中国市场而言,凭借独特的成本优势与政策红利,为企业设立独立的Token预算科目,已不仅是财务精细化的需求,更是一场抢占“AI定价权”的战略博弈。

指数级消耗倒逼财务变革:Token是新型“生产力采购”

过去一年,全球日均Token消耗量增长近300倍,IDC中国追踪的企业级Token年度总消耗量过去一年也增长了近20倍,这一数字背后是AI从“辅助工具”向“生产力主体”的身份转变。

IDC调研进一步指出,已有超过60%的中国头部企业开始将生成式AI纳入核心业务流程(如研发、客服、营销自动化),其中超过30%的企业已经出现“AI调用成本不可控”的问题,这正是Token预算缺失的直接表现。

对企业而言,忽视Token预算的风险正在显现。一方面,若沿用传统的软件订阅制预算逻辑,企业将面临难以预测的“成本黑洞”——例如,一个重度使用的工程师,其年度AI推理支出可能突破10万美元,占其总人力成本的20%以上;另一方面,缺乏独立核算将导致投入产出比失真,无法精准衡量“每一美元Token究竟换来了多少业务价值”。

因此,将Token支出从“软件采购”剥离,升级为与人力、供应链同等重要的“核心生产资源”进行独立核算,已成为企业财务管理的必然选择。这标志着企业采购逻辑的转变:从购买“软件工具”转向购买“生产力服务”。

中国市场的“弯道超车”:性价比即竞争力

对于中国公司而言,制定Token预算具有特殊的地缘战略意义。当前,中国AI大模型市场正凭借极致的性价比在全球竞争中抢占先机。

IDC数据显示,中国大模型市场呈现出“高性价比+高调用量”的双重特征:2025年中国生成式AI模型调用量预计将占全球约35%以上,且增长速度显著高于北美市场。

得益于“东数西算”工程带来的绿电成本优势(西部数据中心电价仅为欧美的1/3至1/5),国产模型在Token单价上展现出碾压性优势。目前,中国主流大模型的Token单价仅为国外竞品(如Gemini)的1/6至1/10。

这种成本红利直接转化为市场数据:2026年初,中国大模型的周调用量已在全球主要API聚合平台上历史性地反超美国市场。

这意味着,中国公司若能充分利用本土模型的“价格洼地”,其Token预算的每一分钱都将具备更高的购买力。这不仅是降本增效的手段,更是中国企业在全球AI应用层竞争中实现“弯道超车”的关键窗口。

未来竞争的关键,不只是“谁用AI”,而是“谁用更低成本的Token创造更高密度的业务价值”。

如何编制你的Token预算?分层配置与动态调整

面对Token经济的浪潮,企业应如何着手准备预算?结合行业实践,建议从以下三个维度入手:

1. 分层设置消耗配额:

  • 基础层:保障高频、轻量级应用(如内部知识库、客服机器人),预算编制可参考历史消耗量,并叠加行业年均降价预期(预计年降本约30%)。
  • 战略层:预留高价值场景预算(如视频生成、AI自主编程、智能体编排),并将预算额度与具体的业务增长目标挂钩,确保高投入带来高回报。

2. 响应国家“算力通胀”治理:

国家数据局已将“降低社会算力总成本”列为重点任务。

IDC预计,到2027年,中国数据中心算力规模将增长超过2倍,其中AI算力占比将超过40%。在此背景下,Token成本管理将成为企业参与“算力资源配置”的关键能力。

企业设立独立的Token预算科目,不仅便于合规申报深圳等地推出的“算力券”补贴,也有助于满足ESG(环境、社会和公司治理)披露要求,如追踪单位Token的碳足迹。

3. 配置弹性对冲机制:

鉴于Token成本受地缘政治(如算力出口限制)和电力波动影响显著,建议企业在总预算中配置约20%的弹性空间,以应对不确定性。

IDC建议

IDC中国研究总监卢言霞表示,正如工业时代的企业必须预算电力成本,AI时代的企业必须学会预算Token成本。阿里巴巴成立“Token Hub”事业群、英伟达高呼“推理拐点已至”,这将提醒所有企业:Token不仅是成本,更是未来企业竞争力的量化指标。

IDC认为,未来3年内,是否具备“Token精细化管理能力”,将成为企业AI成熟度的重要分水岭。领先企业将呈现出三大特征:

  1. 将Token纳入核心财务指标体系
  2. 建立跨部门的AI成本治理机制(财务+IT+业务)
  3. 实现Token消耗与业务价值的实时映射

每个公司都应该现在就开始思考:你的年度预算表里,准备好“Token”这一项了吗?

关于Token预算、AI投入或相关实践,如果您有更多思考或问题,欢迎与我们交流。IDC也将持续分享最新研究与市场洞察,与您一起探索AI时代的增长机会。

如需进一步了解与研究相关内容或咨询 IDC其他相关研究,请点击此处与我们联系。