Organizations today are navigating powerful crosscurrents. Economic uncertainty, regulatory shifts, and workforce disruption are intensifying at the same time that AI is moving from experimentation to enterprise scale. Many leaders have responded by launching pilots, testing use cases, and investing in new tools.

A gap is emerging.

AI is present across the enterprise, yet measurable value remains limited.

Across industries, organizations are finding that experimentation does not automatically lead to impact. Pilots stall. Use cases remain isolated. Investments increase, but outcomes remain uneven.

The challenge is no longer whether to adopt AI. The challenge is how to operationalize it at scale.

The hidden barrier: From pilots to fragmentation

Most organizations are now well into their AI journey, yet many are unable to move beyond early deployments.

Isolated use cases create pockets of progress, but they do not transform the enterprise. Teams deploy agents, automate workflows, and generate insights, but these efforts are not connected to core operations.

This creates a new layer of complexity:

  • AI tools that do not integrate
  • Data that does not move in real time
  • Agents that operate without shared governance
  • Workflows that cannot scale across the organization

At the same time, the number of AI agents is increasing rapidly, introducing new demands for coordination, lifecycle management, and oversight.

Without a unifying approach, organizations face rising costs, inconsistent results, and delayed returns on investment.

In this environment, fragmentation becomes the primary barrier to progress.

The inflection point: From experimentation to orchestration

IDC’s FutureScape 2026 predictions highlight a clear shift.

Organizations that achieve impact will move beyond experimentation and adopt enterprise-wide orchestration.

This shift changes how the enterprise operates.

AI becomes embedded into the way decisions are made, work is executed, and systems interact.

Enterprise-wide orchestration includes:

  • Agents coordinating work across functions
  • Continuous data flow across systems
  • Applications evolving into AI-driven platforms
  • Governance integrated into daily operations

This is the transition from isolated deployments to connected systems that operate as a unified whole.

Charting the path: Four moves to scale AI with confidence

Reaching enterprise-wide orchestration requires deliberate action across strategy, architecture, and operations.

Based on FutureScape 2026 insights, four moves define this path.

1. Establish a control plane for AI orchestration

Scaling AI requires centralized coordination.

Leading organizations are building orchestration layers that manage agents, workflows, and governance across the enterprise. This creates consistency, reduces duplication, and enables AI systems to function together.

Without this coordination, complexity increases as deployments expand.

2. Re-architect for real-time, event-driven operations

Agentic AI depends on timely and contextual data.

Organizations must shift from batch-based systems to event-driven architectures where data flows continuously. This enables faster decision-making and allows agents to respond in real time.

In this model, data becomes an active component of operations rather than a static resource.

3. Build an AI lifecycle, not just deployments

Deploying AI is only the first step.

Organizations need structured lifecycle management that includes development, deployment, monitoring, and governance. This ensures that AI systems remain reliable and aligned with business objectives as they scale.

The adoption of formal lifecycle practices is becoming essential as agent usage expands.

4. Align the workforce to an orchestrated future

Enterprise orchestration requires changes in how work is performed.

As AI agents take on execution tasks, human roles shift toward oversight, coordination, and innovation. New responsibilities emerge in managing outcomes, ensuring accountability, and guiding AI systems.

Organizations that prepare their workforce for these roles will be better positioned to scale AI effectively.

The payoff: Enterprise impact at scale

When orchestration is achieved, organizations begin to see consistent and measurable impact.

AI supports coordinated operations across functions. Decision-making improves through real-time insights. Automation becomes more efficient and scalable. Innovation becomes a continuous process.

Organizations also gain greater adaptability. They can adjust workflows, reallocate resources, and respond to change more effectively.

From navigation to execution

The crosscurrents shaping the global economy will continue to evolve.

Navigation remains essential. Execution determines outcomes.

Organizations that adopt enterprise-wide orchestration can maintain direction, manage complexity, and scale their AI investments with confidence.

FutureScape 2026 makes the path forward clear.

AI adoption alone is not enough.
Operationalizing AI at scale is what drives results.

Those who take this step will define the next phase of the agentic future.

Explore the predictions behind charting the path to enterprise-wide orchestration

To move from AI experimentation to enterprise-wide orchestration, leaders need a coordinated view across applications, data, infrastructure, and operating models. The following FutureScape 2026 reports provide deeper insight into the predictions shaping this transition:

Core Research

Analyst perspectives

On-demand webinars

eBooks
IDC - -

International Data Corporation (IDC) is the premier global market intelligence, data, and events provider for the information technology, telecommunications, and consumer technology markets. With more than 1,300 analysts worldwide, IDC offers global, regional, and local expertise on technology and industry opportunities and trends in over 110 countries. IDC’s analysis and insight help IT professionals, business executives, and the investment community make fact-based technology decisions and achieve their key business objectives.

The 2026 Beijing Humanoid Robot Half Marathon has officially concluded. Compared with the 2025 event, this year’s competition demonstrated significant advancements in scale, technical complexity, and ecosystem participation—highlighting the industry’s accelerating transition toward commercialization.

According to IDC, global shipments of humanoid robots are expected to exceed 510,000 units by 2030, representing a compound annual growth rate (CAGR) of nearly 95%. As foundational technologies mature, application value deepens, ecosystems expand, and business models evolve, competition will increasingly center on real-world deployment capabilities and value delivery.

Industry Participation Expands as Performance Breakthroughs Accelerate

This year’s event attracted over 100 teams from enterprises, universities, and research institutions. There were notable breakthroughs in both core technologies and product performance. Leading players—including Honor—delivered standout results, with some robots surpassing human-level running speeds, reflecting significant improvements in locomotion capabilities.

Honor’s championship win underscores a broader industry trend: growing strategic commitment to humanoid robotics. As embodied intelligence continues to evolve, computing power, algorithms, and foundational models remain critical. Meanwhile, the entry of consumer device vendors is expected to create differentiation in edge computing and visual models. Combined with their large user bases and ecosystem strengths, they are well-positioned to accelerate both technological iteration and real-world adoption.

Autonomous Navigation Upgrade, From Single Capabilities to System-Level Validation

The competition has moved beyond testing basic mobility. Notably, 38% of participating teams adopted fully autonomous navigation, and the winning robot leveraged this capability under weighted scoring rules.

This shift reflects a broader transition: humanoid robots are now evaluated by their ability to operate reliably in complex, dynamic environments. Success requires seamless integration across perception, decision-making, and executions supported by high system stability and engineering readiness for scalable deployment.

Key Technology Highlights

Multimodal Perception
Robots combined data from multiple sensors—including satellite positioning, LiDAR, vision systems, and IMUs—along with real-time mapping technologies. This enabled stable operation across slopes, sharp turns, uneven terrain, and dynamic obstacles, significantly enhancing adaptability to real-world environments.

Reinforcement Learning and Motion Control
Extensive reinforcement learning in simulation environments, combined with high-quality human motion data and continuous adaptation and tuning in real-world environments, has driven major improvements in motion control algorithms. Robots now demonstrate enhanced balance, posture optimization, and human-like movement, enabling long-distance autonomous navigation, obstacle avoidance, and path optimization.

Hot-Swappable Batteries and Liquid Cooling
Energy management emerged as a critical enabler. Hot-swappable battery systems allow efficient recharging without downtime, while advancements in lightweight design, energy optimization, intelligent power distribution, and liquid cooling significantly extend operational endurance.

Hardware-Software Co-Optimization
Breakthroughs in hardware-software integration and engineering capabilities emerged as a key highlight and a critical focus for future development. Facing real-world physical environments and task requirements, robots must continuously learn and adapt to new scenarios and tasks, enabling end-to-end coordination across perception, decision-making, and execution. At the same time, deeper integration and precise alignment between AI models and diverse hardware configurations are required to establish real-time interaction loops. This ensures responsiveness, control precision, and system stability in complex tasks, accelerating progress toward highly reliable, maintainable, and scalable real-world deployment.

Commercialization Accelerates at “China Speed”

Humanoid robotics is rapidly evolving toward a closed-loop embodied intelligence system encompassing perception, learning, decision-making, and execution. Engineering capability is emerging as the key determinant of commercial viability.

In 2025, the global humanoid robot market experienced a breakout year, led by Chinese vendors, with shipments exceeding 18,000 units. More than 85% of deployments were concentrated in performances, education, data collection and guided tour service scenarios—primarily focused on demonstration, interaction, and technology validation. Early pilots have also emerged in manufacturing and logistics.

Looking ahead, IDC Humanoid Robotics Research forecasts that by 2030:

  • Global shipments will surpass 510,000 units
  • The industry will enter a scaling phase
  • Growth will be driven by improvements in hardware, application value, ecosystem collaboration, and business models

1. Hardware Evolution: China Leads in Scale and Manufacturing

Chinese vendors are expected to account for 95% of global shipments in 2025, establishing a dominant position in manufacturing and scalability. Several leading companies are projected to achieve annual production capacity in the tens of thousands by 2026, further strengthening supply capabilities.

Key innovation areas include structural optimization, joint and energy system upgrades, mass production capabilities, and motion control improvements. Additionally, dexterous hands—critical for fine manipulation—are poised for rapid development.

Fastest-growing categories:

  • Wheeled humanoid robots: High stability and suitability for indoor/semi-structured environments (projected CAGR ~120%)
  • Full-size bipedal humanoids: Greater flexibility for diverse scenarios (projected CAGR >95%)

2. Application Value: From Demonstration to Productivity

Industrial Adoption Accelerates
Collaboration with industrial leaders is validating performance metrics such as cycle time, task success rates, and operational stability. Deployment in manufacturing environments is expected to scale rapidly, with shipment growth exceeding 200% in 2026.

IDC research indicates that over the next three years more than 80% of users plan to deploy robots in tasks such as palletizing, handling, picking, and machine tending.

Service Applications Deepen
Humanoid robots are expanding into personalized services, enhancing customer experience and engagement in areas such as retail guidance and food service.

3. Ecosystem Development: Data, Models, and Scenarios

Data Scale Expansion
The integration of simulation data, internet video data, and real-world operational datasets is driving rapid growth in training data. China has already accumulated tens of thousands of hours and nearly petabyte-scale datasets, andis leading the development of the world’s first international standard for humanoid robot datasets.

Model Evolution
Advancements in motion models, combined with deeper integration of world models and vision-language-action (VLA) models, are improving generalization and intelligence. Leading global humanoid robotics and AI model companies are continuously accelerating the iteration and upgrading of foundational models.

Scenario Co-Creation
Oriented toward real-world industrial application scenarios, ecosystem players are jointly advancing application development and solution building, bridging the critical gap between technical validation and large-scale deployment, and accelerating the industrialization of humanoid robotics technologies.

4. Business Models: RaaS Gains Traction

Robot-as-a-Service (RaaS) models—including leasing and subscription—are lowering adoption barriers and accelerating market penetration.

IDC research shows that user acceptance of RaaS has doubled year-over-year. As service systems, pricing models, and maintenance capabilities mature, adoption is expected to further accelerate.

Outlook: A Critical Window for the Next 2–3 Years

IDC believes the 2026 Beijing Humanoid Robot Half-Marathon has become a key benchmark for assessing both technological maturity and industry progress. The event not only validated core capabilities but also accelerated ecosystem development and commercialization.

Over the next 2–3 years, the humanoid robotics industry will enter a pivotal phase:

  • Competition will shift from technical demonstrations to real-world application performance
  • Vendors with system-level capabilities and engineering execution will emerge as market leaders

Humanoid robotics is transitioning from technically feasible to commercially viable. Leading companies are already securing strategic positions in high-value scenarios, while the window for late entrants is rapidly narrowing.

Learn More

This analysis is based on IDC research, including:

For organizations evaluating entry strategies, identifying priority use cases, or assessing vendor capabilities, IDC offers comprehensive research and advisory services to support decision-making and accelerate time-to-market. For more information and related research, please contact trago@idc.com.

Lily Li - Research Manager - IDC

Lily Li is a research manager for emerging technologies in IDC China. She is responsible for conducting research and analysis for Internet of Things (IoT) in the same country. She is also involved in global and regional consulting as well as business development in related markets. Prior to joining IDC, Lily has had in-depth working experiences in the urban digital transformation (DX) field and a wide range exposure to Smart City developments. She has a deep understanding of the status quo and is knowledgeable about the market's future trends. Lily holds a master's degree from the Graduate University of Chinese Academy of Sciences (GUCAS).

Why scaling AI and proving ROI are now the real challenge for European organizations.

What comes next is far less straightforward.

For some time, the European AI narrative was fairly comfortable: lots of enthusiasm, plenty of pilots, and just enough regulatory drama to keep things interesting. Companies could experiment broadly, point to a few wins, and call it a strategy.

IDC’s recent research, based on a survey of 200+ European organizations conducted in late 2025, tells a story that is a tad inconvenient for anyone still in “innovation exploration” mode: more than half of European companies report that over 50% of their AI projects have already delivered measurable business outcomes. This is no longer a single pilot result; it is becoming a pattern. And patterns have a tendency to change expectations.

Europe is past the “AI is interesting” phase, but not quite at “AI is effortless” either. Most organizations are somewhere in the messy middle: proof points, momentum, but still unable to explain why that momentum is not turning into something more systematic. Nearly 9 in 10 say their ability to scale AI has improved. And yet, a large portion is operating with what you might call partial discipline. They are moving forward, but without the playbooks, governance structures, and execution models that make scaling feel less like controlled improvisation.

The technology was never the hard part of AI scaling
European organizations are not struggling to build AI. They are struggling to absorb it. When asked what most prevents them from realizing the full potential of their AI investments, the top answers were competition with other transformation priorities, regulatory uncertainty, resistance to process change, difficulty proving ROI, and budget pressure. None of these are technology problems. The blockers are organizational, political, and structural. Throwing more engineering at them will not help.

This is, in fact, a sign of progress. Europe’s AI constraints have shifted from technical feasibility to enterprise commitment, which means the technology has largely done its job. The hard part now is everything surrounding it: sponsorship that survives the next budget cycle, processes redesigned after years of inertia, and ROI demonstrated clearly enough to compete with every other initiative in the budget allocation process. AI is now being tested as a business program, and business programs depend on organizational discipline.

But can organizations measure AI ROI and business impact?

European organizations are no longer just tracking model performance or project completion. Operational efficiency, user adoption, business KPIs, and financial outcomes are all on the scorecard now. This removes a certain flexibility that AI teams might have previously enjoyed. A technically elegant deployment that nobody uses is no longer a qualified success. It is simply not a success.

The encouraging news is that many organizations are starting to respond, with a clear move toward formal business metrics and ROI logic built in from the start.

The gap is widening

Europe’s AI market is entering a separation phase. This is the point where the gap between organizations that can operationalize AI and those still generating isolated use cases starts to widen. The organizations pulling ahead are building the necessary connective tissue: prioritization discipline, outcome measurement, and governance that works at speed. Meanwhile, those still in exploration risk producing impressive narratives about their AI journey while actual business outcomes remain limited.

For enterprise leaders, IDC research is clear about what separates the scalers from the stragglers:

  • Stop treating AI as a project portfolio. Projects create motion; systems create lasting value.
  • Build measurement in from day one, not just as good practice, but because organizations that cannot prove value will lose internal budget competition to those that can.
  • Treat governance as a speed advantage. Organizations that build compliance into reusable controls will move faster, not slower, than those handling it case by case.

For vendors and service providers, the message is equally clear: more features are not the answer to executive skepticism. Proof of business impact is becoming a primary buying criterion. The ability to show how value will be measured, attributed, and reviewed matters more than model benchmarks.

Want to go deeper?
These dynamics are part of a broader shift shaping IT investment across EMEA in 2026. In our recent webcast, IDC analysts explored where growth is materialising, how AI maturity is evolving from pilots to scaled deployment, and what separates organisations that are successfully operationalising AI from those that are not.

If you missed it, the session is now available on demand. Watch it here and get the full data-driven perspective for your strategy.

Ewa Zborowska - Research Director, AI, Europe - IDC

Ewa Zborowska is an experienced technology professional with 25 years of expertise in the European IT industry. Since 2003, she has been a member of the IDC team, based in Warsaw, researching IT services markets. In 2018, she joined the European team with a specific emphasis on cloud and AI. Ewa is currently the lead analyst for IDC’s European Artificial Intelligence Innovations and Strategies CIS.

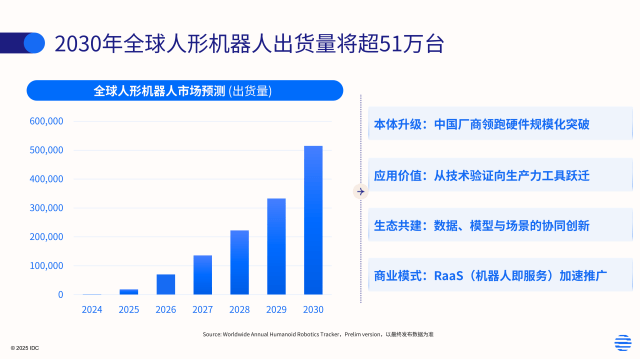
近日,2026 北京亦庄人形机器人半程马拉松落幕。从赛事规模、技术复杂度与产业参与度来看,较 2025 年大幅提升,再次展示行业迈向商业导入的能力与进展。IDC 预测,2030 年全球人形机器人出货量将突破 51 万台,年复合增长率近 95%。伴随本体技术升级、应用价值挖掘、产业生态共建及商业模式持续完善,未来行业竞争将聚焦应用能力与商业价值交付。

本届赛事吸引超百支企业、高校等多元主体队伍同台竞技,在核心技术与产品性能上实现多项突破。荣耀等厂商为代表的参赛主体表现突出,部分机器人奔跑速度已超越人类水平,核心运动性能显著提升,为产业落地注入强劲动能。

荣耀夺冠进一步体现出产业参与主体持续扩展,越来越多厂商开始从战略层面重视人形机器人的长期发展。在具身智能演进过程中,算力、算法与模型仍将构成核心底座。同时,消费终端厂商的入局,有望在端侧算力与视觉模型等关键环节形成差异化优势,叠加其庞大的用户基础与生态能力,将加速技术迭代与应用落地进程。

自主导航升级,从单项能力展示走向系统级能力验证

本届赛事对机器人的要求已超越基础运动能力,38% 的参赛队伍采用全自主导航模式,且自主导航机器人凭借赛事加权规则夺得冠军。贴近真实应用场景的综合考验,标志着人形机器人竞争核心转向复杂环境持续稳定运行,打通算法与本体之间的深度融合,更要求其实现感知到执行全链路高效协同,兼具高水准系统稳定性与规模化部署的工程化能力。

  • 多模态融合让机器人具备复杂环境的自主感知。机器人依托多传感器融合(卫星、激光雷达、视觉、IMU等)与实时建图技术(结合预加载赛道地图),实现对复杂物理环境的自主感知,在坡道、急弯、不平整路面及动态障碍等场景中保持稳定运行,显著提升对多样化真实环境的适应能力。
  • 强化学习与运控突破赋予机器人高拟人动态运动能力。当下,通过在仿真环境中大量开展化强化学习训练,并结合高质量人类运动数据的采集与应用,持续优化运控算法,同时在现实环境中进行持续适配与调优,机器人在运动过程中的实时感知、平衡稳定、姿态优化及拟人化表现均取得显著提升,实现了长距离赛道中的自主导航、动态避障与路径优化。
  • 热插拔换电与液冷散热是关键突破,保障机器人长时连续运行。热插拔实现机器人高效电池更换与补能;同时通过轻量化设计、能耗优化、智能功率分配及液冷散热系统的多维升级,全面提升机器人整体续航表现,二者结合为机器人长时间运行的连续性、稳定性提供双重支撑。
  • 软硬一体的系统协同与工程化能力获突破,成赛事亮点与后续攻坚重点。面向实际物理环境与作业任务需求,机器人需持续学习适配新环境、新任务,实现感知、决策、执行模块的全链路高效协同;同时推动算法模型与不同构型的硬件本体深度融合与精准适配,打通实时交互链路,在复杂任务中保障响应速度、控制精度与系统稳定性,从而加速向高可靠性、可维护性及规模化部署的工程化落地演进。

人形机器人商业化跑出“中国速度”, 2030 年全球出货量将超 51 万台

总体来看,人形机器人正向“感知—学习—决策—执行”闭环的具身智能体系演进,工程化能力成为产品商业应用落地的核心,赛事验证能力也将加速向真实场景迁移。

回顾2025年,以中国厂商引领的全球人形机器人市场迎来爆发,出货量超1.8万台。其中,以技术验证、展示交互为主的文娱表演、教育科研及导览导购等场景应用出货量占比超过85%,工业制造、仓储物流场景也已开展一批试点探索。

IDC预测,到2030年全球人形机器人出货量将超过51万台,随着本体升级、应用价值提升、生态共建推进及商业模式持续完善,行业将逐步进入规模化应用阶段,实现近95%的年复合增长率。

本体升级:中国厂商领跑硬件规模化突破

  • 市场格局: 2025 年中国厂商人形机器人出货量预计占全球 95%,在硬件制造与规模化领域形成绝对主导优势;同时,多家中国头部厂商预计将在 2026 年实现万台级产能,进一步强化规模化供给能力,并有望持续巩固这一先发优势。
  • 本体升级:聚焦本体结构优化、关节与能源系统升级、量产能力提升及运控算法优化,为后续商业化落地筑牢硬件基础。此外,作为精细操作核心载体的灵巧手,也将迎来快速发展。
  • 品类增长:轮式与全尺寸双足人形机器人是增速最快品类。其中,轮式人形机器人于2025年应用起步,凭借更高的稳定性与可靠性可快速适配并运行于室内及半结构化环境,预计到 2030 年实现年复合增长率约120%的快速发展;全尺寸双足人形机器人依托全方位的灵活性实现更广泛场景落地,年复合增长率预计超 95%。

应用价值:从技术验证向生产力工具跃迁

  • 工业加速:联合工业龙头企业开展场景探索,完成节拍、作业成功率及连续作业稳定性验证后,加速工厂环境落地推广,预计2026 年以出货增速超 200% 居首。IDC 调研显示,未来3年,用户计划进一步在码垛、搬运、拾取、上下料场景应用机器人的比例均超 80%,这些场景可作为重点突破方向。
  • 服务深入:向个性化服务延伸,通过优化用户满意度与客户粘性,拓展在导览导购、餐饮等商业服务市场的应用空间。

生态共建:数据、模型与场景的协同创新

  • 数据规模:融合仿真数据、互联网视频数据及各类数采中心的实操数据,推动虚实数据融合与规模扩张,为核心算法与具身智能的通用能力提升提供关键支撑。当下,中国已汇集上万小时、近千TB数据集,并牵头立项全球首项《人形机器人数据集》国际标准。
  • 模型迭代:加速机器人运动模型的升级以提升运控能力,推动世界模型与VLA模型的深度融合以增强智能泛化性,从而强化人形机器人的具身智能通用能力。全球头部人形机器人及AI模型厂商正持续加速底座模型的迭代升级。
  • 场景共创:面向真实产业应用场景,推动应用开发与解决方案的生态共建,打通从技术验证到规模化应用的关键链路,加速人形机器人技术的产业化落地。

商业模式:RaaS(机器人即服务)加速推广

  • 租赁、订阅等RaaS模式通过降低用户的使用门槛,显著加快市场对人形机器人的认知与推广速度。IDC最新调研显示,用户对RaaS模式的接受率较上一年翻倍。随着服务体系、计费模式及运维体系完善,RaaS普及将进一步提速。

IDC认为,2026北京亦庄人形机器人半程马拉松已成为观察人形机器人技术成熟度与产业进展的重要窗口。赛事不仅验证了关键技术能力,也加速了产业生态构建与商业化进程。未来2–3年,人形机器人行业将进入关键发展阶段,厂商竞争将从技术展示转向实际应用能力与商业价值交付。具备系统级能力与工程化落地能力的厂商,将在新一轮市场竞争中占据主导地位。

本文核心内容引自IDC相关报告:

IDC《Worldwide Annual Humanoid Robotics Tracker》(即将发布)

IDC《具身智能与人形机器人:中国工业落地新机遇》(Doc# CHC53325326,2026年2月)等。

了解更多:

人形机器人正处于从“技术可行”迈向“商业可行”的关键窗口期,领先企业已经开始加速布局并锁定核心场景。对于仍在观望的企业而言,留给试错与判断的时间正在快速减少。

基于长期跟踪与一线调研,IDC已形成覆盖市场规模预测、重点行业机会、应用优先级排序及厂商竞争格局的完整研究框架,可为企业提供从战略判断到落地路径的系统性支持,帮助快速识别可规模化复制的商业机会。

如果您正在:

  • 评估是否进入人形机器人赛道
  • 寻找优先落地的高价值应用场景
  • 分析重点厂商能力与合作机会
  • 制定未来2–3年的业务布局与投资策略

欢迎与IDC研究团队直接联系,获取最新研究数据与定制化洞察支持。我们也可根据您的业务需求,提供一对一交流与专项分析,帮助您在关键窗口期做出更快、更准的决策。

请点击此处与我们联系。

Lily Li - Research Manager - IDC

Lily Li is a research manager for emerging technologies in IDC China. She is responsible for conducting research and analysis for Internet of Things (IoT) in the same country. She is also involved in global and regional consulting as well as business development in related markets. Prior to joining IDC, Lily has had in-depth working experiences in the urban digital transformation (DX) field and a wide range exposure to Smart City developments. She has a deep understanding of the status quo and is knowledgeable about the market's future trends. Lily holds a master's degree from the Graduate University of Chinese Academy of Sciences (GUCAS).

医疗大模型的准确率已从80%提到95%,但真正的下一站不是更准的模型,而是智能体驱动软件重构。IDC最新实测揭示:通用大模型与医疗大模型的差距正在收窄,未来的分水岭在于——谁能用智能体重塑长流程业务。

本文核心观点来自IDC于2026年4月发布的两份最新研究报告,为医疗机构及软件厂商提供技术选型、产品演进与市场策略的参考。

医疗大模型技术的价值初步得到认可

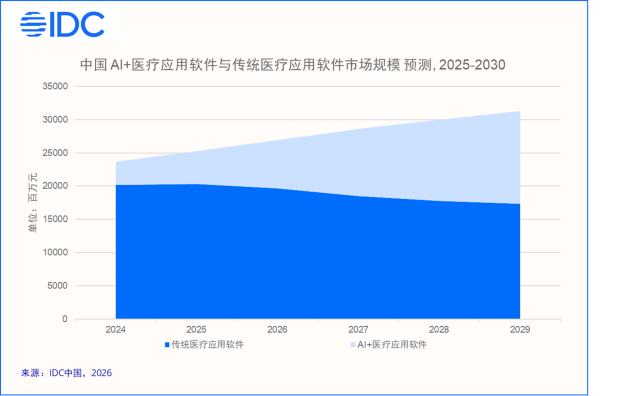
从通用大模型到部署垂直医疗大模型,2025年大模型在中国医疗体系中的应用进程被显著加速。医疗机构对这一技术的态度从被动向主动合作转变,部分机构展现出了付费意愿。2025年AI+医疗应用软件市场规模达到35.4亿元人民币,预测到2030年市场规模将达到140.0亿元人民币,渗透率达44.7%,成为医疗应用软件市场的重要增长来源。

医疗大模型实测:头部厂商的模型实现从性能到质量的综合能力提升

医疗大模型作为重要基座,其能力将影响智能体在医疗场景的能力,因此继2025年3月的第一次实测之后,IDC展开了第二次医疗大模型实测工作,此次收录的医疗大模型厂商包括百川智能、东软集团、福鑫科创、浪潮云、讯飞医疗、卫宁健康(按名称首字母排序)等发布了医疗大模型的厂商。设计了目前医疗机构最为广泛采用的医学知识、健康咨询、门诊病历生成、辅助诊断、病历分析、检验检查解读、诊后管理及随访场景实测。经过实测,IDC 有以下发现:

  • 模型在场景中的表现较去年显著提升。在任务场景表现方面,厂商的准确率较2025年有明显提升,尤其是客观选择题方面正确率从80%提升至95% ,集中在了案例类的题目;在分析类场景中,头部能够全面考虑给出的信息,引用给定的信息和出处,多模态融合决策分析,给出全面性、可循证的信息。
  • 医疗大模型之间呈现梯队化差异。相较于第一期的测试,头部厂商的大模型,如东软集团、讯飞医疗、卫宁健康等(按名称首字母排序)在各类场景中的准确率、专业度、可解释性明显提升,呈现出专业医师的水平,同时其模型性能、生成质量、模型数据显著改善。
  • 服务及落地能力形成了明显差异。基于厂商的基因不同,厂商在AI方面的人才结构、业务和客户资源、对产品的理解能力不同,部分技术厂商在向医疗领域切入时,会发现其能力方面表现较好,但是在落地应用、产品开发及验证、客户拓展等方面与头部厂商形成了明显差异;同时,医疗背景厂商在技术表现上较优,但对其AI方面能力的认可较低。
  •  

未来,以医疗领域的大型模型为基础,加速软件向AI原生化革新,重塑业务流程

在本次实测中,IDC同时纳入通用大模型,根据结果发现,头部的医疗大模型和头部的通用大模型在一些标准化程度较高的病历生成、检验检查解读,以及这些单点化场景的结果差异并不显著。因此,相对于发展全科的医疗大模型以及外挂的单点智能体,行业发展将从以下两点展开:

  • 医疗大模型需持续提升模型的性能及生成质量,同时深入肿瘤、妇科、儿科等专科的数据训练,完善门诊到住院的长流程的场景化模型训练,从而为智能体奠定基础;
  • 从单点的医疗软件+智能体的形式,转变成Agent原生的软件体系,从而发挥出大模型的推理、决策,以及智能体的自主、执行等能力,切入更长流程的业务,打造更灵活的业务流程。

适配技术发展,厂商所须具备的能力也需要对应提升

短期,跑马圈地,通过高频场景的Agent占市场先机。软件+AI形式仍将是短期内大模型技术进入医疗机构的重要落地形式,也成为了厂商产品进入医院市场的重要方式,厂商需要从高频的病历生成、检验检查解读等场景切入,尽快完善医疗软件+AI的产品及服务能力,尤其与HIS、EMR等主流软件的融合,加速验证该类产品的成熟度,从而快速抢占医院的AI需求,从而为后续的增值扩展合作建立基础。

中长期,重构软件,储备全栈式智能体能力切入长流程场景。厂商需要拓展更面向复杂的手术、住院的医疗场景,从而形成差异化竞争。厂商一方面需要重新构建由智能体驱动的软件体系,储备从全域数据平台建设、数据治理、数据标注、模型开发训练、智能体开发等综合技术能力,另一方面也要深入医院实际工作和业务系统,加深对长流程业务场景的理解。

配套按量、按需、按效果等多元化付费模式。近年来医疗机构的信息化预算收缩,而大模型及智能体的广泛应用需要配套软件及硬件的全面升级,面对高昂的费用支出,医疗机构将会望而却步。因此,厂商需要调整合作模式以适配用户的需求,包括按照分期付费、调用次数付费、按照资源消耗付费、按照使用效果付费模式等的前期探索也是厂商取得成功的关键。

本文核心观点来源于以下IDC研究报告:

  • 《中国医疗大模型技术评估,2026》(Doc# CHC53377725,2026年4月)
  • 《中国医疗软件系统解决方案市场预测, 2026-2030》(Doc# CHC53828426,2026年4月)

医疗大模型的竞赛,正在从“模型有多强”转向“业务流能改多深”。IDC最新实测显示,当标准化任务的准确率突破95%之后,真正的分水岭已经出现——谁能用智能体重构长流程业务,谁才能真正占领未来五年的医疗软件市场。

如果您正在关注:

  • 医疗大模型的真实落地能力与选型评估
  • 智能体如何与HIS、EMR等核心系统深度耦合
  • 从“软件+AI”到“Agent原生”的路径规划
  • 医疗AI应用的付费模式与ROI测算

IDC医疗行业研究团队持续追踪医疗大模型、智能体应用及医疗软件市场,拥有覆盖技术评估、厂商实测、市场预测的完整研究体系。欢迎随时与我们联系,获取报告更多信息,或针对您业务场景的定制化交流。让决策,先于趋势。

请点击此处与我们联系。

Erin Lin - Senior Market Analyst - IDC

Erin Lin serves as a senior market analyst of the IDC China Health Insights group. She is responsible for conducting research and analysis about the health industry for both domestic and regional markets. She is also involved in consulting and business development in related markets. Before joining IDC, Erin had four years of experience in medical administration; then served as an analyst in the health industry for two years. Erin is familiar with healthcare institutions and related businesses, and has been gathering deep insights into the health industry and emerging medical technologies. Erin holds a master's degree in Leadership and Management in Health and Social Care from the University of Southampton, and a bachelor's degree in Clinical Medicine from Capital Medical University.

AI is starting to be framed as a price war. Vendors are cutting costs, model access is becoming more competitive, and the market is beginning to assume that cheaper AI will decide the winners.

That view is not wrong. It is just not deep enough.

What is happening now is bigger than pricing pressure. The market is not simply resetting the cost of AI. It is resetting the enterprise application model. And in that shift, price matters, but outcomes matter more.

From an IDC perspective, this is the real issue: enterprises are moving from a world where employees use applications to do work to one where agents increasingly become the work layer itself. That is a major change in how software is consumed, how value is created, and how buying decisions will be made.

In the old model, users opened applications, navigated workflows, triggered tasks, and completed processes. Automation improved parts of that model, but people still sat at the center of execution.

In the new model, employees express intent, and agents increasingly interpret, orchestrate, and act across systems, with guardrails in place. The application does not disappear, but it fades into the background. The workstream becomes the interface.

That is why the AI price-war narrative misses the point. Enterprises are not buying AI because it is cheap. They are buying AI to improve productivity, accelerate decisions, reduce friction, strengthen customer experiences, drive better business outcomes, and increase sustained economic value. The real competition is not over lowest-cost intelligence. It is over who can deliver trusted, measurable outcomes at scale.

The technology is moving faster than enterprise readiness

Enterprise software vendors have responded quickly to the AI push. They are embedding assistants, conversational interfaces, agentic capabilities, and tools for building new AI-driven workflows. At the same time, AI-native platforms are offering alternatives that promise faster innovation and, in some cases, lower cost.

But the key issue is not whether the technology is available. It is whether enterprises are ready to use it now.

In many cases, they are not. This is the gap that matters most right now. Organizations may be eager to adopt AI, but many are not yet prepared to move from human-led application workflows to agent-driven operating models. Lower prices will encourage experimentation, but they will not fix the operational weaknesses that limit scale and business value.

That is where the market will be won or lost.

Four issues will decide who gets value

Skills must shift from usage to orchestration
The move to agent-driven work demands a different set of skills. Employees need to do more than know how to use software. They need to define intent clearly, manage exceptions, understand workflow dependencies, and evaluate AI-driven outputs.

IDC research finds that 44% of organizations have prioritized an AI-ready workforce in 2026 to enable employees to use AI assistants and agents.

(IDC Future Enterprise Resilience and Spending Survey, Wave 1, March 2026 )

This raises the importance of prompt design, orchestration thinking, API awareness, and analytical judgment. These are not side skills. They are becoming essential to turning AI into real performance improvement.

Governance becomes the scaling mechanism
Agentic systems raise the stakes on trust. These systems do not just assist; they can take action across systems, shape decisions, and influence business outcomes. That creates new challenges around security, identity, explainability, compliance, and control.

IDC research continues to show that weak governance and unclear ROI are among the top reasons AI initiatives stall.

IDC research also finds that 39% of organizations are prioritizing AI governance in 2026 to establish trusted AI decision and risk frameworks, while 35% report difficulty quantifying and demonstrating AI ROI to stakeholders.

(IDC Future Enterprise Resilience and Spending Survey, Wave 1, March 2026 )

In an agent-driven model, governance is not a back-office exercise. It becomes the operating discipline that allows organizations to scale AI with confidence and trust.

Operating models need redesign
Enterprises cannot simply layer agents onto existing workflows and expect transformation. Agent-driven execution changes the role of the employee, the structure of the process, and the logic of oversight.

IDC research finds that 46% of organizations are prioritizing their AI business strategy in 2026 to increase the adoption of AI use cases tied to business goals.

(IDC Future Enterprise Resilience and Spending Survey, Wave 1, March 2026 )

Organizations need to rethink where humans stay in the loop, how exceptions are handled, how performance is measured, and how trust is maintained. This is not a feature upgrade. It is an operating model change.

Data and integration still decide the outcome
Agents are only as good as the systems and data they can access. If data is fragmented, APIs are weak, and workflows are disconnected, agent-driven execution will break down quickly.

This is why the most visible AI layer is rarely the hardest problem. The real challenge is below the surface: trusted data, strong integration, clear lineage, high-quality metadata, and resilient process connectivity. Without that foundation, outcome-based AI models collapse under complexity.

 IDC research finds that 46% of organizations are focused on AI data-ready architecture in 2026, implementing controlled access to all enterprise data, whether structured, unstructured, or event streams.

(IDC Future Enterprise Resilience and Spending Survey, Wave 1, March 2026 )

This market is shifting from features to outcomes

That is the real strategic change now underway.

The winners will not be the vendors with the most AI features or the lowest-cost model access. They will be the ones that help enterprises reduce manual effort, improve process completion, increase productivity, and deliver measurable business value.

For enterprise application vendors, embedded AI is becoming table stakes. Buyers will increasingly ask not whether AI is in the product, but whether it improves outcomes across workflows. Vendors that can orchestrate across systems, support trusted execution, and align pricing to measurable value will have the stronger position.

For services providers, the opportunity is also shifting. Enterprises need help redesigning workflows, modernizing integration, strengthening governance, and measuring value. The market will reward providers that can connect AI strategy to operating reality.

For enterprises, the message is simple: buying tools is not enough. Organizations that succeed with AI will invest in operational readiness. They will build new skills, strengthen governance, redesign workflows, and improve data discipline. They will treat AI as a new execution model, not just another feature set.

Price matters, but it is not the main event

None of this means pricing is irrelevant. Lower-cost AI will matter. It will pressure incumbents, expand experimentation, and change software economics.

But price is not the endgame. It is the opening move.

In enterprise markets, the cheapest AI does not automatically win. The AI that wins is the AI that works consistently, securely, and at scale. This is why AI pricing should be viewed less as a race to the bottom and more as a race to the outcome layer.

Bottom line

The market is right to watch AI pricing. It is wrong to make pricing the center of the story.

What is really happening is a shift in the enterprise software model, from users operating applications to agents increasingly executing work across them. That changes how enterprises buy, how vendors compete, and how value is measured.

The winners will not be the ones with the cheapest AI. They will be the ones that help enterprises achieve trusted outcomes at scale.

Price may open the door. Outcomes will decide who stays in the room.

What to watch

There are several signals that will confirm or challenge this shift over the next year.

First, watch buyer conversations. If enterprises start focusing less on AI feature breadth and more on cycle time, productivity, workflow completion, customer experience, and financial impact, that will confirm that outcome-based competition is taking hold.

Second, watch pricing models. If vendors move toward transaction-based, workflow-based, or value-based pricing, rather than simply charging for seats or usage, that will be a clear sign that the market is reorganizing around outcomes.

Third, watch deployment patterns. If organizations continue to pilot AI widely but struggle to scale it across core workflows, it will reinforce the point that operational readiness, not price, is the real constraint.

Finally, watch where value accrues. If the market rewards vendors and providers that can orchestrate across ecosystems and deliver measurable business outcomes, then the real battleground has shifted to the outcome layer. If value moves mainly to the lowest-cost providers, then the price-war thesis will prove stronger than this view suggests.

Mickey North Rizza - Group Vice President - IDC

Mickey North Rizza is Group Vice-President for IDC's Enterprise Software. She leads the Enterprise Applications & Strategies research service along with a team of analysts responsible for IDC's coverage of next generation of enterprise applications including digital commerce, employee experience, enterprise asset management and smart facilities, ERP, financial applications, HCM and payroll applications, procurement, professional services automation and related project-based solutions software, supply chain automation, and talent acquisition and strategies. In her role, Mickey and the team advises clients on these intelligent, modern, and modular enterprise applications for businesses of all sizes with an emphasis on the key trends, opportunities, innovation and the IT and Business Buyer concerns, requirements, and buyer behaviors.

AI infrastructure investment is accelerating at a pace that signals a clear shift from experimentation to long-term commitment. The latest Q4 2025 data highlights just how quickly spending is scaling and where momentum is building across regions and technologies.

AI infrastructure moves from experiment to scale

Worldwide spending on artificial intelligence (AI) infrastructure reached $89.9 billion in Q4 2025, a 62% year-over-year increase from Q4 2024, closing a record year. Full-year 2025 AI infrastructure spending totaled $318 billion, more than double the $153 billion recorded in 2024. Growth was anchored by continued hyperscaler investment in the United States, accelerated server adoption, and the early expansion of sovereign AI programs across emerging regions.

Why it matters

The Q4 2025 results confirm that AI infrastructure investment has moved well beyond initial proof-of-concept phases into a sustained, multi-year capital commitment cycle. Enterprise technology buyers, cloud service providers, and national governments are making long-term decisions about where to build, how much to spend, and which AI workloads to prioritize.

For vendors, this signals a prolonged period of elevated demand across accelerated compute, high-performance storage, and supporting network infrastructure. For enterprises, the data shows that AI capacity is becoming a structural cost of doing business at scale and that late movers risk falling behind on both performance and cost efficiency.

IDC now projects the global AI infrastructure market will surpass $1 trillion by 2029, underscoring the long-term structural importance of investments being made today.

What is shaping AI infrastructure spending

Four key forces shaped AI infrastructure spending in Q4 2025:

  1. U.S. hyperscaler dominance continued to expand. The United States accounted for $69.2 billion, representing 77% of global AI infrastructure spending, growing 81.5% year over year. Large-scale data center buildouts by leading AI platform providers drove sustained demand for GPU servers and high-capacity networking infrastructure. This dominance is expected to persist through 2026 and beyond, though its relative share may moderate as other regions catch up.
  2. Accelerated compute remains the structural backbone. Server spending represented $87.7 billion, or nearly 98% of total AI infrastructure in Q4. Within that, accelerated systems (primarily GPU-based) drove the majority of value. Both ODM Direct and OEM channels saw elevated activity as AI platforms scaled to meet growing training and inference workloads.
  3. China faced export-control headwinds. China (PRC) recorded an 8.1% year-over-year decline in Q4 2025, falling to $8.4 billion, as restrictions on advanced semiconductor exports continued to constrain access to leading-edge accelerators. Despite this, China remains the second-largest AI infrastructure market globally, with significant domestic investment in alternative compute architectures.
  4. Emerging regions accelerated sharply. The Middle East & Africa region grew by more than 500% year over year in Q4 2025, reaching $1.8 billion, driven by sovereign AI initiatives in the Gulf region and targeted government investment in national AI infrastructure. Asia/Pacific (excluding Japan) grew 47%, and Western Europe advanced 42%, both benefiting from hyperscaler expansion and regional cloud buildouts.
Total AI Infrastructure Spending (Q4 2025)$89.9 billion
Year-over-Year Growth (Q4 2025 vs. Q4 2024)+62.2%
Full-Year 2025 AI Infrastructure Spending$318 billion
Full-Year 2024 AI Infrastructure Spending$153 billion (YoY +107.6%)
Server Share of Q4 2025 AI Spending$87.7 billion (97.6%)
Storage Share of Q4 2025 AI Spending$2.2 billion (2.4%)
USA Market Share (Q4 2025)$69.2 billion (77.0%, +81% YoY)
China (PRC) Market Performance (Q4 2025)$8.4 billion (9.4%, -8.1% YoY)
Middle East & Africa Growth (Q4 2025)$1.8 billion (+535% YoY)
2029 Forecast — AI Infrastructure>$1 trillion

What to expect in 2026 and beyond

IDC projects AI infrastructure spending will reach $487 billion in 2026, representing approximately 53% year-over-year growth. This marks a moderation from 2025’s triple-digit gains, but still reflects one of the largest absolute-dollar expansions ever recorded in a single IT market segment. By 2029, global AI infrastructure is forecast to exceed $1 trillion, with a five-year compound annual growth rate (CAGR) of approximately 31% from 2025.

What could accelerate this trajectory:

  • Faster-than-expected scaling of inference workloads as enterprise AI application deployment broadens
  • Expansion of sovereign AI programs in the Middle East, Southeast Asia, and Europe, driving incremental greenfield investment
  • New model architectures and AI agent frameworks requiring deeper, more distributed compute infrastructure

What could constrain growth:

  • Power generation and grid capacity constraints, which remain the primary operational bottleneck for new data center commissioning in major markets
  • Memory and storage component scarcity, which can increase server BOMs and slow procurement cycles
  • Expanded export controls and data sovereignty regulations, which could reshape where AI workloads are deployed and which vendors win enterprise deals

Investors and technology buyers should monitor Q1 2026 capital expenditure guidance from leading hyperscalers and AI platform providers, as these forward signals remain the most reliable leading indicator of near-term infrastructure demand.

For comprehensive vendor share, forecast data, and taxonomy detail, see: IDC Worldwide Quarterly AI Infrastructure Tracker. For taxonomy and methodology definitions, see: Worldwide Artificial Intelligence Infrastructure Tracker Taxonomy, 2025.

Juan Seminara - Research Director, Worldwide Infrastructure Trackers - IDC

Juan Pablo Seminara is the Research Director for IDC's Worldwide Enterprise Infrastructure Trackers within the Data & Analytics organization. Mr. Seminara is responsible for leading a team of analysts in charge of the product concept, roadmap, implementation, execution, and client support for IDC’s enterprise infrastructure Trackers and forecast worldwide. In his role, he oversees the quarterly interaction amongst a global group of more than 50 IDC analysts in different regions that participate in the execution and market trend analysis of all enterprise infrastructure Trackers and forecast for IDC.

Digital sovereignty is moving from concept to strategic requirement. As organisations focus on managing IT risk, control, and compliance, expectations towards providers are rising. This blog explores why the “sovereign” label is no longer enough and what it takes to meet these new demands. 

Many technology providers in Europe today claim to offer “sovereign” solutions. 

But ask a simple follow-up question, what exactly makes them sovereign, and the answers quickly become less clear. 

At the same time, demand for digital sovereignty is increasing. Over the past 15 months, geopolitical and economic uncertainties have pushed the topic higher up the agenda. When asked about digital sovereignty, almost 50% of organisations globally say their interest has increased compared to the previous year. 

But focusing on geopolitics alone misses the bigger shift. 

Why digital sovereignty expectations are changing 

As interest grows, so do expectations. Digital sovereignty is no longer an abstract or purely regulatory concept. It is becoming an essential strategic requirement in IT decision-making. 

At the same time, it remains a source of confusion. Many organisations still struggle to define what sovereignty actually means in practice, what is required to achieve it, and whether they need it at all. And then you need to ask, who can you trust? And then you need to ask, who can you trust? 

This creates a gap in the market. Providers talk about sovereignty. Customers are still trying to understand it. 

What is really driving digital sovereignty adoption 

Despite the geopolitical backdrop, the main drivers are far more practical. 

Organisations are prioritising control over their data, stronger governance and compliance, and the ability to manage risk. In Europe in particular, protection against extra-territorial data requests has emerged as the highest concern. 

This is where expectations begin to change. 

More than 40% of organisations globally say they will increase the frequency and granularity of their reviews of IT vendors and platforms to better assess and manage this risk. Furthermore, when asked what was most needed to achieve data sovereignty, 85% cited enhanced tools and solutions for governance, risk and compliance as the extremely or very important. 

Thus, if digital sovereignty is ultimately about managing IT risk, it cannot be reduced to a label or a feature. It needs to be something that is tangible and can be clearly explained, implemented, and validated. 

This also changes the role of providers. They need to help organisations assess their risk appetite, manage that risk, and deliver the solutions required to meet these expectations. 

And this is where many providers are not yet aligned. 

What digital sovereignty actually requires 

Part of the challenge lies in how sovereignty is framed. It is often treated as a single capability, when in reality it spans multiple dimensions. 

One practical way to approach it is through three areas: data sovereignty, technical sovereignty, and operational sovereignty. These form the three key pillars of cloud sovereignty, which itself represents a subset of the broader concept of digital sovereignty. 

Together, these define how control is exercised across data, infrastructure, and operations. 

For providers, this raises the bar. Sovereignty is no longer something that can be communicated in broad terms. It needs to be articulated across these dimensions, in a way that is transparent and verifiable. 

Where sovereignty really matters: high-risk workloads 

It is also important to clarify where sovereignty actually needs to be applied. 

Sovereign requirements are typically focused on workloads that involve sensitive data, regulatory exposure, and or critical business processes. This increasingly includes certain AI use cases, where data control and model governance are essential. 

This is also where trust becomes central. 

Customers need confidence that sovereignty claims hold up under scrutiny, especially in high-risk scenarios. It is no longer enough to state that a solution is sovereign or to only address isolated aspects such as data residency or localisation. 

Providers need to demonstrate how sovereignty is ensured, where the boundaries lie, and what guarantees are in place. This assurance must extend across the entire partner ecosystem, from primary providers to their partners and beyond. 

From positioning to proof 

The conversation around digital sovereignty is evolving quickly. Expectations are rising, and with them, the level of scrutiny applied to providers. In this environment, sovereignty is no longer a positioning or marketing statement. It is something that needs to be clearly defined, agreed upon by all stakeholders, consistently implemented, and credibly demonstrated.

For many providers, that requires a shift. From broad claims to precise explanations. From messaging to evidence. And ultimately, from sovereignty as a label to sovereignty as a trust model that delivers autonomy, control, transparency, and resilience.

IDC’s strategic guide, Digital sovereignty beyond the label, breaks down what that shift looks like in practice, including a self-assessment framework across the three pillars of cloud sovereignty: data, technical, and operational.

One global technology provider put this to the test ahead of a major infrastructure launch, asking IDC to stress-test its sovereignty leadership claim before going to market. The case study covers what changed as a result.

For a closer look at how customer expectations are shifting and what that means for positioning, the webinar Digital sovereignty beyond the label: how customer expectations are changing is now available on demand.

 
All data sources: IDC Europe, Worldwide Digital Sovereignty survey 2025, July 2025 

Rahiel Nasir - Research Director, European Cloud Practice, Lead Analyst, Digital Sovereignty - IDC

Rahiel Nasir is responsible for leading and contributing to IDC's European cloud and cloud data management research programs, as well as supporting associated consulting projects. In addition, he leads IDC's worldwide Digital Sovereignty research program. Nasir has been watching technology markets and writing about them throughout his professional life.

Global disruption is not caused by an isolated event. It is continuous, multidimensional, and increasingly interconnected. Economic volatility, geopolitical fragmentation, regulatory expansion, workforce transformation, and rising customer expectations are converging to reshape how organizations operate and compete.

IDC’s FutureScape 2026 identifies this convergence of forces as Navigating the Crosscurrents of Disruption. This defines how organizations can respond to these overlapping pressures with deliberate strategy rather than reactive adjustment. At the core of that response is agentic AI, not as an isolated capability, but as a governed, strategy-aligned force that converts disruption into momentum.

Without deliberate navigation, leaders risk being dragged sideways by disruption, leaving them unprepared to capture the benefits of the agentic economy.

A framework for navigating compounding disruption

Crosscurrents are not independent variables that can be managed in sequence. They have a cascading effect.

A regulatory shift in one market affects supply chain strategy. Geopolitical instability reshapes technology sourcing decisions. Workforce disruption intersects with AI adoption. Leaders acting on one pressure are already absorbing consequences from several others.

This is the decision environment mapped by FutureScape. Not as a catalog of threats, but as an analytical lens for understanding how simultaneous forces compound and where deliberate action creates leverage.

Leaders must balance competing priorities while maintaining forward momentum. Success depends less on predicting disruption and more on navigating it effectively.

AI sits at the intersection of these crosscurrents. It is subject to regulatory and sovereignty constraints and is often limited by fragmented implementation. Yet it can also serve as a mechanism for coordination, enabling organizations to integrate data, align decisions, and respond more dynamically to economic and operational complexity at scale.

When governed and aligned with enterprise strategy, AI transforms the crosscurrents into momentum. Deployed without that alignment, it can amplify the complexity leaders are already facing.

The structural impact of disruption

The crosscurrents are no longer hypothetical pressures on the horizon. They are already reshaping infrastructure decisions, cost structures, and leadership accountability across technology suppliers and enterprise buyers.

Disconnected systems, duplicated investments, and uneven execution are introducing new layers of cost and operational burden that organizations must actively manage.

Architecture is being reshaped by sovereignty and regulation

This shift is most visible in AI architecture. Sovereignty laws and evolving regulatory requirements are forcing organizations to make deliberate decisions about where data resides, how models are deployed, and which systems can operate across jurisdictions.

Compliance fragmentation is becoming a defining constraint. Organizations must navigate inconsistent regulatory frameworks across regions, often requiring localized architectures, governance models, and data environments. This limits standardization and increases structural complexity.

IDC predicts that 60% of global firms will split their AI stacks across sovereign zones by 2028. Enterprise architecture is no longer designed for global uniformity. It must accommodate regulatory divergence while maintaining cohesion across the organization.

Implementation complexity is slowing outcomes

As AI adoption scales, the focus is shifting from experimentation to execution. Disconnected investments across business units, regions, and use cases are creating duplication, inefficiencies, and inconsistent results.

This increases cost and slows progress. Organizations must fund parallel initiatives, manage overlapping capabilities, and invest in integration to connect systems separated by region and function.

According to IDC research, 40% of organizations will miss their AI goals due to implementation complexity in 2026. The issue is rarely the technology itself. It is the gap between AI deployment and the enterprise structures, governance models, and integration required to make it work at scale.

Complexity becomes the primary constraint

As these forces converge, complexity becomes the defining constraint on progress.

For leaders, this translates into rising costs, slower execution, and reduced strategic flexibility. Organizations must coordinate across architectural boundaries and operational silos while managing regulatory demands and investment trade-offs.

Those that build alignment across architecture, investment, and execution will be better positioned to sustain momentum. Those that do not risk being constrained at every layer of the enterprise.

Maintaining direction in a shifting environment

Navigating the crosscurrents requires getting three foundational areas right. These areas are interdependent, and gaps in any one limit what is possible in the others.

To move forward, leaders must:

1. Define ownership and strategic direction
Crosscurrents do not respect organizational boundaries. Economic risk, AI governance, regulatory compliance, and technology investment are converging into the same course of decision making. Leaders must ensure the right stakeholders own these decisions and that CIO and CFO mandates are aligned around shared outcomes rather than managed in parallel.

2. Evolve workforce models for new operating realities
Workforce fragmentation is increasing across regions, regulatory environments, and technology stacks, creating inconsistencies in execution and decision-making. Navigating at the pace of change requires unifying this environment through human–AI collaboration as a core operational capability.

3. Strengthen foundations for integration and adaptability
Infrastructure decisions made today define future strategic options. Data foundations, integration architecture, and sovereignty-ready systems are not simply IT priorities. They are decisions about where the organization can operate and how quickly it can adapt.

Deliberate navigation across these three fronts separates organizations positioned to capture the agentic economy’s upside from those that lose direction in the crosscurrents.

The stakes of standing still

The crosscurrents shaping the agentic economy are not temporary conditions. Economic and geopolitical volatility, regulatory fragmentation, and workforce disruption are structural features of the environment in which leaders now operate.

Leaders who build strategic alignment, workforce capability, and infrastructure readiness will not only maintain direction within this changing environment but also convert external pressures into coordinated progress. That preparation cannot happen at the point of disruption. It must be in place before challenges arise.

Navigating the crosscurrents is where that work begins. Understanding the crosscurrents, mapping their interactions, and identifying where deliberate action creates the most leverage are the first steps to success in the agentic economy.

Explore navigating the crosscurrents of disruption in depth

Explore navigating the crosscurrents of disruption in depth

FutureScape 2026 includes detailed research, analyst perspectives, and webinars that expand on the themes within navigating the crosscurrents.

Core research

Analyst perspectives

On-demand webinars

eBooks
IDC - -

International Data Corporation (IDC) is the premier global market intelligence, data, and events provider for the information technology, telecommunications, and consumer technology markets. With more than 1,300 analysts worldwide, IDC offers global, regional, and local expertise on technology and industry opportunities and trends in over 110 countries. IDC’s analysis and insight help IT professionals, business executives, and the investment community make fact-based technology decisions and achieve their key business objectives.

IDCの最新レポートでは、今回の中東での戦争が2026年に向けてクラウドのレジリエンス、サイバーリスク、サプライチェーン、IT計画にどのような影響を及ぼすかを考察しています。
地政学的危機は、明確な予兆なく発生することがほとんどです。そして一度発生すれば、デジタルインフラ、サプライチェーン、テクノロジー運用に即座に大きな負荷がかかります。
今回の中東での戦争は、現代のデジタル経済、そして混乱下でも事業継続を担うCIOにとって、構造的なストレステストとなっています。
過去の紛争と異なり、現在の企業IT環境はクラウドインフラ、サブスクリプション型サービス、そしてグローバルに相互接続されたサプライチェーンに大きく依存しています。そのため、影響は局所的にとどまらず、地域・システム・パートナーを横断して急速に拡大します。
CIOにとっての課題は、単なるリスク管理ではありません。変化する状況に適応しながら事業運営を維持し続けることです。

IDC の見解:From Conflict to Continuity: How CIOs Can Respond to Disruption from the Middle East War.

なぜ今回の危機はCIOにとってこれまでと異なるのか

企業ITは、従来の内部完結型環境から、高度に分散されたエコシステムへと移行しています。

現在の企業は以下に依存しています:

  • クラウドプロバイダーおよびプラットフォームサービス
  • 分散型インフラおよび運用
  • テクノロジー供給および提供におけるグローバルサプライチェーン

この依存構造は、新たなリスクを生み出しています。

地域の不安定化は、以下に影響を与えます:

  • アプリケーションの可用性およびパフォーマンス
  • ハードウェア導入スケジュール
  • サイバー攻撃の増加
  • インフラおよびエネルギーコスト

これらの圧力は、既存のデジタル戦略の前提をすでに揺るがしています。

CIOにとっての優先事項は、自社のリスク露出(エクスポージャー)を把握し、それが業務にどう影響するかを理解することです。

エクスポージャーマッピングとシナリオプランニングから始める

最初のステップは、どこにリスクが集中しているかを特定することです。

CIOは以下の4つの観点で依存関係を整理すべきです:

  • 影響地域に所在する従業員・契約社員
  • 影響市場に関連する顧客および収益源
  • 混乱が発生している物流ルートやサプライヤー
  • 地域インフラに依存するアプリケーション、データ、運用

このマッピングが意思決定の基盤となります。

その上で、シナリオプランニングにより複数の展開に備えることが可能になります。

IDCは、CIOが検討すべき2つのシナリオを提示しています:

  • 地域の不安定状態が長期化するケース
  • エネルギーやサイバー領域に波及する広範なエスカレーション

シナリオごとに、レジリエンス、セキュリティ、投資の優先順位は変化します。

CIOが今優先すべきこと

CIOは以下の5つを直ちに見直す必要があります:

1. クラウドとインフラのレジリエンス再評価

単一リージョンや特定プロバイダーへの依存度を確認し、フェイルオーバー体制のギャップを特定する。

2. サイバーセキュリティの強化

脅威の増加を前提に、検知・対応・復旧能力を強化する。

3. テクノロジーサプライチェーンの多様化

供給のボトルネックを特定し、単一供給源への依存を低減する。

4. データ主権とコンプライアンスの見直し

地政学的緊張はデータローカライゼーションや規制強化を加速させる。

5. 人材・業務継続計画の整備

リモートワークや代替コミュニケーション手段を含め、業務継続を確保する。

これらは新しい課題ではありませんが、「同時に、かつ迅速に」対応する必要性が高まっています。

IDC アジアウェビナー(英語):Asia Pacific IT Spending Outlook 2026: Where to Win Amid Market Volatility

混乱下でのリーダーシップ

レジリエンスは技術課題であると同時に、リーダーシップの課題でもあります。

CIOは不確実性の中で明確な方向性を示す必要があります。成功する組織は、チームが目的を理解し、迅速に行動できる組織です。

有効なリーダーシップ行動には以下が含まれます:

  • 重要システム保護への明確なフォーカス
  • 意思決定の迅速化
  • 課題の分解と優先順位付け
  • 環境の簡素化と強化の機会特定

こうした局面では、技術的負債や運用の非効率、レジリエンスの欠如が顕在化します。

優れた組織は、混乱を「停止」ではなく「行動の契機」として捉えます。

混乱からオペレーショナル・レディネスへ

現在の状況は、地政学とデジタル運用の関係が変化していることを示しています。

CIOはもはや単発のインシデントに備えるのではなく、複数領域に同時影響が及ぶ前提で対応を進めなくてはなりません。

そのためには、継続的なレジリエンス強化が必要です:

  • 依存関係とリスクの可視化の継続
  • 複数シナリオを前提とした計画
  • 日常業務へのレジリエンスの組み込み

この能力を構築できた組織は、不確実性の中でもパフォーマンスを維持できます。

シナリオフレームワークの活用

リスクの把握は出発点に過ぎません。重要なのは、それを意思決定に落とし込むことです。

IDCのレポートでは以下について詳述しています:

  • IT支出やAI投資への影響
  • インフラ、サイバーセキュリティ、人材継続性への考慮点
  • 状況変化を把握するためのリスク指標

執筆者(Authors)

Rick Villars – Group VP, Worldwide Research – IDC

原文:2026年3月23日公開(英語)|日本語版監修:寄藤 幸治

関連する調査やご相談について

より詳細なインサイトや市場動向については、当社アナリストへお気軽にご相談ください。