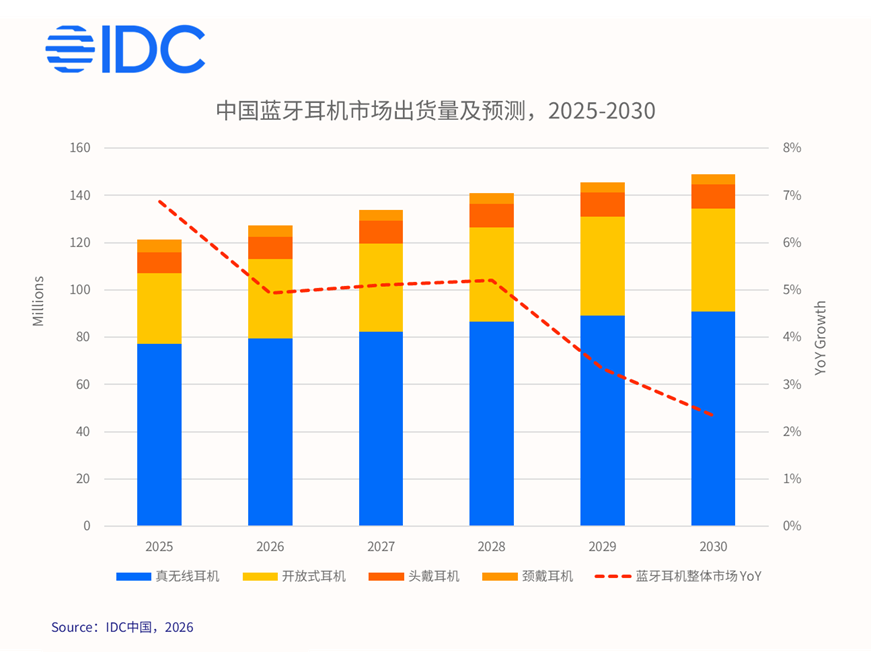
近年来,中国蓝牙耳机市场在经历高速增长后逐步进入结构调整阶段。国际数据公司(IDC)最新发布的《中国无线耳机市场季度出货量跟踪报告,2025年第四季度》显示,2025年,市场出货量达到12,137万台,同比增长6.9%。在整体温和增长的表象之下,产品形态、竞争主体与用户需求正同步发生深层次变化,行业正从规模扩张转向结构优化与价值重塑。

从竞争格局来看,生态协同能力持续强化,手机厂商进一步巩固主导地位;从产品演进来看,开放式耳机在经历高速增长后进入分化发展阶段,增速放缓,同时耳机行业的场景细分化趋势进一步深化;与此同时,AI技术加速渗透,虽仍处于早期探索阶段,但已成为厂商布局差异化的重要方向。基于IDC最新数据与市场观察,本文将对当前市场变化进行解读,并对未来发展趋势与厂商策略提出洞察与建议。
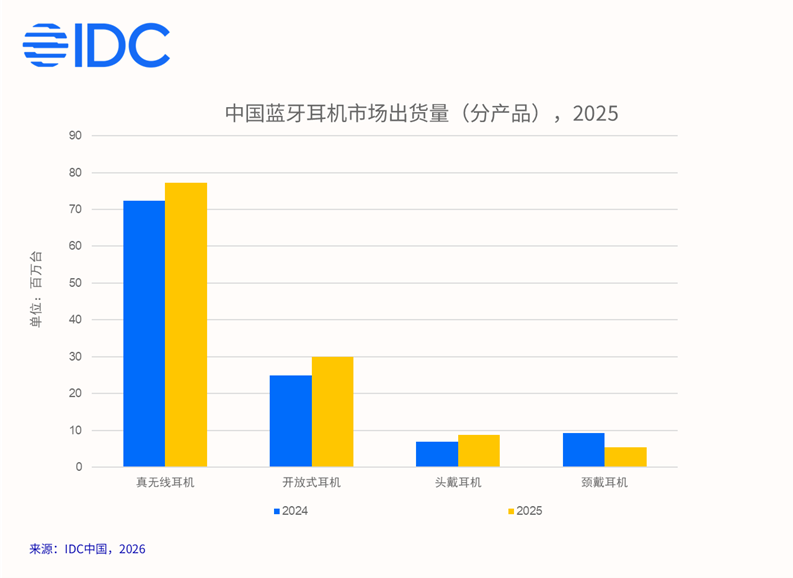
2025年中国蓝牙耳机市场,真无线产品出货7,721万台,同比增长6.7%,入门级产品及与手机绑定的出货政策带动增长。开放式产品出货2,996万台,同比增长20.2%,开放式已从快速爆发阶段逐步转向稳健增长阶段,其中细分市场呈现出不同的发展结构。头戴产品出货878万台,同比增长26.3%,电竞,学习等场景带动入门级市场增长。颈戴产品继续下滑,厂商资源收缩,叠加使用场景被替代。

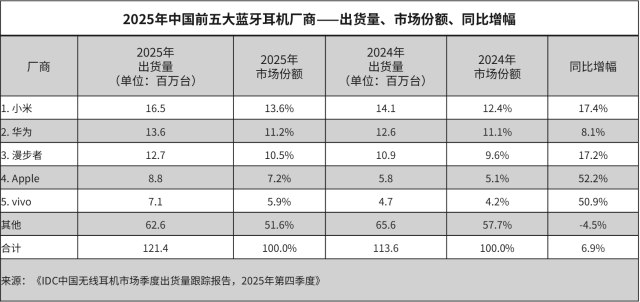
2025年中国蓝牙耳机市场Top 5厂商表现
小米

25年小米蓝牙耳机出货量位居中国市场首位。厂商持续深耕真无线入门级市场,Redmi系列产品形态丰富,迭代节奏稳定,依托高性价比优势与手机生态协同效应,实现了强劲的业务增长。

华为

华为发力布局开放式赛道,拓展耳挂形态并推出耳夹迭代机型,25年其开放式耳机在内部出货份额中提升10个百分点。FreeClip耳夹系列将时尚饰品属性与音频功能结合,在佩戴体验与使用场景上实现创新突破。同时,真无线SE系列持续夯实品牌在入门级市场的竞争力。

漫步者

漫步者依托多子品牌矩阵,在时尚,电竞,性价比等细分赛道实现多系列产品并行布局与快速迭代,覆盖多元消费场景。头戴耳机作为漫步者传统优势品类,25年持续发力,同时通过子品牌快速布局开放式耳夹,耳挂产品。

Apple

Apple推出AirPods 4双版本产品矩阵,有效拉动整体出货量增长,且助力半入耳主动降噪市场增长。9月AirPods Pro 3 上市完成旗舰迭代,进一步巩固其在真无线高端市场的领先优势。

vivo

25年vivo在真无线市场持续推进双品牌差异化布局,vivo耳机聚焦全场景综合体验,iQOO耳机主打电竞性能与高性价比,厂商整体出货量实现稳步增长。其中,vivo TWS A4 依托手机核心渠道优势,出货量实现显著提升。

从头部厂商表现和数据看洞察:2025年中国蓝牙耳机市场三个核心洞察

洞察一:生态协同成核心竞争力,手机厂商主导地位持续巩固

2025年手机厂商在中国蓝牙耳机市场的出货份额占比达48%,较2024年提升7个百分点。其中,中国手机厂商借助与手机的捆绑销售,礼盒赠送等营销模式,依托自身成熟的手机渠道体系,实现蓝牙耳机出货量的显著增长,进一步巩固其市场地位。

洞察二:开放式耳机步入结构分化阶段,增速趋缓但格局重构

2025年开放式耳机出货量同比增长20.2%,其中耳夹增速领先,同比增长51.0%,耳挂同比增长12.3%。耳夹在华为,韶音等头部品牌引领下推进高端化升级,同时通过更新配色,推出联名耳饰等方式,持续强化其时尚饰品属性。耳挂此前受电商低价产品冲击,高端化发展承压。2025年随着手机品牌入局且聚焦中高端市场,行业格局迎来优化调整,当前耳挂产品仍以运动场景为核心定位。

洞察三:AI概念热度攀升,厂商跟风搭载AI相关能力

随着AI概念升温,耳机厂商纷纷将AI能力作为产品差异化卖点加速布局。其中,传统音频硬件厂商受自身研发实力限制,多通过与第三方大模型合作落地AI功能。从应用场景来看,当前AI功能布局较为单一,主要集中在翻译,会议记录等工作场景,AI整体应用仍处于浅层阶段。
2026年中国蓝牙耳机发展趋势展望

趋势一:场景化深度细分,耳机从通用产品转向专属化工具

预计26年蓝牙耳机市场竞争核心由参数硬件比拼,转向用户场景需求的精准满足。在运动,睡眠,办公,游戏等主流场景基础上,细分需求持续扩容,产品将针对不同场景,打造高度专业化的形态与功能,并进一步推动一人多机的消费趋势。

趋势二:悦己消费与她经济驱动产品美学与情感化体验升级

悦己消费趋势凸显,女性消费群体成为蓝牙耳机市场的核心增长动力之一,颜值与使用体验并重的需求逐步取代基础音频功能,成为她经济下的重要消费特征。品牌加速打破电子产品中性化刻板印象,聚焦情感化设计与佩戴体验。随着耳机使用场景与时长持续拓展,产品价值由实用功能,延伸至情感陪伴与生活方式表达。

趋势三:技术迭代推动蓝牙耳机向智能硬件加速演进

未来随着AI,连接与低功耗技术持续升级,蓝牙耳机将逐步搭载更高算力芯片与轻量化智能系统,向具备本地AI能力,部分场景独立交互的智能硬件方向靠拢,减少对手机的依赖。当前芯片算力,电池续航与功耗仍是行业需持续突破的瓶颈。与此同时,开放式耳机凭借舒适,可长时间佩戴的特性,有望成为AI智能硬件的重要载体之一。

结合蓝牙耳机市场2025年的市场洞察与2026年的市场趋势,IDC为行业参与者提出以下三点建议:

建议一:突破技术同质化,构建差异化核心竞争力

摆脱单纯比拼硬件参数与价格竞争,推动技术研发从参数竞争转向场景定义。聚焦自身优势细分领域,强化用户体验感知。同时,摒弃单一产品思维,构建覆盖不同需求的产品矩阵,兼顾性价比与情价比,形成独特的品牌竞争壁垒,规避同质化竞争风险。

建议二:融合渠道体验,实现分平台精准触达

线上依托内容电商与直播带货,强化场景化内容传播,利用大数据实现用户精准匹配。线下深化与运营商,潮品店及品牌体验店的合作,构建沉浸式体验场景,提升实操感知与品牌认知。针对悦己消费与她经济趋势,在年轻化平台开展差异化沟通与场景营销,精准覆盖目标用户群体。

建议三:深耕AI功能融合,打造场景化智能体验优势

把握AI技术与蓝牙耳机产业深度融合的行业趋势,摒弃将AI功能作为营销噱头的功利化发展模式,推动AI功能从基础交互层面向场景化赋能方向升级,聚焦用户核心使用需求,让AI技术真正落地到实际应用场景中。

分析师观点

IDC中国研究经理戴翘楚认为,2025年蓝牙耳机市场已显现出生态协同与AI概念驱动的竞争格局,手机厂商主导地位强化。展望2026年,市场将加速向场景化细分和情感化体验转型。厂商需摆脱同质化竞争,通过技术深耕与渠道融合,将AI能力转化为真正的场景化智能优势,把握行业发展机遇。

IDC将持续跟踪中国蓝牙耳机市场及相关技术演进,提供数据支持与前瞻洞察,助力企业制定更具针对性的产品与市场策略。如您希望进一步了解市场数据、竞争格局或定制化研究服务,欢迎随时与IDC保持联系。

如需进一步了解与研究相关内容或咨询 IDC其他相关研究,请点击此处与我们联系。
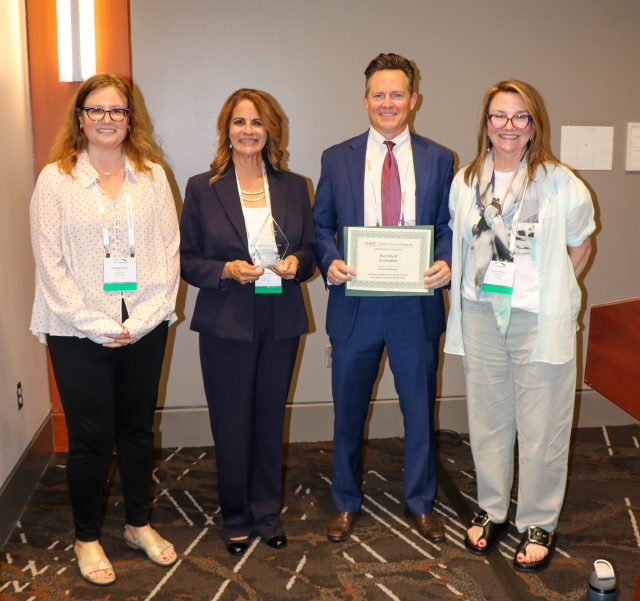
IDC’s Smart City North America Awards program has recognized public safety innovation since its inception, and this year’s competition brought in some of the strongest entries yet. Across the public safety category, five cities and one regional airport demonstrated how they built operational capability around constrained budgets, growing service demands, and the evolving capabilities of artificial intelligence and unmanned systems.

AI adoption challenges in public safety

Given the focus on AI in many of the award nominations, the following data points from IDC’s U.S. Government Buyer Intelligence survey provide important context for the city summaries below:

  • First, data privacy and security concerns ranked highest, with 52% of respondents citing them as a central issue. Budget constraints and digital infrastructure gaps tied for second, each noted by 44% of public safety respondents—significantly higher than the rest of government. Half of public safety agencies allocate just 6–10% of total IT spend to AI, leaving little room for expansion. This makes integration both more critical and more difficult to fund.
  • Second, 48% of public safety agencies name data privacy and security as their top AI security priority, compared with 39% across the rest of government—a 9-point gap. AI-generated misinformation (44%) and audit and accountability (42%) round out the top concerns. Agencies that produce evidence for legal proceedings and operate under civil rights oversight are right to prioritize data privacy and security.
  • Third, public safety agencies are struggling to scale. Eighteen percent have not attempted to scale any AI initiative—almost four times the rate of other government agencies.

Against that backdrop, this year’s winners did what our survey data confirms is rare: they integrated next-generation technologies across systems most agencies leave disconnected, governed them with genuine accountability structures, and measured results against operational outcomes that justified the investment. Drumroll, please…

The 2026 award entries

The headline this year belongs to Scottsdale, Arizona, which took home the Overall Winner award—the top distinction across all categories—for its AI-Powered Real-Time Crime Center with Drone-as-First-Responder program.

The program’s strength is integration: Scottsdale’s Real-Time Crime Center brings together more than 5,800 cameras, citywide license plate recognition, gunshot detection, body-worn cameras, and drone-as-first-responder capabilities into a unified intelligence platform. When a 911 call comes in, drones deploy first, delivering aerial and thermal imagery to officers before they arrive on scene. The system has logged more than 70 drone missions and supports thousands of incidents annually.

Equally notable is the governance model: the system activates only on verified incidents, with no blanket surveillance and full audit trails.

The Public Safety category winner was the Phoenix Police Department, recognized for its Unmanned Aerial Systems Program—a methodical, department-wide buildout that has grown from 11 pilots at launch in 2022 to a fully staffed unit in 2026.

PPD flew more than 12,500 missions in its first two years, covering everything from search warrant service and surveillance of violent offenders to crime scene documentation and major event overwatch. The program began as a collateral-duty assignment and matured into an embedded patrol capability, with 24/7 coverage launched in late 2025 and beyond-visual-line-of-sight operations planned for 2026. The department made a clear case for cost-effectiveness: fewer officers managing more complex situations more safely, with measurable reductions in overtime reliance.

Scalable innovation in practice

The finalists round out a strong field. Phoenix also entered its Real-Time Operations Centers—two precinct-based intelligence hubs established in 2023 that support patrol officers with live camera feeds, gunshot detection analysis, license plate data, and rapid criminal history checks. From January 2024 through mid-2025, the RTOCs helped recover 369 stolen vehicles, recover 191 firearms, and process more than 7,900 intelligence requests.

Mesa’s Police Department took a different angle on the AI question, applying it to the unglamorous (but consequential) work of crime classification. Mesa processes more than 66,000 incident reports annually for federal NIBRS (National Incident-Based Reporting System) compliance—work that previously required an 11-person team and still produced a chronic two-week backlog.

A proof-of-concept AI classification system processed 60,000 historical cases and achieved roughly 90% consistency with human analysts, with full audit trails on every decision. Mesa projects saving 15,000 analyst hours annually. The system also helped leadership identify an anomaly in aggravated assault data that turned out to be a reporting methodology artifact, not a real crime trend.

Midland, Texas, addressed an older but equally critical problem: the Permian Basin region’s four major public safety agencies could not reliably communicate during major incidents. The city’s transition to a P25 simulcast platform aligned Midland’s infrastructure with Odessa, Midland County, and Ector County, creating shared talkgroup templates and joint governance. The 2019 Midland-Odessa mass shooting had exposed the fragility of the region’s communications posture. The interoperable system went live in September 2025 across 4,312 total subscribers.

Finally, Cincinnati/Northern Kentucky International Airport (CVG) demonstrated that the public safety challenge is not unique to law enforcement. CVG deployed a Bluetooth-based micro-location platform across its 7,700-acre campus to address a straightforward but underserved problem: where workers and assets are in real time—without GPS dead zones and without surveillance overreach.

The result has been measurable improvements in asset visibility and lone-worker safety, with emergency alerts now reaching personnel who previously had no radio access.

What sets leaders apart

The pattern across all entries is clear: the most effective deployments paired operational rigor with clear outcome measurement. Just as importantly, the cities that built governance frameworks alongside their technology investments achieved the most durable results.

Alison Brooks - Research Vice President, Smart Cities Strategies, Public Safety - IDC

As Research Vice President for IDC's Worldwide and US Public Safety practice, Dr. Alison Brooks focuses on public safety and first responder research and advisory services, with a specialization in Smart Cities and Communities. Dr. Brooks' research provides detailed analysis on the digital transformation of public safety and first responders, covering topics such as digital evidence management, integrated physical security solutions, intelligence-led policing, advanced analytics, video surveillance and visualization, first responder communications and alternative policing frameworks. Dr. Brooks has held a number of positions with IDC over the past 15 years, previously working as IDC Canada's Director of public sector research.

Ruthbea Yesner - Program VP - IDC

Ruthbea Yesner is the Vice President of Government Insights at IDC. In this practice, Ms. Yesner manages the US Federal Government, Education, and the Worldwide Smart Cities and Communities Global practices. Ms. Yesner's research discusses the strategies and execution of relevant technologies and best practice areas, such as governance, innovation, partnerships and business models, essential for government and education transformation. Ms. Yesner's research includes analytics, artificial intelligence, Open data and data exchanges, digital twins, artificial intelligence, the Internet of Things, cloud computing, and mobile solutions in the areas of economic development and civic engagement, urban planning and administration, smart campus, transportation, and energy and infrastructure. Ms. Yesner contributes to consulting engagements to support K-12 and higher education institutions, state and local governments and IT vendors' overall Smart City market strategies.

Each year, IDC’s Smart Cities North America Awards provide a unique window into how cities are evolving—not just in ambition, but in execution. This year’s entries, finalists, and winners tell a clear and compelling story: Smart Cities are no longer conceptual. They are operational, integrated, and delivering measurable impact in communities of all sizes.

At their core, Smart Cities have always been about using technology to improve the quality of life for residents, businesses, and visitors. What stands out in 2026 is how firmly that vision has translated into action.

From experimentation to execution

One of the most striking trends across this year’s submissions is the level of operational maturity. Projects are no longer exploratory pilots or isolated proofs of concept. Instead, they are focused on execution and performance.

We saw widespread adoption of technologies that enable cities to function more effectively every day, including digital procurement and workflow automation, GIS and data integration, real-time monitoring and dashboards, and AI-enabled analytics. These capabilities are not just enhancing services—they are transforming how cities operate at a foundational level, particularly in critical systems such as public safety, fire response, and water management.

Another notable trend is the growing—but pragmatic—use of AI. Rather than being positioned as a standalone innovation, AI capabilities are embedded within broader solutions to analyze data, support decision-making, automate workflows, and improve service delivery. We saw this in projects focused on procurement automation, real-time analytics, and operational intelligence, as well as in Scottsdale’s AI-powered real-time crime center.

AI in Smart Cities is not experimental or abstract—it is being applied in targeted ways to solve specific problems and deliver measurable outcomes. This was also reflected in the many panels at the Smart Cities Connect conference, which showcased how cities are using AI in defined use cases to achieve concrete results.

This shift signals an important milestone: Smart Cities have moved beyond experimentation and into sustained, real-world delivery.

Breaking down silos: The rise of systems thinking

Another defining characteristic of the 2026 entries is the move toward integrated, multi-domain approaches. Cities are increasingly designing solutions that cut across traditional silos, embracing systems-thinking models rather than isolated implementations.

Many of this year’s projects span multiple functional areas or departments, with common combinations including public safety, infrastructure, and transportation; administration, civic engagement, and digital equity; and urban planning paired with resiliency initiatives.

This evolution reflects a growing ability to collaborate across departments and address challenges in an interconnected way, using coordinated solutions that bring together data, technology, and stakeholders. Key to this shift is the increasing influence of innovation teams, leaders, and smart city directors acting as city-wide coordinators.

Technology in service of community priorities

Across all categories, one theme was consistent: technology is being applied to clearly defined community needs.

Projects focused heavily on areas such as flood mitigation and environmental monitoring, community resiliency, accessibility and digital inclusion, and public safety innovation. Many also emphasized strong cross-sector partnerships, bringing together government agencies, private sector partners, nonprofits, and academic institutions.

This alignment between technology and community priorities reinforces a critical principle of Smart Cities: technology is not the goal—it is the enabler. The most impactful projects start with a clear understanding of local challenges and apply technology deliberately to address them.

Innovation that is scalable, agile, and inclusive

Another encouraging finding from this year’s awards is how accessible Smart City innovation has become.

A significant number of projects were delivered with relatively modest budgets, with 37 initiatives under $100,000 and only a handful exceeding $10 million. At the same time, most projects were implemented in less than two years.

This demonstrates that meaningful innovation does not require massive, multi-year capital investments. Instead, cities are embracing modular, agile approaches that allow them to move quickly, scale solutions, and deliver results.

Equally important, innovation is no longer concentrated in large metropolitan areas. This year’s submissions highlight strong participation from mid-sized cities and regional communities, underscoring that Smart City capability is widely distributed across North America.

Celebrating the 2026 finalists and winners

At the heart of the Smart Cities Awards is the recognition of the cities and partners leading this transformation.

This year’s awards highlight the breadth of innovation happening across North America. The finalists and winners exemplify what is possible when vision meets execution and demonstrate the diversity of approaches organizations are taking. A few examples include:

  • The City of Boston, advancing both digital equity and operational efficiency through initiatives such as Green Light for Education, which addresses student access and transportation challenges, and BidBot, an AI-enabled tool transforming municipal procurement.
  • The City of Pittsburgh, driving climate-focused urban planning through initiatives like Planting with Purpose, using data and partnerships to strengthen community resiliency and guide sustainable development.
  • Austin Water, modernizing infrastructure through advanced metering initiatives that improve water management, operational visibility, and customer service.
  • New Jersey Transit, enhancing resiliency and infrastructure intelligence with its Storm Surge Early Warning System, using real-time data to anticipate and respond to flooding risks.
  • The City of Phoenix, pushing innovation across multiple fronts, particularly in public safety—from its Unmanned Aerial Systems (UAS) program to broader efforts in real-time operations and community engagement.
  • The City of Scottsdale, recognized as the overall winner for its AI-powered real-time crime center and drone-as-first-responder program, highlighting the power of integrated, data-driven approaches.

Each finalist and winner represents not just a successful project, but a model for others to learn from and build upon.

Looking ahead

One of the most compelling aspects of Smart Cities is that while the definition continues to evolve, the purpose remains constant: improving communities and addressing complex urban challenges through technology.

Today’s Smart Cities are practical, multi-domain, partnership-driven, and deeply focused on outcomes. They are powered by technology, but centered on people—the practitioners, innovators, and leaders working every day to make their communities better.

As we celebrate this year’s winners and finalists, we are also recognizing a broader movement—one that is steadily transforming how cities operate and how they serve their residents.

Ruthbea Yesner - Program VP - IDC

Ruthbea Yesner is the Vice President of Government Insights at IDC. In this practice, Ms. Yesner manages the US Federal Government, Education, and the Worldwide Smart Cities and Communities Global practices. Ms. Yesner's research discusses the strategies and execution of relevant technologies and best practice areas, such as governance, innovation, partnerships and business models, essential for government and education transformation. Ms. Yesner's research includes analytics, artificial intelligence, Open data and data exchanges, digital twins, artificial intelligence, the Internet of Things, cloud computing, and mobile solutions in the areas of economic development and civic engagement, urban planning and administration, smart campus, transportation, and energy and infrastructure. Ms. Yesner contributes to consulting engagements to support K-12 and higher education institutions, state and local governments and IT vendors' overall Smart City market strategies.

Alison Brooks - Research Vice President, Smart Cities Strategies, Public Safety - IDC

As Research Vice President for IDC's Worldwide and US Public Safety practice, Dr. Alison Brooks focuses on public safety and first responder research and advisory services, with a specialization in Smart Cities and Communities. Dr. Brooks' research provides detailed analysis on the digital transformation of public safety and first responders, covering topics such as digital evidence management, integrated physical security solutions, intelligence-led policing, advanced analytics, video surveillance and visualization, first responder communications and alternative policing frameworks. Dr. Brooks has held a number of positions with IDC over the past 15 years, previously working as IDC Canada's Director of public sector research.

Over the years, smartphone makers have been “selling us” the need for better cameras, more power, longer battery life, and improved displays. In the last couple of years, the conversation began to shift toward intelligence, but very little was shown about the future of truly intelligent devices. This year in Barcelona, that story changed.

The most important announcements were not about hardware specifications, but about how devices interpret, anticipate, and act on behalf of the user. What we witnessed at Mobile World Congress 2026 was not another cycle of AI promises—it was execution. Devices are now designed with AI from the ground up and are able to interpret context, anticipate needs, and act on behalf of the user, significantly improving the user experience.

From AI as a feature to AI as the foundation

Until recently, AI in smartphones was largely an add-on layered on top of core features. It enhanced photography, powered voice assistants, or enabled isolated capabilities. At MWC 2026, AI has moved into the core architecture of the device.

Samsung provided one of the clearest demonstrations of this transition with the Galaxy S26 and the broader Galaxy AI ecosystem. The focus is no longer on responding to commands, but on enabling systems that operate with a degree of autonomy.

Samsung demonstrated systems capable of:

  • Understanding context across multiple apps – Devices such as the Samsung Galaxy S26 are beginning to interpret user intent by linking activity across applications (e.g., recognizing a travel confirmation in an email and cross-referencing it with calendar availability).
  • Aggregating personal data into actionable insights – Devices can consolidate data streams to generate meaningful recommendations (e.g., Samsung demonstrated how intelligence improves when devices work together).
  • Acting autonomously to complete tasks on behalf of users – The most advanced demos focused on autonomous execution. Samsung positioned the S26 as a device that “anticipates intent and takes action” ahead of the user.

Samsung exemplified this transition with its expansion of Galaxy AI across smartphones, PCs, tablets, and wearables, anchored around agent-based experiences that execute tasks rather than simply respond to commands. Similarly, Xiaomi’s focus on computational photography and intelligent imaging reflects how AI is redefining even mature use cases like the camera.

The industry is converging toward devices that function as orchestrators within a wider ecosystem, rather than standalone endpoints.

Intelligence extends beyond the smartphone

Another important takeaway from MWC 2026 is that this shift is not limited to smartphones.

Lenovo’s presence highlighted how AI is being embedded across PCs and emerging form factors. Concepts such as modular AI PCs, foldable gaming devices, and glasses-free 3D laptops point to a future where intelligence provides continuity across devices, adapting dynamically to user behavior.

TECNO, on the other hand, focused on accessibility. Its approach centers on bringing AI capabilities to more affordable segments while tailoring experiences to local environments. The example of noise cancellation optimized for high-noise regions is particularly relevant, as it shows how AI can be applied in a highly contextual and differentiated way.

At the silicon level, Qualcomm’s announcements confirm that this transition is being enabled from the ground up. Advances in AI-capable chipsets, combined with next-generation connectivity such as 5G Advanced and emerging Wi-Fi standards, are making on-device intelligence both scalable and efficient.

In effect, intelligence is becoming pervasive, embedded across the entire technology stack—from components to services.

New device categories signal behavioral change

Several key announcements highlighted how intelligence is reshaping device categories themselves.

Honor’s “Robot Phone” is perhaps the most relevant example. Built around a gimbal-mounted camera system, the device can physically track users, follow movement, and interact in a more human-like manner—blurring the line between smartphone and personal assistant and taking AI beyond software into hardware.

Motorola’s Razr Fold reflects another trend: premium form factors combined with productivity features such as stylus support and multitasking, targeting higher-value segments where intelligence enhances utility rather than novelty.

Meanwhile, TECNO’s modular concept introduces a different dimension of innovation. By enabling interchangeable hardware modules, it suggests a future where devices evolve over time, potentially reducing replacement cycles and aligning with sustainability pressures.

Even in the midrange, innovation is being redefined. The Nothing Phone 4(a) generated significant attention not because of raw specifications, but because of how it uses AI to extract, organize, and operationalize personal information—turning passive data into active utility.

Ecosystems are becoming the new battleground

A strong theme at MWC 2026 is the shift from devices to ecosystems. Xiaomi’s broad portfolio illustrates a strategy focused on scale and integration. The device is no longer the product; it is the entry point into a connected environment.

This was echoed across vendors. Samsung is extending AI across its entire Galaxy portfolio. Lenovo is aligning PCs and peripherals into unified AI systems. Telecom operators are introducing AI-driven services such as real-time call assistance.

Competition is no longer defined solely by device specifications. It is increasingly about how effectively companies connect devices, data, and services into a seamless experience.

A market under pressure: The memory constraint

Despite the optimism around AI execution, a structural risk dominated executive conversations: the emerging memory shortage.

From an IDC perspective, this is not a marginal issue. The industry is entering a period where demand for AI-capable devices is rising, but supply-side pressures are intensifying. IDC expects global smartphone shipments to decline by approximately 13% in 2026, with PC shipments projected to contract by around 11%. This reflects a combination of macroeconomic softness and component constraints, including memory availability and cost volatility.

This introduces a paradox. Just as demand for AI-capable devices accelerates, the industry faces constraints that could limit supply and compress margins. The result is likely to be increased cost pressure, tighter margins, and more selective innovation cycles.

What this means for the industry

MWC 2026 will likely be remembered as a turning point where AI moved from narrative to reality.

First, differentiation is shifting from hardware to intelligence. Performance still matters, but experience is becoming the primary driver of value.

Second, the center of gravity is moving from standalone devices to ecosystems. The winners will be those who can orchestrate seamless interactions across multiple devices and services.

Third, interaction models are evolving from user-driven to agent-driven. Devices are beginning to take initiative, reducing friction and redefining how users engage with technology.

For vendors, competing on hardware alone is no longer sufficient. The ability to integrate intelligence deeply across software, services, and ecosystems will define the next phase of the market.

The industry has spent years talking about AI. In Barcelona this year, it finally started delivering.

Francisco Jeronimo - Vice President, Data & Analytics - Devices - IDC

Francisco Jeronimo is VP for Data and Analytics at IDC EMEA. Based in London, he leads the research that covers mobile devices, personal computing devices, emerging technologies and the circular economy trends across EMEA. His team delivers data on personal computers, tablets, smartphones, wearables, PC monitors, PC gaming, enterprise Thin Client devices, smart home, augmented reality and virtual reality, and sales of used devices. He provides in-depth analysis of the strategies and performance of the key industry players.

Agentic AI is moving from experimentation toward enterprise orchestration. Early deployments emphasized efficiency. As systems scale, the more significant shift lies in how enterprises redesign value creation, capture, and long-term advantage.

IDC’s FutureScape 2026 predictions identifies this transition as one of four strategic imperatives shaping the agentic future. Unlocking innovation beyond productivity defines how organizations translate AI maturity into new business models, revenue streams, and sustained competitive position.

Innovation beyond productivity refers to the structural redesign of business models, industry boundaries, and economic logic enabled by agentic AI operating across enterprise portfolios and ecosystems. It reflects how organizations convert AI maturity into scalable growth, differentiated customer value, and durable competitive advantage.

This is the focus of Pillar 4 within FutureScape 2026.

The productivity plateau

The first wave of AI delivered measurable gains. Contact centers reduced handle times. Back-office operations automated repetitive tasks. Sales and marketing teams improved throughput. These gains were important because they made AI investment tangible.

However, efficiency advantages diffuse quickly. What creates competitive differentiation in one quarter becomes standard capability the next. Productivity improvements, when layered onto existing operating models, eventually reach saturation.

Productivity-first strategies constrain long-term impact in three ways:

  1. They reinforce functional silos. AI is deployed by department, and each team optimizes local objectives.
  2. They lock in current assumptions. Optimization strengthens workflows designed for earlier market conditions.
  3. They produce linear gains. Efficiency improvements reach saturation when underlying structures remain unchanged.

The constraint is not AI capability. The constraint is operating design. When AI is layered onto legacy structures without structural redesign, outcomes remain incremental.

Innovation as the structural payoff of agentic AI

Innovation occurs when AI reshapes enterprise structure rather than simply accelerating task execution. Agentic AI enables coordinated decision-making across marketing, supply chain, finance, service, and ecosystem partners. Systems move from isolated automation toward orchestration embedded in enterprise operating models.

Innovation beyond productivity highlights three requirements for structural innovation in the agentic era:

  • Redefined industry boundaries. Agentic AI facilitates collaboration between domains that previously operated independently, reshaping competitive landscapes.
  • New economic logic. When agents operate autonomously at scale, assumptions about capacity, cost, and output change. Business cases designed for linear improvement do not capture compounding value created through coordination.
  • Governance as infrastructure. Governance must support cross-domain orchestration while embedding accountability into operating design.

Where value models are being rebuilt

FutureScape research identifies structural pressure points where value creation is already evolving. These signals reflect changes in pricing structures, industry organization, and coordinated delivery models.

Pricing model evolution
Traditional pricing frameworks were built around human labor and seat-based licensing. As agent interactions increase, value shifts from access to measurable outcomes. Enterprises and providers are redesigning pricing logic to reflect agent-mediated execution and results. This indicates a change in value capture, not simply a change in delivery.

Life sciences reinvention
Agentic AI is transforming pharmaceutical research and development. By 2030, 80 percent of pharmaceutical companies are projected to partner with TechBios, leveraging agentic AI and quantum computing to reduce R&D costs and failure rates. This signals new industry architectures built on coordinated discovery and ecosystem collaboration.

Healthcare system coordination
Healthcare has traditionally operated through linear care pathways. Agentic AI enables continuous orchestration across diagnosis, treatment, monitoring, and escalation. By 2030, one in three top-tier hospitals is expected to deploy AI agents delivering real-time decision support and autonomous workflows with high levels of accuracy. Clinical value becomes embedded in system coordination rather than isolated interventions.

Consumer ecosystem realignment
Immersive digital environments and gaming platforms are evolving into coordinated ecosystems for engagement and commerce. By 2026, two-thirds of Gen Z and Gen Alpha are projected to spend more time gaming than on social media. This signals movement toward platforms designed for persistent interaction and orchestrated value creation.

Rethinking AI ROI

As AI becomes integral to enterprise operating logic, traditional ROI metrics require reassessment. Leaders must reconsider three assumptions:

  • Short-term cost savings do not define strategic value.
  • Pilot programs do not create durable advantage without integration.
  • Model accuracy does not guarantee enterprise impact if objectives remain unchanged.

Legacy metrics focus on time saved and expenses reduced. Structural innovation requires evaluation of adaptability, cross-functional coordination, and long-term growth potential.

This shift aligns AI outcomes with enterprise design and economic logic, not isolated task performance.

Innovation as portfolio and ecosystem strategy

Agentic AI generates the greatest impact when managed as a coordinated portfolio rather than discrete initiatives. Each deployment should strengthen enterprise adaptability, improve cross-functional coordination, and expand future strategic options.

Unified governance frameworks support this model by embedding oversight into operating systems and enabling autonomous action within defined boundaries.

As agents operate across organizational and ecosystem boundaries, value creation becomes interdependent. Competitive advantage becomes systemic and embedded within enterprise design.

Defining the next horizon

Productivity remains necessary. Structural innovation determines sustained advantage.

The transition highlights a pivotal transition within the agentic journey. Agentic AI is redefining economic models, industry boundaries, and enterprise architecture. Organizations that redesign for orchestration, portfolio coordination, and ecosystem alignment position themselves for long-term growth in the AI-fueled economy.

Explore innovation beyond productivity in depth

FutureScape 2026 includes detailed research, analyst perspectives, and events that expand on the innovation beyond productivity theme.

Core Research

Analyst perspectives

On-demand webinars

IDC - -

International Data Corporation (IDC) is the premier global market intelligence, data, and events provider for the information technology, telecommunications, and consumer technology markets. With more than 1,300 analysts worldwide, IDC offers global, regional, and local expertise on technology and industry opportunities and trends in over 110 countries. IDC’s analysis and insight help IT professionals, business executives, and the investment community make fact-based technology decisions and achieve their key business objectives.

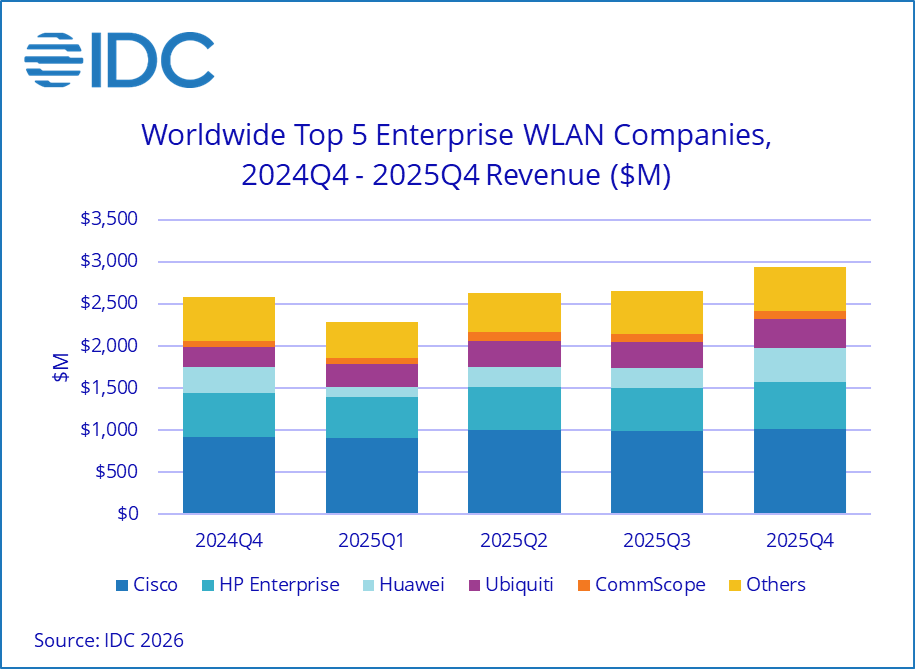
In the fourth quarter of 2025 (4Q25), the worldwide enterprise WLAN market reached $2.9B, growing 13.9% year over year. The primary driver was the rapid adoption of Wi-Fi 7, which accounted for 39.7% of dependent access point segment revenue, up from 10.25% a year earlier. For full-year 2025, the market totaled $10.5B, with 11.4% annual growth, reflecting ongoing demand for advanced wireless standards.

Why enterprise WLAN matters in the AI era

In the AI era, connectivity is no longer just infrastructure—it is a strategic foundation for digital business. Enterprise WLAN plays a critical role in delivering secure, reliable, and high-performance connectivity across enterprise campuses, branches, and edge environments. At the same time, AI-driven applications, video traffic, and the rapid growth of IoT devices are placing unprecedented demands on network capacity, latency, and efficiency, pushing organizations to rethink and modernize their wireless networks.

IDC’s 4Q25 WLAN Tracker highlights a clear inflection point: 60% of global enterprise WLAN spending is now directed toward Wi-Fi 6E and Wi-Fi 7. This shift reflects a move from early adoption to mainstream deployment, as enterprises invest in next-generation WLAN technologies to support higher performance requirements and enable emerging AI-driven and distributed business models.

Market dynamics: WiFi 7 and AI drive upgrades

The enterprise WLAN market is being shaped by continued innovation, evolving architectures, and the growing influence of AI. The expansion of 6GHz spectrum with Wi-Fi 6E and the accelerating adoption of Wi-Fi 7 are driving a new wave of upgrades.

At the same time, AI is improving how WLANs are designed and operated through greater automation and optimization, while enterprises adopt platform-based approaches that integrate WLAN with broader networking, security, and observability tools. Combined, these trends are driving strong growth in the enterprise WLAN market, both in 4Q25 and for full-year 2025.

From a geographic perspective, in 4Q25, the Americas saw a 13.9% year-over-year increase, while Europe, the Middle East & Africa experienced robust growth of 25.2% YoY. In contrast, the Asia Pacific region saw a slight revenue decline of 0.9% YoY, highlighting regional disparities in technology adoption and investment priorities.

Vendor performance: Cisco leads as growth accelerates

Cisco maintained its leadership in the enterprise WLAN market, with revenue rising 10.8% year over year to $1.0B and a market share of 34.6% in 4Q25. For the full year, Cisco’s revenue increased 4.9% to $3.9B, giving the company a market share of 37.2% at year-end.

HPE, now including Juniper following its July 2025 acquisition, grew 4.7% YoY to $552.8M, capturing 18.8% of the market in 4Q25. For the full year, HPE’s revenue increased 7.6% to $2.0B, giving the company a market share of 19.7% at year-end.

Ubiquiti saw the highest growth among major vendors, increasing 49.0% YoY to $344.5M and holding 11.7% market share in 4Q25. For the full year, the company’s revenue grew 53.1% to $1.2B, maintaining an 11.7% share in 2025.

Huawei posted strong growth, up 32.1% YoY to $409.8M, with a 14.0% share in 4Q25. For the full year, revenue rose 18.4% to $1.0B, giving the company a 9.6% share.

CommScope (Ruckus Networks) grew 13.4% YoY to $88.8M, representing 3.0% of the market in 4Q25. For the full year, revenue rose 26.0%, giving the company a 3.4% share.

Outlook: Wi-Fi 7 momentum and AI-driven networks

IDC expects continued momentum in enterprise WLAN upgrades as organizations pursue higher performance, greater automation, and tighter integration with AI-driven and distributed workloads. Wi-Fi 7 adoption is likely to accelerate further—alongside increased deployment of tri-band APs—particularly in regions with strong digital transformation initiatives.

Growth will also be supported by rising adoption of AI-driven network operations, platform-based networking approaches, and cloud-managed architectures, as enterprises seek more scalable and flexible environments. At the same time, evolving security requirements, including zero trust frameworks, will remain a key driver, while supply chain constraints or macroeconomic headwinds may temper growth in certain regions. Watch for continued innovation in AI capabilities, architectural models, and vendor strategies in the coming quarters.

For deeper analysis and IDC research on enterprise WLAN trends, visit IDC’s Worldwide Quarterly WLAN Tracker or contact IDC for the latest market insights.

Brandon Butler - Sr. Research Manager - IDC

Brandon Butler is a Senior Research Manager with IDC's Network Infrastructure group covering Enterprise Networks. His research focuses on market and technology trends, forecasts and competitive analysis in enterprise campus and branch networks. His coverage includes technologies used in local and wide area networking such as Ethernet switching, routing/SD-WAN, wireless LAN, and enterprise network management platforms. While contributing to ongoing forecast and market share updates, he also assists in end-user surveys, interviews and advisory services and contributes to custom projects for IDC's Consulting and Go-To-Market Services practices.

Petr Jirovsky - Senior Research Director, Network Infrastructure and Services - IDC

Petr Jirovsky is a Senior Research Director within IDC's Enterprise Infrastructure global research domain. He provides quantitative insights on network infrastructure for the datacenter, cloud, and campus/branch environments as part of the Network Infrastructure and Services subdomain. Petr serves as the global lead for IDC's Network Infrastructure Trackers, which track Ethernet switches, routers, wireless equipment, and application delivery appliances and services. He also contributes to numerous custom data projects and supports the publication of market share and forecast documents for the subdomain.

Diego Anesini - VP D&A, LatAm & Director Enterprise and Telecom - IDC

Diego Anesini serves as Research Vice-President, Data & Analytics for IDC Latin America, overseeing all the Information and Communications Technologies. Prior to this position, Diego held various roles in the company. The most recent was Enterprise Infrastructure and Telecom Director for Latin America. He has extensive experience in the Telecom and IT markets, due to his more than 25 years in the industry.

在刚刚落幕的英伟达GTC大会和阿里巴巴组织架构调整的双重催化下,“AI Token预算”已从科技圈的前沿话题,迅速演变为企业管理层案头的必答题。随着AI智能体(Agent)开始替代传统软件执行复杂任务,Token不再仅仅是技术计价单位,而是企业参与未来竞争的“数字石油”。

IDC最新研究显示,2025年中国AI相关IT支出预计将达到约380亿美元,并将在2027年前保持超过25%的年复合增长率,其中生成式AI推理相关支出占比快速提升,成为企业数字化投资中增长最快的子项之一。这一趋势表明,Token作为AI消费的核心计量单位,正在从“技术指标”转变为“财务指标”。

对于中国市场而言,凭借独特的成本优势与政策红利,为企业设立独立的Token预算科目,已不仅是财务精细化的需求,更是一场抢占“AI定价权”的战略博弈。

指数级消耗倒逼财务变革:Token是新型“生产力采购”

过去一年,全球日均Token消耗量增长近300倍,IDC中国追踪的企业级Token年度总消耗量过去一年也增长了近20倍,这一数字背后是AI从“辅助工具”向“生产力主体”的身份转变。

IDC调研进一步指出,已有超过60%的中国头部企业开始将生成式AI纳入核心业务流程(如研发、客服、营销自动化),其中超过30%的企业已经出现“AI调用成本不可控”的问题,这正是Token预算缺失的直接表现。

对企业而言,忽视Token预算的风险正在显现。一方面,若沿用传统的软件订阅制预算逻辑,企业将面临难以预测的“成本黑洞”——例如,一个重度使用的工程师,其年度AI推理支出可能突破10万美元,占其总人力成本的20%以上;另一方面,缺乏独立核算将导致投入产出比失真,无法精准衡量“每一美元Token究竟换来了多少业务价值”。

因此,将Token支出从“软件采购”剥离,升级为与人力、供应链同等重要的“核心生产资源”进行独立核算,已成为企业财务管理的必然选择。这标志着企业采购逻辑的转变:从购买“软件工具”转向购买“生产力服务”。

中国市场的“弯道超车”:性价比即竞争力

对于中国公司而言,制定Token预算具有特殊的地缘战略意义。当前,中国AI大模型市场正凭借极致的性价比在全球竞争中抢占先机。

IDC数据显示,中国大模型市场呈现出“高性价比+高调用量”的双重特征:2025年中国生成式AI模型调用量预计将占全球约35%以上,且增长速度显著高于北美市场。

得益于“东数西算”工程带来的绿电成本优势(西部数据中心电价仅为欧美的1/3至1/5),国产模型在Token单价上展现出碾压性优势。目前,中国主流大模型的Token单价仅为国外竞品(如Gemini)的1/6至1/10。

这种成本红利直接转化为市场数据:2026年初,中国大模型的周调用量已在全球主要API聚合平台上历史性地反超美国市场。

这意味着,中国公司若能充分利用本土模型的“价格洼地”,其Token预算的每一分钱都将具备更高的购买力。这不仅是降本增效的手段,更是中国企业在全球AI应用层竞争中实现“弯道超车”的关键窗口。

未来竞争的关键,不只是“谁用AI”,而是“谁用更低成本的Token创造更高密度的业务价值”。

如何编制你的Token预算?分层配置与动态调整

面对Token经济的浪潮,企业应如何着手准备预算?结合行业实践,建议从以下三个维度入手:

1. 分层设置消耗配额:

  • 基础层:保障高频、轻量级应用(如内部知识库、客服机器人),预算编制可参考历史消耗量,并叠加行业年均降价预期(预计年降本约30%)。
  • 战略层:预留高价值场景预算(如视频生成、AI自主编程、智能体编排),并将预算额度与具体的业务增长目标挂钩,确保高投入带来高回报。

2. 响应国家“算力通胀”治理:

国家数据局已将“降低社会算力总成本”列为重点任务。

IDC预计,到2027年,中国数据中心算力规模将增长超过2倍,其中AI算力占比将超过40%。在此背景下,Token成本管理将成为企业参与“算力资源配置”的关键能力。

企业设立独立的Token预算科目,不仅便于合规申报深圳等地推出的“算力券”补贴,也有助于满足ESG(环境、社会和公司治理)披露要求,如追踪单位Token的碳足迹。

3. 配置弹性对冲机制:

鉴于Token成本受地缘政治(如算力出口限制)和电力波动影响显著,建议企业在总预算中配置约20%的弹性空间,以应对不确定性。

IDC建议

IDC中国研究总监卢言霞表示,正如工业时代的企业必须预算电力成本,AI时代的企业必须学会预算Token成本。阿里巴巴成立“Token Hub”事业群、英伟达高呼“推理拐点已至”,这将提醒所有企业:Token不仅是成本,更是未来企业竞争力的量化指标。

IDC认为,未来3年内,是否具备“Token精细化管理能力”,将成为企业AI成熟度的重要分水岭。领先企业将呈现出三大特征:

  1. 将Token纳入核心财务指标体系
  2. 建立跨部门的AI成本治理机制(财务+IT+业务)
  3. 实现Token消耗与业务价值的实时映射

每个公司都应该现在就开始思考:你的年度预算表里,准备好“Token”这一项了吗?

关于Token预算、AI投入或相关实践,如果您有更多思考或问题,欢迎与我们交流。IDC也将持续分享最新研究与市场洞察,与您一起探索AI时代的增长机会。

如需进一步了解与研究相关内容或咨询 IDC其他相关研究,请点击此处与我们联系。
生成式AI和智能体的快速普及,正在改变网络安全的攻防模式。企业不仅要利用AI提升安全能力,也必须应对AI带来的新型风险。

近期,中国类OpenClaw应用快速发展,市场上出现了许多不同的龙虾智能体,如火山引擎的的ArkClaw、腾讯的QClaw等。阿里巴巴近日也发布了企业级Agent平台 “悟空” 。大模型、智能体的快速发展为千行百业带来众多机遇,网络安全产业也不例外。

一方面,AI正在赋能安全检测、漏洞分析和自动化修复,大幅提升安全运营效率;另一方面,AI应用本身也正在成为新的攻击入口。IDC在《IDC Link:中国网络安全技术前瞻,2026Q1》中指出,当前网络安全技术的发展正呈现出明显的 “All in AI”趋势。

以下是IDC观察到的七个关键技术趋势。

趋势一:安全智能体有望替代部分传统安全产品,成为安全团队“协作者”和“运营者”

2026年2月,Anthropic发布 Claude Code Security。这款安全智能体能够通过语义理解分析代码逻辑,并在真实环境中发现 500多个此前未被识别的高危漏洞。事实上,Google和OpenAI早在2025年就推出了类似的安全研究智能体,并将其应用于漏洞识别、代码审计和漏洞验证等场景。

与传统SAST、DAST或SCA工具相比,代码安全智能体在以下方面具有明显优势:

  • 更强的上下文理解能力
  • 更复杂的场景识别能力
  • 自动化修复能力

IDC认为,在任务重复度较高、难度较低的安全场景,智能体会快速落地,并替代掉部分安全工具和产品。但短期来看,AI并不会取代安全专家。当前主流安全智能体仍然保留 人工审批机制(Human in loop),因为在风险决策、责任归属和异常处理方面,人类仍然是关键环节。

趋势二:AI智能体应用正在成为新的攻击入口

OpenClaw龙虾爆火全球,其具备长期记忆能力,在本地运行,可以主动通过用户偏好的现有消息应用向用户发送消息并在后台持续运行,受到了全球用户的广泛关注并引发安装潮。但这类能力与高度自主性息息相关,意味着助手在实现目标时可能表现出异常强大的资源整合能力,这既带来了益处,也会大幅扩大威胁暴露面,“裸奔”的小龙虾会造成巨大的安全风险,给个人、企业带来难以挽回的巨大损失。

具体来说,OpenClaw存在如公网暴露+弱认证、Skill供应链风险、Agent权限失控风险、提示注入风险、敏感信息明文存储风险等。国家信息安全漏洞库(CNNVD)发布通报,2026年1月到3月9日,共采集到82个OpenClaw漏洞,存在极大的安全隐患。

为此 IDC 建议:禁用公网直接暴露,改用 127.0.0.1 并加密远程访问;最小化权限,关闭高危命令并启用二次确认;加密敏感数据,杜绝明文存密;仅安装官方可信插件;定期自查安全配置,及时整改风险。IDC《全球CIO议程2026年预测——中国启示》报告预测,到2030年,中国500强企业中15%的组织将因对AI智能体的管控与治理不足,引发高关注度的运营中断,进而面临诉讼、高额罚款及CIO被解雇的情况。企业管理者亟需构建一套智能体安全和治理体系来帮助企业安全地用好智能体,规避安全风险。

趋势三:非人类身份管理将成为现代身份管理体系的核心

在AI和自动化环境中,企业身份体系正在发生变化。除了员工身份外,越来越多 非人类身份 正在出现,如AI智能体、API密钥、服务账号等,这些身份推动企业自动化运行,但同时也扩大了攻击面。

IDC观察到,非人类身份管理平台(NHIM) 正成为企业安全架构的重要组成部分,非人类身份管理平台(NHIM)可为多云和代码环境中的机器身份提供基于AI驱动的自动化生命周期管理,具体能力如下:

  • 非人类身份的自动发现和分类
  • 最小权限管理
  • 动态密钥轮换
  • 身份归属管理
  • 态势监控与管理

IDC认为,通过整合这些功能,NHIM平台可实现一致的治理和安全性,使身份管理实践与零信任框架保持一致。未来,非人类身份管理将弥补IAM体系中的关键缺口,通过主动安全控制措施增强企业机器身份管理能力,降低机器身份相关事件发生的概率。

趋势四:AI-ready data成为AI安全的关键基础设施

在推进AI项目时,企业往往面临一个核心挑战:如何在推动AI应用落地的同时保护敏感数据。

IDC提出 AI-ready data 概念,即经过整理、清洗、脱敏和合规化处理的数据。

构建AI-ready data通常需要:

  • 用于AI训练推理的数据识别和分级分类治理
  • 跨场景统一安全策略
  • 细粒度访问控制

IDC认为,AI-ready数据既能保障数据安全与数据质量,消除 AI 项目推进的关键障碍,又能通过分层安全机制降低数据泄露与合规风险,为企业安全、高效、规模化落地 AI 应用提供稳定可靠的数据基础。

趋势五:PCC技术将推动企业数字化架构向更高的安全性、灵活性和智能化演进

当前许多企业在落地大模型应用时面临一个典型困境,即自建大模型成本过高,但使用公有云模型又担心数据隐私。PCC(Private Cloud Compute)私密云计算 正成为解决这一问题的重要技术路径。

PCC通过 端到端加密和硬件级安全隔离 构建 “数据可访问但不可见” 的运行环境,使企业能够在云端运行AI模型的同时保护核心数据。其既保留了云计算能力对复杂大模型任务的支持能力,又避免了传统公有云数据流的泄漏风险。

IDC认为,PCC可让企业在安全使用云端大模型能力的同时保护自身数据隐私,加速 AI 从试点探索走向规模化落地,并推动数据治理从静态合规评估转向动态隐私保护,实现大模型全生命周期安全管控。同时,PCC 能够拓展 AI 应用场景、提升用户信任,助力企业以轻资产模式快速部署合规的云 AI 服务。

趋势六:Deepfake防护需求快速增长

生成式AI正在让身份欺诈变得更加复杂。攻击者可以利用AI生成:深度伪造视频、合成身份以及自动化攻击脚本,这些攻击可能导致账户接管、财务损失和声誉风险。

为应对这一挑战,基于 AI 的生物识别和活体检测的多层身份验证技术正在成为关键防护手段,其主要功能包括:

  • AI生物识别
  • 活体检测
  • 分层身份认证

这些技术可以通过SDK或API集成到业务系统中,在提升安全性的同时保持用户体验。

IDC认为,多层身份验证技术可以帮助企业获得针对高级身份欺诈的认证保护,降低财务与声誉风险,满足全球合规标准,同时以快速无密码验证的方式提升用户体验与转化率,通过自动化降低运营成本,构建安全、合规且无摩擦的身份生态系统,为企业抵御不断演变的威胁提供未来保障。

趋势七:智能防偷拍技术补充了传统数据防泄漏技术在应对手机偷拍场景下的防护不足问题

传统DLP系统在防止文件外泄方面效果明显,但在手机偷拍场景中存在明显不足。例如2025年台积电数据泄露事件中,攻击者通过手机拍摄终端屏幕获取核心技术信息,并将相关信息外泄给竞争对手,造成了巨大损失。

智能防偷拍技术结合端侧AI能力和业务场景化设计,能够识别并阻断各类偷拍风险,通过终端侧AI模型,这类技术在不依赖特定手机型号的背景下可以:

  • 识别偷拍摄像头
  • 检测偷拍行为
  • 实时报警和阻断

IDC认为,随着AI技术的发展以及手机算力性能的不断提升,智能防偷拍技术将不断演进,在准确性、性能上不断提升,并进一步得到广泛应用。

IDC建议:以AI应对AI,构建面向未来的安全能力


IDC建议,企业应充分认识到AI正在重塑网络安全产业,并据此调整安全策略与技术路径。
一方面,随着众多安全智能体的出现,企业应逐步引入并应用安全智能体能力,对传统安全工具和产品进行AI化升级,在提升检测与防护能力的同时,优化安全软件体系与产品组合。


另一方面,随着OpenClaw等AI智能体应用的快速发展,AI自身的安全防护正成为全新的网络安全攻防战场。企业在延续传统网络安全手段的基础上,应重点关注AI应用带来的新型风险,并加强相关安全防护能力建设。


在此背景下,IDC建议企业逐步构建“以模治模”的安全防护体系,利用AI技术对抗AI驱动的攻击,通过AI赋能安全检测与防护能力,形成适应AI时代的网络安全产品与技术体系,从而更有效地保护用户在AI环境下的网络安全。

IDC更多相关研究

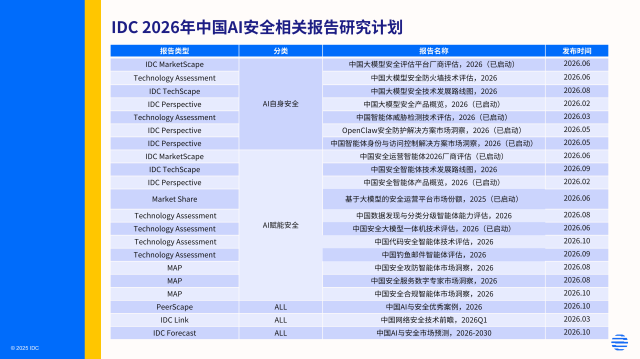
IDC已于2026年启动AI安全技术系列研究,围绕AI原生安全架构、安全智能体成熟度评估、AI驱动DevSecOps实践路径及企业级AI治理框架展开深入分析。

如需进一步了解与研究相关内容或咨询 IDC其他相关研究,请点击此处与我们联系。
Sophia Wang - Research Manager - IDC

Sophia Wang is a Research Manager in IDC China. She is responsible for the analysis and research of China's cybersecurity market. Her primary focus is on China's cybersecurity appliance and services market and operational technology (OT) security market. Additionally, she provides related research and consulting services for regional and global IT customers and supports their business development. Prior to joining IDC, Sophia worked in several consulting companies. She was independently responsible for consulting projects in fast-moving consumer goods (FMCG), internet, and other industries. Through market analysis and benchmarking analysis, she helped many clients solve problems in the different stages of their development. Sophia graduated from the University of Southern California with a master's degree in econometrics. She also majored in human resource management and journalism for her bachelor's degree.

随着生成式AI、大模型及Agent能力持续演进,围绕“AI是否会取代SaaS”的讨论正在快速升温。基于当前企业采用进度、软件支出变化、AI规模化落地情况以及企业工作方式转型趋势的综合观察,IDC的判断是:AI不会在中短期内取代SaaS,但将推动SaaS进入新一轮结构性重构周期。 企业软件市场未来的主要变化,不是SaaS的消失,而是SaaS从“功能交付工具”向“智能执行平台”演进。

当前,AI与SaaS之间并非替代关系,而更接近于“能力叠加”与“价值重定义”关系。随着企业客户从模型试点走向业务落地,从当前市场需求变化看,企业对软件平台的要求,正在从基础数字化和AI集成能力,进一步延伸至以AI Agent为代表的智能能力,包括任务执行、流程协同、系统连接、治理承接及业务结果支撑。

在明确 AI 与 SaaS 并非替代、而是能力叠加的核心关系后,我们可以从企业预算与市场结构的维度,进一步拆解这一演进趋势的现实表现 ——AI 技术的渗透并未削弱软件市场的基本盘,反而在重构企业对软件价值的判断标准与采购逻辑。

观点一:AI预算快速增长,但软件支出并未被替代

IDC数据显示,2025年全球生成式AI支出将达到 1843亿美元,同比增长151.6%。与此同时, 2025年全球IT总支出将达到 6.8万亿美元,其中软件支出将达到1.3万亿美元,同比增长 14.2%。这表明,AI投资扩张并未系统性挤压企业软件预算,反而正在推动企业重新定义软件的能力边界。

从市场结构看,企业并没有因为AI出现而停止采购软件,而是在加速采购“具备AI能力的软件”。这意味着,SaaS的需求基础并未减弱,但产品标准正在提升。未来,缺乏智能能力、缺乏AI与业务流程融合能力以及缺乏数据壁垒的传统SaaS产品,竞争压力将加大;而能够承接AI任务并支撑流程执行的平台型软件,战略重要性将持续提升。

观点二:AI采用率提升很快,但规模化价值兑现仍处于早期阶段

IDC的数据显示,2025年,亚太地区企业平均每年开展17.9个生成式AI概念验证(PoC)项目,PoC转入生产环境的比例为34.5%,也就是说,每10个PoC项目中约有3至4个最终进入生产阶段。在KPI达成率方面,亚太地区平均为36.8%,意味着进入生产环境的GenAI服务中,约37%能够实现预期业务目标。这些最新数据表明,企业对AI试点的热情依然高涨,但从PoC走向规模化生产的转化率,以及业务成效的实际达成率,仍有较大提升空间。

这表明,AI要从“具备生成与回答能力”进一步走向“具备执行能力、可审计性、可复制性和规模化应用能力”,仍需经过持续的场景验证与业务实践。仅依靠AI模型本身,尚不足以形成完整的企业级价值闭环,企业仍需要由业务系统与平台能力持续提供数据访问、权限控制、复杂流程编排、主数据管理及合规治理等关键支撑能力。也正因为如此,SaaS在AI时代并不会被削弱,反而将在任务执行、流程承接与治理支撑等方面承担更加重要的角色。

观点三:AI正在改变企业应用软件的交互方式与价值交付逻辑

传统SaaS的核心价值,在于以模块化、标准化的方式承载企业流程,并通过菜单、表单、权限和审批机制推动业务数字化落地。但随着生成式AI和AI Agent能力不断渗透,企业软件的交互逻辑正在发生明显变化:从过去的 “用户操作功能” , 逐步转向 “用户提出需求、系统理解意图并执行任务” 。在这一变化过程中,软件价值的衡量标准也在同步改变。企业关注的重点,正在从功能是否齐全,转向任务完成效率、流程自动化水平,以及对实际业务结果的支撑能力。

IDC预测,到2027年,约有50%的企业将在核心业务流程中引入AI agents,重塑人与机器之间的协作方式。这一趋势表明,AI agents正在从辅助工具逐步演变为企业工作体系的重要组成部分,而不再只是单点能力的补充。这也意味着,未来的软件平台,无论是SaaS还是企业级PaaS,都不再只是承担数据录入和流程流转的基础角色,而将进一步承担任务编排、系统集成、过程留痕和治理支撑等职责,成为AI执行任务时所依赖的业务底座。

与此同时,AI也正在重塑企业软件的交付方式与商业模式。基于用量的定价、智能体驱动的交互界面,以及基于结果的价值衡量,正在对传统的按席位订阅模式形成冲击。这种变化并不只停留在概念层面,而是已经在市场中逐步发生。

观点四:将被替代的更可能是低壁垒、浅流程的SaaS产品

从竞争格局变化看,AI对SaaS市场的影响并非均匀分布。预计首先受到冲击的,将是那些功能相对单一、流程嵌入程度有限、差异化不足,且主要依赖界面交互提供价值的轻量型SaaS产品。随着AI Agent逐步具备任务理解、流程拆解与自动执行能力,这类产品的独立价值空间可能被进一步压缩。

相比之下,深度嵌入企业核心流程、掌握关键业务数据、具备权限控制与合规支撑能力,并拥有行业知识积累的平台型软件,在AI时代更可能提升其战略重要性。这类平台不仅更有条件承接AI Agent的任务执行与流程协同,也更有可能在未来企业软件架构与采购体系中占据核心位置。

IDC中国企业级应用软件市场高级研究经理徐文婷认为,未来2-3年,企业将不会简单以AI替代现有软件系统,而是要求软件平台具备AI原生能力,并能够支撑AI Agent在业务场景中的应用。预计市场竞争焦点将逐步从功能覆盖转向任务执行、流程自动化和业务结果支撑能力。对SaaS厂商而言,关键不在于是否面对AI技术本身,而在于能否将AI有效嵌入企业级数据、业务流程和治理框架。从当前市场发展看,AI正在重塑SaaS的产品定义,但尚未改变企业对系统平台的根本需求。随着AI Agent从试点走向生产环境,SaaS将进一步向平台化和智能化演进,并承担更多任务执行与治理支撑职能。

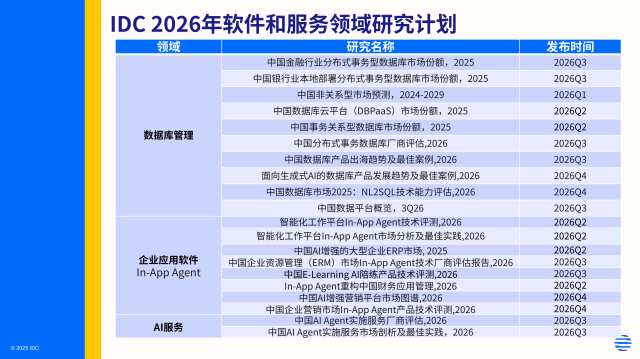
为了更好的帮助用户了解企业级软件AI的发展动态和未来趋势,IDC正式启动《中国AI-Enable ERP市场份额研究,2026》报告、《中国企业资源管理(ERM)市场AI Agent技术厂商评估报告,2026》报告研究,欢迎大家与我们保持沟通交流,与IDC共同开展更多前瞻性与实践性研究。

IDC相关研究报告:

Worldwide AI and Generative AI Spending Guide 2025

Worldwide Black Book 2025

Automation, AI, and Agentic AI for FoW: Worldwide Tech Buyer Perspective Doc#:EUR154249426

IDC Survey: Enterprise AI Trends – the Latest Survey Insights Doc#:AP53632426

IDC 2026年软件和服务领域研究计划:

如需进一步了解与研究相关内容或咨询 IDC其他相关研究,请点击此处与我们联系。
2026年中国家电及消费电子博览会(AWE2026)于3月12日至15日在上海双区同步举行,以“AI科技,慧享未来”为主题,首次采用“一展双区”模式,全面呈现AI原生产品的加速落地。主展区聚焦AI+生态,涵盖智能家电、健康个护、家庭机器人等核心品类;新设的“消费电子先进科技展区”则集中展示消费电子产业的前沿技术突破,成为全球科技首发的关键平台。本届AWE无疑是历届以来AI含量最高、场景融合最深的一届。

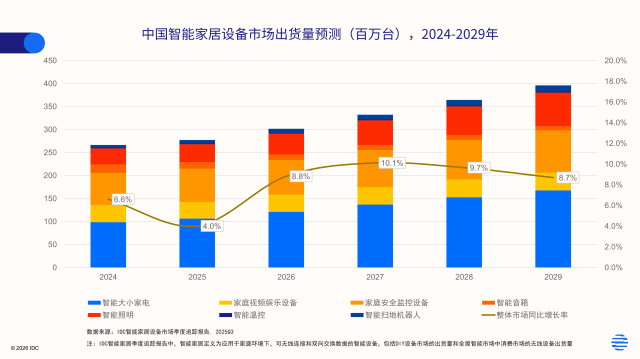
据《IDC中国智能家居市场跟踪报告预测数据,2025年第四季度》预测,2026年中国智能家居设备市场预计出货达3亿台,同比增长8.8%。其中智能扫地机器人及智能照明设备市场引领增长。

四大关键词:AI重塑家庭场景的核心逻辑

  • 主动感知:从“被动响应”走向“主动服务”

全屋智能系统突破传统语音指令局限,搭载主动感知、智能预判能力,实现多设备无缝联动协同,让家居智能从 “被动响应” 迈向 “主动服务”。

  • 适老升级:居家康养成智能设备新刚需

紧扣老龄化社会刚需,居家康养成为家庭设备升级核心方向。智能看护设备、家庭服务机器人纷纷聚焦适老化场景,成为品牌技术与服务能力的重要展示窗口。

  • 跨界融合:打通“人、车、家”多元生活场景

AWE 持续以场景化体验为核心,打通人、车、家多元生活场景,各品类家电互为生态链接枢纽,重构未来品质生活图景,打造一体化智慧生活新愿景。

AI原生落地:从技术概念到生活实景

创新科技展区成为 AI 技术家庭落地的实践窗口,头部品牌将大模型、深度学习、感知交互等核心技术深度融入产品,AI 原生手机、AI 眼镜、AI 会议耳机等前沿终端悉数亮相,推动 AI 原生时代全面到来。AI Agent能力成为决胜厂商竞争力的关键。

五大市场洞察:从功能叠加到系统智能的跃迁

  1. 未来厨房加速演进,数据能力成厂商新护城河

未来厨房概念在本届AWE吸引关注。当前新设备整合油烟、燃气、温湿度、视觉、用户行为、菜谱等多类型数据,形成统一场景决策,同时需要基于烹饪习惯、设备使用数据,提供精准菜谱、场景模式与主动服务。从网络接入看,需采用本地边缘计算与云端协同架构,支持 Wi‑Fi 6/7、Thread 等多模连接,满足低时延、高可靠与多设备并发需求。数据层面,传感器、控制及多媒体数据爆发式增长,要求边缘实时处理、本地存储与云端分析结合,兼顾数据安全与隐私合规。厂商从卖单品转向打造厨房全链路智能方案,并有机会围绕适老等热点以安全便捷为核心推出新的细分赛道爆品。

  • 情感化AI崛起,陪伴式服务成差异化突破口

海尔、TCL、珞博智能、灵童机器人、宇树科技、魔法原子等集中展出陪伴式服务产品,涵盖情感陪伴机器人、家庭服务机器人等。智能家电需从指令执行转向主动关怀,聚焦适老、育儿、独居等更符合当前中国家庭的真实场景。当前,厂商可通过融合语音、表情、肢体、语气等多模态交互弱化机械感,同时依托经典 IP 或打造原生机器人 IP,构建更具辨识度、难以替代的陪伴体验。

  • 细分场景迈向品质化,清洁设备更具“人性”

用户对细分场景的需求,已不再满足于基础功能的实现,而是全面迈向品质化、精细化、个性化的高阶体验。随着居家场景不断细分与多元,消费者诉求也愈发具体、私密与专属。无论是健康护理、居家清洁、智慧厨房还是睡眠起居等垂直领域,参展企业均以高端材质、人性化设计、原生 AI 主动服务及系统化解决方案,提升场景体验的舒适度、专业性与高级感,充分彰显家居消费升级下品质优先的核心趋势。作为家居生活的核心场景之一,本届 AWE 清洁类新品更具温度与人性,从被动执行转向主动理解、贴心适配。依托 AI 大模型实现环境感知、行为预判与个性化清洁方案,搭配高温蒸汽除菌、仿生机械臂贴边、轮足跨层越障等前沿技术,让家庭清洁场景的迭代始终围绕人的真实需求展开,真正做到科技为人服务、清洁以人为本。

  • AI智能体时代:竞争从“单点”走向“系统”

在家庭场景中,智能产品的竞争维度正加速拓宽。竞争焦点已从单一的性能参数,延伸至多智能体协同、具身智能落地、垂直场景深度适配、全链路数据与隐私保护等综合能力层面。同时,硬件自研、系统级调度与开放生态建设也成为关键竞争力。展会现场的实际案例进一步表明,行业已从早期的“单点智能”竞争,演进为以“系统智能”为核心的价值创造阶段。竞争格局日趋立体,呈现“功能叠加”向“体验整合”跃迁的明显趋势。

  • 中国厂商领跑新品类,从参与者变定义者

本届AWE有一百多家企业首次参展。全新的机器人、拍摄眼镜、感知戒指、电动滑板车、老人AI敲击呼叫器等等新品类层出不穷,国内企业已从市场参与者,升级为技术、产品与场景的定义者和引领者。在核心技术自研、产品形态创新、场景深度适配、生态协同构建等方面实现系统突破。凭借快速工程化能力、本地化场景理解与全产业链协同优势,中国品牌正不断拓展产业边界,成为全球家电与消费电子领域新质生产力的关键载体,在新品类的竞争格局中日益占据主导地位。

IDC中国高级分析师赵思泉认为,本届AWE以家电为主要切入口,实际上是消费电子企业展示AI能力的集中亮相,更是在家庭框架下对未来生活方式的一轮预演。以家电 AI 化 为核心,通过深度语义理解、用户行为自主学习及长期记忆能力,新一代智能家居系统能够持续沉淀用户操作、场景偏好与使用习惯数据,并不断迭代形成专属用户模型。在此基础上,家庭设备可突破单一指令响应模式,实现跨场景、多设备的智能协同与需求预判,提供更贴合生活节奏的个性化自动化服务,推动家电从被动执行工具升级为具备理解、学习与适配能力的智慧家庭中枢。

延伸阅读与沟通:

如需了解更多IDC相关研究或进一步与我们沟通,欢迎识别二维码与 IDC 联系,我们将安排专人与您对接,为您提供定制化的市场洞察与咨询服务。


如需了解IDC在智能终端领域的最新研究报告、数据产品及行业分析,请扫描二维码,在线获取完整研究目录与内容简介,助您精准把握市场脉动。

Claire Zhao - Senior Market Analyst - IDC

Claire Zhao is senior market analyst for Client System Research of IDC China. She is responsible for conducting research on the augmented reality (AR)/virtual reality (VR) market, and vertical analysis for the PC market. She started working for IDC China as a summer intern in 2019 as part of the Telecommunication group. Prior to joining IDC, Claire did some internships in the banking and insurance industries, and had some research experiences related to risk management, financial market, and data analytics. Claire graduated from Rensselaer Polytechnic Institute with a master’s degree in Financial Mathematics.