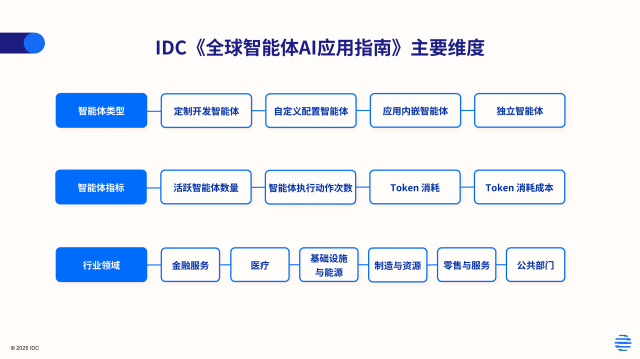
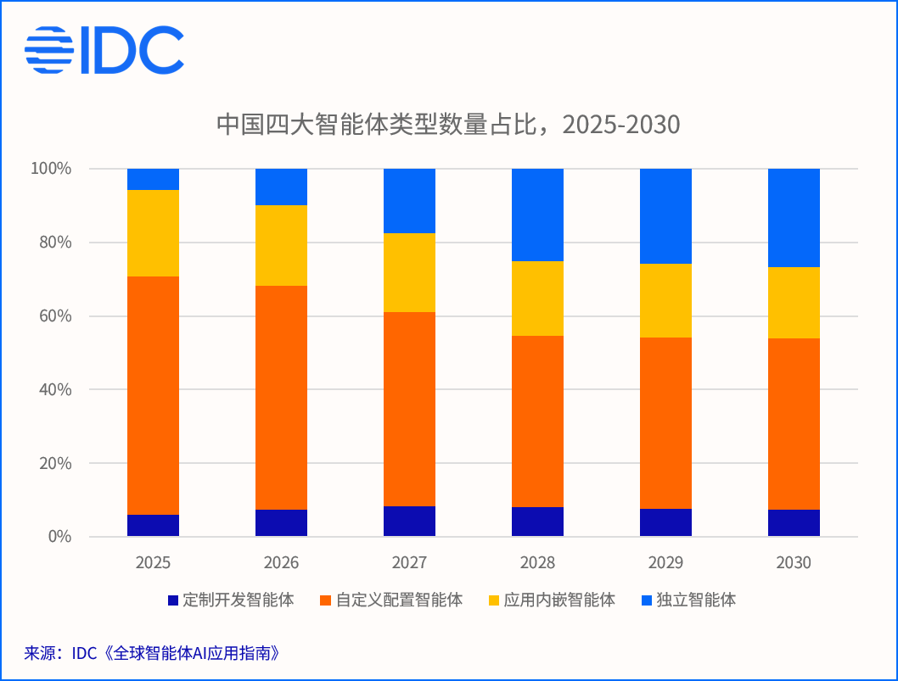
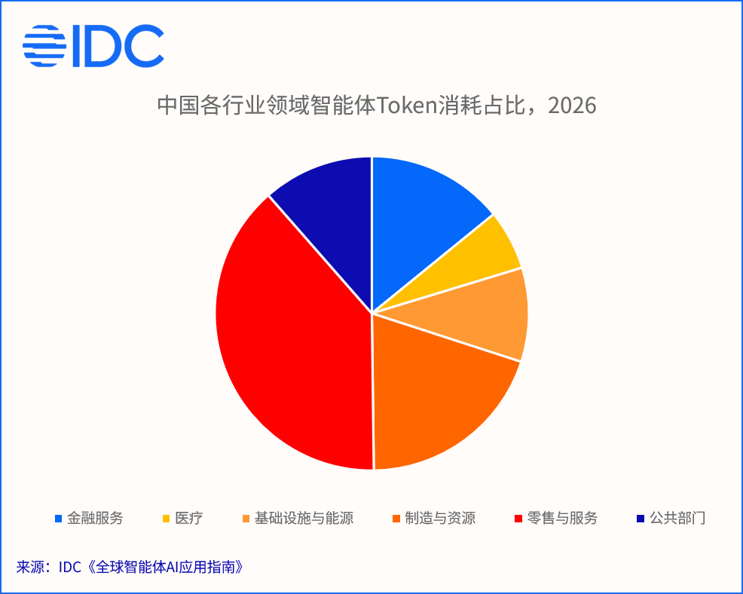
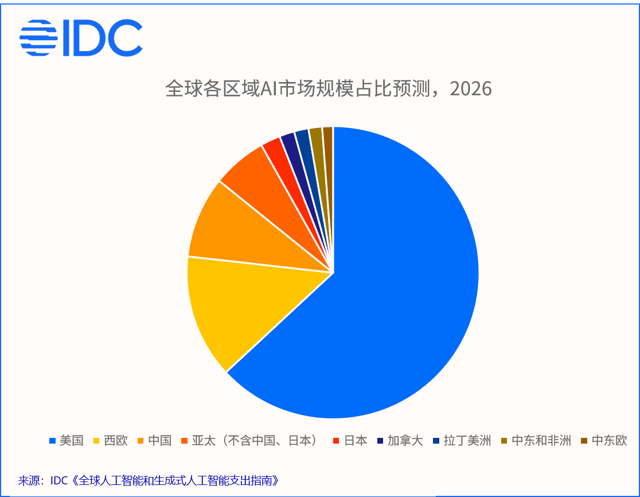
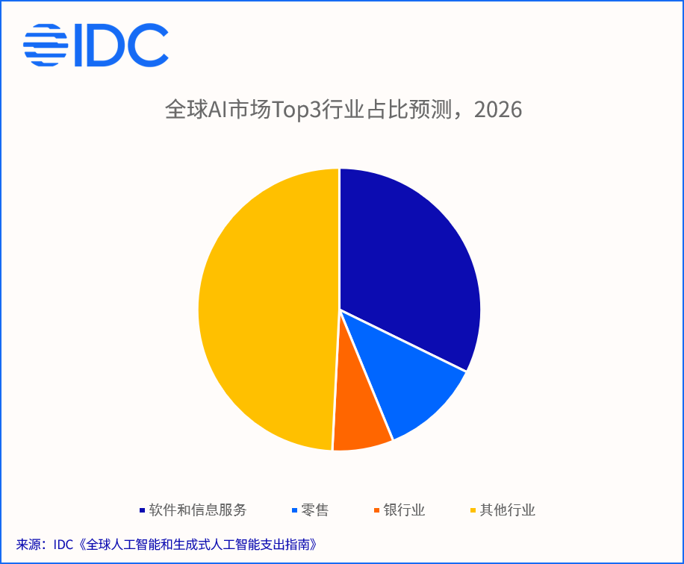
2026年,Agentic AI 已全面进入生产环境。然而,早期部署者正面临一个普遍且棘手的现象:活跃智能体数量平稳增长,而月度Token消耗与基础设施成本却出现数倍乃至数十倍的剧烈波动。单纯关注Agent数量已无法解释成本曲线的陡峭程度。本文基于IDC《Worldwide Agentic AI Adoption Guide》数据,从算力消耗结构、部署形态演进与行业渗透路径三个维度,给出2026-2030年的关键判断。
Agentic AI 并非短暂的技术热潮,而是长达数年的生产力范式转移。深刻理解落地规律的企业,将在 2026 – 2030 年的智能化浪潮中,精准锚定架构方向,真正将 AI 转化为可持续的竞争优势。
备注:本文中的 Token 消耗仅统计生产环境中企业级智能体执行业务动作时产生的 Token 及 API 调用消耗,不包含模型预训练、消费级个人设备上的智能体以及独立生成式 AI(如通用聊天机器人)所消耗的 Token。
IDC对四类智能体的定义如下:
定制开发智能体(Bespoke agents):这类智能体依托专用的智能体 AI(Agentic AI)框架或平台实现,在 AI 智能体的设计、开发与部署全环节具备极高的灵活性与可定制性。纯代码级(Pro-code)智能体 AI 框架与平台最适配技术功底深厚的团队——这类团队需要对开发过程拥有极致掌控权,以此落地高度专业化的功能。
自定义配置智能体(Custom-configured agents):企业可围绕主流业务运营自动化需求,自行设计、配置并部署这类 AI 智能体,无需具备深厚的编程能力。低代码工具能够简化、加速 AI 智能体的开发流程,但和所有低代码 / 无代码工具一样,存在相应的权衡取舍:由于深度复用预构建的框架与组件库,开发过程中会内置预设的前提假设与能力边界。
Wendy Zhang is a research analyst in the Data and Analytics group at IDC China. She is responsible for business operations and spending guide in China Enterprise Team. She provides dynamic forecasts of future China and global ICT market development.…
NVIDIA’s agreement to acquire Hugging Face stands to accelerate the transformation of open models into specialized enterprise intelligence.
According to NVIDIA’s acquisition announcement, the $12.93 billion deal would give NVIDIA ownership of a platform used by more than 18 million developers, researchers, and creators to share more than 3 million models.
Developers also use Hugging Face to access datasets, evaluate models, customize model behavior, and prepare digital solutions for production. The acquisition would extend NVIDIA’s business into the platform and services developers use to transform open models.
The finalization of NVIDIA’s acquisition of Hugging Face is all the more notable given the meteoric rise of open models in recent months. Increased adoption of open models in the enterprise has created demand for technologies that help organizations adapt these models to their business processes and sustain them in production. Hugging Face provides the development resources and community knowledge for this work, while NVIDIA provides capital, compute, and engineering expertise. Their combination stands to expand enterprise adoption of open models and intensify competition between open-model ecosystems and proprietary model providers.
NVIDIA has the potential to grow open-model development
NVIDIA’s agreement to acquire Hugging Face could create a stronger community of practice for open model development. Developers and technical decision-makers require post-training data, evaluation methods, reference architectures, recipes, cookbooks, and implementation guidance to transform open models into production digital solutions. Hugging Face provides many of these resources and supports the community relationships through which developers share and improve them. NVIDIA can contribute capital, engineering expertise, and experience with large-scale AI development. The combined organization can make effective development practices more accessible to enterprises, software vendors, researchers, and developers.
A stronger community of practice will help enterprises adapt open models to their business processes and workflows. Development teams can use shared recipes and cookbooks as starting points for post-training and then compare results based on quality, safety, latency, and cost. Developers can document the approaches that prove effective through reference implementations and adapt them to other projects. Testing across models and workloads will refine these methods over time.
China’s open models boost Hugging Face’s global role
NVIDIA’s agreement to acquire Hugging Face would make it the steward of one of the AI industry’s most valuable developer platforms.
China’s open-model ecosystem represents an important part of that platform. Qwen, DeepSeek, Kimi, and GLM have attracted communities that distribute models, create derivatives, publish datasets and evaluations, and develop methods for adapting these models to specialized requirements. Their participation broadens the technical depth and global relevance of Hugging Face.
Stewardship of Hugging Face gives NVIDIA responsibility for a global open-model community whose development extends well beyond its own Nemotron portfolio. The platform brings together models and developers from the United States, China, Europe, and other regions within a common development environment. NVIDIA’s position will depend on its ability to preserve that participation and support competing model families fairly. Successful stewardship would consolidate NVIDIA’s leadership across one of the most prized parts of the AI development ecosystem.
Open-model growth supports NVIDIA’s infrastructure business
Open-model development and enterprise adoption support NVIDIA’s infrastructure business through two distinct sources of GPU demand. Technology suppliers consume GPU capacity when they train, post-train, evaluate, and refine new model families and derivatives. NVIDIA benefits from these workloads even when other technology suppliers develop models that compete with its own portfolio. Hugging Face gives NVIDIA a direct role in the community through which many of these models and development resources are distributed.
Enterprise adoption creates a second source of demand for NVIDIA infrastructure. The more open models enterprises use, the more GPU capacity they consume to customize, evaluate, deploy, and operate them. This demand extends across accelerators, networking, software, cloud capacity, and enterprise support. Hugging Face can connect model selection and customization with the infrastructure required for production. It can also increase utilization across the AI factories that NVIDIA and its partners are constructing to support training and inference workloads.
This relationship gives NVIDIA a way to benefit from model proliferation across the industry. Large model providers continue to invest in custom silicon, and hyperscalers are expanding their own accelerators. Hugging Face provides NVIDIA with a broader source of infrastructure demand that extends beyond any single model provider or cloud platform. Every additional model family, derivative, and enterprise deployment can create workloads for NVIDIA technology. NVIDIA’s objective should be to offer the strongest technical and economic implementation path for the models developers select.
NVIDIA gives Hugging Face greater capacity to fulfill its mission
NVIDIA gives Hugging Face access to the capital and computing infrastructure required to expand its mission. Hugging Face must support a rapidly expanding collection of models, datasets, digital solutions, and development resources. Model hosting, post-training, synthetic data generation, evaluation, and inference also require substantial computing capacity. NVIDIA can fund the infrastructure and longer-term investments needed to expand Hugging Face’s repository offerings, improve platform reliability, and strengthen its tools for model customization and evaluation.
These investments can make open-model development accessible to more developers, researchers, and enterprises. Greater capacity can also help Hugging Face support organizations that require reliable services throughout the production lifecycle. Enterprises need technical support, predictable service levels, model updates, security controls, and governance processes. NVIDIA has the engineering resources and enterprise experience to help Hugging Face address those requirements.
Hugging Face’s neutrality is essential to the acquisition’s value
Hugging Face’s neutrality is essential because developers rely on the platform to access technologies from competing providers. NVIDIA has committed to preserving choice across models, frameworks, cloud services, inference providers, and computing platforms. Developers will not need to use NVIDIA hardware to build on or deploy through Hugging Face. Continued support for AMD accelerators, hyperscaler chips, and other infrastructure will be necessary to maintain confidence in that commitment.
Fair treatment must extend to models that compete with NVIDIA’s portfolio, including those developed on NVIDIA GPUs. The platform must also remain neutral toward models developed on non-NVIDIA accelerators. Hugging Face should apply consistent policies to model discovery, evaluations, featured content, hosting, and distribution. Governance of these functions should remain separate from the commercial priorities of NVIDIA’s model-development teams. Hugging Face will create greater value for NVIDIA if developers continue to trust it as a platform for the entire open-model ecosystem.
Open-model momentum is reshaping the AI infrastructure landscape
NVIDIA’s agreement to acquire Hugging Face places it alongside OpenAI, Anthropic, SpaceX, Google, and Meta among the small group of companies positioned to shape how AI is developed and delivered. Each company combines models, developer technologies, distribution, and access to large-scale compute in a different configuration. NVIDIA’s position brings together Nemotron, Hugging Face, and the industry’s leading AI infrastructure portfolio.
Competition among these companies will produce multiple forms of intelligence across proprietary frontier models, open-model families, and specialized enterprise models. Organizations will select and transform these forms of intelligence according to their business processes, workflows, data, and operating requirements. The acquisition positions NVIDIA to influence both the development of this increasingly diverse market and the infrastructure that supports it. Whether AMD accelerators and hyperscaler chips remain fully supported on the platform NVIDIA now owns will be one test of that influence.
Arnal Dayaratna - Research Vice President, Software Development
Dr. Arnal Dayaratna is Research Vice President, Software Development at IDC. His research focuses on agentic AI, generative AI, foundation models, agentic coding technologies, and low-code and no-code developer technologies. He also examines the broader technology stack around foundation models,…
Ashish Nadkarni - Group Vice President and General Manager, Global Domain Lead, Enterprise Infrastructure
Ashish Nadkarni leads IDC's enterprise infrastructure global research domain. Ashish oversees five global research subdomains: core infrastructure, cloud infrastructure and services, network infrastructure and services, semiconductors and enabling technologies, and digital and datacenter infrastructure and services. Ashish’s coverage spans infrastructure…
In the second quarter of 2026 (2Q26), the worldwide Ethernet switch market reached $18.9B, growing 43.4% year over year (YoY), according to IDC’s Quarterly Ethernet Switch Tracker. The datacenter segment (covering high-speed switching infrastructure in hyperscale, service provider, and enterprise datacenters) grew 64.5% YoY to $12.3B, driven by continued build-out of AI training and inferencing infrastructure.
NVIDIA maintained its position as the #1 branded vendor in datacenter Ethernet switching market share, now holding 20.4% of datacenter segment revenues.
800GbE ports accounted for 41.2% of datacenter revenues, reflecting the relentless push toward higher speeds to meet AI cluster bandwidth demands. The non-datacenter (campus and branch) segment grew 15.7% YoY to $6.6B, supported by enterprise hardware refresh activity and higher component pricing.
The worldwide Router market reached $4.5B in 2Q26, growing 22.8% year over year, according to IDC’s Quarterly Router Tracker. Both the service provider and enterprise segments posted double-digit growth, with the Americas leading the growth across all regions.
Ethernet switch market highlights
Datacenter segment: The datacenter portion of the Ethernet switch market grew 64.5% YoY in 2Q26 to reach $12.3B, according to IDC. The AI infrastructure build-out continues to be the primary growth driver, as hyperscalers, cloud providers, and large enterprises expand capacity for generative and agentic AI training and inferencing workloads. High-speed ports dominate spending: 800GbE switches accounted for 41.2% of datacenter segment revenues, while 200G/400G speeds represented 33.6% — together making up nearly 75% of datacenter Ethernet switch spending.
Campus/branch (non-datacenter) segment: Enterprise campus and branch Ethernet switch revenue grew 15.7% YoY in 2Q26 to $6.6B, per IDC. A broad hardware refresh cycle remains the structural driver, as organizations upgrade aging switching infrastructure to support the latest wireless standard, Wi-Fi 7, and AI-capable workloads. AI-powered network management and integrated security, including post-quantum cryptographic capabilities, are other key drivers in this segment. Higher average selling prices, driven by component cost pressures, continue to contribute to revenue growth above underlying unit volumes.
Regional performance: Ethernet Switch revenues grew across all geographies in 2Q26, according to IDC. The Americas led with 50.4% YoY growth to $10.2B, reflecting robust hyperscaler and enterprise AI investment in North America. EMEA grew 36.9% YoY to $4.1B, while Asia Pacific posted 35.3% growth to $4.6B.
Router market highlights: The total Router market reached $4.5B in 2Q26, growing 22.8% year over year, driven by investment in both service provider and enterprise network infrastructure, according to IDC’s Quarterly Router Tracker.
Service provider segment: The service provider segment — including communications service providers and cloud SPs — made up 74.2% of total router market revenues in 2Q26, reaching $3.3B with 23.8% YoY growth. Cloud and telecom infrastructure upgrades, including 5G backhaul expansion and core network modernization, remain the primary growth drivers.
Enterprise segment: The enterprise router market contributed $1.2B in 2Q26, growing 20.1% YoY, reflecting sustained investment in enterprise WAN connectivity, SD-WAN-enabled infrastructure modernization, and the expansion of AI-ready branch and edge network environments.
Regional performance: The Americas router market rose 31.1% YoY in 2Q26 to $1.9B, leading all regions. EMEA grew 20.9% YoY to $1.1B, while Asia Pacific posted 15.2% growth to $1.5B.
Vendor highlights
Cisco: Cisco’s total Ethernet switch revenues grew 36.2% YoY in 2Q26 to $5.4B, maintaining a 28.7% market share and retaining the #1 market share position in the overall Ethernet switch market, per IDC. In the datacenter segment, Cisco generated $2.2B (18.2% share), growing strongly with AI networking demand. Cisco’s total router revenue grew 31.6% YoY to $1.6B, with a 34.7% share of the global router market.
NVIDIA: NVIDIA’s Ethernet switch revenues — entirely from the datacenter segment — surged 181.1% YoY to $2.5B in 2Q26, giving it a 20.4% share of the datacenter Ethernet switch segment, according to IDC. NVIDIA maintained its position as the #1 branded vendor by revenue in datacenter Ethernet switching. The Spectrum-X platform — an end-to-end AI networking solution integrating Spectrum Ethernet switches with BlueField DPUs and NVIDIA LinkX cables, purpose-built for large-scale GPU clusters — continues to win hyperscaler and AI-native cloud provider deployments at scale.
Arista Networks: Arista’s revenues grew 37.6% YoY in 2Q26 to $2.5B, per IDC, with the company holding a 13.4% share of the total Ethernet switch market and 18.7% in the datacenter segment. With approximately 90.9% of revenue from the datacenter segment, Arista continues to maintain a strong position in 400G and 800G deployments among hyperscale and cloud customers.
Huawei: Huawei’s total Ethernet switch revenue grew 28.6% YoY in 2Q26 to $1.5B, with an 8.2% market share, per IDC. Huawei’s Router revenue grew 21.6% YoY in 2Q26 to $1.3B, giving the company a 29.9% share of the global router market — underscoring continued strength in service provider networking, particularly in China and select emerging markets.
HPE: HPE’s total Ethernet switch revenue grew 1.6% YoY in 2Q26, reaching a 6.1% market share, per IDC. HPE revenues include Juniper Networks, following the July 2025 acquisition. The company’s campus and branch portfolio, which represents approximately 70.1% of its Ethernet switch business, continues to benefit from the enterprise hardware refresh cycle. HPE’s router revenues grew 25.3% YoY to $483M in 2Q26, representing a 10.7% market share.
Worldwide Top Ethernet Switch Companies
Market dynamics
AI infrastructure fuels another quarter of record datacenter spending: For the second consecutive quarter, AI infrastructure investment drove Ethernet switch market growth above 40% YoY. Hyperscalers and AI-native cloud providers are accelerating the deployment of GPU-dense AI factories, requiring ultra-low-latency, high-bandwidth switching fabric capable of sustaining the massive east-west traffic flows generated by distributed training workloads. The share of 800G ports in datacenter Ethernet switch revenues rose to 41.2% in 2Q26, up from 35.9% in 1Q26, reflecting a clear and accelerating shift toward next-generation port speeds.
Enterprise refresh and pricing dynamics sustain non-datacenter growth: Non-datacenter Ethernet switch revenue grew 15.7% YoY in 2Q26, sustained by a multi-year enterprise hardware refresh wave and persistent component-price inflation. Organizations are upgrading campus and branch switching infrastructure to support newer wireless standards, AI-capable applications, and modern digital workloads. IDC notes that supply cost pressures — particularly in memory components — continue to inflate revenue growth above underlying unit shipment trends, a dynamic that is expected to persist.
Router market accelerates on SP and enterprise investment: The router market’s 22.8% YoY growth in 2Q26 reflects broad investment across both segments. Service providers are investing in network infrastructure to support 5G expansion, cloud interconnect, and edge deployments. Enterprise demand reflects ongoing WAN modernization, SD-WAN adoption, and the expansion of AI-ready branch and edge environments. The Americas accounted for 41.9% of global router revenues in 2Q26, growing 31.1% YoY — the fastest regional growth rate — driven by strong North American SP and enterprise network investment.
“
AI cluster buildouts are now the single biggest driver of datacenter network spend, and the rapid move to 800GbE shows hyperscalers optimizing for bandwidth and latency more than ever before. As GPU clusters keep scaling, switching fabric and related networking has become one of the fastest-moving and most critical layers of AI infrastructure investment.
“
The campus refresh cycle is accelerating as organizations modernize switching infrastructure to support Wi-Fi 7, AI workloads, and higher-speed connectivity. The convergence of networking and security—including post-quantum cryptography and rapid AI-driven threat patching—is reshaping infrastructure requirements and driving sustained upgrade momentum through 2026.
Why it matters
The 2Q26 results confirm that AI infrastructure demand is the defining force in the datacenter networking market, with sustained implications for vendor strategy, technology architecture, and enterprise procurement. The accelerating shift toward 800G and beyond is compressing product cycles and raising the stakes for vendors to maintain technology leadership. Outside the datacenter, enterprise networking teams face a critical decision point: legacy campus and branch infrastructure must be modernized to support AI-capable applications, next-generation wireless, and the increasing data throughput demands of digital operations. For enterprise buyers and IT leaders, the 2Q26 data underscores the urgency of aligning networking refresh cycles with a multi-year AI buildout that is accelerating, not plateauing.
Outlook
IDC expects the Ethernet switch market to continue posting strong year-over-year growth through 2026, driven by ongoing AI infrastructure investment in the datacenter and sustained enterprise refresh demand in the campus and branch segments. The pace of 800G adoption is expected to accelerate further, and early demand signals for 1.6T ports are beginning to emerge as hyperscalers plan next-generation AI cluster architectures. In the router market, service provider investment in 5G core and backhaul infrastructure, combined with enterprise WAN modernization, is expected to sustain double-digit growth. IDC will continue to track these dynamics through its quarterly tracker programs.
Paul Nicholson is Research Vice President within IDC’s enterprise infrastructure global research domain and part of the networking infrastructure and services subdomain. He focuses on AI, cloud, and datacenter network infrastructure. His research spans Ethernet and InfiniBand switching, application delivery…
Brandon Butler - Senior Research Manager, Networking and Infrastructure Services, Enterprise Infrastructure
Brandon Butler is a Senior Research Manager within IDC’s enterprise infrastructure global research domain and part of the networking infrastructure and services subdomain. His research covers market and technology trends, forecasts, and competitive analysis in enterprise campus, branch, and edge…
Petr Jirovsky - Senior Research Director, Networking and Infrastructure Services, Enterprise Infrastructure
Petr Jirovsky is a Senior Research Director within IDC’s enterprise infrastructure global research domain and part of the Networking and Infrastructure Services subdomain. He provides quantitative insights on network infrastructure for the datacenter, cloud, and campus/branch environments. He serves as…
Diego Anesini serves as Vice-President, Data & Analytics, Networking. Prior to this position, Diego held various roles in the company. The most recent was VP, Data & Analytics for Latin America. He has extensive experience in the Networking, Telecom and…
It’s all in the name: Real Results. IDC’s annual FinTech Rankings and Real Results program doesn’t hand out recognition for a slide of names. It looks for technology providers that made a measurable difference at real financial institutions, and this year’s winners are now live, marking the 24th year of the Rankings and the 14th year of Real Results.
The Rankings started as a straightforward ask from IDC’s institutional clients: banks, capital markets firms, and insurance carriers who wanted a clear picture of the technology landscape serving their industry. “They really wanted from us kind of what the landscape looked like in terms of technology providers,” Silva says
IDC evaluates and categorizes technology providers by prior-year revenue from financial institutions across hardware, software, and services. Two lists come out of that work. The Top 100 covers firms that specialize in financial services: more than a third of their revenue comes from the industry, and they don’t spread across more than two other verticals. The Enterprise Top 50 covers larger, broader technology firms, think Microsoft, IBM, Dell, that generate meaningful financial-services revenue without being narrowly focused on the industry.
What separates the Top 10 from the rest of the list
Making either list depends on revenue. Where a company lands within it depends on something else. Silva points to product and capability range as the real differentiator between the Top 10 and everyone below it. Companies further down tend to specialize in one function, like payments or fraud, while the leaders cover core banking, payments, risk and compliance, customer experience, and data and analytics all at once. “Those companies at the top of the list tend to be incredibly broad,” he says.
How Real Results complement the rankings
Rankings measures size and reach. Real Results measures something else entirely: whether the technology actually worked. The program was Silva’s addition, and it came from a specific frustration. After decades on the institution side of the industry, he’d grown tired of innovation awards that never tied back to a measurable outcome. “I kept seeing all these innovation awards out there that never really focused on what was the benefit,” he says. “It was always about, well, this will enable the client to do X, Y, Z in the future. Well, that doesn’t help me.”
So Real Results asks technology providers to submit case studies: real projects, at a named institution, with a verified metric attached. IDC contacts someone at the institution directly to confirm the numbers. Fourteen years later, the program covers seven categories: infrastructure modernization, omni-experience customer engagement, treasury and trade, payments, capital markets, insurance transformation, and digital trust and stewardship.
The bar is strict. “If a submission doesn’t have those numbers, doesn’t have quantifiable, measurable benefits, I disqualify it,” Silva says. Projections about future value don’t qualify. IDC only considers results that have already happened..
The biggest shift in this year’s case studies: AI, everywhere
That bar produced a clear pattern in this year’s submissions. Historically, no single technology dominated Real Results entries. The closest IDC came to a unifying trend was the cloud migration wave of 2018-2019. That’s changed. For the past two years, AI has driven nearly every entry, and this year’s winners went further than a single AI tool.
“Most of the winners, all except maybe one, used a combination,” Silva says: traditional machine learning, generative AI for content creation, and agentic AI to orchestrate the whole process, often in the same project.
The overall winner illustrates it well. A large bank had a legacy process scattered across multiple systems, and instead of stitching those systems together point to point, the technology provider used machine learning and generative AI to create usable data out of the legacy sources, with AI agents orchestrating the process end to end. The result was fewer errors and lower costs, with a process that used to take days now finishing in hours.
Where financial services technology spending is headed next
That same AI-everywhere pattern shows up in where the market is headed next, though not in the part of the business most people assume. Over the past six to nine months, investment has shifted away from front-office, customer-experience projects and toward the back office: modernizing databases, finance platforms, and HR systems.
Two forces are driving it. Most institutions don’t have their data in a state that’s ready for AI to run against multiple sources at once, so they’re investing to fix that first. And once an AI platform is in place, institutions want a more open, API-driven back office instead of stitching new tools to legacy systems one connection at a time.
The scale of that investment is notable on its own. IDC’s newest forecast puts financial services technology spending, hardware, software, and services combined, at more than a trillion dollars a year globally by 2030, growing around 12% annually. “I think you’ll see a huge shift to the back office until they start solving some of those problems,” Silva says.
Where to see the full 2026 IDC FinTech Rankings winners
The full 2026 IDC FinTech Rankings and Real Results winners are live now. Twenty-four years in, institutional clients still use the list the same way they did at the start: as a shortlist. As Silva puts it, when institutions are evaluating a project, “the list actually helps them narrow down that short list.”
Christina Cardoza - Content Marketing Manager - IDC
Christina Cardoza is a Content Marketing Manager at IDC, where she specializes in brand content and social media strategy. With a background in journalism and editorial leadership, she has a proven ability to transform complex technology topics into clear, actionable insights.
Apple used this cycle to launch its first foldable iPhone, the iPhone Duo, alongside the iPhone 18 Pro family, Apple Watch Series 12 and Ultra 4, AirPods 5 and to widen the Apple Intelligence and Siri AI story across the range. The iPhone Duo is the flagship, a test of whether design, ecosystem and premium positioning can reshape a segment that has largely failed to appeal to the mainstream consumer.
Pricing was at the center of the event. At a time when we expected prices to rise beyond what consumers are comfortable paying due to memory costs, Apple held its increases below what we expected. The iPhone 18 Pro arrives at $1,199 and the Pro Max at $1,299, each only $100 up from last year (we expected at least a $150 increase). The company kept the starting price of its new Apple Watch Series 12 and Ultra the same as last year ($399 and $799). AirPods 5 bring active noise cancellation to a $129 entry point, $50 below the $179 price of the noise-cancelling AirPods 4. The foldable, Apple’s most expensive iPhone yet, starts at $1,999 versus an industry expectation of $2,499, which was the biggest surprise of all. Apple expanded the number of products it offers at mainstream prices and opened a super-premium tier at the top, all in a single keynote.
Apple Watch and AirPods strengthen the ecosystem
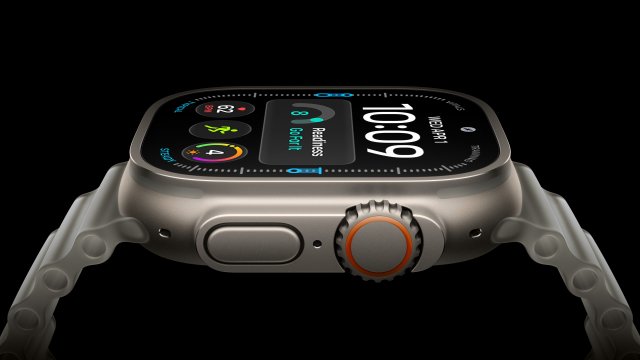
Apple Watch Series 12 and Ultra 4 put health sensing at the center. Both use the Apple S11 chip and a redesigned sensing system that reads heart rate every five seconds and heart-rate variability every five minutes, enough for continuous measurement rather than the isolated readings of previous versions. The new Readiness score combines training load, vitals and sleep quality, and the redesigned Health app adds Insights, Longevity and a Health Age metric, with Apple Intelligence underneath it. The proposition is moving from measurement toward interpretation and guidance, and looks to bring Apple into line with fitness-focused devices and services such as Whoop.
Audio Intelligence features on the watches, designed to help you hear what you missed (Live Rewind), capture sounds (Sound Recognition) or capture notes (Siri Recap), find Apple attempting to walk a fine line between always-listening ambient AI computing and its desire to respect users’ privacy.
AirPods 5 apply the same pricing logic lower down the range. The $129 model brings ANC to the entry point, and the $149 version adds volume swipe, wireless charging and an extra hour of battery. Apple says the new ANC is 50% better than its prior open-ear model with ANC. Lowering the entry price pulls more people into a companion device they rarely give up.
iPhone 18 Pro Series reinforces the premium core
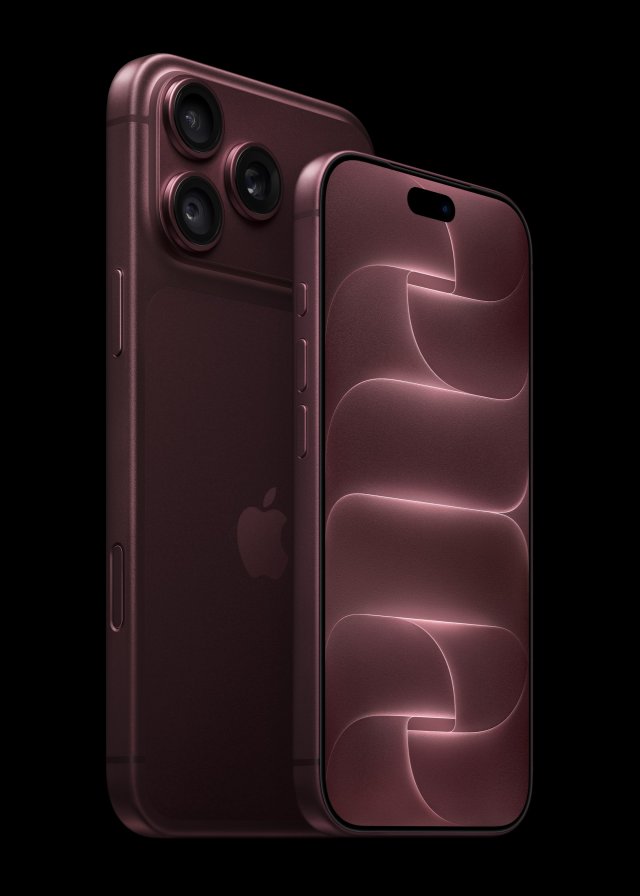
The iPhone 18 Pro and Pro Max defend the conventional flagship through performance, imaging and AI. The A20 Pro runs on-device Apple Intelligence, with Private Cloud Compute handling heavier work, and the 48MP Fusion main camera adds a physical variable aperture as wide as f/1.48. The most notable addition is Apple Reference Image, which signs pixel-level data at the sensor so a user can prove a photo was captured on the device and not altered. These products hold the premium core in place while the Duo enters above it, the Pro at $1,199 for 256GB and the Duo at $1,999 for the same storage.
18 Base Model moves to spring, redefines cadence
While the spotlight is on the Duo today, an important factor is the silent omission of the 18 base models. Apple’s shift of the base iPhone 18 to spring is a portfolio decision, decoupling the base models from the premium lineup in the fall. According to IDC, the last two base iPhone launches drove 16% of Apple’s total shipments in their first two quarters, though as lower-ASP devices their share of revenue runs below that unit figure. The new cadence allows Apple to even out its performance seasonality throughout the year and give each line clearer positioning.
Apple has also diversified its iPhone lineup into six different models, widening its demographic reach. The six are clearly grouped into two categories: the premium line (Pro, Pro Max, and Duo) launches in the fall; the budget-friendly line (base, E, and Air) follows in the spring. Each wave of devices gets a clear commercial narrative instead of six SKUs competing for the same spotlight.
iPhone Duo changes the foldables equation
The iPhone Duo is a polished piece of first-generation hardware. It positions foldability as a finished product rather than a work in progress. It pairs a 7.6-inch internal Super Retina XDR display with a 5.4-inch external one and runs on the A20 Pro with a dedicated display engine and a custom titanium hinge of more than 100 components, high-strength glass and a nano-texture finish meant to cut glare and play down the crease.
The software is the more differentiated part, with fluid transition from closed to open, intuitive execution of side-by-side apps, paired apps for repeated workflows, content movement between them, use in partly folded orientations and a redesigned standby, with Apple Pencil USB-C support due later this year. The point is to make the larger display more useful in day-to-day use rather than just feeling like a bigger phone. As with any first-generation foldable, the open questions are hinge and display durability over time and how the crease and added weight hold up in daily use.
Pricing starts at $1,999 for 256GB and passes $3,000 at 2TB of storage. That entry sits $500 below the $2,499 the market expected, and at roughly 1.6 times Apple’s non-foldable iPhone ASP of around $1,209. IDC still puts the blended iOS foldable ASP higher once storage mix is counted. Apple has not built a mass-market device. It has created a premium product for high-value iPhone users, which lets the Duo lift both foldable volume and Apple’s premium mix.
A value opportunity, not a volume-led category
IDC’s forecast explains why the Duo can matter even if foldables stay a small share of the market. Worldwide foldable value grows from $26.7 billion in 2025 to $42.0 billion in 2026 and $68.2 billion by 2030, a 20.6% CAGR from 2025 to 2030, while units rise from 20.3 million in 2025 to 35.8 million in 2030. Value grows faster than volume, which is what makes the segment worth Apple’s attention. Foldables move from 2.2% of global smartphone units in 2026 to 3.1% in 2030, but their revenue share climbs from 6.9% to 10.0%.
Apple does not need unit leadership for the Duo to pay off, though its design and price could deliver that as well. Supply may be the initial constraint, as Apple’s exacting standards make the unit hard to manufacture in large volumes at the start. We expect the company to ship roughly ten million units in the first 12 months. With Android foldable units forecast to fall this year, IDC expects Apple’s entry to be the main driver returning the segment to growth. The gap between value and unit share is the key: Apple can take a disproportionate share of category revenue by setting the premium reference point.
The China Test
China is the toughest test for the Duo, and also its clearest value opportunity. Huawei led the market with 79.4% of foldable units and 82.2% of value in the second quarter of 2026, backed by an established range, market familiarity and channel strength. IDC projects iOS foldables in China to reach 2.0 million units and $4.9 billion in value in 2026, rising to 4.4 million units and $10.3 billion by 2030, with Apple’s share of China foldable value growing to 50.8% and its unit share to 39.7% over the same period.
Apple leads on value well before it leads on units, which fits a premium entry priced above the rest of the market. The requirement is execution: industrial design, durability, display quality and app support strong enough to trade buyers up in a market that already has credible alternatives. If it gets that right, Apple can take a meaningful share of category value, helped by its standing as an aspirational brand. Get it wrong, and Huawei’s entrenched lead and China’s support for homegrown brands could hold the Duo to a niche.
What the September lineup signals
Taken together, the lineup reads as one strategy: AirPods lower the barrier to a premium feature, Apple Watch adds health value while holding price, the iPhone 18 Pro defends the premium core with measured discipline, and the iPhone Duo opens a new high-value tier below the price the market expected. Each move serves a larger active installed base, more multi-device ownership and stronger ecosystem attachment, with Apple Intelligence and Siri AI as the connective layer and on-device processing supporting the privacy story.
The real test for Apple is whether it can make foldables a more valuable category, own the defining premium product and use that position to extend the economics of the iPhone portfolio. IDC’s forecast suggests it can, with Apple positioned to be a principal driver of category growth through 2030.
Getting there requires strong first-generation execution, a convincing software story, and a credible strategy in China. Deliver those and the iPhone Duo stops being a new form factor and becomes a margin engine and a mix lever, and a sign Apple can still shape a category it entered years after competitors did.
Francisco Jeronimo - VP, Data and Analytics, Devices, IDC EMEA
Francisco Jeronimo is VP for Data and Analytics at IDC EMEA. Based in London, he leads the research that covers mobile devices, personal computing devices, emerging technologies and the circular economy trends across EMEA. His team delivers data on personal…
Tom Mainelli - Group Vice President, Device & Consumer Research
Tom Mainelli heads the Device & Consumer Research Group, overseeing a wide array of hardware and technology categories catering to both home and enterprise markets. His team's research spans PCs, tablets, smartphones, wearables, smart home devices, thin clients, displays, and…
Nabila Popal is Senor Director with IDC's Data & Analytics team, specializing in Mobile Phones, PC Monitors and other consumer devices. Ms. Popal is responsible for the global research and quality and timely delivery for her respective technologies, coordinating with regional…
The worldwide WLAN market reached $3.2B in the second quarter of 2026 (2Q26), growing 23.2% year over year (YoY). That’s an acceleration from the 15.6% growth in 1Q26. The quarter’s growth reinforced Wi-Fi 7 (802.11be) as the new dominant Wi-Fi standard in the enterprise.
Wi-Fi 7 is now the single largest revenue category in enterprise WLAN, reflecting a broad shift in enterprise purchasing priorities.
The results span all major regions and vendor tiers. The market has moved past its early-adoption phase into a full replacement cycle.
WLAN market highlights
Total market: The worldwide WLAN market grew 23.2% YoY in 2Q26, reaching $3.2B. That’s a meaningful acceleration from the prior quarter. The enterprise dependent access point (AP) segment grew 27.6% YoY to $2.7B, outpacing the broader market and reflecting sustained corporate investment in dependent wireless infrastructure. The pace of growth suggests that enterprise Wi-Fi refresh cycles are broadening beyond early adopters to mainstream deployment.
Wi-Fi 7 momentum: Wi-Fi 7 dependent AP revenues reached $1.4B in 2Q26, representing 53.0% of enterprise dependent AP revenues and growing 219.5% year over year. This transition reflects the convergence of a maturing Wi-Fi 7 product ecosystem, enterprise demand for higher-throughput infrastructure, along with the pull-forward effect of AI-driven network requirements and AI-powered wireless management.
Wi-Fi 6/6E trajectory: As Wi-Fi 7 adoption continues, earlier-generation standards are declining in share. Wi-Fi 6 accounted for 29.4% of enterprise dependent AP revenues in 2Q26 (down from 34.8% in 1Q26), while Wi-Fi 6E held 16.9%. Both previous-generation standards remain relevant in phased enterprise rollouts and mid-market deployments. In new projects, though, Wi-Fi 6/6E investment has largely given way to Wi-Fi 7.
Regional performance: Growth was broad-based across all three regions in 2Q26. EMEA led with 32.2% YoY growth, reaching $1.0B supported by enterprise refresh investment and expanding Wi-Fi 7 adoption across Western and Central Europe. The Americas grew 21.6% YoY to $1.5B, maintaining its position as the largest regional market. APJ expanded 15.2% YoY to $708.1 million.
Vendor highlights
The 2Q26 vendor field reflects a market in active expansion, with the top five vendors posting revenue growth.
Cisco: Cisco posted $1.3B in enterprise WLAN revenues in 2Q26, growing 27.2% YoY and maintaining its position as the market share leader with a 39.0% share. Cisco’s growth reflects enterprise demand across its Wi-Fi 7 portfolio and continued momentum in large campus and branch deployments. Cisco’s scale and long-standing enterprise relationships keep it entrenched in complex, multi-site deployments, backed by a go-to-market channel that’s hard for smaller vendors to match.
HPE/Juniper: The combined HPE and Juniper entity posted $557.2 million in enterprise WLAN revenues in 2Q26, growing 7.5% YoY with a 17.2% market share. While the growth rate is more moderate than its peers this quarter, HPE’s Aruba and Juniper Mist AI-driven platforms remain the pick for enterprises that prioritize AIOps and cloud-managed deployments, particularly those consolidating wired and wireless management under one roof.
Ubiquiti: Ubiquiti posted $415.9 million in 2Q26 revenues, growing 33.1% YoY with a 12.8% market share. Its continued above-market growth reflects traction in the mid-market and among managed service providers, where the company’s competitive pricing and rapid Wi-Fi 7 product refresh are leading to consistent revenue momentum.
Huawei: Huawei posted $339.7 million in 2Q26 revenues, growing 44.0% YoY and reaching a 10.5% market share, up from 6.0% in 1Q26. Growth was driven by its Wi-Fi 7 campus portfolio and integrated campus networking solutions, with standout performance in markets across Asia Pacific and EMEA where Huawei holds established enterprise customer relationships.
Vistance Networks: Vistance Networks (formerly CommScope/Ruckus) posted $107.2 million in 2Q26, growing 9.9% YoY with a 3.3% market share. The Ruckus portfolio continues to hold its position in high-density verticals including hospitality, education, and large venues, where its enterprise-grade quality and deployment flexibility remain competitive differentiators. In April 2026, Belden announced its intent to acquire Ruckus Networks from Vistance Networks, a $1.85B deal that closed in July 2026.
WLAN Top Companies Chart
Market dynamics
Wi-Fi 7 as the new enterprise baseline
The 2Q26 results confirm that Wi-Fi 7 is no longer a premium upgrade choice, rather it has become the default selection for enterprise wireless procurement. The speed and breadth of this transition is driven by a combination of factors: a broad hardware refresh cycle that has created natural replacement demand across installed Wi-Fi 5 and early Wi-Fi 6 deployments; a matured vendor product portfolio that has brought Wi-Fi 7 to competitive price points across all market tiers; and the pull-forward effect of enterprise AI adoption, which is raising throughput and latency requirements across office environments, campuses, and branch sites.
Persistent supply chain headwinds caused by industry-wide memory shortages continue to extend lead times and increase average selling prices (ASPs) across the enterprise WLAN market, forcing enterprise buyers into difficult trade-offs. Organizations are choosing between accelerating purchases to secure inventory or deferring deployments to manage costs, reshaping buying patterns as cost-conscious enterprises prioritize strategic deployments while others absorb premium pricing.
“
Strong 2Q26 results in the enterprise WLAN market underscore a market in full transition. The campus refresh cycle is accelerating across regions, driven by the convergence of Wi-Fi 7, multi-gigabit switching, and AI adoption. Organizations are modernizing networks to support AI workloads while simultaneously leveraging AI and agentic capabilities to streamline engineering and operations. Despite supply chain headwinds, IDC expects momentum in the enterprise wireless industry to continue as organizations across the globe prioritize network modernization in the AI era.
Why it matters
Who should care? CIOs, network architects, and IT procurement teams making refresh decisions in the next 12-18 months should treat Wi-Fi 7 as the standard starting point, not an optional upgrade. The market has moved: vendors are shifting development and supply chain focus to Wi-Fi 7, and the price premium over Wi-Fi 6 is narrowing rapidly. Deferring Wi-Fi 7 now means retrofitting networks to meet AI application requirements sooner than expected.
Business impact: The acceleration in enterprise WLAN growth, 23.2% YoY, up from 15.6% in the prior quarter, reflects real enterprise budget commitment to wireless modernization. Organizations that have invested in Wi-Fi 7 infrastructure are building the connectivity foundation for AI-powered collaboration, real-time location services, and high-density mobile workloads. The TCO calculus increasingly favors Wi-Fi 7 over incremental Wi-Fi 6E upgrades.
What’s next for the WLAN market
IDC expects the enterprise WLAN market to sustain growth through the second half of 2026, with Wi-Fi 7 continuing to consolidate its dominant position, despite supply chain headwinds. As the enterprise installed base of Wi-Fi 6 and 6E access points continues to mature, the addressable refresh opportunity remains substantial. Demand from AI-intensive applications (spanning inference at the edge, high-density video, and IoT integration) will continue to pull forward network investment decisions. Integrated, secure networking is another key driver in the refresh opportunity.
The competitive dynamics established in 2Q26 are likely to persist. Cisco’s scale advantage in large enterprises is durable, but Huawei’s trajectory and Ubiquiti’s mid-market momentum mean that market share will remain actively contested. Macro risks, including regional economic uncertainty and supply chain disruptions, are real watch items for the back half of the year. None of them have shown up yet in the refresh demand IDC is tracking.
For deeper analysis and IDC research on enterprise wireless LAN trends, visit the IDC Quarterly Wireless LAN Tracker, or contact IDC for the latest market insights and custom research.
Brandon Butler - Senior Research Manager, Networking and Infrastructure Services, Enterprise Infrastructure
Brandon Butler is a Senior Research Manager within IDC’s enterprise infrastructure global research domain and part of the networking infrastructure and services subdomain. His research covers market and technology trends, forecasts, and competitive analysis in enterprise campus, branch, and edge…
Petr Jirovsky - Senior Research Director, Networking and Infrastructure Services, Enterprise Infrastructure
Petr Jirovsky is a Senior Research Director within IDC’s enterprise infrastructure global research domain and part of the Networking and Infrastructure Services subdomain. He provides quantitative insights on network infrastructure for the datacenter, cloud, and campus/branch environments. He serves as…
Diego Anesini serves as Vice-President, Data & Analytics, Networking. Prior to this position, Diego held various roles in the company. The most recent was VP, Data & Analytics for Latin America. He has extensive experience in the Networking, Telecom and…
The AI line item on this quarter’s cloud invoice doesn’t match anything in the forecast tab. Six months ago it was a rounding error. Now it’s the fastest-growing number in the budget, and finance, IT, and the vendor each have a different answer for who owns it.
What is token economics, and why is it suddenly a CFO problem?
Token economics, or “Tokenomics,” is the financial discipline of measuring, benchmarking, and governing what an enterprise pays per unit of AI inference (the token), instead of treating AI spend as an extension of software licensing. This year, the Linux Foundation formalized the discipline by launching the Tokenomics Foundation, with founding support from Google Cloud, IBM, Microsoft, SAP, Accenture, and JPMorganChase. A dozen of the world’s largest technology and financial institutions agreeing to standardize how AI cost gets measured is itself the signal: AI spend had gotten too complicated to track the old way.
Why AI costs don’t behave like software licensing
A seat count is predictable. A token count is not. It moves with every prompt, every agent reasoning step, and every tool call an application makes on a user’s behalf, and it can double inside a single product decision an engineering team makes without ever looping in finance. IDC research puts a number on how unevenly that cost lands: output tokens run 3 to 5 times more expensive than input tokens, and a multiagent pipeline that isn’t monitoring its input-to-output ratio can understate its true inference cost by 3x or more. Two enterprises already know what that miscalculation costs in dollars: one exhausted an entire year’s AI budget by April after rolling out a coding assistant at scale, and a hospital system logged more than $6 million in unplanned charges before its finance team traced the source.
Every dollar of wasted AI agent spend is a governance failure.
Eighteen months ago, that framing would have stayed inside IT. Now it’s pushing the ownership question into board-level conversations, next to the AI budget line itself.
What CFOs can do now: Building a full-stack token cost model
The starting point is visibility, not restriction. A full-stack token cost model — compute, storage, networking, power, cooling, and facilities, expressed per million tokens by workload — is the analytical foundation every AI infrastructure and purchasing decision now depends on. IDC research shows that routing tokens to right-sized models, rather than defaulting every workload to the largest frontier model available, cuts cost per token by 30 to 60 percent with no new hardware investment. That’s the shift worth pushing for this budget cycle: a defined per-million-token cost figure attached to every new AI request before it reaches sign-off.
Ask engineering for input-to-output token ratios by workload before the next planning cycle closes.
Require any new AI deployment request to show a per-million-token cost estimate, the same way a seat-based software request shows per-seat pricing.
Put the ownership question on the agenda directly. CFOs demanding embedded governance, modular architecture, and real-time cost visibility from vendors are already ahead of most of the market.
What to expect new
Expect the CFO-CIO ownership question to formalize rather than resolve itself quietly: joint AI-FinOps governance structures, full-stack token cost modeling required before any new infrastructure commitment, and CFOs setting vendor selection criteria that used to belong to IT alone. The enterprises moving on this now are building that model before the FY27 budget cycle locks. Everyone else is having the ownership argument for the first time, mid-budget-season, with finance and IT starting from different numbers.
Ryan Smith - Content Marketing Director - IDC
Ryan Smith is the Director of Content Marketing at IDC, where he leads brand-level content and social media strategy, aligning research insights with compelling storytelling to engage technology decision-makers. With a background in both IT and marketing, Ryan brings a unique blend of technical understanding and creative strategy to his work. He’s also a seasoned storyteller, speaker, and podcast host who believes the right message, told the right way, can drive both trust and transformation.
Sophie Pan is a research director for the Client Systems Research team at IDC China. She is responsible for emerging technology device research, including wearable devices and smart home devices. Sophie has a deep understanding of the landscape and ecosystem…
OpenAI公布的评测显示,Astra完成特定场景专业任务时,相比其他旗舰模型的耗时与输出Token消耗有所降低,例如在OSWorld 2.0离线评测的延迟模拟中,单任务耗时比Sol下降约47%;Agents’ Last Exam中,输出Token消耗比Opus 5减少约65%。长链路任务的综合成本因此可能下降,但短链路任务与高频调用则随着Token单价的提升可能会变的更贵;企业的实际支出更多取决于推理档位选择、缓存复用与路由策略,以及智能体场景的工程优化与Skill建设水平。旗舰模型单价随能力代际上移已在形成趋势,Token成本治理也因此成为企业的必要能力。
Zhenya Sun is a research manager for the IDC team focused on exploring the application of technology and industrial development of AI and AI agents. He is also responsible for providing clients with consulting services on technologies, products, and markets…
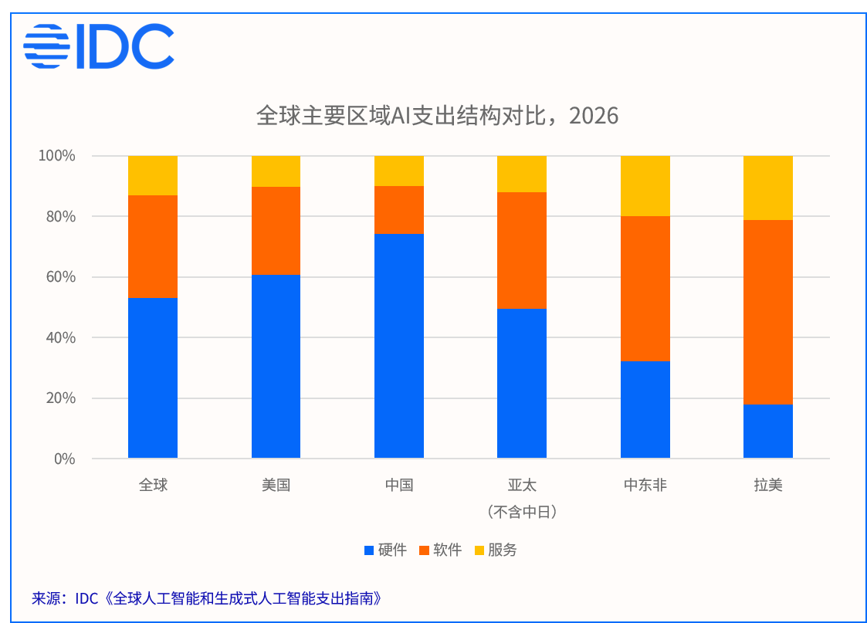
解构 AI 硬件、软件与服务三大技术板块可以发现,海外市场与国内市场在产品形态偏好上差异明显。2026年中国AI支出中硬件占比高达74.3%,呈强基础设施驱动特征。但到了海外,情况截然不同——拉美地区AI硬件仅占18.0%,软件则占比高达60.9%;中东非软件与服务合计占比达67.9%。这意味着,把国内“卖服务器、卖算力卡”的模式直接搬到海外,将遭遇严重的水土不服。
Wendy Zhang is a research analyst in the Data and Analytics group at IDC China. She is responsible for business operations and spending guide in China Enterprise Team. She provides dynamic forecasts of future China and global ICT market development.…
IDC Environmental Policy
International Data Group is committed to protecting the environment, the health and safety of our employees, and the community in which we conduct our business. It is our policy to seek continual improvement throughout our business operations to lessen our impact on the local and global environment. We are committed to environmental excellence, pollution prevention and to purchasing products that reduce the use of natural resources.
We fulfill this mission by a commitment to:
Encouraging all partners to share in our mission
Understanding environmental issues and sharing information with our partners
Recognizing that fiscal responsibility is essential to our environmental future
Instilling environmental responsibility as a corporate value
Developing innovative and flexible solutions to bring about change
Using our platforms and position in the IT industry to promote sustainability
Minimize air travel to help reduce our impact on the environment
Minimize use of materials and energy consumption in our offices
Create a working environment that efficiently uses our office space
Develop and maintain a hybrid working model that benefits both our employees and business partners
Encourage employees to measure, minimize and collaborate on reducing energy consumption at home and in the office
Engaging employees and promoting active participation in environmental and sustainability initiatives
Leaving?
You are about to leave this section. Do you wish to continue?