AI is no longer just a tool for productivity. It’s changing who makes buying decisions, how they evaluate vendors, and what they expect from every interaction. For analyst relations (AR) professionals, that means a new mandate: turning complex buyer insights into influence across executives, marketing, and sales teams.  

During IDC’s recent webinar, Turning Insights into Influence: Leveraging Buyer Behavior Research, Laurie Buczek, Group VP of Executive Insights and Thought Leadership Services at IDC, explored how AI and shifting buyer behavior are reshaping go-to-market strategies. At the end of the session, Laurie answered audience questions about the role of AI, how buying committees are changing, and what AR professionals can do to help their organizations succeed.  

How can AR professionals use AI, especially agentic AI, in their roles?

Start with secure, ring-fenced AI tools that are approved within your organization, and avoid external large language models (LLMs) that may compromise your IP. AI can help AR leaders: 

  • Synthesize analyst insights into key takeaways executives can act on. 
  • Draft executive guidance aligned to business goals. 
  • Offload repetitive tasks to agentic AI, such as generating AR plans, drafting key messages, or synthesizing analyst feedback. 

Think of AI as both an assistant (helping optimize content) and an agent (able to draft or manage elements of strategy that humans then refine and execute). 

How are buying committees using AI, and how shold vendors align with them?

Buying groups are expanding, and each persona approaches discovery differently. Increasingly, they start with AI-powered chat functions to research solutions. That means vendors must rethink how their content is created and structured. 

It’s no longer just about keywords and SEO. Content must be optimized for prompts, designed to answer the jobs-to-be-done that buyers will type into chat engines. In other words, organizations need to rebuild their content supply chain for an AI-first buyer journey. 

Many companies collect buyer insights but struggle to act on them. How can we ensure insights actually influence executives?

Too often, buyer insights live in a persona document or slide deck that gets shelved. AI can change this by: 

  • Implementing insights in real time through optimized buyer journeys and engagements. 
  • Measuring impact continuously: Using AI to track how journeys are performing and where optimizations are needed. 
  • Speaking the executive’s language: Turning insights into meaningful KPIs that demonstrate business outcomes. 

This helps AR professionals not just share insights but prove their value to leadership. 

Buyers rely on AI, but do they still trust peers and analysts?

Absolutely. AI doesn’t replace the importance of trusted experts and communities.  

Buyers are: 

  • Attending events to learn from peers. 
  • Visiting vendor websites for direct information. 
  • Turning to social communities and networks for validation. 

The takeaway: AR leaders should help their organizations influence across multiple channels: AI, digital platforms, peers, analysts, and social networks.

Learn more

The buyer journey is no longer linear. It’s omnichannel, AI-led, and persona-rich. For AR professionals, that means a new mandate: translate insights into influence across executives, marketing, sales, and peers. 

Christina Cardoza - Content Marketing Manager - IDC

Christina Cardoza is a Content Marketing Manager at IDC, where she specializes in brand content and social media strategy. With a background in journalism and editorial leadership, she has a proven ability to transform complex technology topics into clear, actionable insights.

AI is reshaping the way buyers behave. They move fluidly between digital and in-person channels, research on their own terms, and expect every interaction to feel timely and connected. Today, most buyers prefer digital-first engagement, and they notice when experiences fall short.

Even with strong teams and good intentions, it’s easy to miss the mark. Content lands out of sync. Signals slip by. Event engagement fizzles into fragmented follow-ups. The result? Stalled pipeline and missed opportunity.

That’s where orchestration comes in. To meet buyers where they are, and move at the speed and relevance they expect, sales and marketing teams need more than just campaigns. They need plays: repeatable, proven motions that turn insight into action.

Where should you start? Not every team faces the same roadblocks. Some struggle with nurture streams that stall. Others see event ROI fall flat. Some launches never hit stride. These plays are built to help you zero in on the challenges you’re facing right now and run the motion that will get you unstuck.

5 proven GTM plays to unlock growth

  1. Reignite a stalled nurture stream

When leads go quiet, it’s not the end of the story. It’s a signal. Too often, teams focus on chasing new contacts while overlooking the prospects already in their pipeline. By diagnosing drop-off points and re-personalizing the journey, marketers can convert dormant interest into qualified pipeline.

  1. Align event engagement with digital journeys

Events are high-investment moments, but without thoughtful orchestration, they fade fast. Buyers expect pre-, during-, and post-event interactions to feel connected. This play ensures event attention flows into a broader engagement journey instead of stalling out.

  1. Equip sales with signal-based content activation

Almost half of sales teams say they lack visibility into buyer intent. That leaves them pursuing leads without context. This play bridges the gap by translating signals, like demo requests or pricing page visits, into clear next-best actions. Sales gets the visibility and timing they need to act fast.

  1. Execute an orchestrated GTM launch

Great launches should feel like a single story, not a scatter of tactics. But aligning teams and channels is hard. This play brings marketing, sales, and operations together around a shared plan, message, and cadence so launches hit the market faster and with greater impact.

  1. Orchestrate the fully integrated omnichannel experience

This is where everything comes together.

Instead of relying on one-off tactics, this play builds an always-on GTM system that senses buyer signals, sequences interactions, and adapts across every channel. The result is a connected system that scales with buyers and keeps pipeline flowing

Your next move: Smarter, not bigger

Buyers aren’t waiting. They’re moving fast, guided by signals you might not even see. The good news? You don’t have to chase them. You can meet them there.

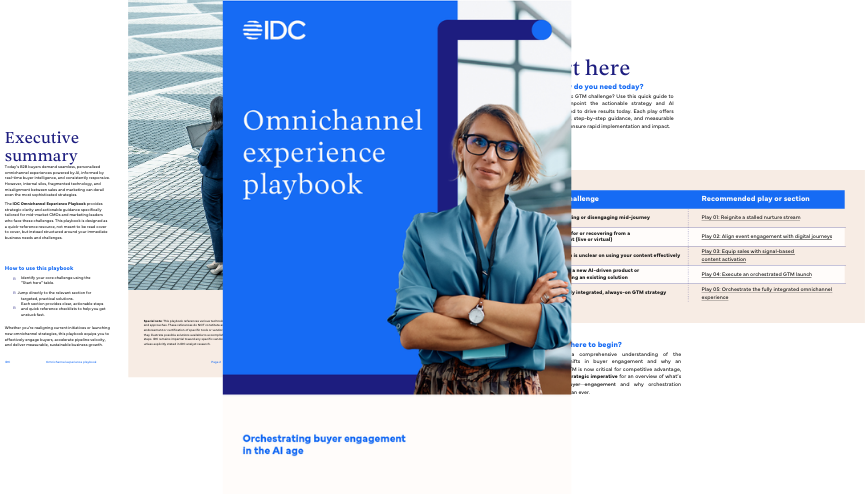
Whether you’re reigniting a stalled nurture, converting event attention into pipeline, or launching your next big solution, IDC’s Omnichannel Experience Playbook gives you the proven plays to move with forward with clarity and confidence.

And when you’re ready to accelerate, the AI Supplemental Guide shows you how to weave intelligence into every step, so your team isn’t just reacting to buyer behavior, but anticipating it, personalizing it, and orchestrating it across every channel.

Ready to move smarter? Download the full Omnichannel Experience Playbook to activate five proven GTM plays. Then explore the AI Supplemental Guide to see how intelligence, personalization, and integration can take every play further, keeping you not just in step with buyers, but one step ahead.

Christina Cardoza - Content Marketing Manager - IDC

Christina Cardoza is a Content Marketing Manager at IDC, where she specializes in brand content and social media strategy. With a background in journalism and editorial leadership, she has a proven ability to transform complex technology topics into clear, actionable insights.

Financial service providers benefit from large global fintechs as well as startups.

The role of fintechs

While the names of the vendors have changed, the impact fintechs have, both large and small, in shaping how we learn, transact and plan our financial journeys has not. 

Today’s customers are looking for many things when it comes to their financial relationships.  First and foremost is that they generally will start their process by doing their research online, whether it’s to compare rates, products, locations or reviews, they want to know the information ahead of time before taking things to the next level. 

Let’s look specifically at the banking industry. Consumers are savvy, and will be loyal if their expectations, both digitally and through employees, is being met.  That often starts right at the point of beginning a new relationship, and the importance of engaging a customer where they are, on any device, with relevant and personalized offers and messages. To do this, often times banks will look towards their core provider, an enterprise platform solution, or specialized vendors to develop solutions.  Large institutions may choose to build their own, but will often augment areas with prebuilt components in order to improve speed to market. 

IDC 2025 FinTech Rankings

IDC Financial Insights has been conducting its IDC FinTech Rankings research for over two decades. The research is a quantitative “state of the industry” measurement for financial services– and fintech-based revenue earned by the top 150 technology firms globally. The financial services industry is made up of banking, insurance, capital markets, and fintech firms that buy hardware, software, and services from third-party IT providers. Two major categories of IT companies are ranked: 

  • IDC FinTech Top 100: Solution providers that derive more than one-third of their revenue from the financial services and fintech industries and across no more than two additional key non-FSI industry verticals 
  • IDC FinTech Enterprise Top 50: Solution providers that support four or more key industries yet have sufficient revenue from the financial services and fintech industries to be ranked 

When one looks at the amount of budget earmarked for technology spend, again in hardware, software and services (not employees), IDC estimates that annually over USD 550 billion is spent by banks, capital market and insurance providers. To put that in perspective, that would make the IT spend by FSI equivalent to being one of the largest 25 in the world by nominal GDP, equivalent in size of the economy of Ireland.  

Finovate Fall themes and messages

As in year’s past, I have had the opportunity to see what the next generation of fintech providers are working on at the Finovate event in New York City. It was great to see so many exciting solutions spanning the banking and wealth management industries. While these fintechs only had a few minutes, seven to be exact, to demonstrate their solution, there were some themes that seemed to resonate with the solutions demonstrated. 

First, the importance of customer experience remains a key component of the demonstrated solutions, but glad to see that the importance of employee experiences has equaled in importance. The reality is that the industry has neglected the solutions supporting our employees, and often times they are being asked to support customers who are using modern technology with outdated interfaces and disparate platforms. Single sign in has been helpful, but there is much that needs to be done. 

Second, and to nobodies surprise is leveraging AI to automate and create efficiencies.  Our research would agree that the primary benefit of AI is to create efficiencies out of inefficient processes, but this does not always necessarily mean that it will automate a process. For example, using AI to begin a fraudulent transaction makes sense to gather as much information as possible, yet we are not ready to have AI actually execute the steps necessary to either disable a card or issue a refund. There still needs to be a human on the loop, whether it is the customer or the bank employee. 

And finally, there were solutions pitched that focused on identify management and improving security, particularly focused on money movement and maintaining compliance with existing and future regulatory requirements.  The idea, which is more refinement than innovation, is to embed fraud prevention within the solution, but ensure that the forensics are available to detect and deter actions by bad actors. 

Marc DeCastro - Research Director - Consumer Banking - IDC

Marc DeCastro is responsible for the consumer banking engagement strategy practice. Mr. DeCastro’s core research coverage includes the complete omni-experience journey for the retail customer, including branch transformation, digital product strategies, and onboarding. Based on his background covering the consumer banking space, Mr. DeCastro’s research also includes a particular emphasis on how consumer trends and habits are forming the next generation products and services that utilize current and emerging technology.

For nearly two decades, search engine optimization (SEO) dictated how brands achieved visibility online.

Ranking high on Google or Bing meant being found, considered, and chosen based on certain criteria. Marketers built entire playbooks around understanding algorithms, shaping content, and winning the top position on the results page.

That world is changing. The rise of generative AI (GenAI) has introduced a new discovery experience. It is one that doesn’t list websites, but delivers answers and tailored recommendations directly to the consumer.

Where SEO once determined rankings, large language models (LLMs) are now shaping which brands appear in conversations and product suggestions. Some models, like Perplexity.ai, make the buyer journey completely seamless from discovery to purchase.

This isn’t a technical adjustment. It’s a strategic reset.

To stay relevant, marketers must learn how to influence the systems consumers increasingly rely on. LLM optimization, a new approach to impacting search results, is quickly becoming marketing’s next imperative.

screenshot of ebook

The shift from “search” to “chat”

IDC forecasts companies will spend up to five times more on LLM optimization than traditional SEO by 2029. This significant budget reallocation signals a broader move from AI experimentation to complete AI integration.

The momentum is clear. In response to ChatGPT’s debut in late 2022, major technology companies have launched (or are developing) their own customer-facing LLMs. Investment is accelerating as well: IDC projects a 59% compound annual growth rate (CAGR) in GenAI spending between 2023 and 2028.

Consumers are moving just as quickly. Over 45% of people now use GenAI weekly, often for personal research and recommendations. The parallels to the early days of search are striking, but this time, implementation is happening in just a few years, not decades.

For CMOs, this means visibility, strategy, and budget will increasingly hinge on how well the brand is represented within LLM systems.

Why SEO alone isn’t enough

SEO was built for a search-first internet. Keywords, backlinks, and metadata drove rankings and reach. But the AI experience era is changing search in ways SEO alone cannot address.

Most major engines now feature enhanced search, where AI-generated summaries appear above traditional rankings. Even the best-optimized content is pushed further down the page. And when customers move directly to platforms like ChatGPT or Perplexity, they bypass ranked results entirely.

In this environment, the familiar metrics of SEO lose influence. A page may be perfectly optimized for keywords yet never shape how an AI model interprets or recommends a brand. Representation is increasingly determined by what the model ingests and prioritizes, not by where content appears in a list.

To remain discoverable, marketers must look beyond search engines. The question isn’t how to rank higher, it’s how to be recognized and represented in AI-powered responses.

Rewriting the rules of visibility

Generative AI has introduced a new standard for digital discoverability. LLMs don’t rank pages; they synthesize responses and recommend options. That means fewer opportunities for discovery, with higher stakes for inclusion.

This new environment is giving rise to practices like Generative Experience Optimization (GEO). GEO focuses on structuring content so it can be ingested and surfaced by generative engines. Research shows it works: brands that apply GEO practices can see up to a 40% increase in visibility within AI-generated responses.

But GEO is only the beginning. It’s a bridge to the broader discipline of LLM optimization: the ability to shape how models interpret, prioritize, and present brands across conversations, shopping experiences, and enterprise tools.

The growing consumer expectation for personalization makes this transition even more important. Customers now frame queries by values and preferences – for example, asking for sustainable brands, locally sourced products, or companies with strong ESG records.

Meeting these demands requires more than SEO tactics. It requires a full LLM optimization strategy to ensure your brand is consistently represented in the answers customers already trust.

Why this matters for marketing leaders

LLM optimization isn’t another channel shift. It’s a new foundation for reach and relevance.

Marketing leaders are under pressure to adapt to the new AI-powered paradigm:

  • Competitive urgency: Early adopters are already experimenting with how to shape generative answers. Just as first movers in SEO once dominated search results, those who adapt quickly will capture an outsized share in LLM-driven recommendations.
  • Customer experience: Generative platforms increasingly guide discovery and decision-making. If your brand is absent or misrepresented in these interactions, you won’t even be on customers’ radar.
  • Brand reputation: Because LLMs synthesize context, any inaccuracies or outdated information about your brand can quickly be amplified, displacing the identity you want to project.
  • Budget challenges: As resources are dedicated toward AI priorities, marketing leaders must demonstrate the value of investing in LLM optimization over long-established tactics.

It’s clear: waiting is not an option for marketing leaders. LLM optimization will determine which brands are consistently elevated in the channels where customers are discovering new products and solutions.

Preparing for the LLM era

As with AI adoption, implementing LLM optimization requires more than experimenting with new tactics It demands a deliberate transition in how marketing organizations approach visibility. IDC has identified three priorities for leaders preparing for this transition:

  1. Audit your brand presence in LLM systems. The way your brand appears in generative search defines the new baseline of representation. If you’re absent from LLM search results, you’ll be invisible to consumers.
  2. Create content optimized for GenAI models. Generative systems reward clarity and authority, not just keywords. The signals that once boosted a page in search rankings aren’t the same ones that will cause a brand to feature in an AI response. You must develop an integrated content strategy primed for ingestion and prioritization within LLMs.
  3. Devote training and resources to GenAI marketing. LLM optimization is not SEO by another name. Additional investment and a fresh mindset are essential to help marketing teams adapt to the new AI-driven content creation standards.

This is just the starting point. Full transformation will require cross-functional alignment, new success metrics, and a commitment to showing up where decisions begin.

The new strategic imperative

The shift from SEO to LLM optimization marks a new era of discovery where AI determines which brands are visible, trusted, and recommended. For marketing leaders, the risk of inaction is invisibility in the very channels where customers go for answers.

The opportunity is clear. Those who prioritize LLM optimization will shape how their brand is represented in an AI-first world, ensuring they have a voice in the conversations that drive decisions. The future of marketing is no longer just about rankings. It’s about investment, leadership, and earning consumers’ trust.

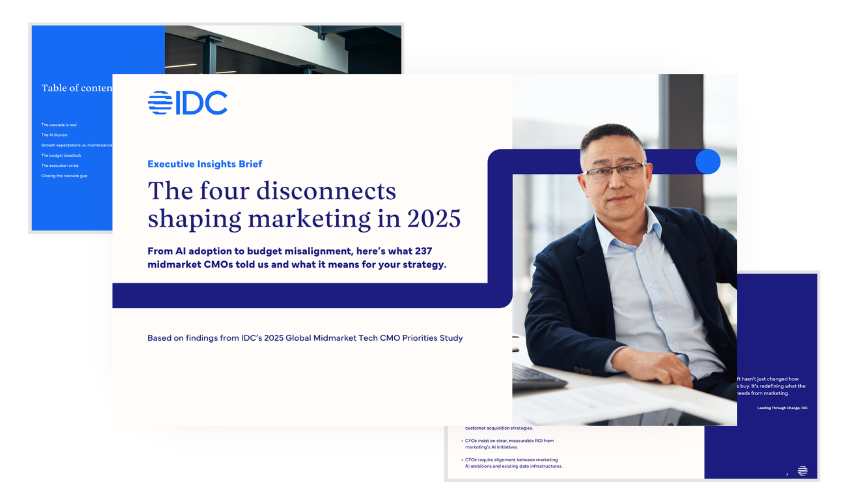
Dive deeper into how to prepare for the future of LLM optimization with IDC’s Four Disconnects Reshaping Marketing Today and Tomorrow. Explore the strategic frameworks, emerging roles, and high-impact actions that will define success in the LLM era.

Apple’s “Awe-Dropping” event this week delivered more than routine updates; it marked a strategic realignment of the company’s hardware portfolio and a deepening of its ecosystem strategy. The new iPhone 17 lineup, including the all-new iPhone Air (starting at $999), addresses competitive pressures, redefines market segments, and further entrenches Apple’s services into customers’ daily lives.

Driving upgrades and shortening cycles

Apple’s 2025 product strategy is simple: increase upgrade rates and shorten replacement cycles. The iPhone 17 Pro redesign and the debut of the iPhone Air introduce distinctive form factors designed to encourage users to upgrade earlier.

This approach aims to sustain iPhone market share, which currently stands at 18% of the global smartphone market and 42% of the global market value as of the first half of 2025, and will likely achieve IDC’s forecast of 4% volume growth this year.

A shift in portfolio strategy: The iPhone Air

The biggest shift revealed was Apple’s discontinuation of its “Plus” model in favor of a new, ultra-thin iPhone Air. This marks a deliberate pivot from segmenting the market by screen size to a more nuanced strategy based on design philosophy and form factor. The goal is to create a new still-premium, but non-Pro tier, fundamentally altering the portfolio’s architecture.

The newly introduced iPhone Air is an ultra-thin model designed to replace the discontinued “Plus” variant. It features a 6.5-inch display, a 48MP Fusion camera system, an A19 Pro chip, eSIM-only support, and a smaller battery that Apple says will still last all day. It weighs 165 grams with a titanium frame and is 2.31mm thinner than the iPhone 17—which also makes it thinner than its direct competitor, the Samsung S25 Edge. This device represents a bet on the market appeal of industrial design.

The strategic positioning of the iPhone Air has a direct parallel with the launch of the MacBook Air in 2008 and the iPad Air in 2013. Like those devices, the iPhone Air trades some specifications for portability and design, targeting consumers who value aesthetics, in-hand comfort, and thinness over maximum camera performance or battery capacity.

With a more durable body, an advanced chip, and most of the iPhone 17’s features, the iPhone Air offers fewer compromises than expected. This product aims to improve sales in the segment between the standard version and the Pro Max version—a segment where the former Plus models were never able to establish themselves as strong performers. Although Plus models accounted for only 5–7% of Apple’s shipments, we expect the Air to contribute well over that given the novelty. The iPhone Air offers similar specs to the standard iPhone 17 but is positioned as a different model and a more desirable kind of premium device, which will help Apple establish a new premium, non-Pro tier that can help grow the overall average selling price, which the Plus version never did.

Although there’s a question mark about how much consumers care about thinner devices, the performance of similar competing products is promising. For example, the Samsung S25 Edge sold over a million units in the first month of sales in Q2 2025 to become the sixth highest-selling smartphone globally in the high-premium ($1,000–$1,600) price segment. This suggests there’s an appetite for thinner devices—or perhaps a desire for a device that stands out from the others—making it a compelling driver for many users to upgrade.

iPhone 17 Pro and Pro Max: Performance and design redefined

For its flagship models, Apple is undertaking a significant re-engineering effort focused on performance, professional-grade imaging, and durability. A key element of this strategy is the material shift for the iPhone 17 Pro and Pro Max. The new lineup moves away from the titanium frames of the previous two generations to a new aluminum unibody.

There are two main reasons for this change: first, thermal management; and second, durability. The new A19 Pro chip with advanced AI capabilities is expected to generate significant heat. This shift from titanium to aluminum is essential for maintaining peak performance during intensive tasks, such as gaming or ProRes video recording. Durability is another important factor. While titanium is stronger, it is also more rigid. Softer aluminum is better at absorbing and dissipating impact energy.

Other factors that went into this strategic decision are design and aesthetics. By using aluminum, Apple gains flexibility in colors and finishes. For example, the new cosmic orange option would not have been possible with titanium. Providing more colors in the lineup also addresses user demands and expands Apple’s user demographics and overall user experience. Finally, switching to aluminum helps Apple scale production and control costs—factors that are increasingly important in today’s volatile economic climate where Pro devices remain in high demand.

The camera system also sees a significant improvement. For the first time, all three rear lenses—Wide, Ultra Wide, and Telephoto—will have 48MP sensors. This upgrade, particularly for the telephoto lens, will enable up to 8x optical zoom in the Pro versions—a substantial leap from the 5x zoom on the iPhone 16 Pro. The front-facing camera is also receiving an upgraded 24MP sensor, a jump from the 12MP sensor of previous generations.

Externally, the new design offers a horizontal camera bar, replacing the traditional square bump. This simple redesign of the cameras will become one of the main motivators for users to upgrade, which will accelerate Apple’s replacement cycle.

Apple increased the price of the iPhone 17 Pro by $100, as it now comes with a minimum of 256GB of storage (compared to 128GB in the iPhone 16 Pro), and maintained the price of the Pro Max model at $1,199—which is noteworthy given the current economic environment impacting the U.S. market.

iPhone 17: Solid, incremental upgrades

The standard iPhone 17 introduces only incremental changes, underscoring Apple’s decision to prioritize its higher-end models. The device retains its $799 price point and includes a 6.3-inch display with upgraded ProMotion capabilities, increased brightness, and improved durability through Ceramic Shield 2 and an anti-reflective coating. Performance gains come via the A19 chip, while the camera system now features a 48MP dual Fusion setup, a new ultra-wide lens with 4x the resolution of its predecessor, and improved front-facing capabilities.

These updates improve usability but stop short of redefining the device. In contrast, Apple has shifted more innovation toward the new iPhone Air and the iPhone 17 Pro line, where design and functionality advances are more pronounced. The result positions the standard iPhone 17 as a modest refresh—solid, but clearly secondary to the company’s premium offerings. Still, the standard iPhone 17 will benefit from a notable upgrade: base storage of 256GB. It will be available later this month.

Apple Watch: Expanding health leadership

Apple’s new smartwatch lineup underscores its push into health diagnostics, durability, and connectivity, further positioning the Watch as both a lifestyle device and an emerging health platform.

Apple Watch Series 11 debuts a thinner, more durable design, efficient 5G, and expanded health monitoring. Hypertension detection, analyzing trends over 30 days, could alert over 1 million users to undiagnosed conditions in year one, according to Apple. Combined with enhanced sleep tracking and 24-hour battery life, it deepens Apple’s stake in preventive health. At $399, it balances premium features with mainstream reach.

Apple Watch SE 3 gains an always-on display, new gestures, sleep apnea detection, and faster charging. At $249, it broadens Apple’s health ecosystem to entry-level buyers, particularly younger and cost-conscious users.

Apple Watch Ultra 3 emphasizes performance and resilience, with Apple’s largest display, new satellite connectivity, and 42-hour battery life. At $799 and built with recycled titanium, it targets outdoor and endurance segments while signaling sustainability.

Apple is advancing wearables into chronic-condition monitoring, a shift that may force rivals to adjust. Samsung must broaden its health capabilities, Google needs to strengthen credibility in clinical use, and Garmin will have to balance its fitness focus with expanding health features.

AirPod Pro 3: Beyond audio

Also announced at the event were the new AirPods Pro 3, representing a bold step toward making earbuds central to Apple’s ecosystem.

Hardware gains include an overhauled acoustic design for deeper bass and a broader soundstage, along with noise cancellation that Apple claims is twice as effective as before. Fit and durability improve with five ear tip sizes and IP57 water resistance. Battery life rises to 8 hours—a 30% increase.

The bigger story is Apple Intelligence. Live Translation is the showcase: real-time, gesture-driven translation between two people wearing AirPods, with ANC lowering background noise to prioritize voices. This could make AirPods more central to travel and cross-border communication.

Apple also expanded its role in health and fitness. A new heart-rate sensor enables tracking across more than 50 exercise types, syncing data into Fitness and third-party platforms. AI coaching arrives via Workout Buddy, indicating a push to make AirPods a more comprehensive wellness companion.

Apple kept the price at $249, with availability later this month. We expect strong holiday-quarter sales, which is a meaningful update.

Apple sets its portfolio up for growth

Apple’s 2025 fall event underscores the company’s ability to reset the narrative at a time when the smartphone market faces headwinds from tariffs, trade frictions, and consumer price sensitivity. By introducing the iPhone Air, Apple is not only filling a gap left by the underperforming Plus series but also signaling a willingness to re-architect its lineup around form factor and design philosophy rather than just screen size. This shift, combined with a substantive redesign of the Pro models and a carefully tiered portfolio, positions Apple to stimulate demand in a slowing market.

The iPhone 17 Pro and Pro Max emphasize Apple’s push into performance, durability, and advanced imaging, while the iPhone 17 delivers a solid refresh at a lower entry point, ensuring the lineup speaks to both premium buyers and more cost-conscious users. The iPhone Air, much like the MacBook Air and iPad Air before it, expands the addressable market by offering a new “premium-but-not-Pro” tier that could resonate with buyers hesitating on $1,100+ devices.

Meanwhile, the Apple Watch lineup strengthens Apple’s role in preventive health monitoring, and AirPods Pro 3 broaden functionality through Apple Intelligence, real-time translation, and fitness tracking. Together, these moves reinforce Apple’s strategy to reignite upgrade cycles and deepen ecosystem loyalty.

Tom Mainelli - Group Vice President - IDC

Tom Mainelli heads the Device & Consumer Research Group, overseeing a wide array of hardware and technology categories that cater to both home and enterprise markets. His team's research spans PCs, tablets, smartphones, wearables, smart home devices, thin clients, displays, and virtual/augmented reality headsets. He also co-manages IDC's supply-side research team, which monitors display and ODM production across various categories. IDC's consumer research, anchored by the Consumer Market Model, employs regular surveys and proprietary models to forecast numerous consumer-focused activities and spending across hardware, software, and services. As Group Vice President, Tom collaborates closely with company representatives, industry contacts, and other IDC analysts to provide comprehensive insights and analysis on a diverse range of commercial and consumer topics. A frequent speaker at public events, he travels extensively, enjoying every opportunity to engage with colleagues and clients worldwide.

Nabila Popal - Sr. Director, Data & Analytics - IDC

Nabila Popal is Senor Director with IDC's Data & Analytics team, specializing in Mobile Phones, PC Monitors and other consumer devices. Ms. Popal is responsible for the global research and quality and timely delivery for her respective technologies, coordinating with regional and worldwide research teams. She continuously engages with global vendors and key market players to discuss the latest industry trends and dynamics. Ms. Popal is also responsible for future product planning and evolution whilst managing client relationships and providing thought leadership and executing custom engagements. She also manages communications with the media and is often published in leading local and international media outlets. Ms. Popal has been with IDC since 2013, and prior to her role with the Worldwide team, she was with IDC MEA, leading the research for Middle East, Africa, and Turkey, based out of Dubai, UAE.

The IDC European Enterprise Communication and Collaboration Survey 2025 reveals increasing market segmentation in the UC space, as customers demand more choice and flexibility. This underlines the need for UC providers to evaluate their strategies and align more closely with evolving market trends. Below are the key findings from the European survey.

Businesses Demand Greater Choice and Flexibility

Most current UC offerings present binary, mutually exclusive choices that lock customers into a single platform. These options fail to address the full spectrum of business requirements, forcing organizations into trade-offs between critical capabilities such as transparency and control versus scalability and flexibility. As a result, many are unable to achieve their desired outcomes to the fullest extent.

A Resurgence of On-Premises Deployments

Cloud solutions provide scalability and eliminate upfront infrastructure costs, but some organizations are reverting to on-premises models to regain greater control and transparency over their IT environments. Regulatory constraints and geopolitical concerns — including the implications of the US Cloud Act — are driving this shift, particularly in sensitive verticals. However, this choice also involves trade-offs, with transparency and control being prioritized over flexibility. But it is not just reverting back to on-premises UCC – 60% across the board have stated that they will replace their existing solutions.

A New Era of Choice in Deployment Models

As customer demand for flexibility increases, the market is seeing greater segmentation and a shift away from traditional “either/or” approaches. Deployment models no longer need to be substitutes for one another. Instead, they can coexist, with each bringing unique, often irreplaceable value. Applications can now be decoupled from the underlying infrastructure, offering a wider range of hosting options across environments. This represents a market inflection point, where customers have more choice and flexibility to adopt solutions that best meet their needs.

Hybrid Deployments Are Becoming the Standard

Two-thirds of European businesses are already using multiple UC solutions across different deployment models to meet diverse requirements. While this hybrid approach enables organizations to capture the strengths of various models, it also introduces challenges — including higher maintenance costs, operational complexity, and integration issues. In the context of AI-driven automation, this creates opportunities for innovation to simplify hybrid environments and reduce complexity.

Strategic Implications for UC Providers

No single vendor can cover all requirements alone. A clear understanding of customer priorities, combined with close ecosystem collaboration, will be critical as the market continues to evolve. IDC’s European UCC research provides the insights needed to help providers align strategies with shifting customer needs.

If you have a question about anything, please fill in this form. 

In today’s digital world, buyers discover, evaluate, and purchase solutions in new ways. To remain competitive, organizations must understand these evolving behaviors and act on them.  

With trusted insights, marketing, sales, and executive leaders can make smarter, faster decisions and reshape their go-to-market strategies. Analyst relations (AR) professionals are uniquely positioned to bridge these insights with influence. In a recent IDC webinar, “Turning Insights into Influence: Leveraging Buyer Behavior Research,” Laurie Buczek, Group VP of Executive Insights and Thought Leadership Services at IDC, shared how AR leaders can guide their organizations through the next wave of change.

AI is reshaping the C-suite

Sixty-three percent of CEOs are already operationalizing AI initiatives.

AI is no longer experimental. It’s strategic, and the shift is starting at the top. IDC research shows AI is accelerating from ad hoc adoption to full-scale transformation:

  • 51% of organizations are in the opportunistic phase of AI adoption.
  • 47% of CEOs rank AI-driven business automation as a top investment priority.
  • 54% see AI as a lever to reinvent business models.

This shift is bigger than technology. AI is influencing how decisions are made across the entire C-suite. That makes it critical for vendors and AR teams to influence beyond IT teams, reaching across business and technical leadership.  

The buyer journey is now AI-first

Sixty-eight percent of the buyer journey is now digital.  

As AI reshapes decision-making at the executive level, it’s also transforming how buyers themselves discover, evaluate, and engage with vendors. IDC research shows: 

  • Application-based searches, like YouTube and Reddit, now surpass traditional internet search for vendor discovery. 
  • 73% of decision makers expect to rely more on AI chatbots in the future. 
  • Among IT buyers, that number rises to 85%. 

The trend is clear: buyers aren’t just digital first. They are becoming AI-first. That means your messaging, content, and influence strategy must be optimized not only for SEO, but for AI prompts, jobs-to-be-done, and discovery tools. 

Marketing’s mandate has changed

These shifting buyer expectations demand new leadership. Marketing, once focused on campaigns and channels, is now being redefined as the orchestrator of the entire journey. IDC research shows CMOs are evolving into Chief Market Officers focused on integrating cross-functional engagement and driving growth. 

This evolution is backed by changing skill demands: 

  • Marketing science and analytics are critical for decision-making. 
  • Creative storytelling remains vital to differentiate and connect. 
  • AI fluency, from prompt engineering to agentic workflows, is becoming a core requirement. 

One CMO summarized the shift well, “Sales has integrated into marketing. The CMO is now the chief commercial officer. We view sales as a channel in the customer’s journey versus a standalone function.” 

Where AR leaders come in

With CMOs stepping into broader commercial roles, AR professionals have a unique opportunity to ensure executives stay aligned with market realities and to turn insights into true influence. 

AR professionals can turn insight into influence by: 

  • Explaining how AI is reshaping customer business models and updating messaging to reflect it. 
  • Mapping the expanded buying committee to avoid missed revenue opportunities. 
  • Rebuilding the content supply chain for a digital, omnichannel, AI-first world. 
  • Helping executives understand that an AI-ready marketing organization is no longer optional. 

Bringing these threads together, the future of buyer engagement is clear: omnichannel, AI-led, and persona-rich. For AR professionals, the mandate is not just to capture insights, but to turn them into influence. 

Christina Cardoza - Content Marketing Manager - IDC

Christina Cardoza is a Content Marketing Manager at IDC, where she specializes in brand content and social media strategy. With a background in journalism and editorial leadership, she has a proven ability to transform complex technology topics into clear, actionable insights.

Artificial Intelligence is entering its most transformative phase yet: The agentic future. In this new era, humans and intelligent systems don’t just interact; they act together with intention, autonomy, and scale. According to IDC’s FutureScape 2026 predictions, organizations in Asia/Pacific are rapidly shifting from AI experimentation to enterprise-wide orchestration—where adoption fuels growth, innovation, and market leadership.​

Why 2026 will be a pivotal year for AI adoption

AI has already moved beyond proof-of-concept. IDC projects that AI-related investments in Asia/Pacific will grow 1.7x faster than overall digital technology spending, creating a $1.6 trillion economic impact by 2027.

By early 2025, AI spending reached $90.3 billion, signaling unprecedented momentum. This acceleration is not just about technology—it’s about competitive advantage.

Key AI adoption trends driving the shift:​

  • Enterprise AI transformation – Companies are integrating AI into core operations to boost productivity, lower costs, and open new revenue streams.​
  • AI-powered customer experience – Personalized, emotionally intelligent interactions are becoming the norm.​

Autonomous systems in business – From supply chains to marketing, autonomous agents are optimizing decisions in real time.​

Opportunities across the AI ecosystem

For technology providers, the agentic future opens massive possibilities:​

  • Infrastructure and cloud providers – Demand is surging for AI-ready platforms and compute resources.​
  • Model and tool developers – Specialized AI models tailored to industry needs are gaining traction.​
  • Consultancies and integrators – Enterprises need guidance on how to implement and scale AI for maximum ROI.​
  • Consumer devices – Tap into where technology providers can serve up new use cases and opportunities in the AI era ​

For enterprise leaders, the biggest gains will come from integrating AI capabilities across departments — not just in isolated use cases.​

Turning predictions into impact

IDC’s predictions for 2026 and beyond are more than industry forecasts—they are a roadmap to revenue. Whether you’re a CIO, CMO, product leader, or technology provider, understanding these trends will help you:​

  • Identify emerging markets before competitors do.​
  • Prioritize high-impact AI investments.​
  • Build an AI adoption strategy that scales.​
charting the agentic future

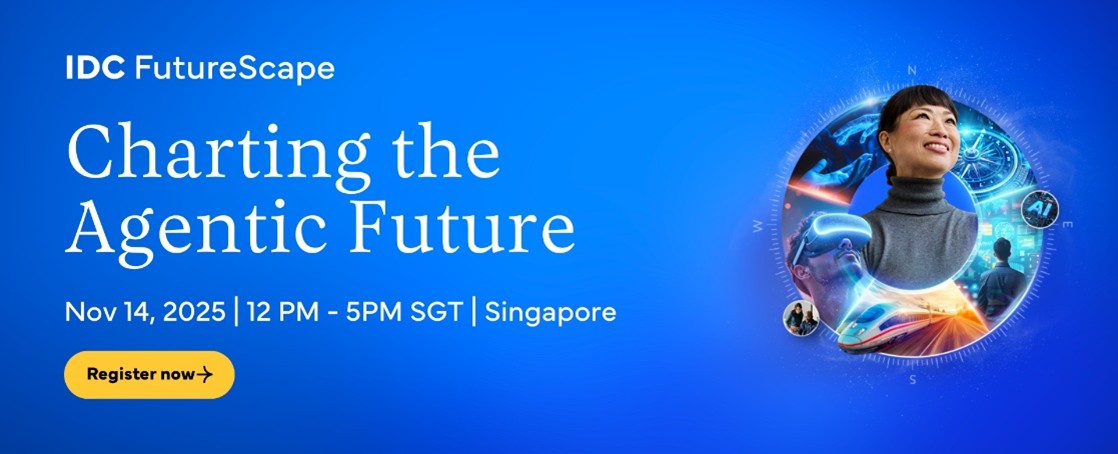
Step into the future ahead of your competition in the Asia/Pacific region. Join us on November 14, 12:00-5:00 PM, and get access to exclusive IDC insights on tech predictions, market forecasts, and direct buyer feedback from IDC’s leading voices on Asia/Pacific technology and innovation:

  • IDC Predictions 2026: Charting the Agentic Future – Sandra Ng, GVP and General Manager for Asia/Pacific Japan Research
  • Everything AI – Dr. Chris Marshall, VP APAC AI and Industry Research
  • Consumers in the AI Era – Bryan Ma, Global and APAC Devices Research
  • Decoupling and Top China B2B/B2C Trends – Zhenshan Zhong, VP China Research
  • Services Disruption in Tech: Thriving in the Age of AI – Linus Lai, VP APAC Services and CEO/CIO Research

Seats are limited so reserve your spot now, register today!

The 2025 Asian Financial Services Congress (AFSC) and Financial Insights Innovation Awards (FIIA) were more than just industry events. They reflected the rapid pace of financial services transformation and spotlighted the technologies and strategies that help institutions respond to constant change.

One truth came out clearly this year: Resilience and innovation are essential for success in 2025 and beyond. At AFSC, financial services leaders explored the emerging technologies and real-world AI use cases that are driving competitive advantage—and discussed how institutions can respond to increasing complexity, from geopolitics to talent shortages.

In adapting to the new landscape, two powerful forces are shaping transformation in 2025:

  • Technology suppliers accelerating innovations, setting benchmarks, and raising the bar for performance.
  • Financial institutions navigating shifting demand, geopolitical pressure, and execution risks.

Staying competitive requires clarity. It’s no longer just about adopting technology—it’s about applying it with precision.

Three strategies to strengthen financial services

These three proven strategies emerged as critical for leaders navigating digital transformation and rising expectations.

  1. Responding to geopolitical risk with five key levers

To stay agile, financial institutions are aligning technology and operating models to address:

  • Technology decoupling and regional sovereignty
  • Intraregional trade and its impact on growth
  • Cybersecurity threats intensified by AI and automation
  • De-dollarization trends in global finance
  • Procurement changes in a shifting supply chain
  1. Closing the financial services skills gap

The challenge isn’t technology, it’s execution. Despite a surge of more than 8 million new STEM graduates in Asia and the release of over 70 new large language models (LLMs) within three years of first launch, many projects failed before delivering value.

To realize ROI, institutions must evolve their workforce. That means reskilling technically trained professionals into financial services experts who can connect innovation to business goals.

  1. Prioritizing high-impact AI use cases

Leaders are no longer experimenting—they’re scaling what works. IDC identified 12 AI use cases delivering measurable value across banking and insurance, including:

  • SME lending automation
  • Customer onboarding optimization
  • Fraud detection
  • Risk modeling and forecasting

Each use case was validated by case studies from top Asian financial institutions, demonstrating operational gains and business impact.

Throughout the event, CXOs and digital transformation leaders reinforced these strategies during expert panels. Technology suppliers brought critical perspective, showcasing how successful AI implementations are creating repeatable models for the industry.

Real use cases. Real results.

Execution matters. The FIIA Awards honored institutions that turned their ideas into action. Ten awards were presented to eight financial institutions, including five full-service banks, one digital-only bank, and two insurers.

Winners were selected based on clear, outcome-oriented criteria:

  • Demonstrated scalability and ROI
  • Customer-centric innovation promoting inclusivity and access
  • Forward-looking initiatives with industry-wide implications.

Congratulations to all the winners for showing how innovation can move from pilot to proof.

What comes next for 2026 onwards

As 2025 enters its final quarter, the direction is clear—financial services institutions must act on proven strategies, invest in execution, and double down on AI use cases that deliver value.

Chart your Agentic AI future! Attend these IDC AI webinar series to dive deeper into the Agentic AI and its use cases:

Ashish Kakar - Research Director - IDC

Dr. Ashish Kakar is research director for IDC Financial Insights in Asia/Pacific. Based in Singapore, he is the lead Financial Insights analyst responsible for all aspects of banking and insurance research. Dr. Ashish's own interest is in fraud and risk, resilience, customer centricity, AI/ML, retail banking, insurance, alternative investment management, cloud and infrastructure, and credit risk management. Prior to joining IDC, Dr. Ashish had over 16 years' experience in Citibank, five years' experience with insurance companies, and has run his own asset management start-up for two years. In his last role in Citibank, Dr. Ashish managed processes across banking technology, servicing operations, and product. He was a regional senior with oversight of the Asia and Europe operations.

Most marketing leaders would agree that driving growth is a critical aspect of their role. But when met with day-to-day realities, growth often takes a back seat. Marketers have to juggle limited budgets, competing demands, and the pressure to show quick wins. This results in marketing efforts that focus on what feels urgent and out of line with what leadership expects.

Forty-one percent of midmarket CMOs say that developing a strategy for new customer acquisition is their CEO’s top expectation over the next 12-18 months. This is according to IDC’s 2025 Global Midmarket Tech CMO Priorities Survey.

Yet many marketing teams remain focused on other outcomes. In fact, 30% say their top priority is increasing revenue from existing customers. Another 29% are focused on reducing costs and streamlining operations.

This isn’t a sign that marketing is off course. It’s a sign that the course itself is more complex. But when executive expectations point one way and internal execution points another, the disconnect can undermine momentum. This is the second of four major disconnects facing marketing teams, as identified by IDC. If left unaddressed, it limits marketing’s ability to deliver measurable business impact at the time it matters most.

nd the first step to achieving true AI-driven growth is breaking through the illusion.

How marketing lost sight of growth

In many ways, this disconnect was inevitable. Over the past few years, CMOs have had to adapt quickly — grappling with new technologies, shifting buyer behavior, and intensifying pressure to do more with less. Along the way, the role itself has fundamentally changed.

Just a few years ago, IDC’s survey data confirmed that most midmarket CMOs didn’t see that change coming. In 2021, 49% of CMOs said they expected no change in their role over the next two years, and only 15% predicted an evolution toward becoming a Chief Market Officer — a title that signals broader responsibility for revenue growth and customer insight. Today, that view has shifted: 33% of CMOs now recognize their role has expanded to include a new title, greater responsibility for understanding the market, and increased accountability for both marketing and sales outcomes.

In short, marketing is no longer responsible solely for generating leads or building awareness. Executives now expect it to directly fuel business growth through acquisition, expansion, and orchestrated, insight-driven customer journeys that span the entire funnel.

Against that backdrop, it’s understandable why many CMOs have leaned into retention and efficiency. In a time of rapid change, focusing on what already works can feel like the safest choice. But when the rest of the business pivots toward bold growth, those instincts can become misaligned. Efforts to protect what’s already working may unintentionally push growth initiatives to the sidelines.

The risks of misalignment

When executive expectations lean into growth while marketing remains focused on retention and efficiency, frustration builds. From the CEO’s perspective, marketing appears out of step. Results are being delivered, just not the ones the business is counting on.

At first, this disconnect can be hard to spot. A strong retention strategy can keep revenue steady in the short term, creating the impression that everything is on track, even as new customer growth begins to stall. Over time, however, the lack of a replenished pipeline becomes impossible to ignore.

The consequences compound quickly:

  • Revenue projections slip as acquisition lags.
  • Cross-functional trust erodes.
  • Strategic credibility suffers.

If this sounds familiar, you’re not alone. Many teams face challenges moving beyond their traditional role at the top of the funnel. Nearly 35% of midmarket CMOs say demonstrating marketing’s strategic impact and ROI beyond lead generation is the top credibility challenge their teams face, according to IDC’s research. Another 25% report difficulty reinforcing marketing’s leadership role in driving business growth across the organization.

Additionally, challenges in measurement deepen the disconnect. While the C-suite continues to prioritize outcome-based KPIs, midmarket CMOs report that these metrics remain the hardest to define and track. Without a clear way to measure and communicate progress toward growth, internal alignment stalls, and confidence from leadership wanes.

Meanwhile, competitors that invest in acquisition today are building relationships that may be difficult to disrupt later. And when pressure to deliver spikes during budget season, board reviews, or sudden pivots in business direction, marketing teams are left scrambling to respond, without the infrastructure or momentum to do so effectively.

This mirrors another key disconnect IDC identified for 2025: the “illusion of AI adoption.” In both cases, surface-level activity is mistaken for strategic progress. A well-run retention strategy may look like success until growth becomes the mandate, and marketing finds itself unprepared to scale.

Recognizing the need for rebalance

This isn’t about choosing between growth, efficiency, or retention. The most effective marketing strategies in 2025 will do it all. But to meet rising expectations from the C-suite, CMOs must rebalance attention, resources, and measurement frameworks toward initiatives that drive net-new business.

That starts with acknowledging the gap:

  • Are your current campaigns designed to reach new audiences?
  • Are acquisition metrics part of your performance benchmarks?
  • Is your team resourced and empowered to prioritize growth?

For many, the honest answer is “not yet.” But that’s not a failure. It’s a starting point. And it signals that now is the time to course correct. The sooner CMOs confront this disconnect, the better positioned they’ll be to respond before it widens.

Realigning for growth

Recognizing the gap is one thing. Closing it takes action.

Retention and efficiency will always matter, but acquisition needs to have a clear place in the strategic plan, with dedicated resources, defined metrics, and visibility across the organization. For many teams, that requires a shift in how priorities are set and how success is measured.

IDC’s Executive Insights Brief: The four disconnects shaping marketing in 2025 outlines specific actions that can help marketing leaders move toward better alignment with growth expectations. These are practical, manageable steps designed to show momentum now and build strategic strength over time.

Ready to bridge the gap between marketing and executive growth goals?
Get the four actionable steps to realign your strategy and strengthen your acquisition efforts today.

Christina Cardoza - Content Marketing Manager - IDC

Christina Cardoza is a Content Marketing Manager at IDC, where she specializes in brand content and social media strategy. With a background in journalism and editorial leadership, she has a proven ability to transform complex technology topics into clear, actionable insights.