
AI now beats search and salespeople as buyers’ top information source.
IDC's 2026 Tech Buyer Behavior Survey found AI is the #1 information source at every stage of the deal. See what it takes to stay visible, what matters most to the people deciding, and how to earn their trust when it counts.
NEW: IDC AI Insights Report
See where your strategy stands in a market that has already moved. Get the latest research on AI buying journeys, credibility standards, and GTM maturity.
What's shaping your work, by the numbers
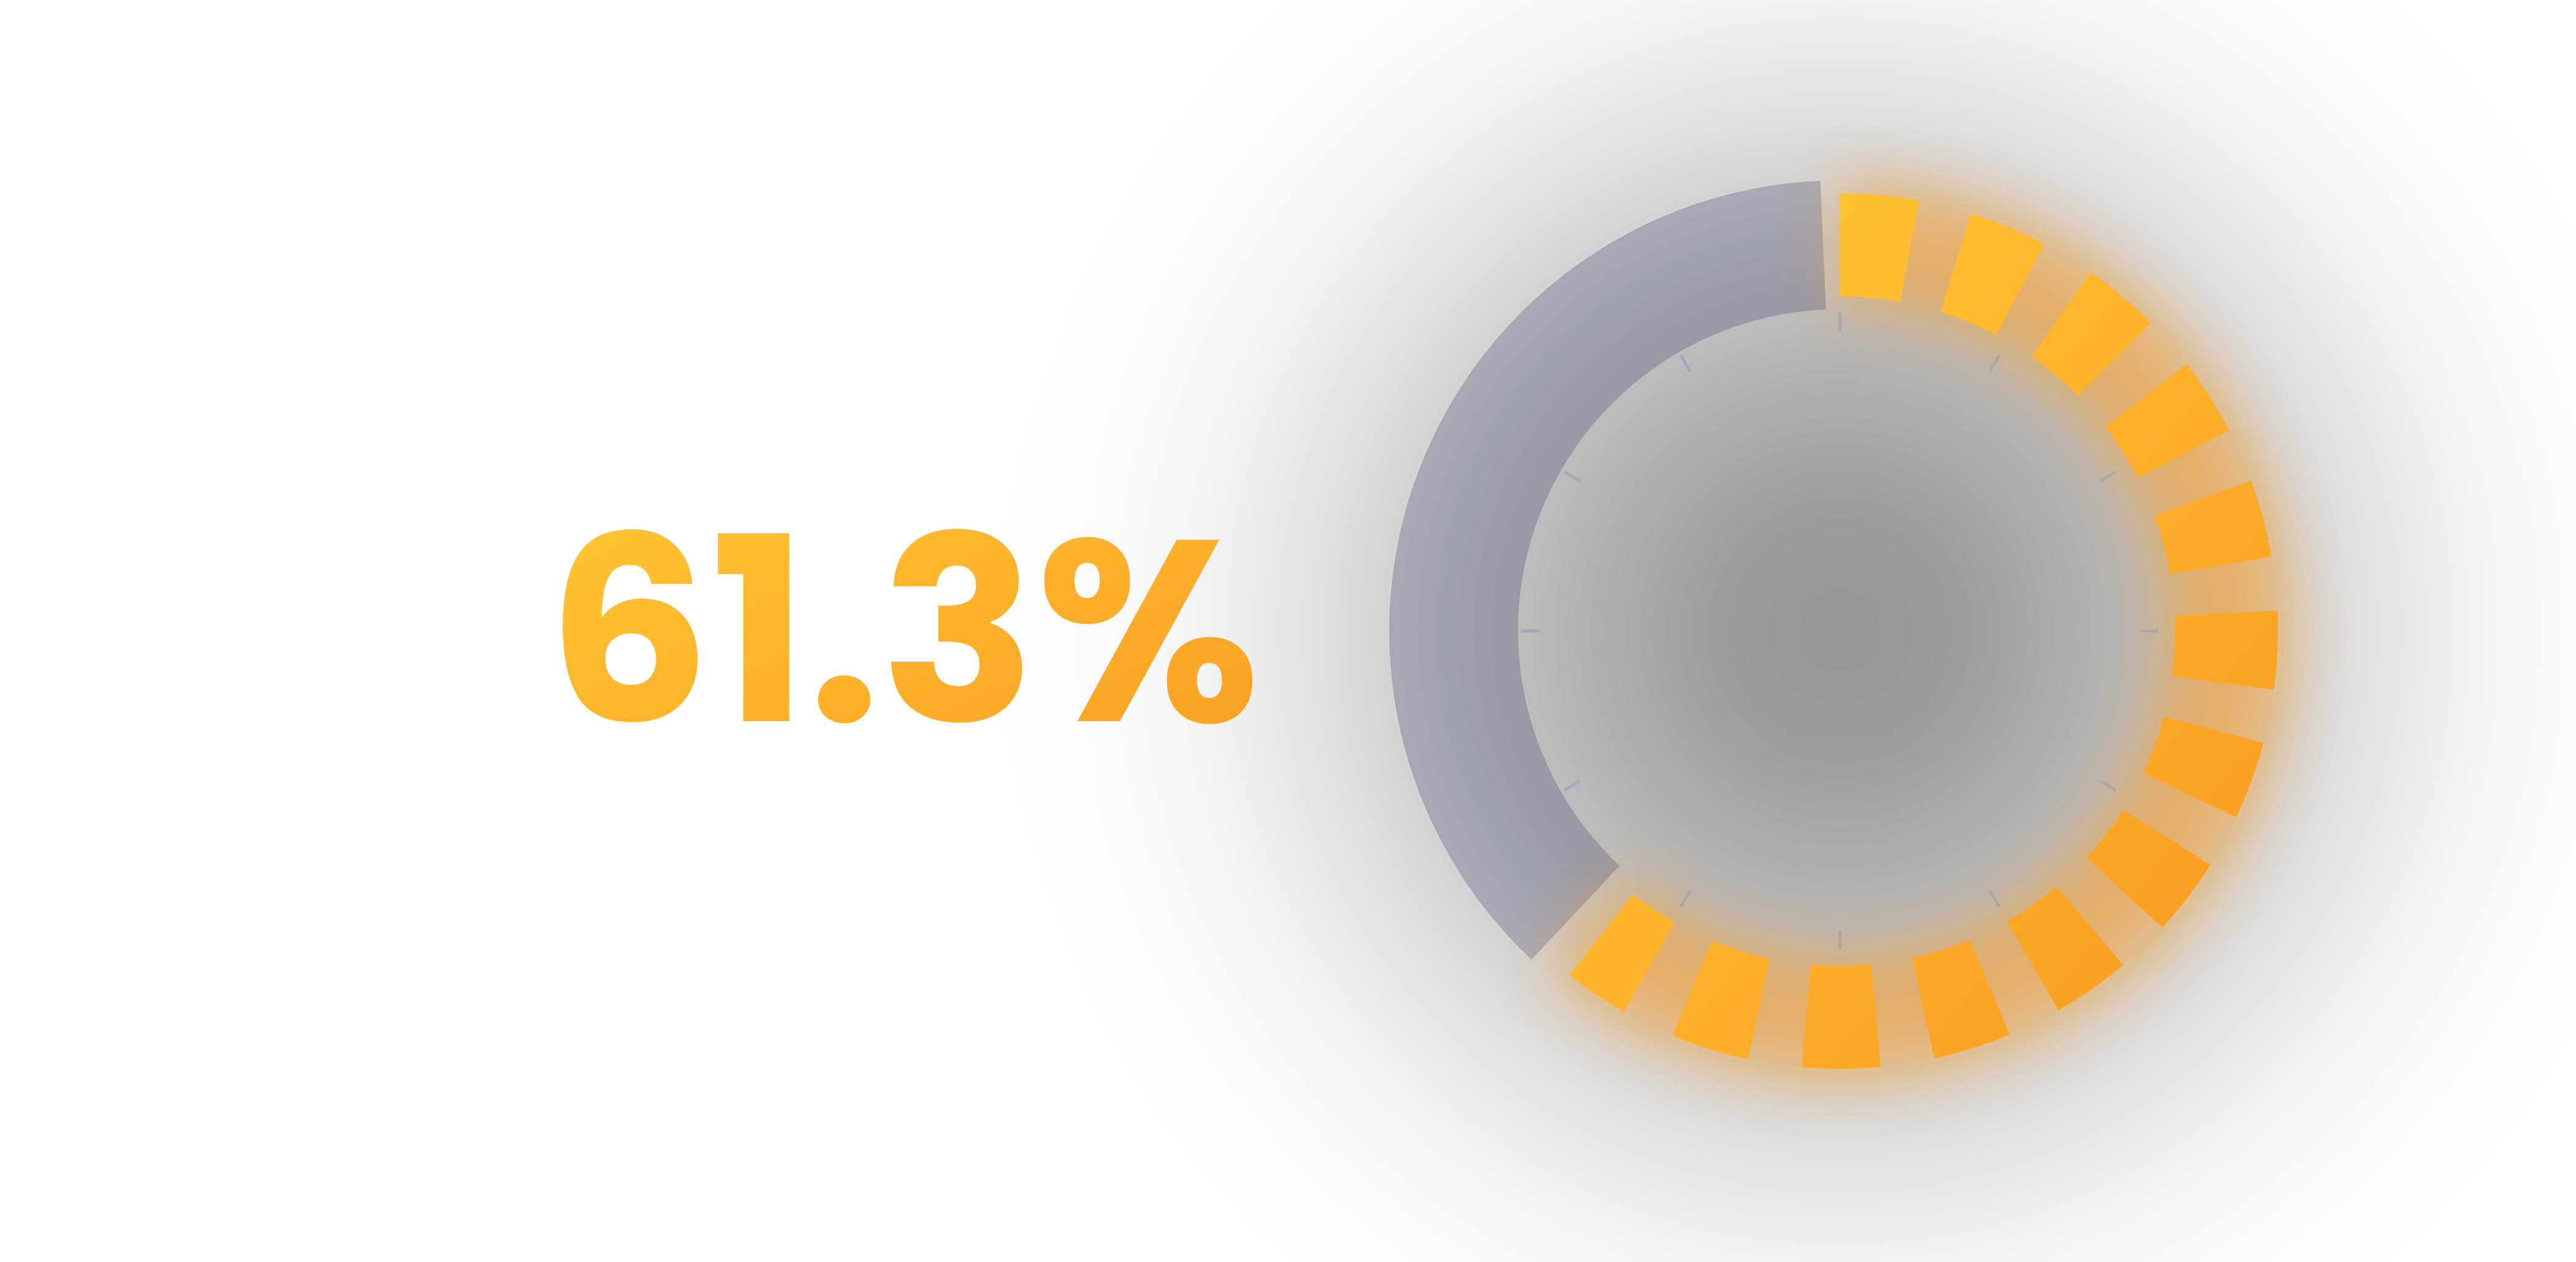
Challenge: 61.3% of orgs call themselves AI-mature, but most can’t back that up under a real benchmark.
Solution: Benchmark your own AI marketing maturity against the same data IDC uses to judge the market.
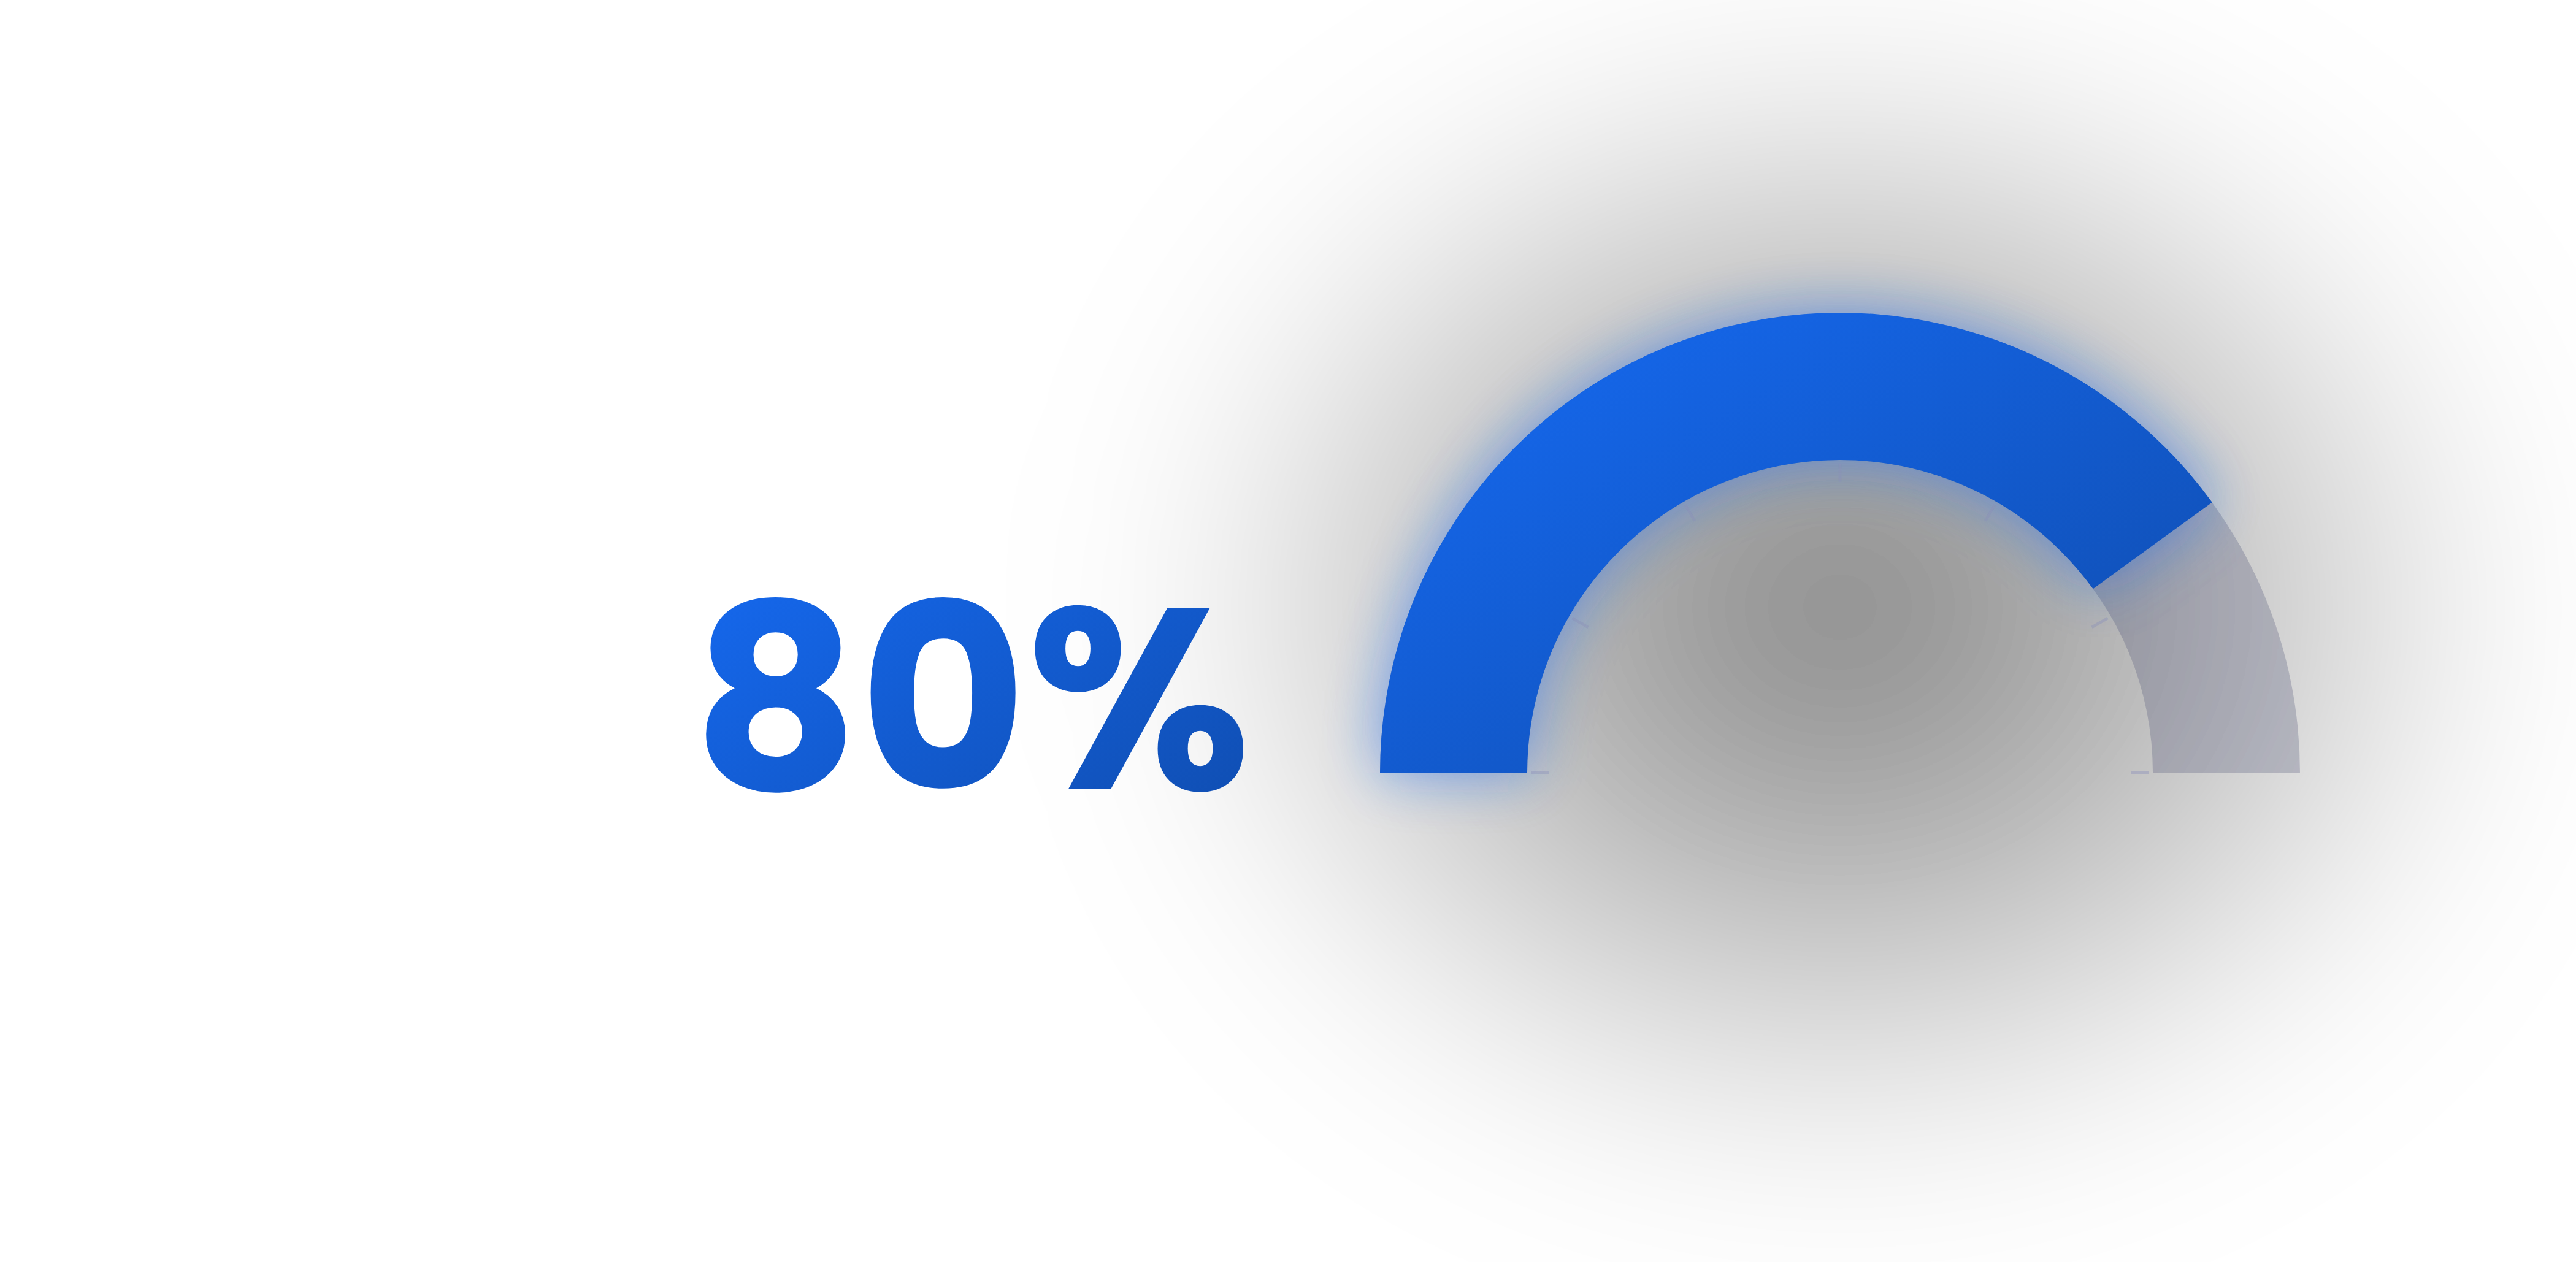
Challenge: 80% of buyers will rely more on AI, less on salespeople, for complex deals, often evaluating you before a rep is ever looped in.
Solution: Arm reps with sourced, defensible account and market intelligence the moment a deal opens.
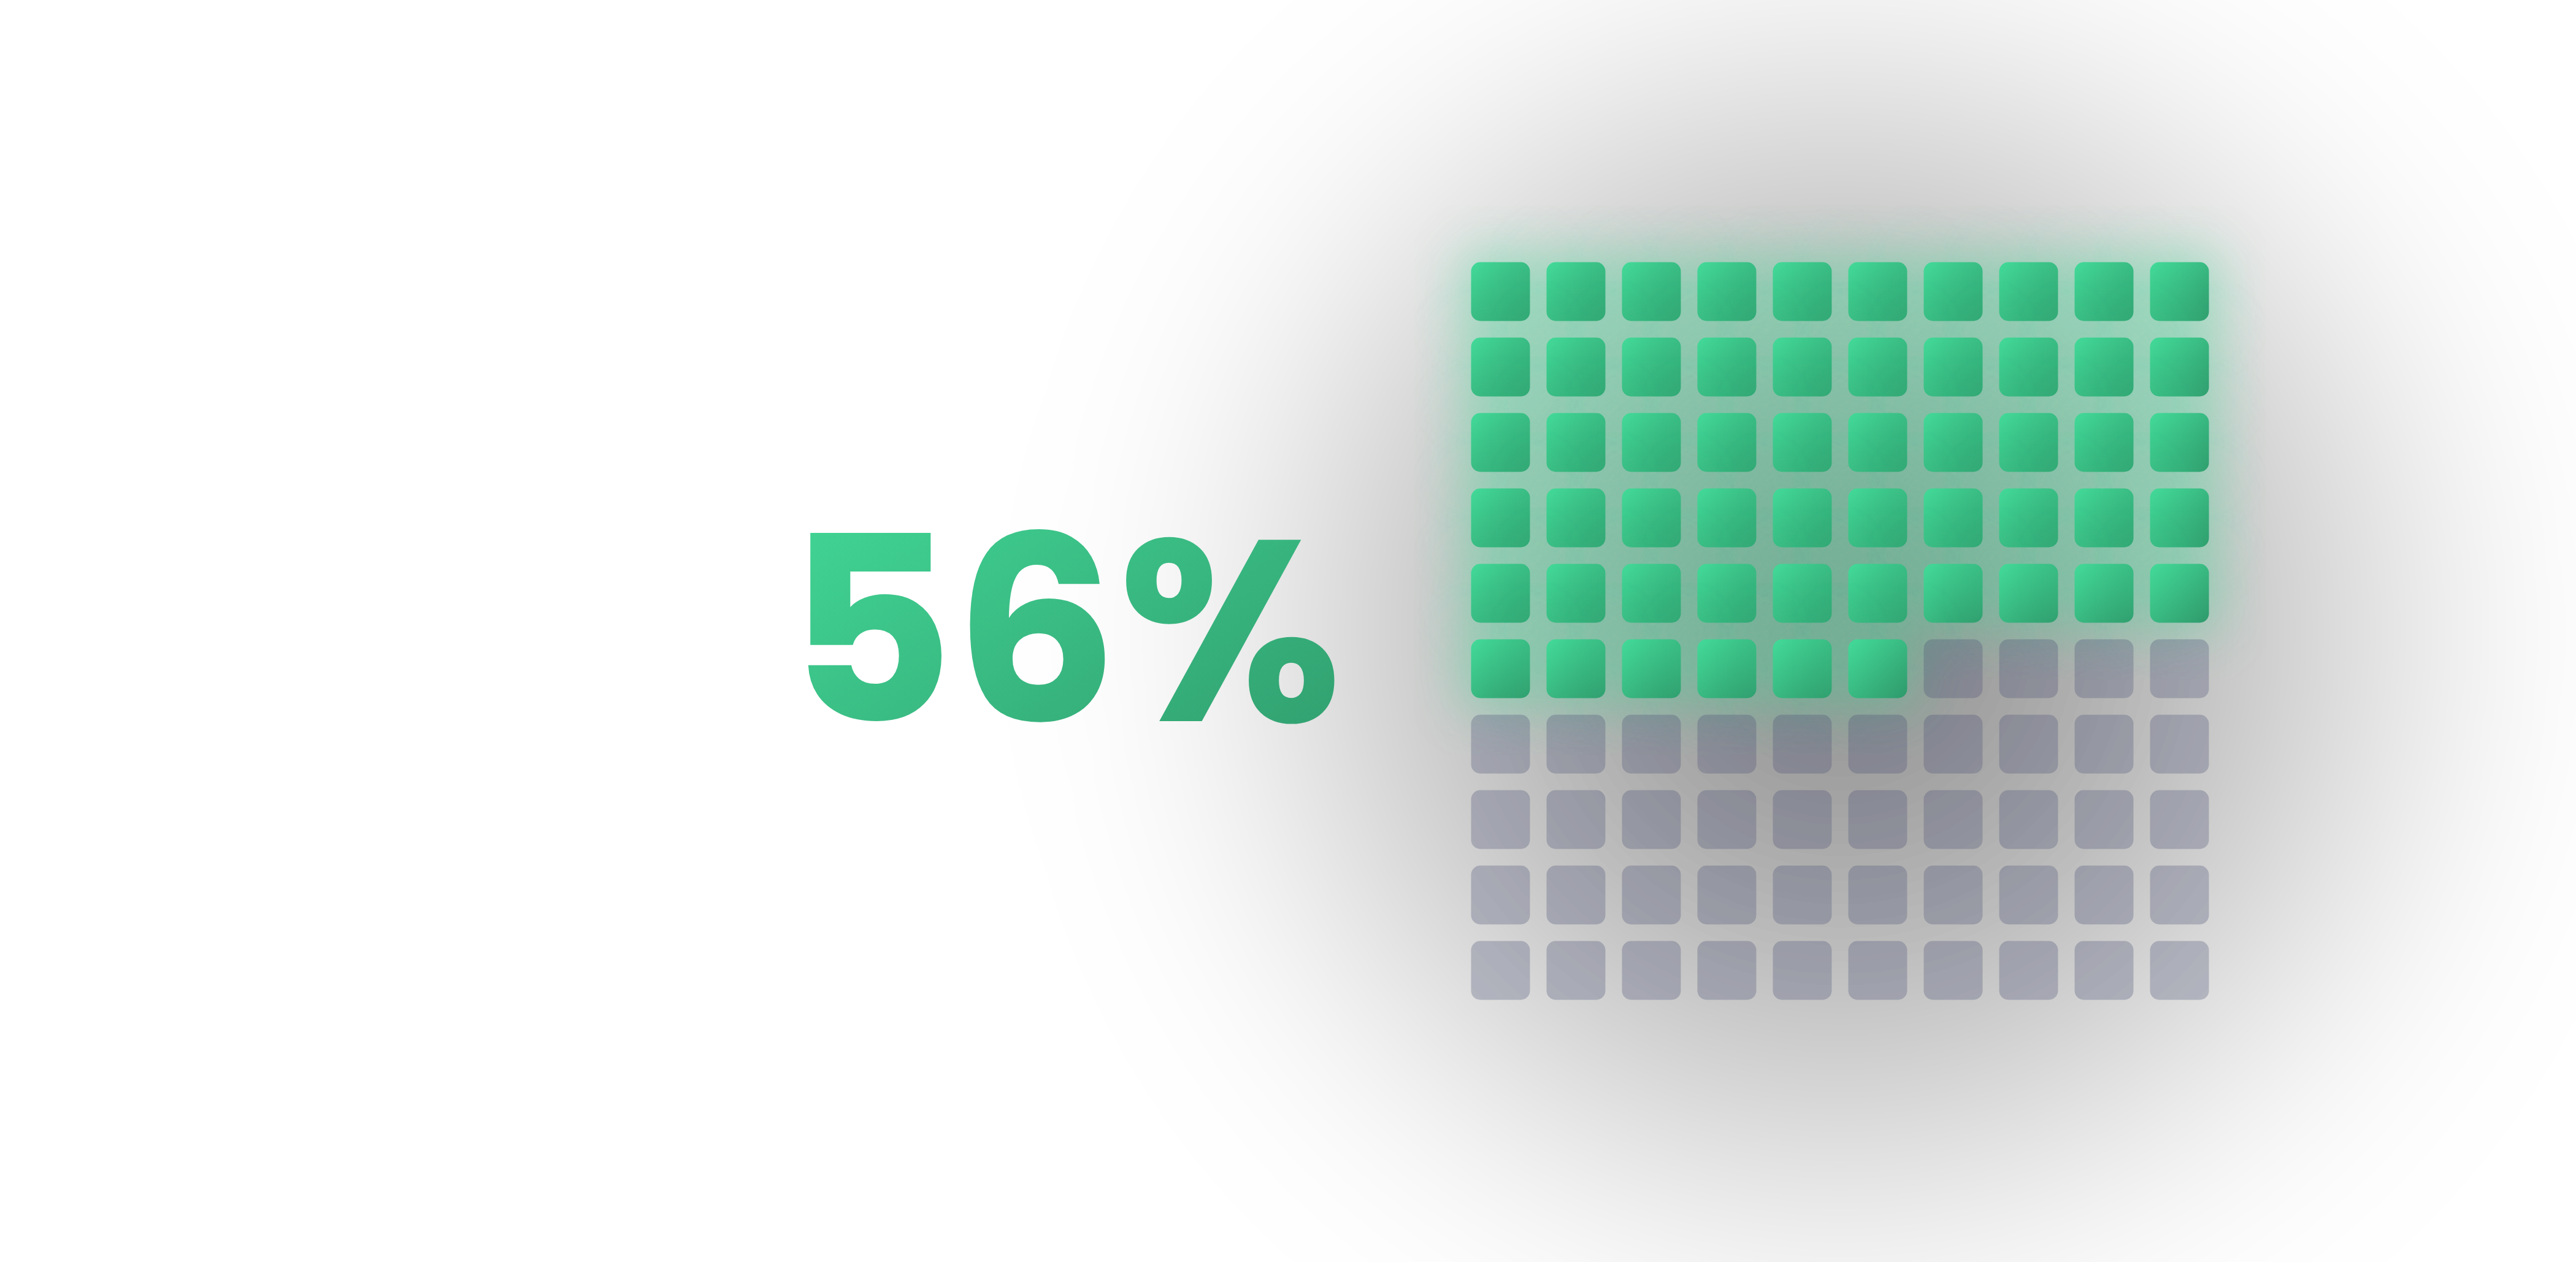
Challenge: 56% of buyers now cite AI tools as their top research source, ahead of analysts themselves, so AR’s evidence has to reach marketing and sales, not just briefing decks.
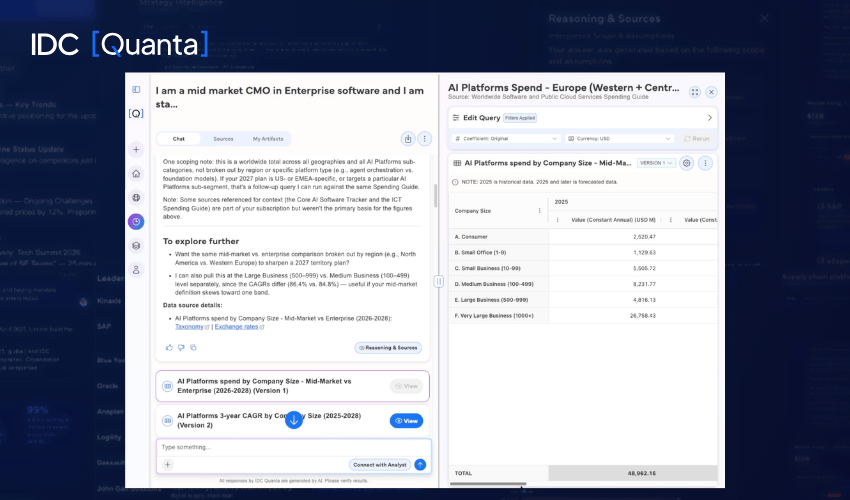
Solution: Turn analyst-grade evidence into something your whole go-to-market team can query and cite.
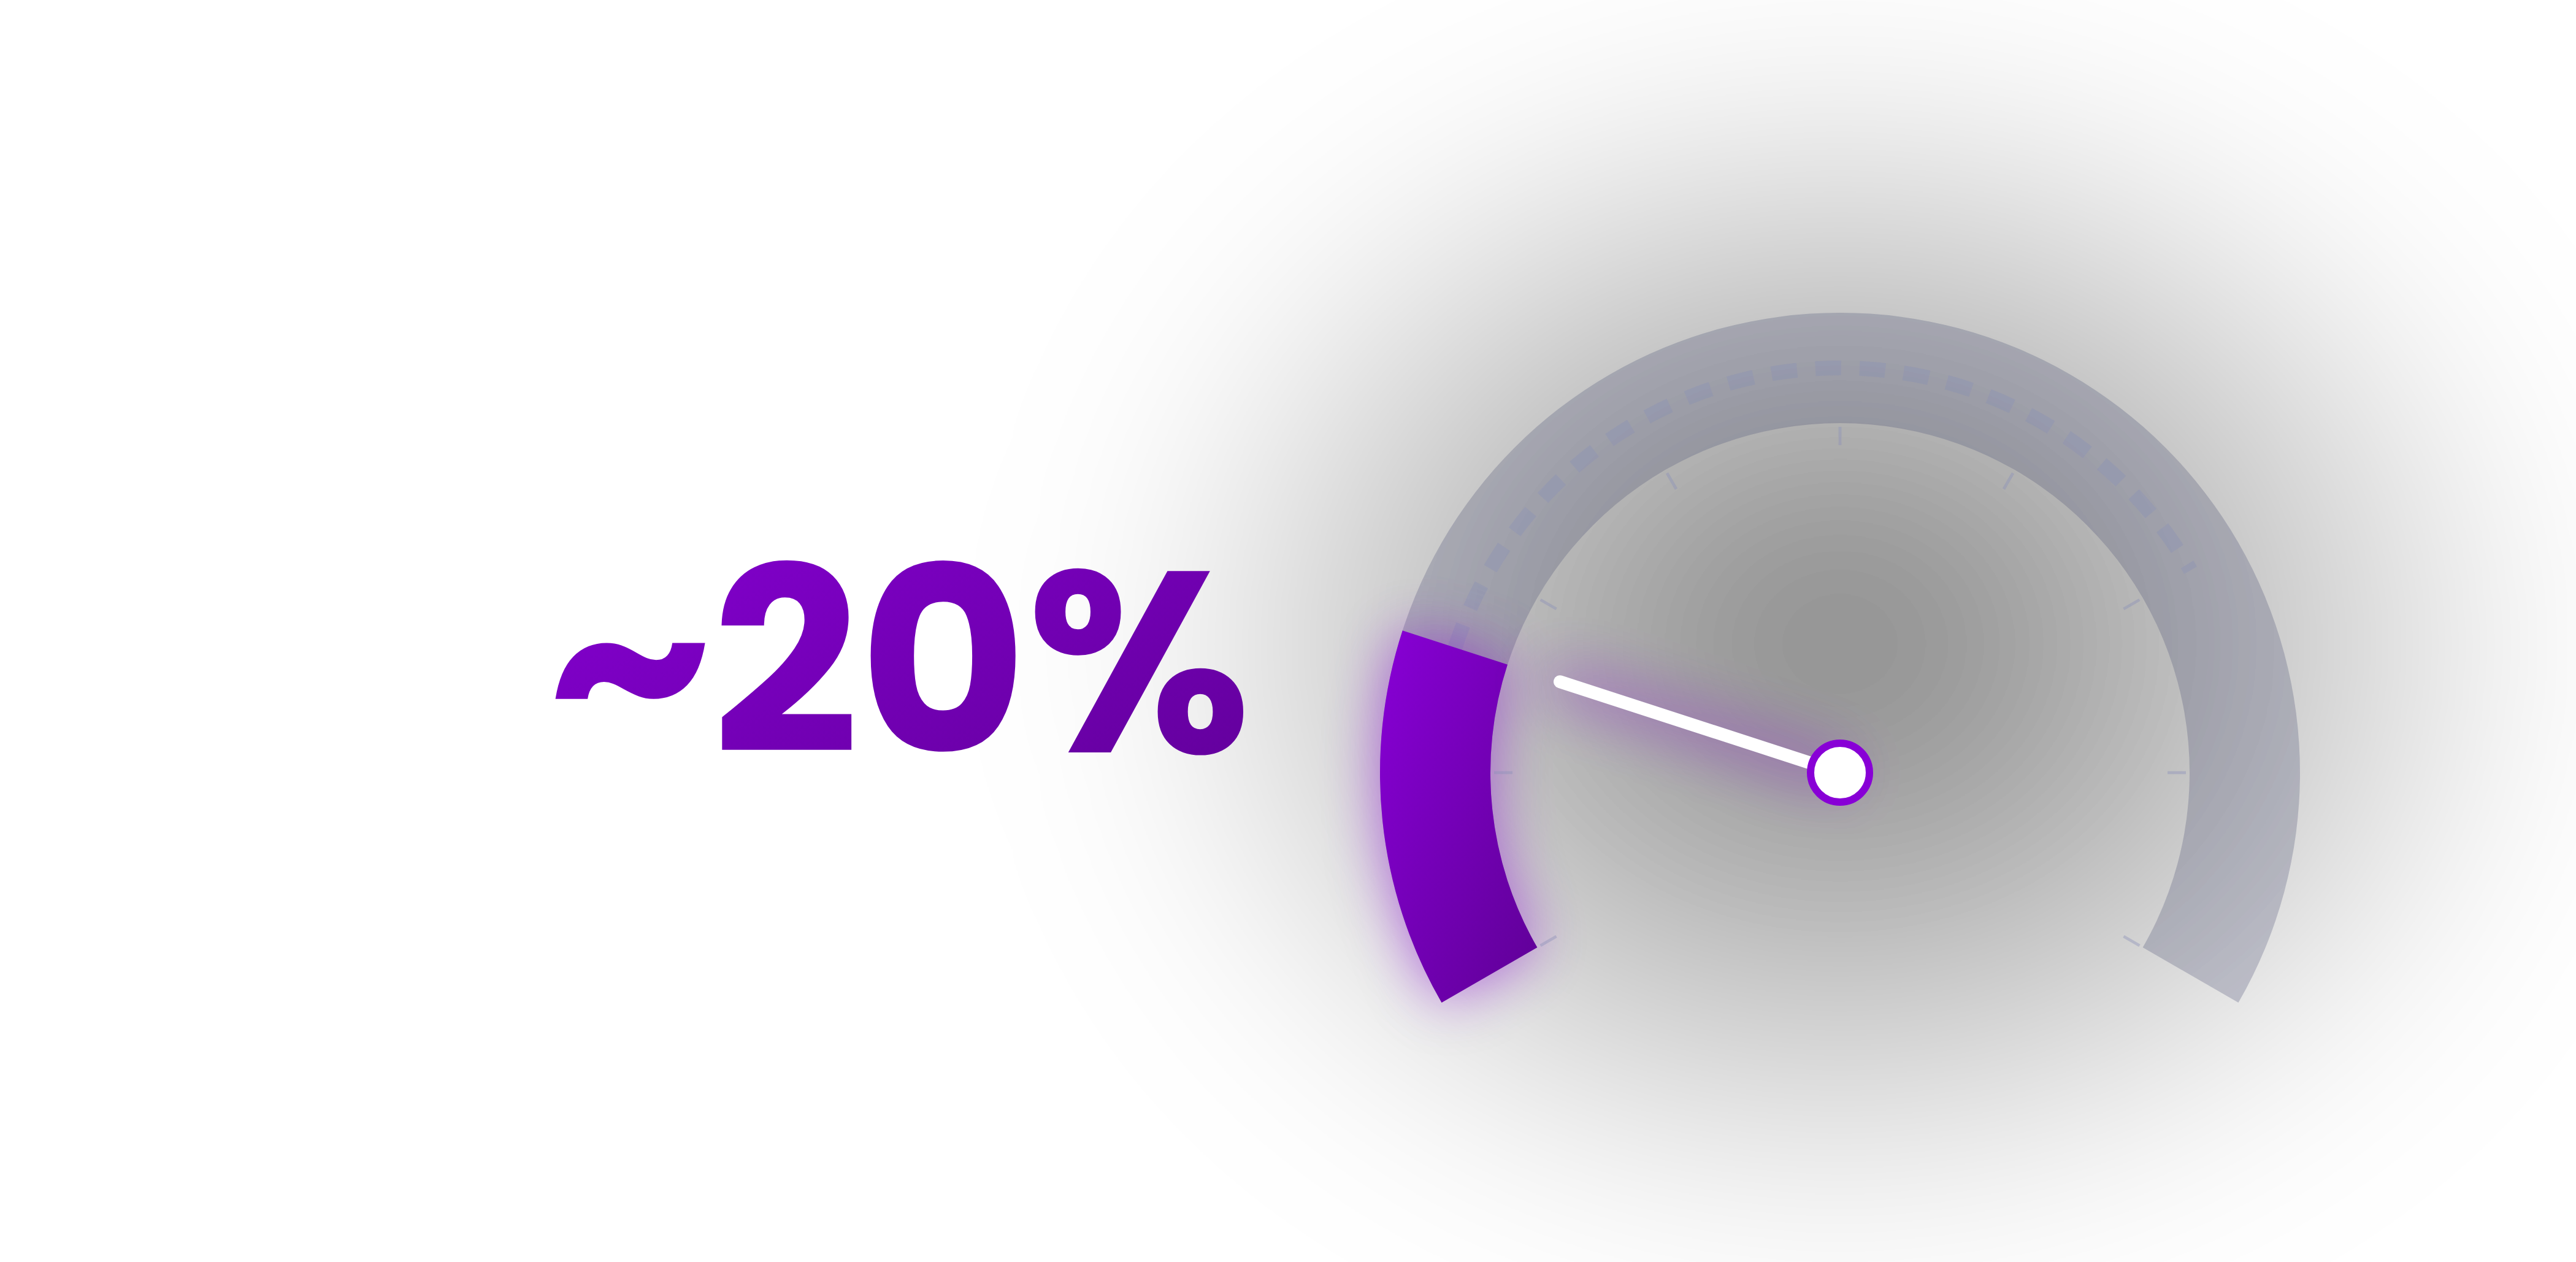
Challenge: Only ~20% of self-declared AI “Thrivers” actually benchmark as mature, so MI teams are increasingly asked to verify leadership claims fast, before they go external.
Solution: Get a queryable layer over 60+ years of IDC research, sourced enough to hand straight to the board, fast enough for same-day requests.
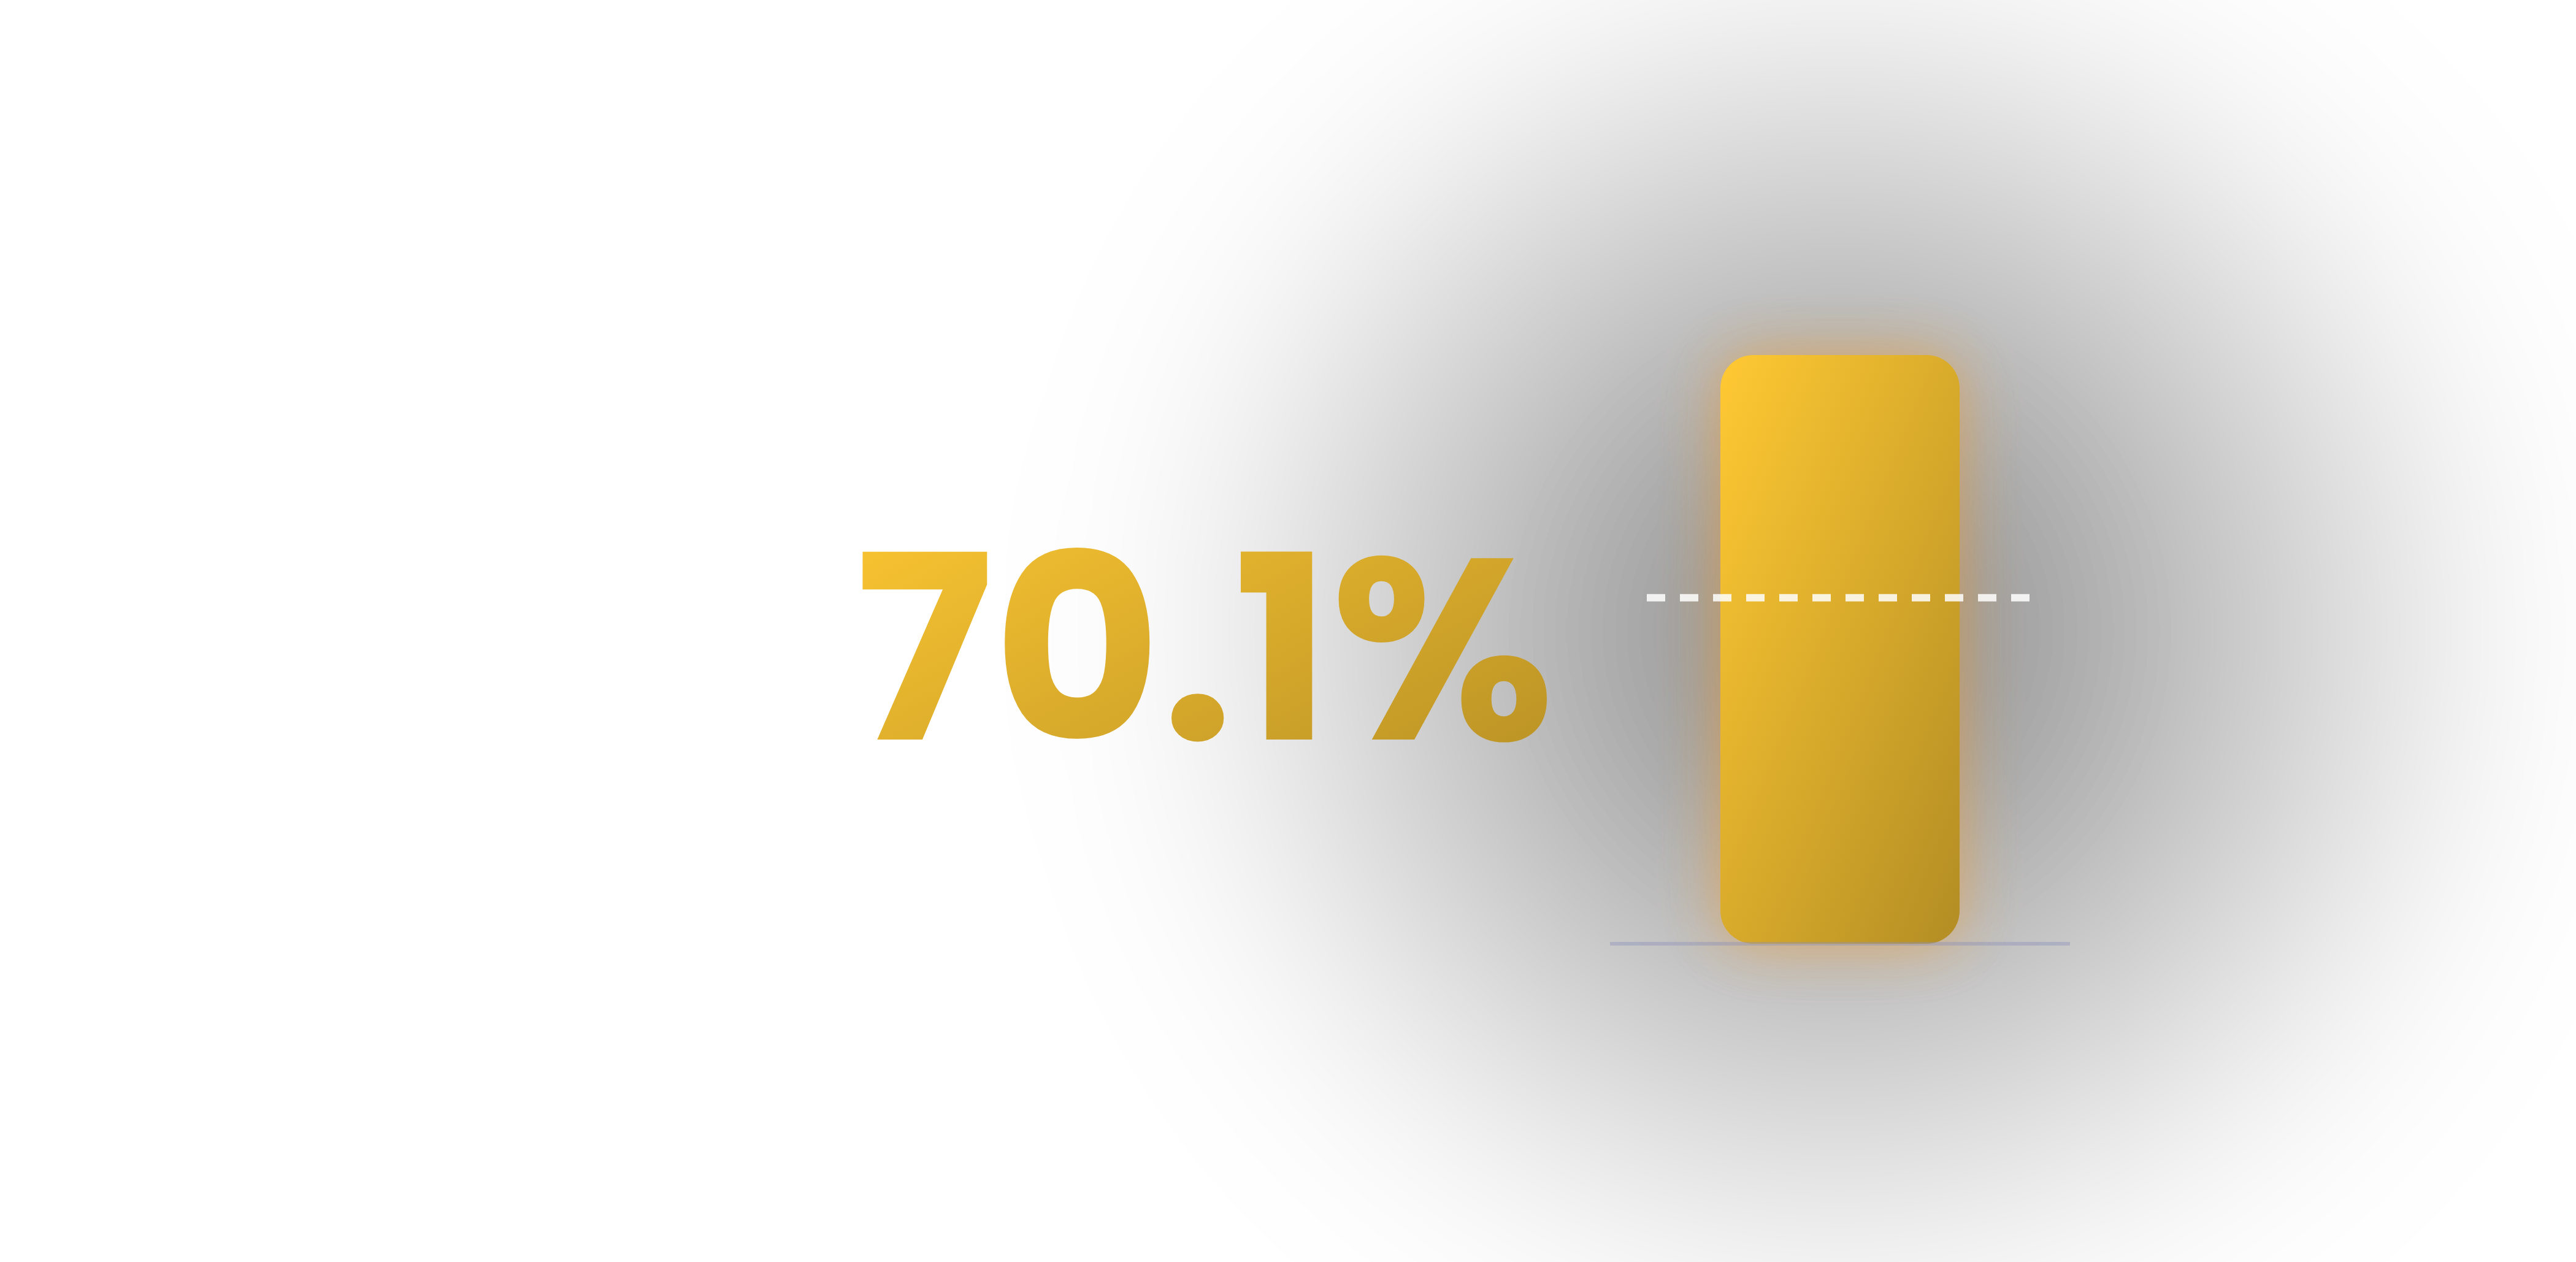
Challenge: Worldwide AI infrastructure spend grew 70.1% in a single year, fast enough to make a plan built on last year’s numbers obsolete before it ships.
Solution: Keep market and competitive forecasts within reach, so your planning horizon doesn’t outlive its own data.
The Intelligence Driving What Happens Next
Governance and outcomes decide who gets shortlisted, not features.
Governance and security top the list at 18%, ahead of measurable outcomes (17%), industry knowledge (14%), ease of doing business (11%), and speed to value (11%).
- Governance/security leads for: CX, sales, operations, HR, finance
- Measurable outcomes leads for: technology, security, marketing, sustainability
If your outbound content still opens with feature comparisons, you’re answering a question your buyer stopped asking.
“The influx of AI across all lines of business has raised the level of scrutiny the C-suite is putting on the governance and security practices of their suppliers.”
— Tony Olvet, Group Vice President, IDC C-Suite Tech Agenda
The AI conversation has moved from “faster” to “different.” Your pitch needs to move with it.
IDC’s FutureScape puts it directly: enterprises now want reinvention, not productivity gains.
- By 2029: Global 2000 orgs measuring AI-human collaboration outcomes will see operating margins up to 15% higher than those still chasing productivity alone.
- By 2030: 30% of service-provider contracts will be outcome-based instead of time-and-materials, driven by agentic AI.
Revenue teams still pricing around headcount or seat count are underwriting a model buyers are actively moving away from.
“As customer choice expands and differentiation becomes harder, this report provides clear guidance on how organizations can stay relevant, deepen engagement, and win by aligning their go-to-market strategies with where technology and customer expectations are headed,”
— Linus Lai, Group Vice President, Services Domain Research
CEOs agree: Proof now outranks pitch.
Buyers rank measurable business outcomes and strong data governance as the top vendor-selection criteria worldwide, in a near-statistical tie (42.3% vs. 42.5%), with speed to value trailing as a distant third and industry expertise last.
- Asia/Pacific: governance and security weigh heaviest, ahead of speed to value, which CEOs here de-prioritize relative to other regions.
- North America: measurable outcomes take the lead, with speed to value and platform consolidation close behind.
- EMEA: priorities are more evenly split, with a more balanced distribution across attributes, including ease of doing business, rather than concentration on one or two criteria.
The evaluation criteria that matters most: buyers want vendors who can prove governance and security discipline and quantify business outcomes.
“The institutions getting the most value aren’t the ones with the flashiest agentic pitch. They’re the ones that stopped treating this as a compliance problem and started treating it as an enterprise and operational risk problem… That requires holding every vendor, not just the ones already ahead, to evidence rather than road map language.”
— Sam Abadir, Research Director, Risk, Financial Crime, and Compliance
From composite AI to agent-first interfaces: where the market is headed by 2029, and what it means for your positioning.
- Now: 70% of Asia/Pacific orgs are adopting composite AI, blending generative, prescriptive, and agentic approaches instead of deploying them in isolation.
- By 2028: 70% of agentic AI use cases will require real-time, contextual data access, pushing most Global 2000 orgs from a gatekeeper to a federated data model.
- By 2029: 45% of IT product and service interactions in the region will use AI agents as the primary interface.
“As AI advancements disrupt markets, CEOs have a choice: either capitalize on this once-in-a-lifetime opportunity by responsibly embracing tech to fuel their business growth or get left behind. Credibility starts at the top, and CEOs must lead by example,”
— Teodora Snoddy, Research Manager, C-Suite Tech Agenda
Two attributes decide vendor trust across the entire C-suite, including CFOs specifically: measurable business outcomes and strong data governance/security
- Outcomes leads for: technology (60%), security (49%), marketing (44%)
- Governance/security leads for: CX (62%), sales (48%), operations (51%), finance (44%), HR (44%)
Neither “ease of doing business” nor “innovative culture” cracks the top two for any function, ranking lowest overall at 11% and 8%. Build proof content around outcome case studies and governance documentation, the two things buyers are actually weighing.
“The digital landscape we are creating has both increased risk and enormous opportunity. In this era of agentic AI and accelerating vendor volatility, resilience depends on anticipating risks, capitalizing on innovations, and responding to changing customer expectations. The next five years will redefine trust not as compliance, but as the ability to prove resilience, secure AI, and turn third-party risk into competitive advantage.”
— Grace Trinidad, Research Director, AI Security and Trust
The foundation for whatever you're building
400,000+ tech leaders surveyed annually
Market intelligence built on real buying intentions, not assumptions, covering technology markets, industries, and buyer behavior most research can’t reach.
15B+ data points, 600K+ companies tracked
Trusted market sizing, competitive benchmarks, and forecast intelligence built for market intelligence, strategy, marketing, and sales teams making high-stakes calls.
1,000+ analysts, 100+ countries
Direct access to the same experts who help IT leaders, executives, and investors make fact-based decisions. Build a TAM, evaluate the competitive landscape, or pressure-test a plan with an expert.
More to explore
-
Blog
The AI Answer Gap
Why fast answers and defensible ones are no longer the same thing
-
Insights Report
AI Inflection Point
New research into AI buying journeys, credibility standards, and GTM maturity
-
Customer Story
Insight at Speed
How Kyndryl delivers validated market intelligence at the speed decisions happen


GET STARTED
Plan your next move, and defend it.
Get a custom walkthrough of IDC Quanta, built around your buyers, market, and top priorities.