Headlines about Europe’s economy rarely mention technology budgets, yet that is where buyers make some of their clearest choices. IDC’s Future Enterprise Resiliency and Spending (FERS) surveys show that 64% of Western European IT leaders expect a recession within the next 12 months, and tariff-driven IT cost inflation ranks among their top concerns. Only 41% expect 2026 growth to beat forecasts, compared with 58% of leaders worldwide. There’s one notable exception: AI; in fact, AI projects are the area most protected from budget cuts, and around 64% of European IT leaders have raised their AI budgets.

Our upcoming webcast will discuss these pressure points with a strategic framework: the triangle of innovation. Value for money of innovation is realized at the intersection of three variables that IT and business leaders can make decisions on:

  • Resources – Who pays, builds, and runs AI: budget ownership, partner types, skills, and the reasons projects fail.
  • Speed – How quickly organizations move from pilot to production: use of AI, GenAI, agentic AI, and physical AI, and how often projects stall.
  • Strategic control – How much autonomy buyers keep or give up: sovereign AI, the trade-offs they accept, human oversight, and governance at scale.
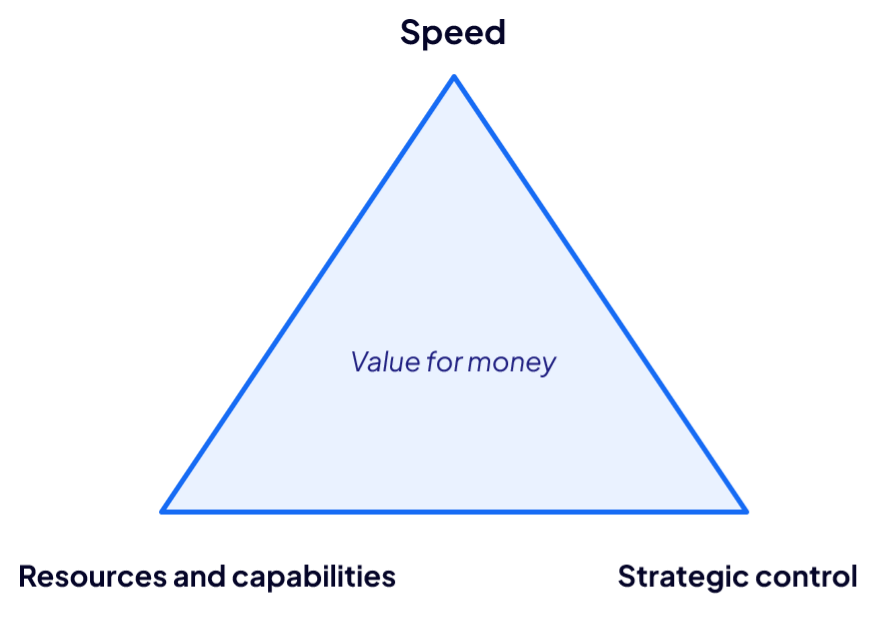
With infinite resources, one could maximize speed and strategic control; in reality, no organization maximizes all three, so every decision make needs to make practical trade-offs. IDC’s 2026 AI Business Trends Survey of 673 EMEA organizations shows that those decisions differ from one industry to the next.

Start with resources. Across EMEA, 59% of organizations had an AI project discontinued, missed, or cut back in the past 24 months, and poor data quality or integration was the most common cause at 38%. Each industry then has its own pain point. Among financial services firms, 41% say the return on investment fell short. Among manufacturers, 48% point to data quality. In energy and utilities, 44% cite low user adoption.

Speed shows the same variety. Manufacturing leads on physical AI[1], meaning AI that directs machines, robots, and sensors, with 33% of manufacturers already running it in production against 24% across EMEA.  At IMTS in September 2026, that shift was easy to see on the show floor. In one demo, fleets of robots were connected and coordinated through a shared software layer instead of being run one by one, which is what turns separate machines into a system. In another, a small cell was building drones, with robots, tooling, and software working as one flexible unit rather than a fixed line. In both, the constraint was less than the machines than the data and software connecting them. Retail faces the same speed question from the customer side: AI moves forward when it improves a personalization, loyalty, or fulfillment metric. Retailers define success in terms of customer-centric outcomes and need to manage risks in terms of customer data protection[2].

Control is where Europe’s priorities stand out. Some 58% of EMEA organizations use sovereign AI, which keeps data, models, and operations under local legal and operational control, for all or critical workflows. Yet only 33% say they could govern hundreds of AI agents with today’s tooling. Governments are the most cautious. In IDC’s July 2026 survey of 69% of national civilian government agencies globally said generative and agentic AI touch 30% or less of their mission-specific tasks, and only 10% automate more than 40%[3]. The trade-offs buyers accept also vary. Manufacturers (41%) and governments (40%) are the most willing to rely on regional or specialist providers to gain sovereignty, while 32% of retailers would pay higher prices for it. Buyer organizations do not accept limited access to innovative capabilities as a trade-off for more sovereign control; at the very least, they demand transparency about when innovative features will become available in more restricted environments.

Technology suppliers that want to differentiate should consider six moves across the triangle. On resources, deliver through integrators and local partners, because European buyers rely on service providers to build and run agents more than their peers worldwide, and start to build packages that align pricing with business success criteria. On speed, help customers fix the data and infrastructure readiness first, so that pilots can be turned into production systems at scale. On control, make governance a product feature, with approval steps, audit trails, and easy override, and offer a choice of sovereign controls across the five layers of the AI stack: Hardware; Infrastructure Operations; Data Management; Implementation & Delivery (encompassing training data sourcing/model development/monitoring & evaluation/ deployment & inferencing); and Ecosystem-delivered AI Assets & Capabilities[4].

In 2027 European demand for AI is holding up while tolerance for ungoverned AI is falling. Join the webcast to see the industry-by-industry data. Register here.


[1] https://my.idc.com/getdoc.jsp?containerId=US54976226

[2] https://my.idc.com/getdoc.jsp?containerId=US54982726

[3] https://my.idc.com/getdoc.jsp?containerId=US54991526

[4] https://my.idc.com/getdoc.jsp?containerId=EUR153902925

Massimiliano Claps

Massimiliano Claps - Research Director

Massimiliano (Max) Claps is the research director for the Worldwide National Government Platforms and Technologies research in IDC's Government Insights practice. In this role, Max provides research and advisory services to technology suppliers and national civilian government senior leaders in…
Gunjan Bassi

Gunjan Bassi - Research Manager

Gunjan Bassi has more than 14 years' experience working in the logistics and transportation sector. Before joining IDC, she worked with Transport Intelligence (Ti), a transportation and logistics research firm based in Bath, England, where she was responsible for vertical…
Ornella Urso

Ornella Urso - Research Director, IDC Retail Insights

Ornella Urso is Head of IDC's Retail Insights team and leads the Customer Experience research group in Europe. Urso conducts market research, industry analysis, and proactively contributes to the definition of thought-leadership at the intersection of businesses priorities and technology…

Application, platform, infrastructure and services each follow their own dynamics. IDC analysts Ewa Zborowska and Carla Arend explain where European demand is heading and how vendors can position for it.

Europe’s AI market is worth $105 billion, and customers are busy building their own AI stack, layer by layer, reshaping each one as they go. For vendors, the interesting question is not whether this market will grow, but where exactly the money is heading in the AI stack and how to position for it.

That was the topic of a recent webinar, where Ewa Zborowska and Carla Arend looked at AI deployments in the cloud versus on-premises, which AI platforms are winning and why, how the application layer is being reshaped, and whether AI sovereignty is realistic.

AI Application Layer: Embedded AI and Outcome-Based Selling

AI adoption has moved well past the pilot stage, and the application layer is changing first. Customers increasingly want AI as a feature of the software they already own rather than as a standalone product, alongside targeted investments in specific use cases. As buyers struggle to prove the return on AI, vendors will need to sell the outcome rather than the model, and embed AI features in the workflows customers already run.

AI Platforms and Agentic Architectures: The Fastest-Growing Layer

The fastest-growing part of the stack sits one layer below, in AI platforms and developer tooling. This layer decides which models, data and guardrails an enterprise can use at all, and it is being transformed by agentic architectures, where multi-component builds replace single-model integrations. The vendors who land the agentic build early have the chance to own the runtime, and to hold on to it through data gravity and governance. Customers will not settle on a single platform, which makes that early position even more valuable.

AI Infrastructure and Sovereignty: Cloud, On-Premises or Both?

Infrastructure tells a different story from the one many expect. In addition to the constraint imposed by raw GPU supply shortages, locality and energy supply increasingly play a role, so the title question has a clear answer: AI will not live in the public cloud alone. Customers will choose a mix of deployments that reflects where their data must sit and what power is available. Vendors competing here will do better selling sovereign capacity and efficiency than selling price per unit of compute. Sovereignty itself is turning from a debate into a deployment, yet there is still no single definition of it. Vendors may label AI as sovereign, but it is the customers who decide what that actually requires, and we will look at what that means for cloud providers, telcos and anyone selling into sovereign requirements.

AI Services: Getting Customers from Pilot to Production

Running across every layer are services, because few buyers get from pilot to production alone, and that is exactly where adoption tends to stall. Automation is also resetting expectations, with buyers now looking for the same work faster and cheaper. Services providers who lead with fast, automated delivery, price on outcomes and SLAs, and keep customers through governance and managed AI operations will be best placed.

What This Means for Vendors in the European AI Market

Across all of this there is opportunity at every layer, and every layer has its own dynamics. Vendors who understand those dynamics will be much better placed to grow.

If you missed our recent webinar The European AI Stack, the on-demand recording takes you through every layer in detail, including what AI sovereignty means for cloud providers and telcos. Watch it at any time here.

For your go-to-market planning, our new IDC playbook tests six common assumptions about the European AI market, from market size to buyer behaviour, against European data and sets out what to do differently. Download the eBook here.

Carla Arend

Carla Arend - Associate Vice President, Cloud and Datacenters, Enterprise Infrastructure

Carla Arend is Associate Vice President within IDC’s enterprise infrastructure global research domain and part of the cloud and datacenters services subdomain. She leads IDC’s Worldwide cloud adoption research. In this capacity, she leads a team of analysts that provides…
Ewa Zborowska

Ewa Zborowska - Research Director, AI, Europe

Ewa Zborowska is an experienced technology professional with 25 years of expertise in the European IT industry. Since 2003, she has been a member of the IDC team, based in Warsaw, researching IT services markets. In 2018, she joined the…

A couple of months ago I was at Siemens Realize LIVE in Amsterdam, and over dinner at the media and analyst reception, a conversation with Tony Hemmelgarn, CEO of Siemens Digital Industries, took a turn I did not expect. From industrial AI to why a Delhi intersection, and a UK roundabout arrive at the same result through completely opposite means.

Somewhere in there the UK driving exam came up too (that thing is brutal!). Tony had lived in the UK for a while himself, so he knew exactly what that experience is like. Stay with me, it made more sense than it sounds.

I grew up in India and have lived in the UK for several years now, which means I have spent enough time driving in both places to appreciate just how different they really are. I also happened to be back home in Delhi this summer for the holidays.

If you have driven in Delhi, you know exactly what I mean. There is a kind of ‘beautiful chaos’ to it. Cars, bikes, buses, auto-rickshaws, pedestrians, delivery guys on scooters, all making their own decisions at the same time, somehow without a plan. There are traffic lights and lane markings, sure, but anyone who has actually spent time on those roads knows the rulebook is only half the story. You are reading the situation constantly. A gap opens, someone takes it. Someone else has already anticipated that. A scooter appears out of nowhere on your left. You adjust. And somehow, everyone just keeps moving.

Now put that next to driving in the UK. Almost comically different. Everything is explicit here. Lane discipline. Signalling. Right of way. Mirrors, always the mirrors. Anyone who has sat the UK driving test knows that knowing how to drive and proving you can drive by the book are two very different things. It took me more than one test (meh!) to pass the exam. Unlearning Delhi’s driving and then learning the UK’s is not a joke.

The UK runs on predictability and rules. Delhi has rules too, but what really keeps things moving is interpretation, anticipation, and a kind of collective improvisation. Being neck deep in all things ‘industrial AI’, I couldn’t stop seeing the parallel, because the real question underneath both is who’s in charge when the rulebook and the improvisation are happening at the same time. That’s basically the orchestration problem, just with more scooters!

What Happens When Rules Fail: The Real-World Orchestration Problem

My last blog was about why the context layer is becoming such a big battleground in industrial AI. The next part to this is what happens after a system actually has that context. Knowing what is going on is one thing. Deciding what to do about it, especially when nobody has seen the situation before, is a different problem entirely.

For decades, industrial automation has been really good at that second part, as long as we can write the rules down. If X happens, do Y. Temperature crosses a threshold, trigger the alert. Machine stops, stop the line. Inventory drops below a level, reorder. That is honestly why automation has worked so well for so long. We take messy physical processes and turn them into decisions that repeat the same way every time. Nothing wrong with that at all, when the world is predictable, rules are genuinely powerful.

But what happens when the world is not predictable?

A machine starts behaving differently because the material batch changed. A supplier is late. Energy prices spike overnight. A production order gets rewritten at the last minute. An operator does something slightly different because they know something the system was never told. Or, my personal favourite, three unrelated things go wrong at exactly the same moment, and now it is not one system’s problem to solve. It is a question of who is in charge, and who decides.

Usually, the problem is not that the system does not have enough data. It might be drowning in it. The problem is that nobody wrote this particular situation into the rulebook, because nobody thought to.

Scaling AI Adoption: Why Most Pilots Don’t Translate to Production

Scaling AI, automation, and digital transformation is now the single biggest business priority for manufacturers globally, ahead of cutting costs, ahead of innovation, ahead of supply chain resilience from IDC’s own Worldwide Manufacturing 2026 Survey. And yet only around one in five manufacturers have actually gotten AI to scaled production use across multiple workflows or sites. Most are still piloting, or stuck running it in a limited corner somewhere. That gap between what people say they want and what is actually running on the floor is, in my mind, that same problem playing out at scale.

Blending Rules and Improvisation: A New Model for Industrial AI

We tend to talk about AI in manufacturing through use cases. Predictive maintenance. Quality inspection. Scheduling. Forecasting. All fine, all useful, but underneath all of that sits a much simpler question: can a system make a good call when the situation was never anticipated in the first place? That, to me, is really the line between automation and autonomy. Automation runs a known response. Autonomy has to read a situation, weigh a few options, and decide what happens next.

This is where the traffic thing earns its place, I think. Delhi has not beaten the UK at this. The UK has not beaten Delhi either. Both systems genuinely work, they just carry complexity differently. The UK gives industrial AI something it cannot do without: rules, constraints, predictability. You do not want an agent treating a safety requirement as optional, or skipping a maintenance step because it spotted a quicker path. Delhi gives you the other half of the lesson, which is that the real world does not always follow the plan, and when it does not, something needs to be able to interpret and adapt in the moment.

Traditional automation asks what should happen when a condition occurs. AI lets us ask something harder: given everything happening right now, what should happen? The first question can be programmed in an afternoon. The second needs judgement, including knowing when to ask a human. It also needs an understanding that the locally smart move can quietly create a bottleneck or a maintenance headache somewhere else entirely.

The decision stops being about one machine or one KPI. It becomes about the whole system, which is probably why I think the next real fight after the context layer is orchestration, agents working across ERP, MES, EAM, supply chain and energy together, not just sitting inside one application doing their own thing.

So maybe the future of industrial AI needs a bit of both: the UK’s rules and Delhi’s improvisation, with AI doing the very unglamorous job of figuring out which one a moment is asking for, across every system involved, not just the one closest to the problem.

The Path Forward

Underneath all of this sits a broader challenge: how intelligence works across systems, processes, people, and increasingly other agents. That’s orchestration. And as industrial AI moves from individual use cases into day-to-day operations, it is becoming harder to ignore.

For manufacturers, I think this changes the discussion slightly. Most organisations already have plenty of AI ideas, pilots, and use cases. What feels less clear is what happens when those systems need to work together. How does an AI-driven decision in one part of the operation affect everything else that sits downstream? Who is coordinating across ERP, MES, EAM, supply chain, and energy systems? And when things do not go according to plan, how does the system decide whether to act on its own or pull a human into the loop?

Those feel like the more interesting questions because they are not really about AI models at all. They are about how intelligence, whether human or machine, is orchestrated across the operation. And that may be one reason why so many organisations still struggle to move from promising pilots to something that operates at scale.

Contact our experts to explore how industrial AI orchestration applies to your manufacturing strategy.

Gunjan Bassi

Gunjan Bassi - Research Manager

Gunjan Bassi has more than 14 years' experience working in the logistics and transportation sector. Before joining IDC, she worked with Transport Intelligence (Ti), a transportation and logistics research firm based in Bath, England, where she was responsible for vertical…