一个正在被低估的变化:云,已经不只是“算力池”

过去十多年,云计算的核心价值在于弹性、规模和成本效率。但 IDC 指出,随着生成式 AI 和智能体(Agentic AI)走向生产环境,云计算正在发生一次根本性转变——它不再只是承载应用的基础设施,而正在演进为 AI 运行、治理与协同的核心平台。

在中国市场,这一变化尤为明显。一方面,AI 应用对算力、数据、网络和安全提出了更复杂、更高频的需求;另一方面,数据安全、数字主权和成本压力,使企业无法简单依赖单一公有云模式。云计算,正在被迫“进化”。

在《IDC FutureScape:全球云计算2026年预测——中国启示》(Doc# ,2026年,1月)中,IDC 系统性地刻画了未来五年云计算将如何围绕 AI 重构自身形态与价值。

十大预测:AI 如何重新定义云计算的形态与边界(原文引用)

预测 1|云基础架构现代化

到 2027 年,海量的计算和数据需求将强制超过 85% 的中国组织将传统云环境转型适配 AI 工作负载的新型平台。

这意味着,传统以 IaaS/PaaS 为中心的云架构已难以支撑 AI 应用规模化,云基础架构现代化将成为企业发展智能业务的前提条件。

预测 2|代理式 AI 云运营

到 2027 年,80% 的中国 500 强企业将会部署代理式 AI 平台,为自动化 IT 云运营提供大规模、持续性的监控、分析、故障修复能力,最小化人工干预。

云运维正从“人驱动”走向“智能体驱动”,IT 团队的角色将随之发生转变。

预测 3|专业的 AI 云服务提供商

到 2029 年,区别于 GPU 资源提供商,至少 30% 的高等级 GPU 将由 AI 云服务商的具备云特性、灵活计费、API、软件服务的资源覆盖。

企业将越来越倾向于选择“懂 AI 的云”,而不仅仅是提供算力的云。

预测 4|边缘 AI 智能体

到 2028 年,具身智能将迎来爆发式增长,云服务提供商将通过在企业边缘环境部署 AI 基础设施和智能体支撑其中 60% 的业务场景。

AI 正从中心云走向边缘,云计算的服务边界被显著拉长。

预测 5|基于私有云的企业级 AI 平台

到 2028 年,为了满足数据隐私需求以及降低公共大语言模型的数据泄露风险,60% 的中国组织将采用能够在数据治理方面提供更多控制能力的私有云平台方案。

私有云正在成为企业级 AI 的关键承载平台,而非“过渡选择”。

预测 6|AI 成本治理

到 2028 年,没有把 AI 投入并入成本治理范围的企业 FinOps 团队将在 AI 相关项目方面面临 30% 的成本增长以及更低的总体回报。

AI 时代,成本治理能力将直接影响云与 AI 投资的可持续性。

预测 7|异构云基础设施

到 2028 年,超过 80% 的中国组织将采用异构云基础设施,用于平衡混合的 CPU、GPU、存储技术以优化 AI 工作负载的性价比。

单一算力形态已无法满足 AI 需求,异构成为常态。

预测 8|云端风险管理

到 2029 年,基于地缘政治的不确定性,50% 的实施数字化自治的中国组织将迁移敏感的工作负载到新的云平台以降低风险和提高自主能力。

云计算正在被纳入更宏观的风险与主权考量。

预测 9|AI 辅助工作负载替代

到 2029 年,60% 的中国组织将采用云端的 AI 融合工具用于评估成本和性能指标,通过部署 25% 的 AI 智能体自动化工作负载的协同,以优化工作负载的替代。

AI 将参与云资源与工作负载的“自我优化”。

预测 10|智能体 SaaS 平台

到 2029 年,50% 的中国企业应用将采用 SaaS 平台模式进行实时工作流中的预定义 APP 功能和 AI 智能体的协同,构建模块化和共享交互的解决方案。

SaaS 正在向“应用 + 智能体”的平台形态演进。

这些预测共同说明了什么?

IDC FutureScape 2026 反复传递出一个清晰信号:AI 已经成为云计算发展的第一驱动力。

云不再只是支撑 IT,而是直接决定 AI 能否落地、能否规模化、能否在合规和成本可控的前提下持续运行。忽视云基础架构演进的企业,将很难在 AI 投资上获得长期回报。

分析师观点

IDC 中国高级研究经理张犁认为,中国云计算市场正从“规模增长期”迈入“能力重构期”。FutureScape 2026 显示,云计算正在围绕 AI 重塑自身的架构、服务形态与商业模式——从基础架构现代化、代理式 AI 运维,到私有云与异构云并行发展。那些能够将云战略与 AI 战略深度融合的企业,更有可能在复杂环境中实现业务韧性与持续创新;而仍将云视为单一基础设施选项的组织,将面临更高的成本、风险与转型阻力。

一个面向管理层的综合建议

IDC 并不建议企业孤立地“上云”或“上 AI”。更重要的是,以 AI 为核心,重新审视云基础架构、云运营模式、成本治理与风险管理能力。
云计算,已经从“是否采用”的问题,转变为“是否足以支撑下一代智能业务”的问题。

如需进一步了解与研究相关内容或咨询 IDC其他相关研究,请点击此处与我们联系。

Lee Zhang - Senior Research Manager - IDC

Lee Zhang is a senior research manager for IDC Cloud Computing whose research theme focuses on cloud technology, namely hybrid cloud infrastructure, cloud-native infrastructure, big data infrastructure, microservice architecture, and deep learning (DL)/machine learning (ML) architecture, among others. Lee is also responsible for providing project consulting, market analysis for cloud service providers and end users, in collaboration with IDC local and regional consulting/research teams. Lee previously worked as a solution architect for Alibaba Cloud in the retail business, primarily focused on hybrid cloud solution design and delivery, and digital transformation project management. He assisted all types of clients, such as private enterprises, state enterprises, and government departments, designing digital transformation solutions with cloud technology such as hybrid cloud infrastructure including infrastructure as a service (IaaS)/platform as a service (PaaS)/desktop as a service (DaaS)/software as a service (SaaS), middle-stage infrastructure, big data platform, migration to cloud methodology, microservice architecture, and DL/ML, to name a few. Lee graduated from Beijing Institute of Technology with a master's degree in Business Administration (MBA). He obtained his bachelor's degree in Automation from the Huazhong University of Science and Technology.
Technology Trends Feb 10, 2026 Masaru Muramatsu

国内ITモダナイゼーションサービス市場予測を発表 ~大・中堅企業の約8割がレガシーシステムを保有、ITモダナイゼーションサービス市場は2030年にかけ年間平均成長率10%で拡大~

IDCでは、2025年の国内ITモダナイゼーションサービス市場(支出額ベース)を、1兆3,044億円、前年比成長率を10.1%と推定しています。また、2025年~2030年の年間平均成長率(CAGR:Compound Annual Growth Rate)を10.2%、2030年の国内ITモダナイゼーションサービス市場規模を2兆1,234億円と予測しています。

Read full release
Artificial Intelligence Feb 10, 2026 Go Suzuki

先進企業の取材から見えたデジタル変革を定着させる「企業風土/組織文化」の共通点 ~国内企業における組織文化変革の課題と実践~

IDC: 人工知能)の推進において必要となる企業風土/組織文化変革の取り組みに関する分析結果を発表しました。これによると、企業風土/組織文化の変革が前進している企業には共通して見られる考え方や取り組みが確認されました。

Read full release

Key Highlights:

  • By 2028, CIOs will increase spending on sovereign-ready cloud and data localization by 50% to stay compliant in Asia/Pacific.
  • By 2030, 15% of A1000 firms will face lawsuits, fines, or CIO dismissals tied to poor AI agent governance.
  • By 2027, AI infrastructure costs will run up to 30% higher than planned, forcing CIOs to expand FinOps practices.
  • Most organizations still struggle to demonstrate consistent, measurable AI business value.

What is changing for CIOs in Asia/Pacific as organizations scale agentic AI?

Between 2026 and 2030, CIOs will be judged less on AI experimentation and more on their ability to operationalize AI securely, affordably, and in compliance with local regulations. IDC FutureScape research shows that success will depend on sovereign-ready architectures, transformational AI leadership, formal AI value playbooks, stronger governance of AI agents, and disciplined FinOps practices.

AI has become a board-level priority across Asia/Pacific (excluding Japan). Enterprises are under pressure to use AI to improve productivity, resilience, and growth, while navigating fragmented regulations, uneven cloud maturity, and persistent skills shortages.

For CIOs, the margin for error is shrinking. Poorly governed or poorly justified AI initiatives can quickly lead to cost overruns, regulatory exposure, or operational disruption. As a result, the CIO role is evolving beyond technology delivery toward enterprise leadership, financial accountability, and risk stewardship.

Five Predictions Defining the Shift to Agentic AI

1. Digital sovereignty

By 2028, CIOs at multinationals will boost investments in modular, sovereign-ready cloud and data localization environments by 50% to future proof operations against rising sovereignty demands.

Digital sovereignty is now a structural constraint on IT and AI strategy in Asia/Pacific. Expanding data localization and AI regulations in markets such as India, China, and Australia are forcing CIOs to move away from highly centralized global cloud models. Modular, sovereign-ready architectures allow organizations to localize data, models, and controls while maintaining operational consistency. Although this raises costs through redundancy and regionalization, it reduces regulatory risk and protects long-term market access.

2. Transformational AI leadership

By 2028, 70% of A500 CIO roles will be held by transformational leaders who can implement new AI-fueled business models with enterprise-wide consistency while modernizing IT to meet AI business needs.

As AI reshapes business models, CIOs are increasingly expected to lead enterprise transformation, not just IT modernization. In Asia/Pacific, where CIOs are more likely to report directly to the CEO, this shift reflects rising expectations that AI investments deliver measurable business outcomes. Transformational CIOs distinguish themselves by aligning AI initiatives with corporate strategy while modernizing core systems to support scale and resilience.

3. AI business value playbooks

By 2027, 60% of A500 CIOs will be tasked to create enterprise AI value playbooks, featuring expanded ROI models to define, measure, and showcase AI impact across efficiency, growth, and innovation.

Despite growing AI investment, most organizations struggle to prove consistent business value. Traditional ROI metrics fail to capture indirect benefits such as faster decision-making, improved customer experience, and resilience. AI value playbooks provide CIOs with a standardized framework to compare use cases, prioritize investment, and communicate impact to executives and boards, helping prevent pilot sprawl and loss of confidence.

4. AI business disruption impact

By 2030, 15% of A1000 organizations will have faced lawsuits, substantial fines, and CIO dismissals because of high-profile disruptions stemming from inadequate controls and governance of AI agents.

Agentic AI introduces new operational and regulatory risks as autonomous systems move into mission-critical workflows. In Asia/Pacific, unified AI governance remains limited, increasing exposure to outages, compliance failures, and reputational damage. CIOs are under growing pressure to implement stronger controls, human-on-the-loop mechanisms, and cross-functional governance before agentic AI scales further.

5. FinOps practices for AI

By 2027, A1000 organizations will face up to 30% rise in underestimated AI infrastructure costs, driving CIOs to expand the scope of FinOps teams to optimize expenses and enhance business value.

AI introduces volatile cost structures across cloud consumption, model training, and AI-infused applications. These costs are often underestimated, particularly in Asia/Pacific’s fragmented hybrid and multicloud environments. Mature FinOps practices are becoming essential to improve cost transparency, align AI spending with business priorities, and prevent unexpected overruns that undermine executive trust.

What Comes Next for CIOs in Asia/Pacific

Over the next three to five years, Asia/Pacific organizations will move from AI experimentation to industrialized, agentic AI operations. Investment will shift toward platforms, governance frameworks, and financial discipline that support repeatability and control. CIOs who establish these foundations early will be better positioned to scale AI while maintaining trust with regulators, customers, and boards.

Key Questions CIOs are Being Asked

  • Why is digital sovereignty shaping CIO priorities now?
    Regulatory enforcement is increasing across Asia/Pacific, making it essential for organizations to localize data and AI controls without sacrificing operational efficiency.
  • Why do AI initiatives struggle to show ROI?
    Many organizations lack standardized methods to measure indirect and long-term AI benefits, resulting in fragmented pilots and weak executive confidence.
  • What is the biggest risk as agentic AI scales?
    Inadequate governance of autonomous systems, which can lead to operational disruption, compliance failures, and executive accountability.

Explore IDC Research on the Asia/Pacific CIO Agenda and Agentic AI

For CIOs and technology leaders navigating AI at scale, IDC’s FutureScape research provides data-driven insight into how sovereignty, governance, cost discipline, and leadership expectations are reshaping the CIO role across Asia/Pacific.

Linus Lai - Group Vice President, Research - IDC

Linus Lai is a distinguished member at IDC Asia/Pacific, in which he spearheads research in digital business, trust, infrastructure, and services. With over 25 years of industry experience, Linus is based in Sydney and serves as the chief analyst for Australia and New Zealand (ANZ). He is a founding member of IDC's Emerging Technology Advisory Council and a respected senior member of the region's CIO100, CSO, and Future Enterprise awards. In his role, Linus provides strategic insights for digital leaders and the technology sector, focusing on sourcing strategies and emerging technology across Asia/Pacific. His expertise has earned him numerous accolades for his contributions to country, regional, and quality research. Previously, as the head of research in Southeast Asia, Linus was instrumental in expanding IDC's presence and influence in the region. His thought leadership is frequently sought after through regular features in various publications and media outlets. He is also a prominent speaker at industry forums, keynote events, and strategy workshops. Before joining IDC, Linus worked with a leading outsourcing service provider with a digital banking focus. He holds a Master of Science degree from the University of Lincoln, United Kingdom.

Daniel-Zoe Jimenez - Vice President, Digital Innovation, CX & Software, DNB/Start-ups, SMBs, Consumer and Channels Research - IDC

Daniel provides strategic advisory services to the C-Suite (CIOs, CTOs, CFOs, CDOs, CMOs, and CHROs) on how to develop and leverage technologies (e.g., AI/Analytics, Cloud, RPA, AR/VR, ERP, CRM) and new business operating models to become more agile, resilient, and competitive. He delivers workshops and strategic engagements for customers across Asia/Pacific such as assessing maturity, identifying gaps, crafting strategies and technology roadmaps, determining ecosystem readiness, business value metrics (KPIs), and skills required to drive future growth and profitability. Also, he provides research and strategic advisory to tech buyers and suppliers into the most emerging technologies and market developments like the Metaverse.

当前,中国工业行业正处于由“数字化”向“智能化”跨越的关键拐点,“人工智能+工业”融合发展已成为产业转型升级的核心引擎。向国内市场看,随着需求加速升级、政策持续加码、技术不断演进,工业 AI 正从概念探索迈向规模化应用的新阶段;向全球市场看,各地区及国家对工业场景 AI 采用的重视程度空前高涨,但由于产业基础、IT/OT 架构与合规环境差异,不同区域在落地阶段与机会窗口上呈现明显分化。IDC 认为,中国工业厂商可依托自身技术积累与产业链优势,以多元化路径有针对性地推进海外市场拓展,实现“场景能力—交付体系—生态伙伴”的渐进式出海。

国内市场

工业 AI 规模化落地与智能体爆发式增长的双向共振

工业 AI 的需求已从早期头部企业的探索性投入,转向全行业“提质降本增效”的刚需。根据 IDC 预测,到 2028 年,中国工业企业 AI 支出规模将接近 900 亿元人民币,年复合增长率达到 38%。

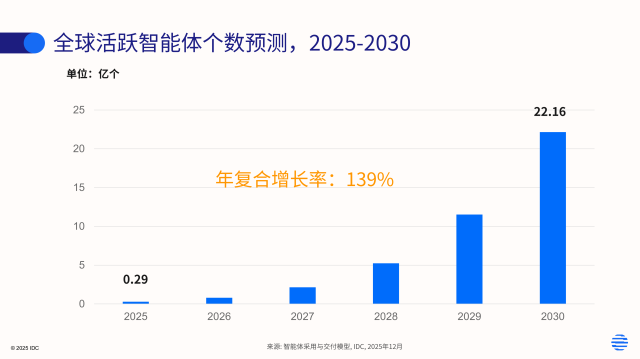
到 2030 年,全球活跃智能体数量将突破 22.16 亿个,年复合增长率达到 139%,其中工业领域的活跃智能体是最重要组成部分之一。IDC 认为,智能体数量的快速增长将与工业 AI 的规模化需求形成共振:一方面,工业企业对跨系统协同与流程闭环的诉求更强;另一方面,智能体作为“任务编排与流程执行载体”,有助于将 AI 从“点状能力”升级为“可运营的生产力”,从而加速规模化落地。

国家布局加码,“人工智能+”专项行动锚定工业 AI 规模化落地

2026 年 1 月,工业和信息化部等八部门联合印发《“人工智能 + 制造”专项行动实施意见》,明确提出到 2027 年推出 1000 个高水平工业智能体的目标,标志着工业智能体已从企业自发探索上升为国家层面的系统性布局;同期,国家发展改革委、国家能源局发布《关于推进“人工智能 +”能源高质量发展的实施意见》,与前者形成政策合力,共同推动人工智能技术与制造、能源等工业领域的深度融合应用。

工业智能体正在向“强专业属性/高专业适配度”技术路线演进

工业本身具有强行业差异与强流程约束,无论制造还是能源行业,每个环节的业务语义、数据形态与约束条件都不同,难以依赖消费级通用智能体“一招通用”。因此,针对工业生产中的设计研发、仿真测试、工艺改进、质量检查、设备运维、能耗管理等不同细分环节,专门适配的工业智能体正在快速增多,并呈现出“更强专业、更深嵌入、更可控可管”的演进趋势。

全球市场

全球各区域工业企业需求多元,中国工业 AI 出海瞄准差异化缺口

根据 IDC 的预测,到 2028 年,全球工业企业 AI 支出规模将接近 2.2 万亿人民币,年复合增长率达到 63%。与中国市场对比可以看出,中国市场的 900 亿人民币工业 AI 支出占比仍有限,海外市场在需求体量、行业多样性与付费能力上,存在更大的市场空间。

同时,IDC 观察到,全球各区域工业 AI 需求呈现差异化:

  • 在欧洲、北美等发达市场,工业企业具备更成熟的数字化与工业软件体系,更偏好体系化、高端定制与长期服务续订,但整体成本高、交付周期长。中国工业 AI 厂商可从工业视觉、能耗优化、新能源场站运维等细分场景切入,以“轻量部署 + 快速见效 + 性价比”形成差异化补位;
  • 在东南亚等新兴市场,工业 AI 落地意愿强但适配性方案与本地化交付供给不足。中国厂商可输出成熟的场景化方案与一体化服务,重点强化本地生态伙伴、交付标准化与运维体系建设,以提升可复制性与持续收入能力。

IDC 也建议,出海不应仅理解为“卖产品/做项目”,更需要同步构建三层能力:合规与数据治理能力、本地交付与合作伙伴体系、以及行业场景的可复用产品化封装。

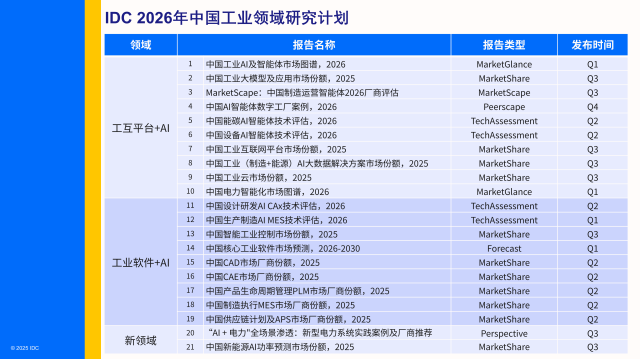
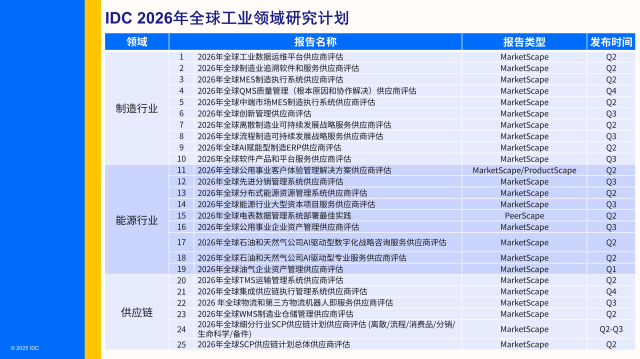
针对全球制造业、能源行业、供应链三大主题,IDC 全球工业研究在今年已启动一系列与工业智能化相关的研究议题,助力中国工业 AI 厂商进入国际工业企业视野,强化品牌可信度与市场触达效率。

IDC 2026年中国及全球工业研究计划:

更多推荐:

在全球工业 AI 政策护航、需求升级、技术迭代与出海进阶的发展背景下,IDC 同步启动工业 AI 领航者奖项征集,围绕行业先锋、出海先锋、创新先锋等多个维度展开评选,旨在发掘具有可复制价值的行业实践,推动工业智能化从“示范”走向“规模化”,并助力“中国方案”在全球工业智能价值分工中占据更重要的位置。

如需进一步了解与研究相关内容或咨询 IDC其他相关研究,请点击此处与我们联系。

AI 时代的一个被低估事实:算力不是瓶颈,基础架构才是

在过去一年里,企业对 AI 的讨论几乎全部围绕模型、算力和应用展开。但 IDC 指出,一个正在被反复验证的现实是:真正限制 AI 规模化落地的,并不是模型能力,而是数字化基础架构的成熟度。

当 AI 从“试点探索”走向“生产级运行”,企业的操作系统、数据中心、网络、存储、边缘节点和运维体系,开始承载前所未有的复杂度和压力。数字化基础架构,已经从后台支撑,转变为 直接影响业务速度、成本结构、韧性与可持续性的核心能力。

在《IDC FutureScape:全球数字化基础架构2026年预测——中国启示》(Doc# ,2026年1月)中,IDC 描绘了未来五年企业基础架构将经历的一次系统性重构。

十大预测:数字化基础架构正在发生哪些“质变”?

预测 1|智能体嵌入操作系统成为标配

到2029年,65%的新操作系统版本将搭载基础设施运维 AI 智能体与 MCP 服务器,大幅提升系统利用率、安全性与能耗效率。

操作系统正从“被动平台”演进为“主动运维中枢”,IT 团队将从日常维护中解放出来,转向更高价值的架构与业务协同工作。

预测 2|人工处理逐步退出日常运维

到2030年,45%的日常 IT 运维任务将由智能体 AI 处理;若事件未在平均解决时间(MTTR)目标内完成处理,则采用通知 IT 人员的模式提供指导。

AIOps 正在改变运维范式,人类不再是第一响应者,而是“最终裁决者”。

预测 3|数字孪生优化基础设施

到2028年,40%的数据中心将通过数字孪生(覆盖 IT 设备至设施全环节)实现优化,推动数字基础设施向可持续、高成本效益、强韧性的方向发生根本性转变。

数据中心运维从“事后响应”走向“事前模拟与预测”。

预测 4|异构计算的应用

到2030年,75%的数据中心将在 CPU、GPU、QPU、NPU、LPU、APU 和 DPU 的混合架构上运行工作负载,从而在特定应用场景中实现显著更快、更节能的处理能力。

未来的数据中心,不再是“单一算力池”,而是高度专业化的计算调度系统。

预测 5|液冷标准形成

到2030年,65%的新液冷部署项目将集成开放式行业标准,实现平台兼容性,并将部署、维护、改造及扩容成本降低三分之一。

液冷从“高端选项”走向“规模化基础设施能力”。

预测 6|AI 加速容器化转型

到2028年,75%的新 AI 工作负载将实现容器化,从而显著提升模型与工作负载更新的速度、一致性与安全性。

容器成为 AI 推理时代的“默认交付形态”。

预测 7|数据管道现代化

到2028年,65%的中国500强企业将实现数据存储基础设施的现代化,并优化数据流程,以便在可优化 GPU 集群的存储系统上,向 AI 模型提供高质量、经过整理的数据。

没有高质量数据管道,再多算力也无法转化为业务价值。

预测 8|推理向边缘侧迁移

到2027年,随着 AI 的重心从训练转向推理,80%的企业将部署分布式边缘基础设施,以提升 AI 应用的延迟表现与响应速度。

AI 正在从“云中心”走向“业务现场”。

预测 9|网络互联驱动基础设施发展

到2027年,75%的企业将部署面向互联的网络,以支持先进 AI 推理与分布式应用,提升安全性、敏捷性与风险管控能力。

网络从“连接工具”升级为“算力与数据流动的关键底座”。

预测 10|私有数字基础设施的复兴

到2026年,60%的企业将主动对私有 IT 基础设施进行再投资,以提升混合云一致性,优化数据隐私、业务韧性、性能与成本。

私有基础设施并未消失,而是在 AI 时代被重新定义。

这些预测共同说明了什么?

IDC FutureScape 2026 反复强调:AI 的竞争,最终会回到基础架构。

模型可以快速迭代,但基础架构一旦落后,企业的 AI 战略将很难持续。真正的领先者,将是在自动化、异构计算、数据流动和治理能力上,提前完成布局的组织。

分析师观点

IDC 中国研究副总裁周震刚认为,中国企业正从“云优先”迈向“AI 优先”的新阶段。FutureScape 2026 显示,数字化基础架构正在从成本中心转变为战略资产——它直接决定 AI 能否规模化落地、业务是否具备韧性,以及企业能否在不确定环境中持续增长。忽视基础架构现代化的企业,将在 AI 投资回报率、系统稳定性和长期成本控制上承受更大压力。

一个面向管理层的综合建议

IDC 并不建议企业孤立地升级某一层基础设施。更重要的是,以“AI 可持续运行”为目标,对操作系统、算力架构、数据管道、网络与运维体系进行系统性重构。


基础架构不是“是否够用”的问题,而是“是否能持续支撑下一代 AI 应用”的问题。

如需进一步了解与研究相关内容或咨询 IDC其他相关研究,请点击此处与我们联系。

Thomas Zhou - Vice President - IDC

Thomas Zhou is the vice president of Enterprise Research for IDC China. He leads the enterprise research team in covering market analyses, tracking of data, forecasting, and consulting for enterprise computing, storage, networking, infrastructure software, cloud, and datacenter. He is also responsible for IDC data tracking of software, services, and the public cloud services market in China. Thomas speaks frequently at IDC, industry, and user events and is always quoted in leading business and technology publications. Thomas joined IDC in 2006. He provides in-depth market analysis, research, and consulting on all aspects of the enterprise infrastructure to IT vendors and investors. During his tenure at IDC China, Thomas has led IDC's primary research focused on emerging trends in enterprise systems and datacenters. This research continues to make IDC a thought leader in enterprise infrastructure‒powered digital transformation. Thomas's recent topics covered software-defined infrastructure, hyperconvergence, virtualization, and cloud computing infrastructure. Prior to joining IDC, Thomas worked for 10 years as a senior project manager and business consultant for several leading IT companies in China. Thomas holds a master's degree in Computer Engineering from the University of Science and Technology of China.

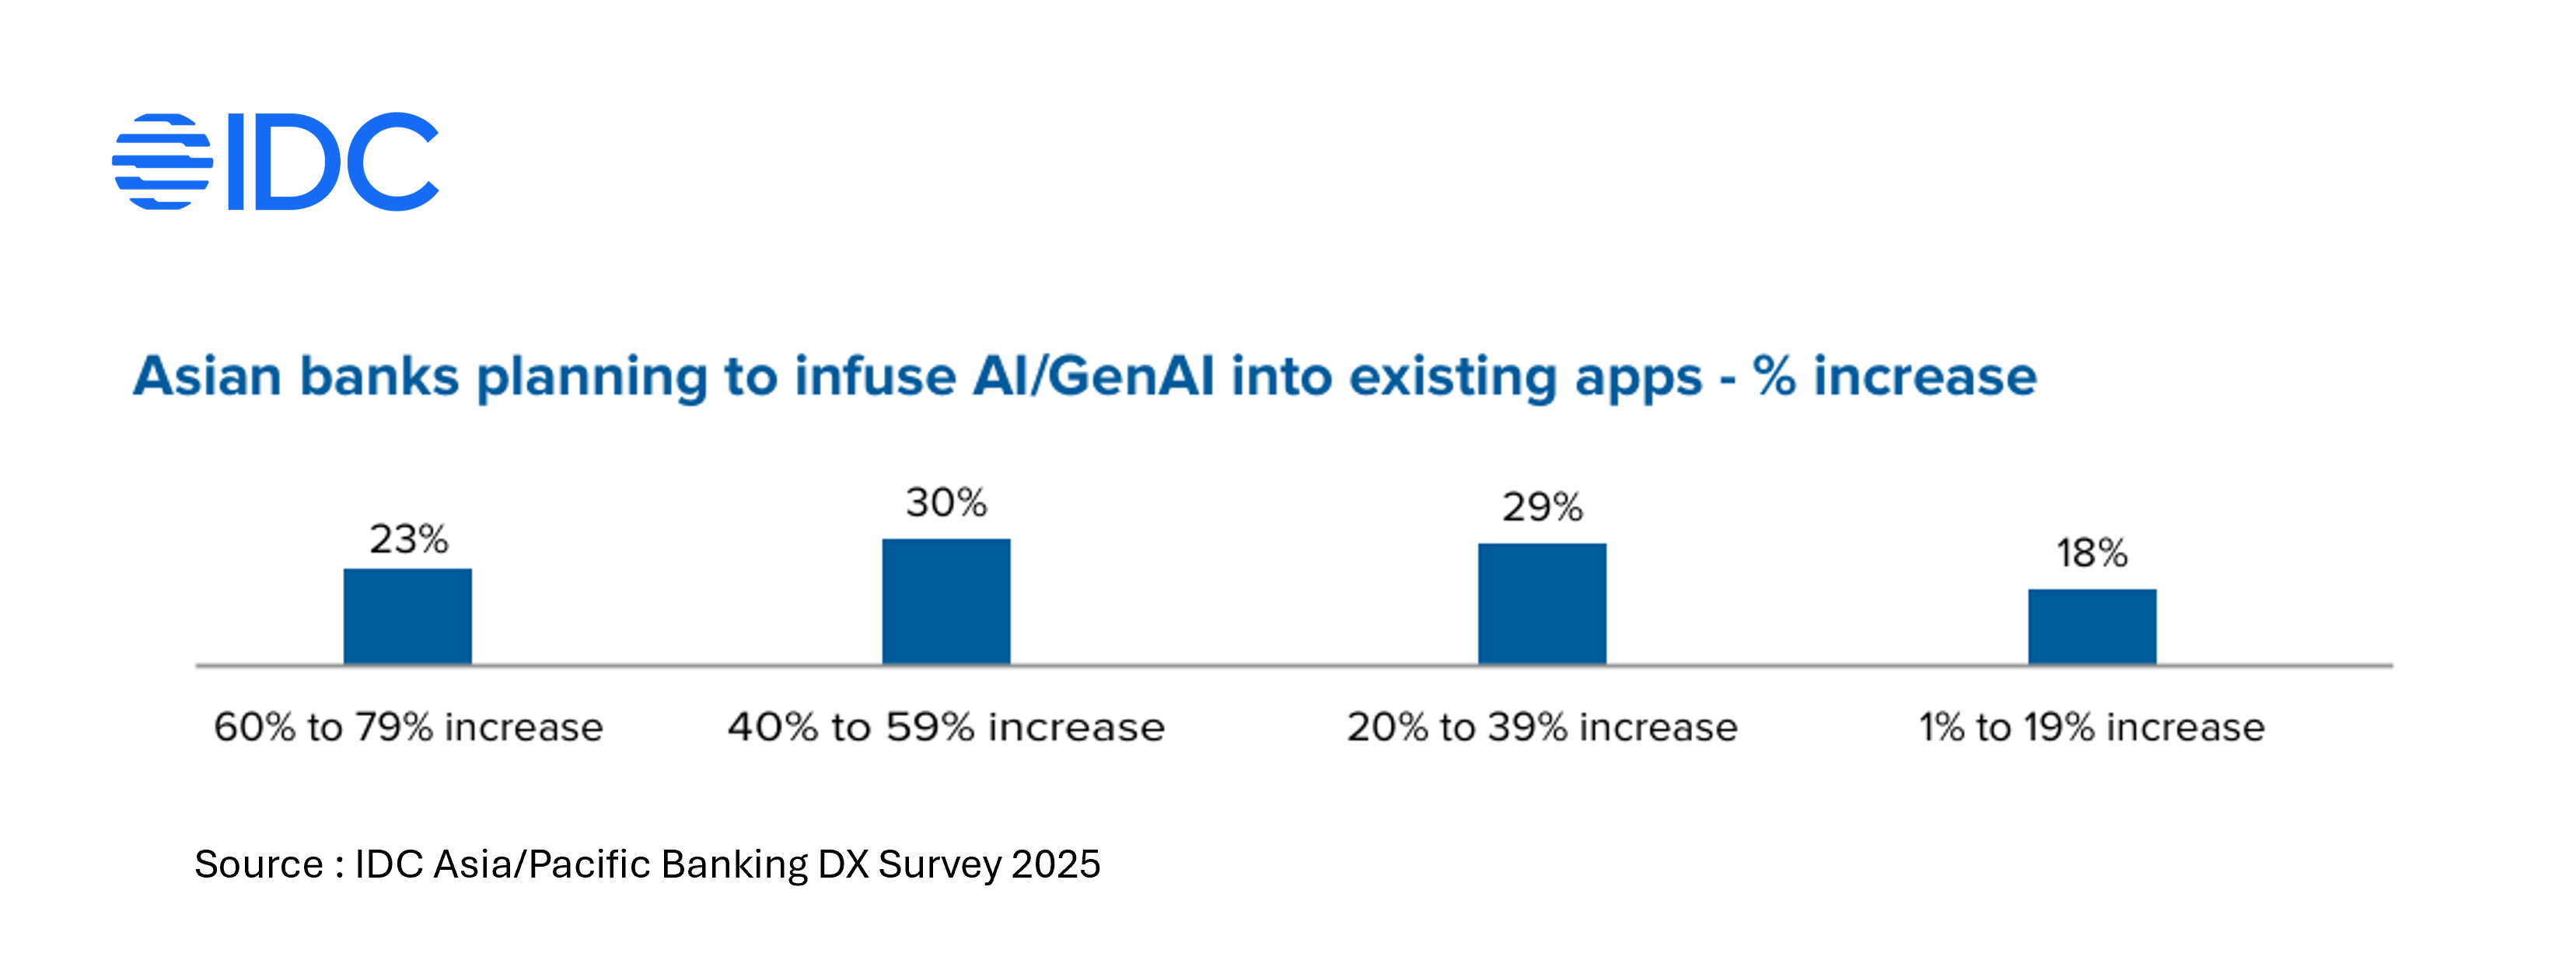
Asian banks are at a strategic crossroads.  Business complexity is rising as new asset classes, digital channels and ecosystem partnerships expand. Meanwhile, banks face softening interest rates, credit pressures, and geopolitical uncertainty. In response, banks are increasing investment in technology, especially AI, to drive efficiency, resilience, and revenue growth.   Recent IDC surveys show a clear rise in AI-related spending across the region.

The critical question is no longer whether banks are investing in AI, but how they can monetize that investment to generate measurable ROI and what role agentic AI plays in that equation.

Agentic AI offers banks a path from AI experimentation to measurable returns. By deploying autonomous AI agents across complex, multi-stage banking processes such as credit decisioning, risk management, and compliance, banks can accelerate decisions, improve consistency, and scale automation while maintaining governance. The greatest ROI comes from disciplined use case selection, AI-ready data and infrastructure, and strong trust and governance frameworks.

What Is Agentic AI in Banking?

Agentic AI in banking refers to AI systems composed of multiple autonomous agents that can independently analyze information, make decisions, and execute actions across workflows within defined guardrails and human oversight.

Unlike traditional AI models or copilots that provide recommendations, agentic AI systems can orchestrate end-to-end processes. This makes them well suited to banking operations, which involve multiple handoffs, probabilistic decision-making, regulatory constraints, and risk thresholds.

Why Banking Processes Are Strong Candidates for Agentic AI

Banking processes are often complex, involving multiple decision stages, approvals, and risk checks.   Many already rely on probabilistic model-driven decision-making engines, making them well-suited for agentic architectures.  

Example: Agentic AI in Credit Approval

Consider a credit approval process:

  • One agent specializes in credit checks against defined risk acceptance criteria.
  • Another agent estimates the maximum unsecured exposure the bank can underwrite.
  • A higher-level supervisory agent evaluates outputs and acts as the approver.

Together, these agents can accelerate credit decisions, improve consistency, and maintain governance and control.

Key Challenges Banks Must Address to Generate ROI

While the opportunity is significant, deploying agentic AI at scale poses several challenges banks must address.

Is the Bank AI-Ready?

Banks must realistically assess their data architecture and infrastructure readiness. Data patching and manual corrections may work during proofs of concept, but are unlikely to succeed in production. Similarly, pilot deployments may run on spare capacity, while scaled agentic AI systems require dedicated, resilient, and secure infrastructure.

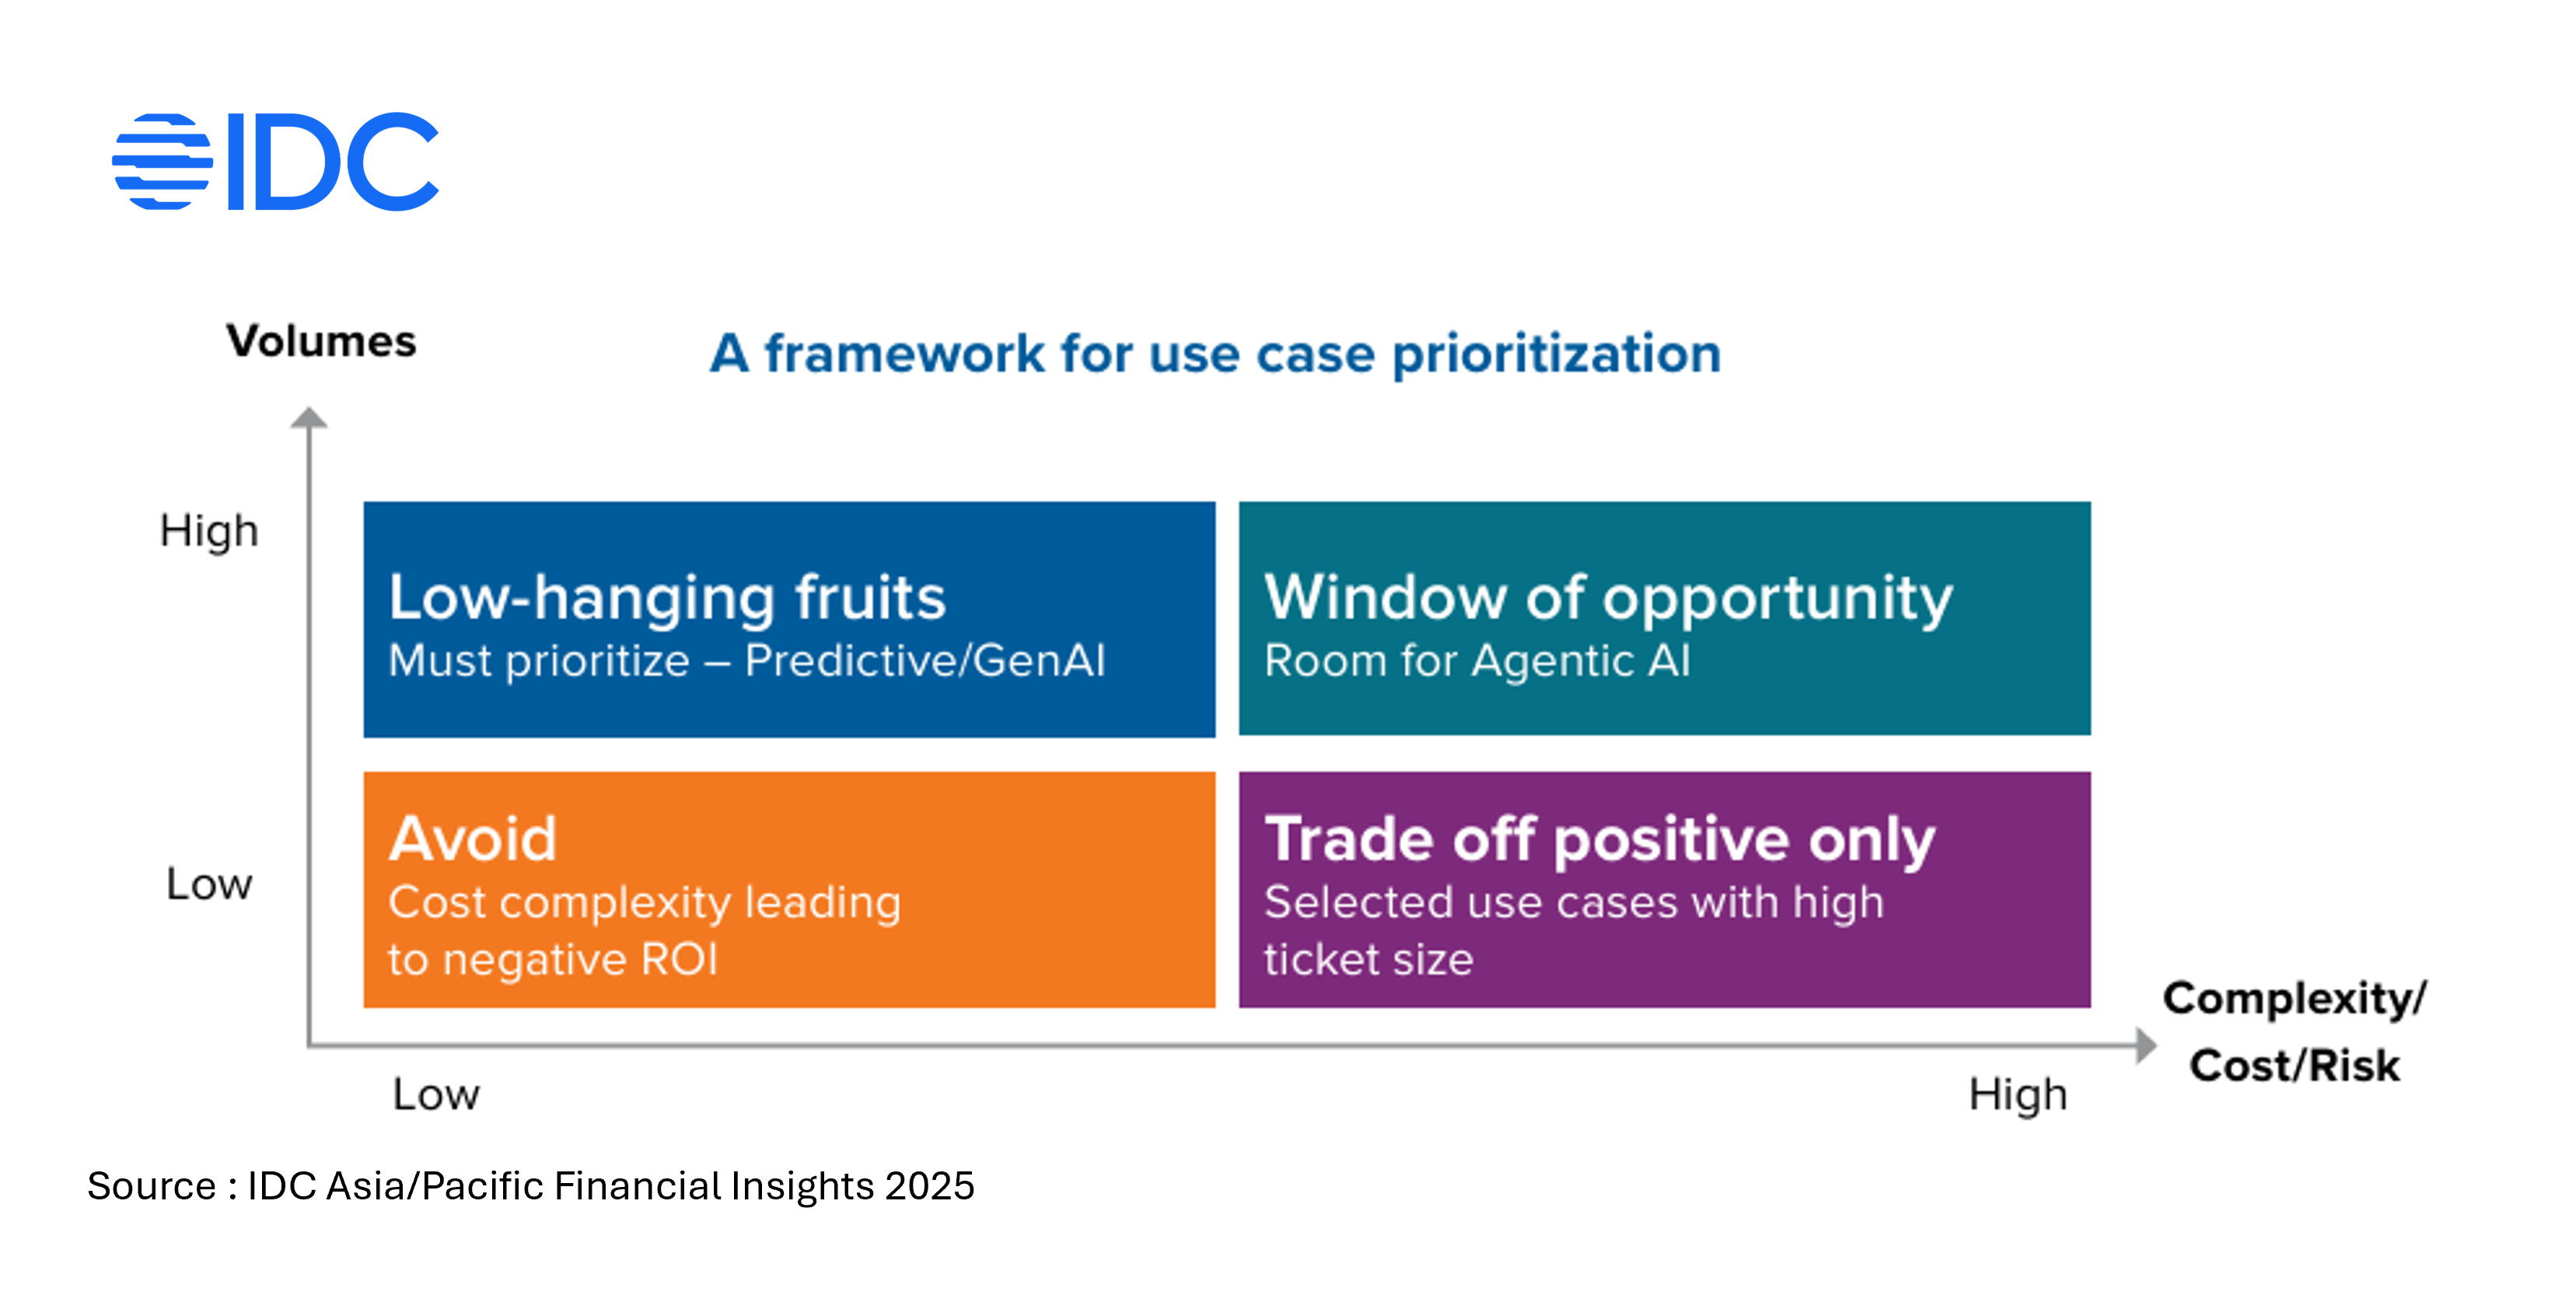
Selecting the Right Use Cases

Use case discipline is critical. Many banks run multiple exploratory or hobby AI projects driven by local enthusiasm rather than measurable business value. Even when proofs of concept show limited ROI, some initiatives still progress.

Prioritization must be anchored in clear business outcomes, such as:

  • Revenue growth
  • Operational efficiency
  • Risk reduction and compliance effectiveness

Establishing Trust and Governance

The AI trust deficit remains a major barrier, especially given the persistence of hallucinations and model errors. Building trust requires governance frameworks, transparency, human-in-the-loop controls, and continuous monitoring.

Turning Agentic AI Investment into an AI Dividend

While these challenges are not insurmountable, overcoming them is essential to generating an AI dividend. IDC research and client engagements include multiple case studies that validate that agentic AI represents a significant opportunity for the banking sector.

According to the IDC FutureScape: Worldwide Banking and Payments 2026 Predictions — Asia/Pacific (Excluding Japan) Implications report, by 2027 in APeJ, the share of AI investments directed toward innovation will rise from 25% to 40%, with increased spending on new products and services.

Banks that act now—focusing on high-impact use cases, readiness, and governance—will be better positioned to translate the potential of agentic AI into measurable business outcomes.

What’s Next

IDC works with banks across Asia/Pacific to assess AI readiness, prioritize agentic AI use cases, and design governance models that support scalable ROI.

Register now for the live webinar on 24 February 2025 at 1:30 pm SGT to join IDC in charting the agentic future with confidence.

Ashish Kakar - Research Director - IDC

Dr. Ashish Kakar is research director for IDC Financial Insights in Asia/Pacific. Based in Singapore, he is the lead Financial Insights analyst responsible for all aspects of banking and insurance research. Dr. Ashish's own interest is in fraud and risk, resilience, customer centricity, AI/ML, retail banking, insurance, alternative investment management, cloud and infrastructure, and credit risk management. Prior to joining IDC, Dr. Ashish had over 16 years' experience in Citibank, five years' experience with insurance companies, and has run his own asset management start-up for two years. In his last role in Citibank, Dr. Ashish managed processes across banking technology, servicing operations, and product. He was a regional senior with oversight of the Asia and Europe operations.

BYD surpassing Tesla in global battery electric vehicle (BEV) sales in 2025 marks a pivotal shift in the global new energy vehicle landscape. This milestone reflects not only divergent market strategies, but also differences in the stage of EV adoption across price segments.

BYD’s global sales momentum was driven primarily by its entry-level models—such as the Dolphin and Atto 3—which have made a substantial contribution to volume growth. This performance underscores BYD’s product competitiveness and signals an acceleration of electrification within the global mass‑market passenger vehicle segment.

According to IDC, global BEV sales are expected to exceed 12.1 million units in 2025, sustaining double‑digit year‑on‑year growth. Growth is being driven largely by the affordable EV segment. Following the rapid electrification of the premium market prior to 2020 and the mid‑range market between 2021 and 2023, entry‑level EVs have now emerged as the next growth engine, supported by declining battery costs and expanding charging infrastructure.

Based on long‑term market tracking, IDC observes that technological innovation typically penetrates the premium segment first before cascading into the mass market. The evolution of EV adoption globally is consistent with this pattern.

Divergent growth paths have shaped different adoption timelines for BYD and Tesla:

BYD: A Representative of a Full‑Scenario Green Energy Ecosystem

BYD’s business extends well beyond passenger vehicles, spanning public transportation, commercial vehicles, rail transit, and energy storage systems—together forming a comprehensive green energy ecosystem.

In the passenger vehicle market, BYD has rapidly expanded in emerging and mass markets through highly cost‑competitive models, while gradually introducing higher‑end product lines in mature markets.

Tesla: A Technology‑Centric Narrative as a Tech Company

From a brand positioning perspective, Tesla has consistently focused on attracting technology‑savvy, high‑end consumers, positioning itself as a technology‑driven company rather than a traditional automaker. Its AI‑related research extends beyond vehicles into areas such as robotics and energy management.

IDC believes that the growth logic of the entry‑level EV market differs materially from that of early‑stage markets. At this stage, cost efficiency, channel coverage, and operational execution become significantly more critical.

Does Sales Leadership Signal a “Return” to the Dealer Model?

In overseas markets in 2025, BYD’s most notable growth has occurred in Europe, driven by the rapid expansion of its dealer and service networks, localized manufacturing, strong product competitiveness, and differentiated technologies.

In Europe, BYD has partnered with established local automotive retailers to deliver sales and after‑sales services. In contrast, Tesla—which has maintained a direct‑to‑consumer (DTC) sales model—has been overtaken by BYD in unit sales.

This has led some observers to conclude that the traditional dealer model is regaining dominance. IDC does not believe this interpretation is accurate.

In the premium segment, the DTC model continues to be adopted not only by NIO and Li Auto, but also by high‑end EV brands incubated by traditional OEMs, such as Zeekr and WEY.

Premium EV customers place a high value on pricing transparency, seamless omnichannel experiences, and post‑purchase engagement. Digitalization and vehicle intelligence have connected historically fragmented offline touchpoints—such as vehicle purchase and maintenance—into a cohesive customer journey, creating a solid foundation for the DTC model.

At the same time, mass‑market EV manufacturers are increasingly adopting hybrid models that combine traditional dealerships with direct sales, or agency‑style structures. These approaches provide OEMs with greater control over pricing strategy and brand consistency, particularly when entering new markets.

For example, BYD has adopted a hybrid agency model in the UK: pricing is set centrally by headquarters, inventory is allocated through a European distribution hub, and local retail partners act as agents responsible for sales, delivery, and after‑sales support.

IDC believes that DTC and agency models remain a critical long‑term trend—not only in the premium segment, but increasingly in the mass‑market EV space as well.

The Long‑Term Rationale for DTC and Agency Models Remains Intact

Electrification is a cornerstone of sustainable development in the automotive industry, yet its market‑side adoption continues to be constrained by multiple factors, including battery technology.

Battery degradation remains highly uncertain. Charging behavior, ambient temperature, and usage intensity all have a direct impact on battery health, making value depreciation difficult to predict. This uncertainty fuels consumer anxiety around long‑term ownership costs and complicates residual value forecasting at a fleet level.

While leasing is often viewed in overseas markets as an effective way to mitigate EV depreciation risk, it carries inherent limitations. Fundamentally, leasing shifts risk rather than eliminating it. If actual battery degradation exceeds forecasts, residual values can still decline sharply, leading to asset impairments and margin pressure.

By restructuring the value chain, DTC and agency models centralize data ownership, enabling transformational solutions to a range of risks—including battery degradation. Under these models, dealers evolve into service partners. OEMs also gain access to full-lifecycle vehicle data, including mileage, battery health, charging patterns, and vehicle condition.

This data‑driven approach has the potential to fundamentally reshape residual value forecasting and risk management.

When further integrated with leasing models:

  • OEMs can retain vehicle ownership and repurpose or refurbish batteries at the end of the lease term, enabling a circular economy that offsets degradation costs and reduces environmental impact.
  • High‑frequency technology updates—from sensor upgrades to algorithm iteration—become feasible, accelerating the commercialization of autonomous driving services and improving the economic viability of autonomous fleets.

Key Takeaways from IDC’s Perspective

IDC recommends that EV manufacturers collaborate closely with dealers that possess strong regional advantages, adopting a “hub‑and‑spoke” hybrid strategy:

  • Hubs serve as brand flagships and data collection centers, ensuring brand consistency in high‑visibility markets.
  • Spokes focus on delivery and service, with dealers’ core competitiveness shifting toward localized customer support.

Under this model, true returns on investment do not primarily stem from higher gross margins, but from data ownership. This data enable the precise deployment of high‑margin services, transforming revenue models from one‑time vehicle sales into recurring income streams.

Direct sales depend on persistent digital connectivity with vehicles. OEMs must work with partners capable of delivering seamless and secure upgrades to ensure long‑term customer engagement and vehicle usability. Technology providers, in turn, must adapt to the demand volatility inherent in direct sales models by developing:

  • Modular, on‑demand manufacturing processes
  • OTA‑ready architectures
  • End‑to‑end cybersecurity protocols

For more information and related research, please click here to contact IDC.  

Bull Wang - Research Manager - IDC

As a research manager for client systems research in IDC China, Bull Wang has his research focused on topics of autonomous vehicle, connected vehicle, new energy vehicle, next-generation mobility service, and other automotive-relevant topics. Bull is responsible for conducting research and analysis for China and the global market, providing services for tech buyers, tech vendors, and tech watchers. Prior to joining IDC, Bull had experience in conducting market research projects, such as brand health tracking, campaign evaluation, car clinic, and consumer portrait. His other experiences include social media monitoring for acquainting public opinion on brand and product. Bull has long served the leading OEMs in automotive industry. Bull graduated from China Foreign Affair University, majoring in diplomacy, and obtained a Law bachelor's degree.