Oct 20, 2025

IDC:算力引擎驱动AI技术创新,上半年智算云基础设施市场(AI IaaS)翻倍增长

北京,2025年10月21日——国际数据公司 (IDC)最新发布的《中国智算云基础设施市场(AI IaaS)(2025上半年)跟踪》显示,2025上半年中国AI IaaS整体市场同比增长122.4%,市场规模达到198.7亿元人民币。其中,GenAI IaaS市场同比增长219.3%,市场规模达166.8亿元人民币;Other AI IaaS市场同比缩减14.1%,市场规模达31.9亿元人民币。

Read full release
Oct 19, 2025

2025 IDC中国未来企业大奖卓越奖在沪荣耀揭晓!

北京,2025年10月17日——2025 年 10 月 17 日,第十届 IDC 中国 CIO 峰会暨数字化转型颁奖盛典在上海盛大收官。作为 ICT 领域的年度重磅盛会,本次大会吸引将近1,000位行业精英齐聚一堂:既有来自各领域的企业用户代表分享实践经验,也有 ICT 技术厂商、合作伙伴机构共探前沿趋势。现场围绕生成式 AI 的产业落地、网络安全的防护升级、可持续发展的路径探索,以及智慧城市建设、数字创新实践、企业出海策略、石油能源数字化转型等热门议题,展开多维度、深层次的思想碰撞,为全球产业智能升级注入新思考与新方向。

Read full release
Oct 19, 2025

IDC:十年沉淀,智选伙伴,加速迈向智能经济——IDC发布《中国数智化50+供应商推荐——2025版》

上海,2025年10月17日—— 2025 年,数字技术浪潮正迎来历史性转折 —— 全球已正式迈入 “生成式 AI” 时代。AI 不再是企业运营的辅助工具,而是重塑生产工具、业务流程、客户体验乃至商业模式的核心引擎。在此背景下,国际数据公司(IDC) 发布了《中国数智化 50 + 供应商推荐——2025 版》 (Doc# CHC52861225 ,2025年9月) 报告,基于过去十年 “未来企业大奖” 获奖数据,遴选出 52 家经市场长期验证的卓越供应商,深度剖析中国企业数智化转型的现状、趋势与实践路径,为行业提供兼具数据支撑与实践价值的洞察。

Read full release
Oct 13, 2025

IDC:12.1亿市场起步,工业大模型应用迈向规模化扩张

北京,2025年10月14日——近日,国际数据公司(IDC)发布了《 中国工业大模型应用市场份额,2024:初起步 》(Doc# CHC5292992 5,2025年8月) 报告。IDC数据显示,2024年工业大模型应用市场规模约12.1亿元人民币。企业预算仍主要投向平台与基础模型体系,驱动力更多来自“不要落后”的探索心态,评估口径正由“有没有”转向“值不值”。

Read full release
Oct 12, 2025

IDC:AI应用指数级裂变,新型云厂商重构Agentic基础设施

北京,2025年10月13日——生成式AI以及Agent的采用势头强劲,大幅带动了AI基础设施的增长。在Agentic时代,曾经相对线性的技术栈已经演变为动态、互联的生态系统。这种变化不仅扩展了老牌企业的角色,也刺激很多企业跨界进入到AI基础设施市场。国际数据公司(IDC)在2025年第三季度研究了亚太地区不断变化的AI基础设施市场及其带来的新挑战,也重点调研了整个生态系统里的典型厂商如何适应这些新要求,并于近日发布了《 AI原生云/新型云厂商重构Agentic基础设施》(Doc# CHC 53815525 ,2025年9月) 报告。

Read full release

The U.S.-China tech rivalry has escalated to a new level this April 2025 with U.S. tariffs becoming a targeted trade tool. The Trump administration unleashed​ waves of tariffson Chinese goods: on March 4, a 10% tariff on all imports was imposed on top of raising tariffs from 10% to 20% on many Chinese electronics, machinery and industrial components; on April 2, ending of de minimis eligibility for China and Hong Kong (from May 2) and the “reciprocal tariffs” on key critical sectors imposed an additional 34%; and on April 8, an additional 50% tariff on semiconductors, EVs, and robotics was announced.

There also continues to be tariff escalations, clarifications and exemptions like in cases where final products have more than 20% of U.S. produced components. Chinese imports can be as high as 245% on needles and syringes or as low as zero for children’s books. Imported smartphones, computers and electronics appear to be currently granted a partial tariff reprieve and may only be subject to the March tariffs of 20%. These adjustments will probably continue as the impacts are felt by American consumers and the global markets.

Some view these measures as a means to derail China’s technological ascendancy by inflating costs, disrupting supply chains, and isolating it from global markets. Beijing’s counterstrategy, a mix of aggressive fiscal stimulus packages, supply chain resilience frameworks, and enforced technology self-reliance, suggests a calculated pivot to absorb short-term shocks while securing long-term growth.

The question then is: can China’s 2025 policy playbook neutralize U.S. tariffs’ impacts and sustain its ICT ambitions?

U.S. Tariffs’ Impact on China’s ICT Sector

IDC’s 2025 projections reveal a sector under strain but adapting. Our baseline scenario, with 20% tariffs in place, China’s ICT spending is expected to grow at 9.1% driven by domestic AI, cloud, and industrial software demand. With 50% tariffs, IDC’s downside scenario will slow down growth to 5.7%, with consumer electronics (PCs, smartphones) declining ​7.6% due to inflated import duty. An optimistic scenario, with tariffs rolled back, sees China’s ICT spending growth at 9.9%, fueled by pent-up innovation and continued existing global partnerships.

Contributing to China’s ICT spending in 2025 are the key trends we are seeing in software/cloud services (+10 to 16% YoY), largely due to organizations prioritization of digital efficiency, as well as in industrial technologies such as AI, IoT, automation, which remains resilient due to state subsidies. While the consumer hardware export market is expected to falter (e.g., iPhone costs rose 25% post-April hikes), domestic demand is expected to remain steady with government subsidies.

China’s Growing Tech Independence

There is increased emphasis on China’s “dual circulation” strategy that was originally a response to the U.S. tariffs and other sanctions introduced between 2018 and 2020. The strategy seeks to prioritize domestic consumption and non-western international trade to gain greater self-reliance and resilience. This strategy can be seen at work in the likes of DeepSeek whose open-source models are now powering a ​significant portion of Chinese Cloud services including Tencent, Alibaba and many more. Huawei’s Ascend AI chips also increased their share of AI-accelerator chips to ​27% in 2024 and is expected to reach 40% by the end of 2025.

Companies’ Response: Increased Agility to Respond to Tariff Chaos

Agility is the name of the game amid all this tariff chaos. Chinese tech giants are restructuring their supply chains by accelerating offshoring to Southeast Asia, shifting their assembly lines to sidestep tariffs. They are also diversifying their markets by pivoting to emerging markets, such as expanding electric vehicle and cloud service exports to tariff-immune regions. Some companies are also innovating operations by adopting leaner strategies like AI-powered factories to cut waste or using direct shipping tech from e-commerce platforms to bypass tariffs.

China’s 5-Point Plan: A Phase-Matched Counterattack

In response to each wave of tariffs, a 5-point plan helped blunt immediate impacts while increasing long-term leverage:

1. Domestic Demand Boost via “Consumer Upgrade Action” Plan

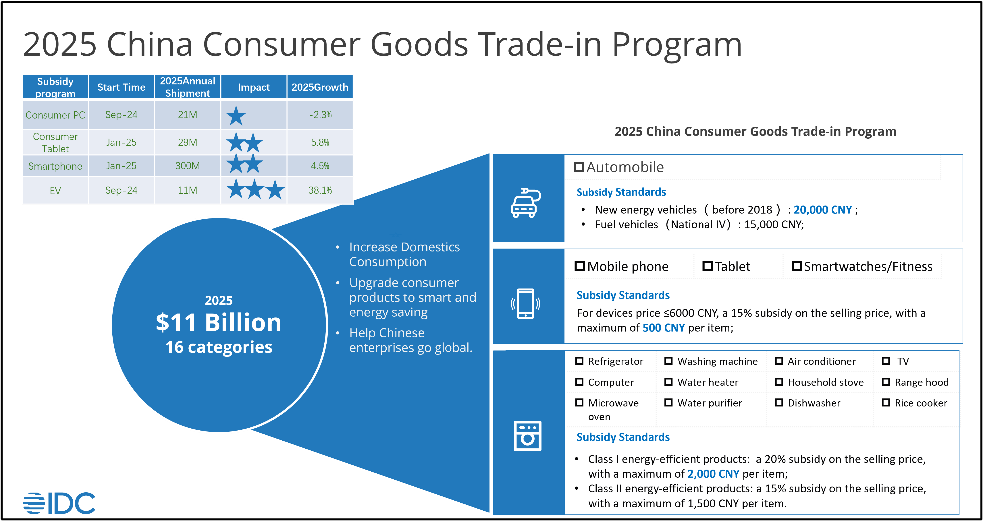
With the aim of boosting domestic demand and spurring economic growth, the Chinese government has put in place subsidies and trade-in programs for eligible consumer goods. For smartphones, tablets, and smartwatches, the government subsidy is up to 15% of product price, capped at ¥500/item. This trade-in program is expanded in 2025 to apply to other electronics, EVs and home appliances as well, as illustrated in the following chart:
The subsidies also target rural/low-tier cities for 5G adoption, smart home devices, and rural e-commerce logistics. There are also plans to stabilize consumer confidence through stock/real estate market reforms and wage growth policies.

The effect of these subsidies can be seen in the latest sales-out PC shipments with flat growth of 1% in 1Q 2025 compared to -16% in 1Q 2024.

2. Increased Funding for Emerging Tech

China’s $138B Innovation Fund aims to boost homegrown tech innovation and reduce foreign reliance amid escalating U.S. tariffs. It focuses on discovering and increasing “original technological breakthroughs” in early-stage startups in AI, quantum computing, hydrogen energy, biomanufacturing, and 6G technology. Funding is a combination of state capital and private/local government long-term (over 20 years) investments in R&D infrastructure and tech-to-product pipelines.

The innovation fund also involves industry stakeholders such as the MIIT (Ministry of Industry and Information Technology), academia, enterprises (to enhance smart manufacturing), and foreign collaborators in the telecom/robotics sectors. The program also aims to cultivate and highlight domestic STEM talent to offset global supply chain risks, with existing success stories like DeepSeek.

3. China’s “Five Financial Priorities” Guidelines

These guidelines provide financial support to organizations providing technology, green finance, digitalization, financial inclusion, and pension products and services. It uses technology investments to bolster innovation and self-reliance. Key measures include: comprehensive financing for national tech projects and SMEs via equity, debt, and insurance tools; capital market focus prioritizing early-stage investments in emerging technology through multi-layered markets; risk mitigation mechanisms to disperse R&D risks and expand venture capital/angel funding; and patient capital to cultivate long-term investments that nurture tech leaders, unicorns, and specialized SMEs. This framework integrates financial resources to advance China’s tech competitiveness and industrial upgrades.

4. Belt and Road 2.0: Decoupling from the U.S. via Global Partnerships

“Belt and Road 2.0” aims to reduce reliance on the U.S. by expanding partnerships and promoting diversification. Strategies include upgrading multilateral mechanisms (e.g., proposed creation of a global banking infrastructure), prioritizing green tech and digital infrastructure (e.g., Green Silk Road projects), and deepening cooperation with Global South nations (e.g., Indonesia, Malaysia). It counters U.S. decoupling attempts by fostering inclusive, non-conditional collaboration and integration with third-party markets. These initiatives also emphasize resilience through regional alliances and tech self-sufficiency.​

5. Private Enterprise Symposium 2025

The symposium was used to develop joint approaches between the public and private sector to offset U.S. tariffs. DeepSeek’s NLP breakthroughs and Unitree’s humanoid robots were highlighted as successful examples that have reduced reliance on foreign tech. At the symposium, China’s President Xi Jinping pledged to dismantle market barriers, ensure fair access to resources, and expedite laws protecting private enterprises.

Conclusion

Considering ongoing trade tensions, both U.S. and Chinese IT companies must adapt quickly to shifting geopolitical dynamics. Agility and scenario planning will be critical. Companies need to develop flexible strategies and implement tools that assess the potential impacts of tariff changes and geopolitical shifts. Regular cross-functional reviews can help minimize risks and ensure swift responses to market changes.

Furthermore, customer-centric innovation will drive market success. Companies must prioritize local market needs through targeted research, ensuring that their products align with specific regional demands such as those seen in healthcare, education, or government sectors. This approach is vital as trade restrictions may limit access to certain markets, but the demand for innovation will remain constant.

Strategic partnerships and alliances are also crucial for navigating challenges. U.S. and Chinese companies should collaborate with local tech providers to better understand market regulations and explore joint ventures to mitigate tariff impacts.

As the demand for smart home appliances grows, especially with trade-in programs, vast amounts of consumer data will fuel the expansion of B2C AI use cases in China. Additionally, China’s focus on infrastructure projects and domestic LLM development marks a new phase in technological independence, where reliance on U.S. technologies may decrease.

By focusing on flexibility, innovation, and strategic partnerships, both sides can thrive despite current challenges.

Learn more how you can navigate China’s geopolitical storms with trusted intelligence, read this complimentary IDC Market Note excerpt.  Alternatively, you can book a meeting with an IDC analyst for a consultation by submitting this form.
Kitty Fok - Managing Director - IDC

As the managing director of IDC China, Kitty Fok manages over 80 specialized analysts and leads all research for the China region. Kitty's expertise includes an in-depth understanding of the IT market, with a focus on emerging technologies, the impact of the Chinese government's policies, and digital transformation, as well as the fundamentals of forecasting, business development, and strategic planning/analysis. She is often invited to be a guest speaker in the industry's leading events and is regularly interviewed by the mainstream media, including the BBC, CNN, Bloomberg, CCTV, USA Today, The Wall Street Journal, South China Morning Post, and China Daily.

With the rise of technology sovereignty, major economic regions are aggressively developing self-sufficient ICT industry supply chains with the semiconductor industry as a key focus area. To contain China’s development in semiconductors and technology, in addition to export control and enactment of the CHIPS Act, the United States has also joined forces with the Netherlands, Japan, etc. to restrict China’s acquisition of semiconductor equipment tools (e.g., EUV and DUV), materials, specialty chemicals, software (EDA and IP) capabilities.

Despite this restrictive environment, Chinese vendors continue to adapt, and IDC has observed these key trends that deserve special attention:

  • Mature Manufacturing Processes Development and Government Subsidy Policy Models Transformation

As China is unable to develop its advanced manufacturing processes because of export controls on equipment, mature processes have become its industrial development focus. In the past, to develop semiconductor autonomy, Chinese government subsidies were mostly on the expansion of wafer manufacturing capacity. However, due to the overall environmental impact and the inability to obtain more substantial orders, many plants have become idle, underutilized, and unable to produce sustainable benefits for industrial development. To remedy this, the current government subsidy model was changed. Now based on operating results, wafer factories must obtain orders first and have a certain degree of capacity utilization to obtain government subsidies. This shift has made Chinese wafer fabs more active in attracting customers through different strategies (e.g., low pricing, placing orders first and then returning part of the investment amount later, etc.). Compared with the previous subsidy model, this incentivizes local fabs and IC design companies to expand their business.

China’s wafer fabs are currently self-sufficient in 22/28nm and older process technologies (given the available equipment tools). In the future, through government policies and subsidies, coupled with the support of China’s huge domestic demand market, it is expected that China will have a mature process market in 2030 (≥ 22nm) and will reach nearly 40% share (30% in 2023). China’s influence on the global semiconductor production capacity will also increase as it puts pressure on International Device Manufacturers (IDMs) and foundries focusing on mature nodes.

  • Focus on Wide-Bandgap Semiconductors

Wide-bandgap semiconductors, such as silicon carbide and gallium nitride, have the characteristics of low power leakage, high power, high-temperature resistance, and high voltage resistance. They are especially suitable for high-voltage and high-current environments. Therefore, in the future, wide-bandgap semiconductors will play a key role in applications such as electric vehicles, high-frequency communications, 5G communications, and green energy. At present, Wide-bandgap semiconductors are mostly regarded as national security-level industries. These are also the projects regions are investing in, developing, protecting, and establishing policies to encourage investment and export controls.

Every region expects to maintain technological independence in wide-bandgap semiconductors. China has listed it as a development priority in its 14th Five-Year Plan and hopes to further develop the technology and use it rapidly in new energy vehicles, communication industries, etc. Under this initiative, related applications are the focus. In 2023, China’s capacity of silicon carbide (SiC) crystal growth continued to grow. In addition to joining hands with IDMs, China will also begin to enter the power components market. If the new production capacity is effectively produced in 2024, China SiC wafer’s market share will increase significantly, and its industrial influence cannot be ignored.

  • Actively Lay Out Chiplets

China is also using chiplets to connect chips with different functions and slow down the impact of the restricted development of high-end chips. China has established a chiplet alliance and produced their first chiplet technical standard. In the “Advanced Cost-driven Chiplet Interface(ACC 1.0)” drafted by China ChipLet League in 2023, more emphasis was also placed on optimizing China’s packaging and substrate supply chain through chiplets and expanding related packaging technologies. However, although China actively hopes to break through in this area, not all chips are suitable for chiplets. For example, chips used in consumer electronics, such as mobile phones and laptops, rarely require chiplet designs. In addition, chiplet design requires more IP and usually the use of advanced packaging technology which is costly and not China’s strength. It will take time to see whether chiplets can become a key driver of China’s semiconductor independence in the future.

Bigger Challenges Lie Ahead

In their efforts to further the development of their semiconductor industry, China has seen initial positive results in the mature processes and IC design fields. However, from a long-term development perspective, semiconductor equipment is still an important key. The market for semiconductor equipment and related components and materials is quite fragmented, and the certification process is complex and cyclical. This market is also currently highly concentrated in the United States, Netherlands, and Japan. Hence, it will remain a challenge for China to achieve full autonomy.

Currently, under the ban, China is no longer able to import high-end machines from ASML. How long the existing tools in the facilities supplied by ASML can maintain operation still needs to be evaluated. Although China actively supports local equipment manufacturers, and related manufacturers, such as Northern Huachuang, AMEC, and Shanghai Microelectronics (who are actively expanding their business), these manufacturers still lag by more than 5 generations compared to international first-tier tool manufacturers in terms of product accuracy and performance. Also, although China has invested in dry/wet etching, thin film deposition, and polishing and grinding equipment, there is still a gap in lithography tools. In the latest phase (the third phase) of China’s National Fund’s plan, related news mentioned that one of China’s areas of focus and development is in chip manufacturing equipment, highlighting the important correlation between semiconductor equipment and China’s semiconductor industry development.

China has actively maneuvered through the ban on semiconductor policies in the United States and other countries and has quickly adjusted its policies. However, as semiconductor equipment and related components are still heavily dependent on imports, it will not be easy to achieve full autonomy within five years. Relying on external advanced technology and equipment, we expect China’s semiconductor development will be a gradual process even with the strategy of upgrading technology and gradually increasing manufacturing experience.

On the other hand, China has gained the opportunity and motivation to develop mature processes despite the restrictions comprehensively. Their mature processes can still meet the requirements of current applications, including consumer electronics, automotive electronics, and industrial, among many other applications in the semiconductor market. Despite all these, China is still currently the second-largest semiconductor application market in the world. As their share of mature processes gradually expands in the future and related IC design capabilities gradually improve, China will still play a key role in the development of the global semiconductor industry.

Helen Chiang - Country Manager - IDC

Helen Chiang is the lead of Asia Semiconductor research and the general manager of IDC Taiwan. She is responsible for analysis, forecast, and research of semiconductor supply chain sectors such as IC design, OSAT, and Asia IC design, AI and automobile semiconductor. Since joining IDC in 2007, Helen conducted numerous research and consulting projects about semiconductor, cloud, AI, IoT, security, emerging technology and vertical market in Taiwan and across Asia Pacific region. She also provided professional market analysis and high-value consulting strategy to C-level managers. She not only leads the team to develop new market opportunities successfully, but also to provide customers with long-term growth capabilities.

The China New Energy Vehicle (NEV) market has soared over the past two years and has become the most promising segment in the China passenger vehicle market. Amid a new round of industrial chain adjustments and upgrades centered around NEVs, Internet of Vehicles (IoV) and intelligentization, o rthe addition of AI to a system, NEVs have become new focal points among suppliers and car manufacturers.

  • The realization of smart cockpits and smart driving functions as the demand for new energy passenger vehicle accelerates.
  • Autonomous driving and smart cockpits have become popular areas for IoV market development.
  • Rapid growth in the automotive cloud market given it is the infrastructure behind IoVs.

NEVs Drive the Intelligent Transformation of China Automotive Industry

The China NEV market size bucked the overall market fluctuations in the first quarter of 2023. Not only did the emerging brands maintain their overall development momentum, but traditional car manufacturers achieved phased progress in electrification.

The NEV market has grown over the past few years with increasing penetration. IDC predicts that the penetration rate of NEVs in the China passenger vehicle market will exceed 30% in 2023.

China’s New Energy Vehicles Make Waves in Automotive Industry

According to Bull Wang, Research Manager at IDC China, the electrification and intelligentization of passenger vehicles is a vital indicator of the development stage of the entire automotive market. Electrification makes the underlying architecture of vehicles more suitable for the realization of smart driving and smart cockpits technologies, the two pillars of vehicle intelligentization.

Research shows that autonomous driving technology is applied in the passenger vehicle market primarily in the form of assisted driving functions, especially for vehicles in the RMB 200,000–400,000 price segment. In terms of smart cockpits, breakthroughs have been made continuously in the dimensions of interaction between vehicles and users, expanding the use cases of cockpits.

In recent years, the industrial upgrading of IoV capabilities is an important support and driving force behind the rapid realization and development of smart driving and smart cockpit technologies.

Vehicle Market Shows the Trend of Electrification, Intelligentization, Networking, and Sharing

A car manufacturers’ launch of many functions is inseparable from the overall upgrading of upstream technologies and product systems in the automotive industry. The vendor led IoV market has formed as an organic combination of technology products for vehicles, roads, communications, cloud infrastructure and platforms, security, services, and solutions. It is now evolving toward electrification, intelligentization, networking, and sharing, among which electrification has been preliminarily completed. Intelligentization and networking are the current market hotspots, and sharing is an important trend in the future development.

Catherine Hong, Senior Research Analyst at IDC China, noted that IoV is an important direction for the integrated application of car manufacturing with software and communications.

With the continuous penetration of assisted driving functions, high-level autonomous driving products have become the mainstream direction with suppliers’ developments focused on technology upgrading and mass production.

Automotive Cloud Will Achieve a Compound Annual Growth Rate (CAGR) of 53.6% Over the Next Five Years

Automotive cloud refers to cloud computing infrastructure*, platforms, and use case solutions to meet the digitization and intelligent transformation of the automotive industry. This includes automotive industry suppliers, main engine manufacturers, and industry users of intelligent vehicles.

IDC predicts that the China automotive cloud market will continue to hit new highs in its growth, exceeding RMB 60 billion in 2027, at a five-year CAGR of 53.6%.

Yang Yang, Research Manager at IDC China, emphasized that the intelligent networking of vehicles has redefined the relationship between cloud and industry. The cloud is the production system, data and algorithms are competitive advantages, and software redefines products and services.

IDC Analyst Viewpoint

Looking ahead, with the further popularization of new energy vehicles, the rapid development of new technologies such as intelligentization, networking and autonomous driving, software-defined vehicles will drive the continuous transformation and upgrading of the automotive industry.

This will also reshape the vehicle industrial chain, leading to a new market competition landscape. How enterprises in the industrial chain will leverage their capabilities, make courageous transformations and seize market opportunities will become the top priority for automotive industry players.

*Cloud computing infrastructure includes public cloud infrastructure services and private cloud infrastructure construction; cloud solutions include platforms and application solutions hosted on various types of cloud infrastructure.

Bull Wang - Research Manager - IDC

As a research manager for client systems research in IDC China, Bull Wang has his research focused on topics of autonomous vehicle, connected vehicle, new energy vehicle, next-generation mobility service, and other automotive-relevant topics. Bull is responsible for conducting research and analysis for China and the global market, providing services for tech buyers, tech vendors, and tech watchers in the automotive industry. Prior to joining IDC, Bull had experience in conducting market research projects, such as brand health tracking, campaign evaluation, car clinic, and consumer portrait. His other experiences include social media monitoring for acquainting public opinion on brand and product. Bull has long served the leading companies in automotive industry, including Volkswagen, BMW, and Lexus, among others, with experience in project management on both agency and client sides. Bull graduated from China Foreign Affair University, majoring in diplomacy, and obtained a Law bachelor's degree.