Last week, a select group of senior print and imaging executives gathered in London for IDC’s Print and Imaging Leadership Dinner. During this invitation-only evening, a conversation unfolded between IDC analysts and the people shaping the industry, moderated by IDC’s Sandra Ng.  

What came out of that dinner? Some of the discussions reaffirmed what many already suspected. But some of the insights revealed will fundamentally change how forward-thinking vendors approach the next 18 months. Here’s a taste of what was discussed, and why you’ll want to be in the room for one of IDC’s executive dinners next time.  

The buying committee has expanded, and most vendors are still selling to the wrong people  

Two years ago, a print deal sat with IT and procurement. That’s no longer the world we’re operating in. IDC’s 2026 European Print Survey, covering 2,000 organisations across eight markets, revealed that the stakeholder landscape has shifted dramatically. The conversation that used to happen in one room now happens in four.  

The implications for how vendors structure their go-to-market approach are significant, and the dinner surfaced a very specific playbook that the those gaining the most ground are already executing. We’ll leave the details for the briefing room.  

Security just overtook cost reduction as the #1 investment driver in print. 

A striking 24% of European technology buyers now cite security and compliance as their primary reason for investing in print. That puts it ahead of both cost reduction and productivity.  

This is more than a repositioning opportunity, as it moves the conversation to a different level within the organization,  with a different buyer. Those in the room heard exactly which messaging reaches the CISO, which regulatory triggers are opening budgets right now, and where the hardware story needs to evolve to stay relevant.  

IDC predicts that 40% of worldwide new office MFP shipments will be classified as AI MFPs by 2027. The vendors with a credible roadmap published today will be the ones with a strategic seat in 24 months. Those without one are already behind.  

The buyer has already formed a view before your sales team picks up the phone  

This was the session’s sharpest insight, and the one most likely to keep vendor CMOs up at night.  

GenAI-sourced web traffic grew 1,200% between 2024 and 2025. Two in three searches today end without a single click. Buyers are shortlisting vendors, forming preferences, and making preliminary decisions inside AI assistants, before they’ve seen your website, opened your brochure, or taken a sales call.  

IDC’s Gala Spasova gave a demonstration that stopped the room. When major AI assistants were asked the questions a head of digital workplace would actually type, around 30 vendor names came back consistently. Not a single print OEM appeared. When the question became print-specific, all the familiar names showed up.  

The print category is owned. The workplace category, where your buyers are actually looking, is invisible.  

What it takes to change that, and how fast it compounds once you do, was laid out in detail at the dinner. The short version: it’s not pay-to-play, and the window to act is narrow.  

Three places the money is actually moving in 2026, and the 12–18 month window you can’t afford to miss  

IDC analysts Jacqui Hendriks and Gala Spasova mapped out three near-term growth areas where European buyer investment is already building, from value-add software and services through to Intelligent Document Processing and a sustainability play that changes both the buyer and the budget.  

The most time-sensitive of these? A three-way alliance opportunity, vendor, channel, certified refurbisher, that’s unserved by the larger SIs and telcos, but not for long. European refurbished device shipments grew 28% in 2025. Demand is running well ahead of vendor readiness. The potential of such a model was discussed at the dinner in some detail.  

The commercial model shift that separates the winners  

The evening closed with a discussion on what’s actually different about the vendors capturing European growth. It’s not just what they’re selling. It’s the contracts they’re willing to sign, the conversations they’re prepared to have, and the partnerships they’re building now.  

Roberto Alunni and Phil Sargeant laid out, with uncomfortable precision, the behaviours that distinguish vendors gaining ground from those defending yesterday’s revenue. Some of it is replicable quickly. Some of it takes 18 months of investment to build. All of it was on the table.  

Were you in the room?  

If you weren’t at IDC’s Print & Imaging Leadership Dinner, or if you’re wondering how to get on the guest list for the next executive dinner, now is the time to reach out. Events like this are where the defining conversations happen: the information and insight that doesn’t make it into LLMs and the strategic debates that shape how the market moves, alongside networking and the connections that open doors.  

Whether your focus is European print and imaging, AI-driven workplace transformation, digital sovereignty, channel partnerships, or any of the many other topics shaping the European technology landscape, IDC brings together the senior leaders and the research to drive the conversation forward.  

To find out more about IDC’s European print and imaging research programme, or to join the conversation at our next event, contact your IDC representative or simply fill in our contact form.  

IDC’s European print and imaging research covers 2,000 organisations across Czech Republic, France, Germany, Italy, Poland, Spain, the UK and the Nordics, across 15 verticals. The 2026 European Print Survey data underpinning this dinner is available to IDC clients and select briefing participants.  
Phil Sargeant

Phil Sargeant - Senior Program Director, Imaging and Hardcopy Devices and Document Solutions, European Region

Phil Sargeant is IDC’s leading expert in the field of imaging, hardware devices and document solutions. As senior program director, he researches and reports on the key aspects of the multifunction, production and large format printer markets and is also…
Gala Spasova

Gala Spasova - Senior Research Manager, Europe Smart Office and EMEA Content & Knowledge Management Strategies

Gala Spasova is a senior research manager in IDC’s Workplace & Imaging team. Her research focus is on intelligent workplace and management. She explores the intersection of technology, sustainability, and workplace transformation, and how they can create positive social and…
Roberto Alunni

Roberto Alunni - Senior Research Director, EMEA Data & Analytics

Roberto Alunni is a Senior Research Director at IDC for imaging, print, and document solutions research across the EMEA region. He is responsible for strategic and operational implementation and leads an international analyst team. He is a specialist in imaging…
Sandra Ng

Sandra Ng - Senior Vice President, WW and APJ Research

Sandra Ng is Senior Vice President at IDC and the Global Domain Leader for Devices, Consumers, Imaging, and Japan. Based in Singapore, she advises technology buyers and vendors worldwide on technology investments, financial priorities, and go-to-market strategies. She leads a…

过去,ERP帮助企业把业务“管起来”;现在,AI正在让ERP把业务“跑起来”。

国际数据公司(IDC)于2026年5月发布的《IDC 中国AI增强的企业级ERP市场份额,2025:AI增强驱动下的中国ERP市场格局》(Doc# CHC54272126,2026年5月)报告显示,2025年,中国 AI-enabled ERP 市场规模达到3.157亿美元,同比增长96.1%。这一高速增长表明,中国企业对ERP智能化升级的投入正在快速释放,AI能力正成为企业管理软件市场的新增长引擎。

需要说明的是,IDC对于 AI-enabled ERP 市场的统计维度,聚焦于ERP场景中由AI产品、AI能力或AI相关模块所产生的收入,不包括传统ERP产品本身的收入。因此,该市场规模反映的是企业在ERP智能化升级过程中,对AI能力的新增投入与采购规模,而非整体ERP软件市场规模。

这一高速增长的背后,并非简单的功能叠加,而是ERP产品逻辑正在发生根本性转变。企业不再满足于用ERP“记录发生了什么”,而是希望系统能直接“参与业务执行”。市场的快速扩张,恰恰反映了这种需求侧的变化正在倒逼供给侧的产品重构。

ERP正在从“记录系统”走向“执行系统”

传统ERP的核心价值,是流程标准化、数据集中化和管理可视化。企业通过ERP记录业务、管理流程、沉淀数据,让组织运行更加规范。但AI进入ERP之后,系统的角色正在发生变化。AI-enabled ERP不再只是回答 “发生了什么” , 而是开始帮助企业判断 “接下来可能发生什么” “应该如何处理” “哪些任务可以自动完成” 。

在财务、供应链、生产、采购、销售和经营分析等场景中,AI能力正在帮助企业实现需求预测、异常识别、资源调度、智能推荐和自动化执行。ERP的价值,也正在从“管流程”走向“提效率、控风险、助决策、促执行”。

市场变化:智能体正在把ERP带入新阶段

当前,中国AI-enabled ERP市场的增长,主要来自企业对智能化运营能力的迫切需求。随着业务复杂度提升,企业不再满足于ERP系统对流程和数据的被动管理,而是希望系统能够基于实时数据进行分析、预测和行动建议。

生成式AI和智能体的成熟,正在改变ERP的产品形态和使用方式。自然语言交互、业务智能体、跨模块任务执行和自动化决策支持,使ERP从“人找功能”逐步走向“系统理解意图并主动服务”。

与此同时,AI更深入参与企业数据处理和业务决策,也带来了新的安全与合规要求。未来,权限控制、模型治理、数据安全、审计追踪和决策可解释性,将成为企业部署AI-enabled ERP时的重要考量。

AI-Enable ERP市场正在形成三条演进主线:

IDC认为,AI-enabled ERP的下一阶段发展,不是给传统ERP简单增加一个AI助手,而是围绕数据、流程、智能体和治理能力,重构企业软件的使用方式与价值边界。从近期头部厂商的产品演进方向来看,市场正在形成三条清晰主线。

第一,ERP入口正在从“功能菜单”走向“业务意图”。随着生成式AI和智能体能力的成熟,ERP系统的交互方式正在发生变化。未来,用户不再需要在复杂菜单中寻找功能,而是可以围绕业务目标,通过自然语言交互、任务触发和智能推荐完成相关操作。例如,SAP围绕Autonomous Enterprise推出相关产品组合,用友发布YonClaw企业超级智能体,金蝶推出灵基企业AI操作系统以及浪潮数字企业发布的Mano企业级智能体平台,均体现出厂商正在将AI能力从单点工具延伸到业务入口和流程协同层。IDC认为,面向业务意图的智能交互,将成为AI-enabled ERP提升用户体验和业务效率的重要方向。

第二,智能体正在从“辅助应用”走向“流程执行载体”。过去,AI在ERP中的应用更多集中在数据查询、内容生成、报表撰写和知识检索等辅助性场景;未来,智能体将更深地嵌入财务、供应链、生产、人力和经营分析等核心业务流程,承担分析、判断、调度、预警和执行等连续任务。企业对AI能力的关注,也将从交互体验和响应准确性,进一步转向其能否稳定、安全、可治理地进入业务流程,完成从洞察生成到任务执行的闭环。

第三,市场竞争焦点正在从“功能完整”转向“智能落地”。传统ERP竞争主要围绕模块覆盖、行业经验和实施能力展开;AI-enabled ERP时代,新的竞争焦点将转向数据基础、业务语义理解、智能体编排、流程执行能力、安全治理和行业场景沉淀。IDC认为,企业不会只为“有AI”买单,而会更加关注AI能力能否带来可衡量的效率提升、风险降低和决策改善。未来,能够将AI能力真正融入核心业务流程,并形成可复制行业实践的厂商,将在市场竞争中获得更大优势。

IDC中国企业级应用软件市场高级研究经理徐文婷认为,2025年中国AI-enabled ERP市场的高速增长,表明ERP智能化升级正在从概念验证进入加速落地阶段。由于该市场统计的是ERP场景下AI产品、AI能力和AI相关模块的收入,而非传统ERP产品收入,因此其增长更能反映企业对AI驱动管理软件的新增需求。未来,AI-enabled ERP将不再只是ERP的功能增强,而是企业智能运营体系的重要组成部分。随着生成式AI、智能体、云原生架构和行业数据能力进一步融合,ERP系统将在企业经营管理中承担更主动、更智能、更关键的角色,推动企业软件市场进入以智能化价值为核心的新阶段。

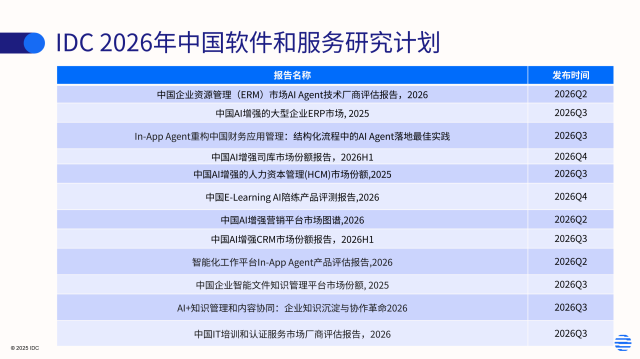
IDC 2026年中国软件和服务领域研究计划:

文中引用的数据与观点来自IDC最新发布的ERP市场研究报告。无论您是希望深入了解市场数据、探讨报告发现,还是有定制化研究需求,IDC中国分析师团队期待与您进一步交流。

请点击此处与我们联系。

Wenting Xu

Wenting Xu - Senior Research Manager

Wenting Xu, senior research manager with IDC China's Enterprise Application Research, focuses on research and analysis of the China enterprise system and software area. She provides intelligence and consulting services for local and multinational corporation IT vendors. Wenting has developed a deep…

Artificial intelligence has been part of the telecom conversation for years. What is changing now is its role and scale. 

AI is no longer limited to isolated use cases or innovation initiatives. It is increasingly influencing core infrastructure decisions, from data center strategy to network architecture and investment priorities. 

Across EMEA, telcos are moving from experimentation to more structured, large-scale adoption. 

AI investment in telecommunications is accelerating across EMEA 

AI and generative AI spending in telecommunications is growing rapidly. In EMEA, spending is expected to increase at a compound annual growth rate of 31.8% between 2024 and 2029. 

Most telcos are already using, or planning to use, AI and machine learning to optimize network operations, improve customer experience, and explore new revenue streams. 

At the same time, operators are becoming more pragmatic. There is increasing focus on aligning AI ambitions with what existing data, cloud, and operational capabilities can realistically support. 

AI is reshaping telco infrastructure priorities 

As AI adoption scales, it is beginning to reshape how telcos think about infrastructure. 

Data center investments are being driven by workloads such as AI inferencing and large language model training. These require high-performance, low-latency environments and are pushing telcos to rethink how compute, storage, and networking are designed and deployed. 

This is reflected in several shifts: 

  • Closer collaboration with hyperscalers and ecosystem partners  
  • Expansion of colocation and edge deployments  
  • Greater focus on GPU-intensive infrastructure  

Infrastructure is becoming more closely aligned with the need to support real-time, distributed AI workloads. 

How short-term ROI is shaping AI adoption in telecom 

While investment is increasing, telcos are prioritizing use cases that can deliver measurable value in the near term. 

Employee productivity, customer experience, automation, and operational efficiency are key focus areas. These areas offer clearer paths to return on investment compared to more experimental AI initiatives. 

This creates a balance between near-term impact and longer-term transformation goals, such as autonomous networks and more adaptive service models. 

Data and cloud foundations remain a key challenge for AI 

Despite strong momentum, many telcos are still working to align their underlying capabilities with AI ambitions. Strong security and data privacy protections are fundamental to ongoing telecom investment in AI capabilities. If a capability or vendor partner is not trusted it won’t be implemented in production. 

Challenges around data quality, data management, and cloud readiness can also practically limit the speed and scale of AI adoption. As a result, AI strategy is closely linked to broader transformation efforts, including modernization of data platforms and investment in hybrid infrastructure. AI capabilities often act as multipliers of existing capabilities. The better the foundation the greater the impact and ability to scale. 

What this means for telecom operators 

AI is becoming a cross-functional priority that connects network, IT, and business strategy. 

Infrastructure planning, partner selection, and operating models increasingly need to reflect AI requirements. At the same time, telcos are working more closely with partners to access capabilities, accelerate adoption, and manage complexity. 

As AI becomes more embedded, it is also influencing how services are designed and delivered, and how operators position themselves in the market. 

Download the full analysis 

AI is one of the defining trends shaping the telecom market. In the IDC eBook State of the Telco Market 2026, you’ll find detailed data, forecasts, and analysis on how AI investment, infrastructure, and operating models are evolving. 

Download the eBook to explore the data behind these developments and better understand how the telco landscape is changing. 

If you’re currently evaluating how AI will impact your infrastructure, operations, or partner strategy, our experts are happy to exchange perspectives. Whether you’re at an early stage or already scaling initiatives, we welcome the conversation. Get in touch with our team to continue the discussion. 

The story being written by the AI market is extraordinary by almost any measure. OpenAI’s revenue grew from $2 billion in 2023 to $20 billion in 2025. Anthropic’s annualized revenue run rate surged from $87 million in January 2024 to $30 billion by April 2026, a trajectory that Salesforce took 20 years to achieve. NVIDIA’s revenue grew eightfold from $27 billion to over $216 billion between 2023 and 2026, achieving that growth in just one-third of the time it took Apple to do so during its heyday between 2007 and 2015. By nearly every reported metric, the AI market is delivering growth at a scale and speed that defies historical comparison.

Yet a narrative has emerged about how much of that growth reflects genuine market demand and how much reflects the circular financing structures that have become a defining feature of AI infrastructure investment. Circular financing in AI describes investment structures where the same capital flows simultaneously as vendor payment and equity stake. A company funds its own customer’s revenue while also supplying that customer’s core infrastructure. The result is reported revenue growth that is real but not cleanly separable from investment activity. The answer matters enormously, not just for investors in AI infrastructure companies, but for every enterprise software vendor and technology buyer trying to make sense of what’s actually happening in the market.

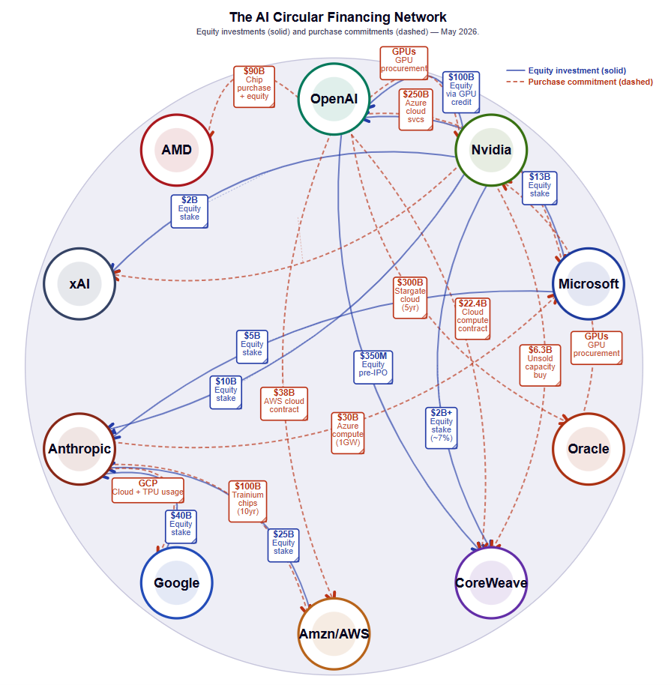
Without getting into any financial analysis of the diagram below, I include it simply to demonstrate the extreme complexity and circular nature of these financial relationships.

Figure 1:

The circular financing problem

Circular financing in AI works through a self-reinforcing loop. NVIDIA committed $30B as part of OpenAI’s $110B financing announced in February 2026, while simultaneously serving as OpenAI’s primary GPU supplier, making it both a major investor in and a vendor to the same company. NVIDIA simultaneously holds equity in CoreWeave, which supplies infrastructure to Oracle, which signed a $300 billion Stargate commitment with OpenAI. Microsoft has invested more than $13 billion in OpenAI while serving as its primary cloud provider, meaning a substantial portion of OpenAI’s rapidly escalating compute spend flows back into Azure revenue. Microsoft has disclosed more than $600 billion in AI-driven remaining performance obligations, of which management confirmed approximately 45% is attributable to OpenAI-related activity. These are just some of the interdependencies that exist, and while they do not make the revenue fabricated, they do make it very difficult to read reported growth figures as clear evidence of external market demand expanding at the rates that match recent headlines.

Stripping out circular flows to estimate genuine arm’s-length revenue is nearly impossible from the outside because none of these companies has any incentive to disaggregate them. What is clear is that OpenAI’s compute costs, projected to reach tens of billions annually, still dramatically exceed its current revenue. While their internal projections point to massive revenue growth over the longer term, the company is expected to remain unprofitable through at least 2029, with positive cash flow not expected until 2030. The infrastructure layer is being built on a combination of genuine demand and financial engineering, and the two are not currently separable from reported figures alone.

Why the application layer is the real signal

This is why revenue growth on the enterprise application layer has become the most important signal in the entire AI market. Enterprise application software does not carry a circularity problem. When an ERP vendor reports AI-driven ARR expansion, when an HCM platform demonstrates higher attach rates on AI-enabled capabilities, when a finance or procurement solution delivers measurable process efficiency gains that a CFO chooses to fund again at renewal, those signals reflect real buyers making real budget decisions based on perceived business value. There is no investment web distorting the demand signal. The revenue either reflects a genuine willingness to pay for demonstrated outcomes, or it does not.

What’s interesting is that we’ve seen this same exact pattern play out multiple times before during historical tech market revolutions. In each of the last several significant platform transitions, the application layer lagged the infrastructure layer in value creation, but eventually surpassed it as the platform matured.

The historical pattern

During the internet buildout, infrastructure companies captured the overwhelming share of market value. Cisco dominated with networking equipment and briefly became the most valuable company on earth, reaching a market cap of nearly $560 billion in March 2000. Companies like Sun Microsystems and Dell supplied servers, and even fiber optic cable makers like Corning and JDS Uniphase had their moment. Meanwhile, the application layer was largely characterized by money-losing dot-com ventures that collapsed when the bubble burst. But over the long term, application layer players like Amazon, Salesforce, and Google eventually dwarfed those companies.

The cloud era was no different. AWS launched in 2006 and, for years, held a dominant share of the cloud market, while enterprise SaaS applications were still proving their business model viability. IDC’s Worldwide Semiannual Public Cloud Services Tracker shows that by 2020, the SaaS application layer had grown to $148 billion in revenue, nearly half of the total $312 billion public cloud market, while IaaS, despite its faster growth rate, remained a significantly smaller share of the overall pie. Once the cloud infrastructure platform matured, value creation in the application layer far exceeded it.

Looking at the current AI boom, it’s following the same early-stage script. NVIDIA first became the world’s most valuable company in mid-2024, and we are in the middle of an AI infrastructure super cycle with trillions of dollars flowing into compute, datacenter construction, and power generation. Meanwhile, enterprise AI application revenues remain nascent relative to the trillions being invested in the infrastructure layer beneath them.

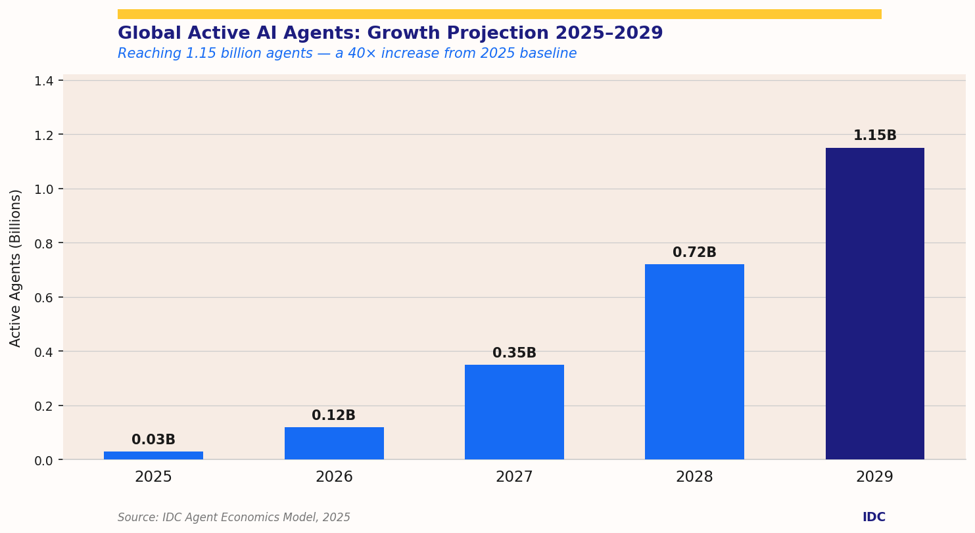
Agentic AI is triggering a fundamental reconsideration of how companies invest in packaged software, as AI agents effectively become the new enterprise apps. IDC’s spending forecasts project AI investment growing 31.9% annually between 2025 and 2029, reaching $1.3 trillion. These are real demand signals, and they are large enough to sustain significant growth at the application layer if enterprise software vendors can connect their AI capabilities to the business outcomes buyers are seeking.

The monetization gap that still needs closing

The monetization gap, however, remains significant and is not yet closing at the pace the market requires. IDC’s Future Enterprise Resiliency and Spending Survey (FERS) finds that few organizations report measurable financial results from their AI projects, despite widespread improvements in individual productivity. While most organizations aspire to grow revenue through AI initiatives, the majority have yet to achieve that goal. This distinction between individual productivity gains and organizational-level financial outcomes is one that enterprise software vendors have been slow to confront directly. Productivity at the individual level is real, documented, and genuinely valuable. Translating those gains into measurable business results that justify enterprise software pricing premiums is a fundamentally different challenge, and one that buyers are increasingly demanding vendors address more explicitly during renewal and contract-expansion discussions.

What vendors must do now

Closing that gap is the defining commercial challenge for enterprise software vendors over the next 12 months. The most urgent shift is from feature availability to outcome accountability: specific, auditable improvements in process efficiency or cost reduction that survive CFO scrutiny at renewal. Transparent commercial models follow from that. If buyers have to build the business case themselves, or fund significant professional services to reach value, adoption curves will flatten and renewal risk will rise. The competitive differentiator in this environment is not model sophistication. It is workflow transformation. Enterprises evaluate software on whether it changes the workflows that actually drive their business.

The infrastructure layer of the AI market may ultimately prove resilient. The circular financing dynamics, while real, are not unlike the capital formation structures that funded prior technology infrastructure buildouts, and genuine demand for compute at scale is not in dispute. The application layer is not a downstream beneficiary of the AI infrastructure boom. It is the proof point on which the entire narrative depends.

Eric Newmark

Eric Newmark - Group Vice President & General Manager of IDC's SaaS, Enterprise Software, CX and Workplace Solutions Division

Eric Newmark is Group Vice President & General Manager of IDC’s SaaS, Enterprise Software, CX, and Workplace Solutions Division, which includes several teams of analysts covering SaaS, 18 enterprise application markets, software monetization, business platforms, marketplaces, and services firms focused…

The AI assistant era is wrapping up.

Chatbots, copilots, summarizers—useful, yes, but that’s the warm-up act. What comes next is agentic AI: systems that don’t just respond to prompts but plan, reason, and execute work across your systems, data, and workflows, with or without human augmentation. Executives are putting agentic AI at the center of their business transformations, reimagining how people work with AI-powered workflows.

The stakes are not theoretical

Business models, skills, economics, governance, compliance, and security requirements are changing rapidly—creating massive, rapidly evolving risks. The numbers bear that out:

CEOs, board members, and shareholders are demanding AI results now. Waiting will stifle market share, growth opportunities, and innovation. Early winners will widen their advantage by applying proven AI learnings across new use cases. In the AI economy, continuous learning creates speed and compounding results.

This isn’t an upgrade. It’s a new operating model

Where a copilot drafts an email, an agentic agent manages the entire workflow behind it: pulling data, making decisions, escalating exceptions, closing the loop. Autonomously. Persistently. Across systems. With or without human intervention. This requires executives to redesign processes with AI at the center, not bolted on, but as the heartbeat of every workflow.

IDC finds that by 2027, enterprises will need architectures that support synchronous movement of data, apps, workflows, and agents. If your current stack wasn’t designed for that, the clock is already running.

“Agentic systems introduce a fundamentally different risk profile than the AI tools most enterprises deployed in 2023 and 2024.”

The implications extend beyond architecture. Copilots operated under human supervision—every output reviewed, every action confirmed. Agents operate differently: they initiate, chain decisions, and act across systems in real time. A misconfigured agent doesn’t just produce a bad answer; it executes a bad decision, potentially at scale, before anyone notices. That shift from human-reviewed output to autonomous action is where governance frameworks built for the assistant era break down entirely.  Governance, security, and orchestration are critical investment requirements, not an afterthought for effective and efficient AI outcomes. Governance and security must be built in from day one, the business and career risks are too high to treat them as afterthoughts. Every digital worker will be governed like a human employee.

Executives who recognize this distinction early hold a structural advantage. They’re not just deploying faster—they’re building the operational muscle, audit infrastructure, and trust frameworks required to scale safely. Those who treat agentic AI as a continuation of their copilot strategy will face compounding remediation costs as agent portfolios grow, and governance gaps widen.

The competitive divide forming now isn’t between companies that have AI and those that don’t. It’s between organizations that have learned to deploy agents with discipline and those still improvising. Speed without structure is exposure. Structure without speed is irrelevance. The executives navigating both are the ones establishing the terms. 

Seven domains. One framework

IDC’s deployment framework surfaces seven domains where early decisions have outsized downstream impact. Get them right and you build momentum:

  • Business outcomes
  • Workflow design
  • Data readiness
  • Runtime architecture
  • Governance
  • Operating model
  • Workforce

Each domain highlights key considerations for executives to gauge their deployment and governance readiness. After the self-assessment, the research provides deep dives into critical areas of transformation—software development, partner and AI infrastructure selection, and IT operations. These recommendations serve as a discussion guide for your agentic AI journey.

Key takeaways for executives

  • Treat agentic AI as a new operating model, not an upgrade to your copilot strategy.
  • Governance and security are now a competitive differentiator—not an IT compliance exercise.
  • The 7-domain framework is your cheat sheet: use it to reduce deployment risk and extract compounding value.
  • Early movers will set the terms. Waiting isn’t neutral—it’s a strategic concession.

Stephen Elliot

Stephen Elliot - Group Vice President, Software Development and IT Operations

Stephen Elliot manages multiple programs spanning IT Operations, Enterprise Management, ITSM, Agile and DevOps, Application performance, Virtualization, Multi-Cloud Management and Automation, Log Analytics, Container Management, DaaS, and Software Defined Compute.   Mr. Elliot advises Senior IT, Business, and Investment Executives globally in the creation of…

Strip away the keynote theatrics and the RTX Spark launch at Computex comes down to a single wager: a meaningful share of future AI work belongs on the PC rather than in a data center. NVIDIA and Microsoft built a Windows platform around a strong GPU and a deep pool of unified memory because they want models and agents running where the user sits. For the next year or two, open-weight models are what make that wager credible. Over a longer horizon, the bet only pays off if the companies behind the best frontier models are willing to change how they do business.

To date, the Windows AI message has leaned on the neural processing unit (NPU) and the idea of small, persistent AI workloads carried out locally. But the early returns were thin. Copilot+ shipped with fewer headline features than promised, and developers never showed up to write for the NPU in any meaningful numbers. It says something, then, that this launch put a GPU and an agent runtime at the center, and went silent on the NPU and on Copilot+ branding. Both will presumably be present in these as-yet-released machines. The choice to keep them offstage is the part worth noting.

Governance first, compute second

Most of the engineering that should interest corporate buyers has little to do with raw compute. NVIDIA and Microsoft added containment and identity controls to Windows and wrapped them in an agent layer called NVIDIA OpenShell. An administrator can spell out exactly what an agent may reach, push sensitive requests to a model running on the machine, and scrub identifying details before any prompt leaves for the cloud. IT teams have made clear they will not let autonomous software roam across managed devices without that kind of governance. Whether it works as advertised is unproven, but the design attempts to answer ITDMs’ legitimate concerns.

Local inference = lower cost

The case for keeping inference on the device is mostly about money. Privacy, security, and lower latency matter too — but the key is that a generous memory pool attached to a robust GPU lets a capable model sit resident and respond locally. The work does not run up charges in a cloud instance every time an agent acts. Once agents are working all day underneath ordinary tasks, paying cloud rates for every token they burn stops being sustainable well before the technology hits any wall. Shifting a portion of that load onto hardware the buyer already owns is one of the few ways the forecasted agentic AI ramp proceeds unimpeded.

Today, open-weight models may be capable enough to run useful agents on a machine like the RTX Spark. That’s the near-term proof point. The best models, though, still sit behind cloud subscriptions from Anthropic, Google, and OpenAI. Companies trust those models, and the AI firms behind them have built large businesses on running inference in their own data centers. Moving part of that work onto a customer’s GPU asks them to do more than ship a smaller model — it asks them to redraw the business: pricing and packaging a hybrid where some inference runs locally and some runs in the cloud. Local tokens for the simple jobs, cloud tokens for the heavy lifting. None of the foundation model companies have offered a subscription like that yet. Until one does, on-device intelligence will run on open models that will likely always trail the frontier.

Price, timeline, and the real test

The practical limits are easy to see. No RTX Spark notebook prices have been set, and launch configurations will almost certainly sit at the top of the premium market. Average selling prices for notebooks have drifted upward for years, and that was before memory costs exploded. Today’s memory pricing will make a fully loaded 128GB RTX Spark system quite steep. The buyers willing to pay for the maximum build will mostly be developers and creative professionals who already understand what running models locally gets them. Everyone else is further out.

None of this makes RTX Spark the mainstream arrival of the agentic PC. The silicon looks capable, and adding a fourth serious contender alongside Intel, AMD, and Qualcomm should sharpen all of them. The shift to more AI compute on device is the more straightforward part of this equation. The questions that determine whether this matters are softer and slower: whether Microsoft’s agent platform earns the trust of cautious IT departments, and whether the frontier labs conclude that some of their inference belongs on the customer’s desk. Settle those two and RTX Spark will look ahead of its time.

Tom Mainelli

Tom Mainelli - Group Vice President, Device & Consumer Research

Tom Mainelli heads the Device & Consumer Research Group, overseeing a wide array of hardware and technology categories catering to both home and enterprise markets. His team's research spans PCs, tablets, smartphones, wearables, smart home devices, thin clients, displays, and…

Most EMEA organisations have the intent to scale AI. What they are missing is a way to execute. On May 28, 2026, IDC’s EMEA Digital Leaders Hub brought together Martina Longo, Daniel Saroff, and Giulia Carosella for a live session drawing on 12 months of conversations within the Hub and fresh IDC research. Below is a brief overview. The full recording is available on demand. 

AI maturity in EMEA in 2026: why execution, not intent, is the real gap 

IDC’s latest MaturityScape Benchmark (EMEA, N=583) tells a clear story: 63% of EMEA organisations are still in the two lowest AI maturity stages. Fourteen percent are ad hoc: scattered initiatives, no coherent strategy. Forty-nine percent are opportunistic, running pilots but without the repeatability needed to scale. Just 2% are effectively scaling AI and Agentic AI initiatives across their organizations, including unlocking AI-driven revenue growth. 

The journey maps from the (Gen)AI Scramble (fragmented, investment-heavy experimentation) through the AI Pivot (structured scaling) to the Agentic Organisation (AI embedded across operations). Most EMEA organisations are stuck in the transition between the first and second stage. The blocker is almost never ambition. It is the ability to execute. 

Why AI adoption in EMEA is stalling: five challenges organisations need to address 

Notably, 49% of EMEA organisations have already shifted their focus from launching new AI pilots to improving existing initiatives The experimentation phase is peaking, and EMEA organizations are no longer seeking new tools but instead focusing on making current AI work effectively first. But five structural challenges continue to slow progress: 

  • Competition for resources among digital initiatives 
  • Regulatory uncertainty slowing deployment decisions 
  • Resistance to process change within the business 
  • Difficulty quantifying and demonstrating AI ROI to the board 
  • Lack of executive sponsorship or organisation-wide buy-in 

These are not isolated problems. They compound each other. Without a shared language for value, the resource conversation is difficult to win. The webinar addressed all five, and the one that generated the most discussion was ROI. 

Measuring AI ROI: why cost savings are not enough 

The most common reason AI initiatives stall is not technical. It is that no one agreed upfront on what success looks like. IDC’s AI Business Value Benefit framework maps nine dimensions where AI creates measurable impact, spanning Revenue Generation and Customer Experience through to Sustainability, Time to Market, and Business Resilience. Most organisations are measuring only one or two of these dimensions and are therefore systematically underselling the value they already have. 

“Know what you want to achieve and how you will measure it” 
  — Alex Catmur, Commercial Director Digital, AtkinsRéalis 

Three practices that came up consistently in the session: 

  • anchor every initiative to a specific business outcome before selecting any tool: Start with value drivers, not technology 
  • if no executive has a stake in the metric, the initiative will eventually stall: Align to KPIs executives already own 
  • productivity gains are visible; resilience and trust are harder to quantify but equally real, and the framework accounts for both: Separate direct and indirect value 

The session also walked through a detailed case study of a global professional services firm that went from no shared ROI lens to confident scale decisions. If that is where your organisation is at present, it is worth watching the recording to hear how they structured the turnaround. 

How the CIO role is evolving in the age of AI 

IDC’s WW C-Suite Tech Survey (EMEA, N=300) makes the expectation clear: 42% of the broader C-suite now expects the CIO to lead digital and AI transformation with a major focus on creating new revenue streams. That expectation is growing faster than the formal authority that would make it achievable. 

The digital leader of the future, as IDC frames it, is an architect of three things: Workforce (orchestrating AI-fuelled change management), Resilience (modernising IT for strategic alignment), and Value (demonstrating what digital technologies actually deliver for the business). 

Three steps for digital leaders looking to prepare for this shift: 

  • not called in to implement choices that have already been taken: Get in the room before decisions are made 
  • accountability for results, not just go-live dates: Own the business outcome, not just the delivery 
  • design AI deployments to grow and withstand failure, not just to ship: Architect for scaling and recovery from the start 

The session went into considerably more detail on each of these steps, including the structural and political dynamics that make them harder in practice than they appear on paper. 

A practical AI transformation playbook: four steps that matter

The session closed with a synthesis that cuts through the complexity. Leading AI-fuelled business transformation comes down to four sequential actions: 

  • modernise architecture and data before scaling AI; pilots built on brittle infrastructure do not survive production: Fix the foundation 
  • anchor every initiative to a KPI an executive already owns; no metric, no mandate: Define the value 
  • redesign workflows and roles alongside the technology; AI layered onto old processes delivers expensive old results: Change the model 
  • run experiments to disprove bad assumptions quickly; promote only what survives to a funded pilot with a scale plan: Scale what works 

Straightforward to state, harder to execute. The webinar covers what this looks like in practice, including the Q&A that followed. 

The complete recording covers the full AI Business Value Benefit framework across all nine dimensions, the case study of a professional services firm moving from pilot to scale, the detailed best practice sessions on ROI measurement and the evolving CIO mandate, and the Q&A with the IDC analysts. If the topics covered are relevant to your organisation’s AI journey, IDC’s EMEA Digital Leaders Hub offers advisory support, benchmarks, and peer roundtables for CIOs and digital leaders navigating this transition. Reach out via the contact form to continue the conversation. 

Martina Longo

Martina Longo - Research Manager, CIO and CTO Buyer Insights

Martina Longo is a Research Manager for the CIO and CTO Buyer Insights program. Her research focuses on the emerging priorities, programs and decision making processes linked to the modern CIO/CTO agenda. This includes advancing AI from experimentation to operational…
Daniel Saroff

Daniel Saroff - Group Vice President Research and Consulting

  Daniel Saroff is Group Vice President of Research and Consulting at IDC, where he leads the research agenda focused on end-user technology leaders, including CIOs and their direct leadership teams. He oversees a team of analysts and advisory professionals…
Giulia Carosella

Giulia Carosella - Senior Research Manager

Giulia Carosella is a Senior Research Manager in IDC's AI-Fueled Business Strategies team, leading the Worldwide research program. In this role, she researches current and emerging global trends in AI?driven business transformation, examining how organizations can reinvent themselves by leveraging…

What Happened in India’s PC Market in Q1 2026? 

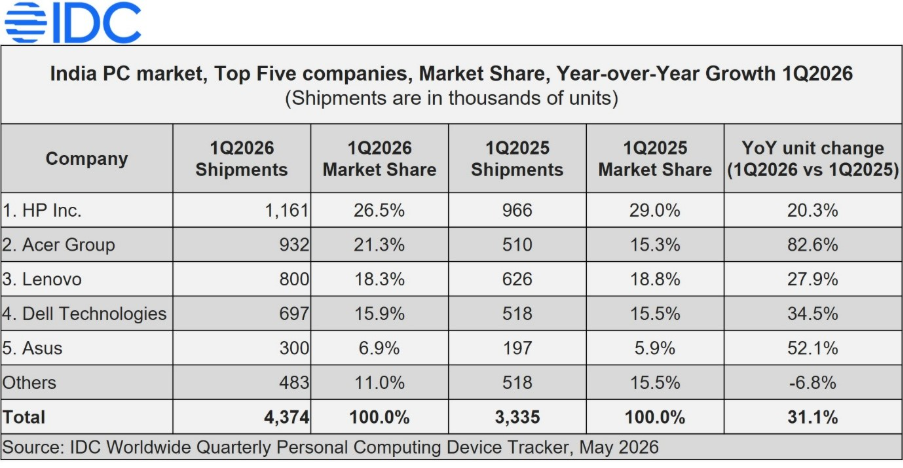
India’s traditional PC market (encompassing desktops, notebooks, and workstations) delivered a standout performance in Q1 2026, with total shipments reaching 4.4 million units, representing 31.1% year-over-year growth, according to IDC’s Worldwide Quarterly Personal Computing Device Tracker. Notably, this marked the third consecutive quarter in which shipments exceeded the 4-million-unit threshold, a milestone that underscores the market’s sustained momentum. The growth came even as PC prices continued to rise due to component shortages. Nonetheless, this reflects strong demand across both consumer and commercial segments, fuelled by digital transformation, enterprise investment, and large-scale education procurement. 

Why It Matters 

The Q1 2026 results signal the resilience of India’s PC market in the face of structural pricing pressures. Here’s what stakeholders should take away: 

  • Vendors should limit dependency on education-led demand and monitor the durability of government procurement pipelines. ELCOT was a major volume driver this quarter, but such big volume projects are rare.   
  • Rising prices are accelerating premiumisation, but they also risk squeezing out price-sensitive buyers in the consumer and SMB segments if unchecked. 

Market Dynamics: What Drove the Outcome? 

Three converging forces shaped the quarter’s strong performance: 

  • ELCOT education project led to notebook surge: The execution of the Tamil Nadu government’s ELCOT education procurement programme was the single largest growth catalyst. It drove the education segment to an exceptional 455.2% YoY growth and propelled the overall notebook segment to 3.3 million units, or a 55.4% YoY increase. 
  • Enterprise investment providing commercial resilience: Sustained domestic and global enterprise spending supported 24.2% YoY growth in the enterprise segment. Workstations, driven by high-performance computing needs in engineering and design, rose 31.8% YoY. 
  • AI adoption and premium segment expansion: Rising demand for AI-capable notebooks helped drive the premium notebook segment (above US$1,000) up 70.1% YoY. Consumer demand for premium devices outpaced commercial, growing 92.4% versus 56.1% YoY. 

Segment Snapshot: Winners and Laggards 

Notebooks: 3.3 million units | +55.4% YoY | Majority of total shipments 

Workstations: +31.8% YoY | Driven by engineering, design, and data-intensive sectors 

Desktops: −13.5% YoY | Elevated prices led to order deferments and cancellations 

Premium Notebooks (>US$1,000): +70.1% YoY | Consumer: +92.4% | Commercial: +56.1% 

AI Notebooks (total): +96.1% YoY  

India PC Market at a Glance: Q1 2026 

  • Total shipments: 4.4 million units (+31.1% YoY) 
  • Third consecutive quarter above 4 million units 
  • Commercial segment: 2.8 million units | Education: +455.2% YoY | Enterprise: +24.2% YoY 
  • Consumer segment: +11.7% YoY | eTailer: +23.1% YoY | Traditional retail: +8.7% YoY 
  • Top five vendors: HP Inc. (#1), Acer Group (#2), Lenovo (#3), Dell Technologies (#4), ASUS (#5) 

Analyst Insight 

“Despite persistent upward pressure on PC prices due to rising component costs, particularly DRAM and GPUs, consumer demand has remained resilient. With prices having increased over the past two quarters and expected to rise further in the coming months, proactive and transparent communication from vendors, partners, and channel stakeholders has encouraged early purchase decisions, thereby helping sustain overall market demand.” 

— Bharath Shenoy, Research Manager, Devices Research, IDC 

Vendor Landscape: Who Won the Quarter? 

HP Inc. retained the top spot with 26.6% market share, driven by ELCOT execution and solid enterprise demand (+27% YoY in commercial). Consumer growth was steady at 8.2% YoY, supported by strong large format retail (LFR) traction. 

Acer Group surged to second place with 21.3% market share, overtaking both Lenovo and Dell. ELCOT billing in the commercial segment, where it captured 25.5% share, was the key driver. A marginal 1.2% YoY dip in consumer shipments due to entry-level supply constraints was the only blemish. 

Lenovo held third with 18.3% market share. Commercial grew 32.3% YoY on enterprise and SMB strength, while consumer grew 20.8% YoY, bolstered by a gaming portfolio surge and e-commerce shipments up 58% YoY. 

Dell Technologies ranked fourth at 15.9% market share. Enterprise demand drove a 37.5% YoY segment increase, with overall commercial growing 38.7% YoY partly from ELCOT fulfilment. Consumer shipments grew 17% YoY despite pricing pressures. 

ASUS rounded out the top five at 6.9% market share. Gaming notebook demand lifted consumer growth 31.9% YoY, and an exceptional 241.1% YoY commercial surge reflected rising SMB momentum. 

IDC Outlook: What’s Next? 

The first half of 2026 is expected to sustain positive momentum, supported by favourable supply allocations, aggressive channel stocking, and front-loaded procurement ahead of anticipated price hikes. However, the second half presents a more cautious picture. 

  • What could sustain growth? Strong enterprise and SMB pipelines would drive 2Q 2026, continued AI notebook adoption, and successful rollout of products like Apple’s mass-market MacBook Neo (launched March 2026) might be some positive drivers for 2H 2026. 
  • What could slow it down? Inventory corrections in Tier 1 and Tier 2 channels, supply-side constraints, rising DRAM and GPU costs, and budget pressures in government and education segments. 
  • What should readers watch next quarter? Whether channel inventory levels normalise, how consumer demand responds to further price increases, and the pace of AI notebook adoption in SMBs. 

“Vendors have so far benefited from favourable supply allocations and are currently managing relatively high inventory levels across Tier 1 and Tier 2 channels. While enterprise and SMB segments continue to support volume-led procurement, shipments might decline in second half of the year. The government and education sectors could face challenges amid rising device prices and constrained budget allocations. The consumer segment may also witness a decline in the second half of the year unless pricing stabilizes. At the same time, Apple’s launch of the mass-market-focused MacBook Neo in March is expected to strengthen its position and potentially expand its presence across both consumer and SMB segments.” 

— Navkendar Singh, AVP, Devices Research, IDC 

Frequently Asked Questions 

Why did the PC market grow so strongly despite rising prices? 

The primary catalyst was the ELCOT education procurement project, which alone drove the education segment up 455.2% YoY and turbocharged notebook shipments. This institutional demand, combined with enterprise investments and early purchasing by both enterprises and consumers ahead of further price increases, more than offset the headwinds from elevated pricing. 

What risks could impact the PC market in 2026? 

The key risks include prolonged component cost inflation (especially DRAM and GPUs), potential inventory overhang in distribution channels, and weakening budget availability in government and education. If prices continue to climb, consumer spending moderation could also temper growth. 

About IDC 

International Data Corporation (IDC) is the premier global provider of trusted technology intelligence, advisory services, and events. With more than 1,000 analysts worldwide, IDC offers global, regional, and local expertise on technology, IT benchmarking and sourcing, and industry opportunities and trends in over 100 countries. IDC’s analysis and insights help IT professionals, business executives, and the investment community to make fact-based technology decisions and to achieve their key business objectives. To learn more about IDC, please visit www.idc.com. Follow IDC Asia/Pacific on X at @IDCAP and LinkedIn. Subscribe to the IDC Blog for industry news and insights. 

All product and company names may be trademarks or registered trademarks of their respective holders. 

For more information, contact Bharath Shenoy, Research Manager — Devices Research, or Navkendar Singh, AVP – Devices Research. 

Bharath Shenoy

Bharath Shenoy - Senior Market Analyst

Bharath Shenoy is a Senior Market Analyst at IDC India. Based in Bangalore, Bharath is responsible for tracking and analyzing market trends of PCs and Printers for Bangladesh. Prior to joining IDC, Bharath has worked with Dataxis as a Telecom…
Navkendar Singh

Navkendar Singh - Associate Vice President, Client Devices & IPDS, IDC India

Navkendar Singh is a Associate Vice President with IDC India, based in Gurgaon. His research domains encompass deep-dive research and insights in and around mobile devices, smart homes, PCs, tablets, wearables, and the printing market in India, Bangladesh, and Sri Lanka.…

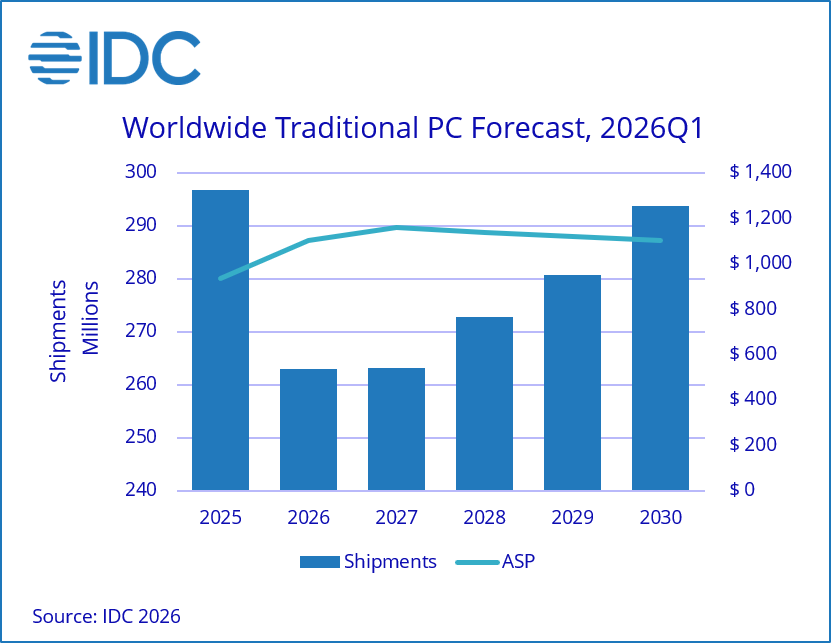
The global PC market is heading into a turbulent second half of 2026, and there’s no quick fix on the horizon. IDC now forecasts global PC shipments will decline 11.3% for the full year, with conditions worsening progressively through Q4, when shipments are expected to fall 20% year-over-year.

The culprit is a persistent memory shortage with no meaningful relief expected before the end of 2027. The knock-on effects are significant: prices are rising and PC manufacturers are struggling to maintain full product portfolios.

Pull-forward demand masked the problem, temporarily

The first quarter of 2026 offered a deceptively encouraging signal, with shipments growing 3% versus the same period last year. But that strength was largely borrowed from the future. Buyers, both consumer and commercial, accelerated purchases ahead of anticipated price hikes and product availability constraints.

“The anticipation of rising prices and of limited availability of some system configurations due to memory and other component shortages has led some end-users to make purchases earlier than anticipated,” said Jean Philippe Bouchard, Vice President of Devices and Consumers at IDC. “We’re not seeing any relief to the memory shortage situation before the end of 2027, which means prices will continue to rise and PC manufacturers will struggle to maintain full product portfolios for the foreseeable future.”

Some of that momentum is carrying into Q2, but the remaining quarters are expected to deteriorate gradually and sharply.

The MacBook Neo factor

One notable wildcard is Apple’s MacBook Neo, which has driven stronger-than-expected notebook demand and prompted IDC to revise its notebook forecast upward. But its ripple effects cut both ways.

“The introduction of the MacBook Neo is putting real pressure on the entire PC ecosystem,” said Jitesh Ubrani, research manager for IDC’s Consumer Devices Trackers. “We expect vendors to respond with a combination of new silicon, a more efficient OS from Microsoft, and aggressive promotional pricing.”

“The competitive pressure from the Neo is providing a partial offset to broader price increases, keeping some low-cost notebook options alive. But the overall trajectory for average selling prices (ASPs) is firmly upward. IDC forecasts ASP growth of 17% in 2026, and even as memory capacity expands over the next two years, pricing is unlikely to return to 2025 levels,” Ubrani added.

What to watch

The PC market is navigating a rare combination of structural supply constraints, macroeconomic headwinds, and platform-level disruption. For buyers, the window for favorable pricing is narrowing. For vendors, the challenge is sustaining portfolio breadth while managing component scarcity and competitive pressure from Apple’s latest hardware.

IDC tracks ongoing developments through its Worldwide Quarterly Personal Computing Device Tracker.

Jitesh Ubrani

Jitesh Ubrani - Director, Consumer Devices Research

Jitesh Ubrani is a Director at IDC leading a team of analysts within the Worldwide Consumer Device Trackers group, covering wearables, augmented reality (AR), virtual reality (VR), tablets, phones, PCs, gaming, and smart home devices, with a focus on market…
Jean Phillippe Bouchard

Jean Phillippe Bouchard - Vice President, Data & Analytics

Jean Philippe (JP) Bouchard is Vice-President, Data & Analytics at IDC Canada. In this role, JP is responsible for leading the team of analysts delivering Continuous Intelligence Services, Trackers and custom research in the Future of Work and Mobility group,…

Fifty percent of organizations are already deploying AI agents in production across multiple business areas. Another 27% have them running in at least one. IDC’s latest Market Glance on agentic AI ecosystems maps the landscape that is making this shift possible. The picture it reveals is both more structured and more dynamic than many organizations currently appreciate.

A market built in layers

Think of the enterprise agentic AI market ecosystem as three interlocking layers. At the surface, there are agents themselves: specialized standalone agents built for specific domains, and in-application agents embedded directly inside the software your teams already use. These agents don’t need an external orchestration layer — they work within the host application’s environment, using its data and functionality to act autonomously on behalf of users.

Beneath that sits a rich set of creation and operation technologies. This is where organizations build, deploy, monitor, and manage agents throughout their full life cycle. It includes multiagent orchestration frameworks, agent discovery and inventory tools (so you know what you’ve deployed and where), and the data foundations (vector databases, knowledge graphs, real-time pipelines) that give agents the contextual grounding they need to work effectively.

Underpinning everything are the execution foundations: cloud and on-premises infrastructure, AI silicon from specialized semiconductor providers, and a growing set of security capabilities including AI security posture management, runtime policy enforcement, and identity and access management for agents. As organizations seek greater control over where and how AI runs, driven by privacy, regulatory and sovereignty concerns, architectural diversity in this layer is accelerating fast.

The convergence you need to understand

What’s making this market particularly dynamic right now is convergence. Enterprise software platform vendors and application providers are racing up the value stack, embedding agentic capabilities directly into their products. At the same time, professional services providers and systems integrators are moving in the opposite direction: building proprietary, asset-based delivery models anchored in the same underlying technologies.

The result is that buyers face a highly dynamic market space. IDC’s research shows organizations are evenly split between build and buy strategies, and most expect to source agents from multiple vendors simultaneously. That’s pragmatism. The agentic AI market is too young and too fast-moving for anyone to bet on a single supplier.

Your next move

Understanding where your organization sits in this ecosystem, and where your partners and competitors sit, is no longer optional. Agentic AI’s promise is the digitization of labor at scale. The organizations that navigate this landscape with confidence will be the ones that mapped it first.

IDC’s Market Glance gives business executives, product managers, and analyst relations professionals the structured view they need to assess opportunities, evaluate partnerships, and make the right decisions about where to place their bets. The ecosystem is moving quickly. Navigate your next move with the evidence to back it up.

Neil Ward-Dutton

Neil Ward-Dutton - Research VP, Agentic Automation & AI Technologies

Neil Ward-Dutton is Research VP, Agentic Automation & AI Technologies at IDC. In this role he guides IDC’s research agendas, and helps enterprise and technology vendor clients alike make sense of the opportunities and challenges across markets spanning core AI…