Six months. Twenty-eight stakeholders. That’s the average enterprise sourcing cycle right now, according to IDC’s Effective Agent Cost Management: A Practitioner’s Framework. If that number sounds high, sit with it a second longer: 28 people means 28 opinions on what “good” looks like, 28 calendars to align, and 28 chances for the process to stall while everyone waits on someone else’s read of the market.
Procurement doesn’t lose sourcing cycles to a lack of vendors. It loses them to a lack of a fast, defensible way to narrow a field that keeps growing every quarter. You open a category review with 12 names on a long list. Three months later, you still have nine, because nobody on the team has the bandwidth or the standing to say, with evidence, who belongs and who doesn’t. This is the exact moment IDC Quanta earns its place in the process.
Ask the question, get the field narrowed
IDC Quanta is the interface between your team and IDC’s full research organization: the analyst expertise and market comparisons the sourcing platform has built, grounded in your own environment and history. You don’t file a request and wait for a report. You ask IDC Quanta a plain-language question, the kind you’d ask a colleague who happened to know the entire market: “Help me narrow this vendor field to five names that fit our environment.”
IDC Quanta takes that question, pulls in the relevant analyst expertise, layers in its market comparisons, and returns an answer built around your specific requirements, not a generic category summary. That distinction matters more than it sounds. IDC Quanta’s answer reflects your scale, your existing stack, and your budget reality.
Full roster, not one point of contact
Here’s what most procurement teams have learned to expect from research access: a single assigned analyst and a calendar to work around. IDC Quanta doesn’t route you to one expert and stop there. Ask about cloud cost management, and IDC Quanta surfaces the analysts who cover both the cost economics and the vendor viability questions, in the same session. You’re not waiting for your one contact to loop in a specialist. IDC Quanta already knows who else in IDC’s roster has the answer you need, and it brings them into the conversation.
For a category review with 28 stakeholders pulling in different directions, that breadth changes the conversation. Instead of one analyst’s opinion carrying the room, you bring evidence from the specific experts whose coverage matches the decision in front of you.
From wide field to structured shortlist
The sourcing platform behind IDC Quanta does the heavy lifting on comparison. Ask IDC Quanta to build a shortlist from 12 vendors, and it draws on the platform’s structured market data to produce a comparison built around the criteria that matter for your specific evaluation.
That’s the shift worth naming: IDC Quanta hands procurement an answer already interpreted against their own context.
Momentum is the real deliverable
Twenty-eight stakeholders don’t need fewer meetings. They need a faster path to shared confidence in the same evidence. IDC Quanta gives procurement a way to bring that evidence into the room before momentum stalls, with a clear, defensible reason for each of the five names on the shortlist.
Ask IDC Quanta the question. Let the roster and the platform do what they do best, and get back to running the evaluation.
Ryan Smith is the Director of Content Marketing at IDC, where he leads brand-level content and social media strategy, aligning research insights with compelling storytelling to engage technology decision-makers. With a background in both IT and marketing, Ryan brings a unique blend of technical understanding and creative strategy to his work. He’s also a seasoned storyteller, speaker, and podcast host who believes the right message, told the right way, can drive both trust and transformation.
Christina Cardoza - Content Marketing Manager - IDC
Christina Cardoza is a Content Marketing Manager at IDC, where she specializes in brand content and social media strategy. With a background in journalism and editorial leadership, she has a proven ability to transform complex technology topics into clear, actionable insights.
Every technology leader has sat through a vendor pitch built on a survey. A few thousand respondents, a well-designed questionnaire, a chart that says most organizations plan to increase spend on something. That’s the quiet limitation of survey-based market intelligence: it measures intent, not action. It looks like evidence. It’s a snapshot of what people said they’d do, taken at a single moment, months before you’re reading it.
Before you trust a market intelligence source with a board-level investment decision, ask where its data comes from.
IDC Quanta is built on independent, continuously tracked research: the judgment of more than 1,000 experts across over 100 countries, benchmarked against a peer universe of 404,000+ enterprises spanning 52 countries and 41+ technology categories.
For years, the market intelligence pitch was about frameworks: maturity models, best-practice checklists, the how-to layer. That layer no longer differentiates one source from another, since a well-prompted generative AI tool can produce a credible maturity model today. The differentiator is data that doesn’t exist publicly, gathered and interpreted by analysts who track the market for a living.
A dataset is only useful if a technology leader can get an answer out of it without hiring a data science team. Quanta’s contextualization layer pairs your own documents and procurement history with IDC’s research, so a plain-language question gets an answer shaped by your specific situation. Upload an IT budget, an AI cost export, or a vendor contract, and IDC Quanta maps it against that data in the same conversation, with no separate portal or new login required. The more you use it, the more it remembers: your vendors and use cases stay active across quarters instead of resetting with every new report.
This isn’t an argument that frameworks are worthless. It’s that the edge lives in evidence a generative model cannot invent, delivered as a straight answer instead of a hundred-slide deck. That’s the confidence a tech leader needs walking into a board meeting or a renewal, with a number a vendor can’t talk you out of.
Ryan Smith is the Director of Content Marketing at IDC, where he leads brand-level content and social media strategy, aligning research insights with compelling storytelling to engage technology decision-makers. With a background in both IT and marketing, Ryan brings a unique blend of technical understanding and creative strategy to his work. He’s also a seasoned storyteller, speaker, and podcast host who believes the right message, told the right way, can drive both trust and transformation.
IDC’s Insights From the 2026 World Robot Conference in Beijing
The 2026 World Robot Conference (WRC) took place in Beijing this August under the theme “Human-Machine Symbiosis, Integrated Production and Demand.” More than 300 companies exhibited, showing over 2,000 products and launching more than 150 new ones. For the first time, the conference added a dedicated Procurement Day, where 49 state-owned enterprises appeared together as an innovation consortium, laying out real industrial demand across 12 application scenarios. Robotics is becoming more application-focused, and shifts on the demand-side are now driving the industry’s growth at scale.
The numbers back that up. China’s Ministry of Industry and Information Technology reports that revenue at the country’s above-scale robotics enterprises topped RMB 90 billion (USD 13.4 billion) between January and May 2026, up 26.9% year-on-year. IDC’s own data shows global humanoid robot shipments reached roughly 18,000 units in 2025, up nearly 800% year-on-year.
IDC’s research also finds that most enterprises piloting embodied intelligence robots are still stuck at the proof of concept stage. Between validating the technology and deploying it at scale sit several real hurdles: stability, cost, ROI, and the operations and maintenance work that keeps a robot running day to day. This year’s show floor told a more advanced story anyway. Robots demonstrated complete task execution rather than single task actions, and several ran in real business settings rather than labs. Physical AI is now competing in industrialization capability as much as technical capability. Four trends from this year’s conference bring that into focus.
Trend One: The Model Race Is Giving Way to Real-World Learning
Over the past year, large embodied intelligence models, VLA models, and world models have advanced quickly, pushing robots beyond perception and understanding into complex task decisions and execution. Heading into 2026, though, the competition is shifting: whose model is strongest matters less than which vendor can get robots working, and learning, in real scenarios. Models are the capability foundation for Physical AI; real-world data and continuous learning are what will define the next stage’s edge.
At WRC 2026, world models, VLA, simulation platforms, robot “training grounds,” and data collection technologies all drew sustained attention. Combining virtual and real environments is becoming an important path to data acquisition: simulation generates data at scale, real scenario data keeps it grounded, and together they lower the cost of trial and error. Operational data flowing back into the training pipeline forms a flywheel: perceive, train, execute, get feedback keep improving.
China already has more than 40 robot training grounds planned or under construction, spanning more than 14 provinces and municipalities. The most mature ones can produce data output in the millions of records a year. At the same time, steady improvement in dexterous hands, force sensors, and other hardware is giving robots the means to capture richer manipulation data. As models, data, simulation, and hardware start to co-evolve, enterprise competition is starting to hinge less on whose model scores best and more on who can turn operational data into a working training loop.
Trend Two: Demo Capability Is Giving Way to Scaled Delivery
As robots move into real business environments, the standard for judging them is changing too. At this year’s conference, several vendors moved past single-action demos to validate complete task workflows, including depalletizing, sorting, delivery, cleaning, and inspection. They are proving out full processes now, not isolated capabilities. The real dividing line in robotics has shifted from technical demos to stable delivery.
Task capability now means continuous operation, not single operation execution:robots need autonomous perception, task planning, continuous execution, and the ability to recover from exceptions on their own. Deployment is the harder test. Moving past a proofmeans users are raising the bar on stability, deployment efficiency, maintenance cost, and ROI, with automotive, 3C electronics, and logistics and warehousing serving as the key proving grounds. And the metrics buyers actually use have shifted with it: task success rate, continuous run time, cost per task, and payback period, not the technical benchmarks vendors cite in a demo.
IDC’s user research shows more than 20% of users have already moved from market attention into pilot exploration, and the pace of progression from proof of concept to scaled deployment is accelerating. Stable operation, rapid deployment, ongoing maintenance, and commercial ROI are the capabilities that will separate vendors over the next two to three years.
Trend Three: From Single Scenario Breakthroughs to Layered Deployment
Physical AI won’t scale across every scenario at once. Differences in technical maturity, environmental complexity, and commercial ROI are settling applications into a layered path: commercial services are exploring, industrial settings are expanding, and home and consumer use is still building toward the future.
Commercial services are in a deep exploration phase. Dining, hospitality, and retail all have clear task demand, but their environments are more complex than industrial settings, so they need stronger autonomous navigation, environmental understanding, and exception handling. Embodied intelligence is accelerating here, carefully.
Industrial manufacturing will scale fastest. Automotive, 3C electronics, and logistics and warehousing are relatively structured, with clearer task boundaries and strong demand to cut cost and improve efficiency. IDC data shows China’s industrial embodied-intelligence robot market was worth approximately RMB 5.74 billion in 2025, with industrial robots contributing about RMB 3.62 billion and humanoid robots about RMB 2.12 billion. Right now, this is where technical maturity and commercial value line up best.
The home and consumer market holds long-term potential. Home environments are highly unstructured, with complex, long-tail task types that demand more from a robot’s generalization ability, safety, interaction skills, and cost. The potential application scope is broad enough, though, and the long-term market opportunity is significant.
Robot applications will keep working their way from highly structured environments toward moderately and then loosely structured ones, and different robot form factors will keep finding sharper matches to specific scenarios as they go.
Trend Four: Whole Machine Competition Is Giving Way to System Capability
As Physical AI enters its industrialization phase, the robotics industry chain is expanding from a single hardware platform to include computing power, models, data, core components, and applications, all at once. At this year’s conference, companies from across the domestic and international industry chain participated deeply, and the 49 SOEs appeared together as an innovation consortium. Competition is shifting from single-technology supply to industry chain collaboration and joint scenario creation, and the boundary of enterprise competition is expanding into hardware-software collaboration and ecosystem building as a result.
Industry chain collaboration continues to deepen: chips, sensors, reducers, servo systems, dexterous hands, and other core components are accelerating collaboration with robot platforms.
Models and hardware are converging faster, aslarge model companies, robot manufacturers, and research institutions collaborate on VLA, world models, and motion control.
Industry support systems are accelerating. Dozens of embodied intelligence innovation centers have already launched across China, covering technology development, pilot-scale validation, data training, and scenario deployment.
International cooperation is widening the circle further: the conference attracted 30 international supporting institutions across research, engineering, industry, and investment.
The companies best positioned to move from point applications to scaled commercial deployment will be the ones with the strongest ecosystem-organizing capability, not necessarily the strongest single product.
IDC Outlook
Physical AI is moving from technology display to industrial value validation. Robotics companies’ core competitiveness will depend not just on technical sophistication, but on whether they can turn that technology into stable, replicable products and solutions with real commercial value. Physical AI is entering the deep waters of industrialization, and the next stage of competition in robotics will focus more closely on real demand and real value.
The next two to three years will be an important window, as embodied intelligence robots move from technology validation to scaled application. Different scenarios will show a layered deployment pattern: service scenarios will be first to explore application, industrial scenarios will become the key direction for scaled deployment, and the home and consumer market holds long-term development potential. At the same time, Physical AI will push industry competition from single hardware capability toward a systemic capability built on models, data, hardware, and applications together.
Upcoming Webinar: Global Robotics Outlook 2026-2027
WRC 2026 showed where robotics is headed technically. But a new US policy is redrawing who wins. Join IDC’s live webinar, How the US ban is reshaping the robotics market, on Wednesday, October 14, 2026 at 11:00 AM EDT. We’ll cover the 2025-2030 forecast for humanoid, autonomous mobile, and commercial service robots, the competitive landscape, and what the July 2026 US restriction means for your next move. Register now!
Can’t join live? Register anyway — an on-demand recording and translated access will be available afterward.
For Further Discussion
The robotics industry stands at a critical juncture, moving from technology validation toward scaled application. If you’re interested in Physical AI deployment pathways, embodied-intelligence scenario value assessment, or industry-chain competitive dynamics, visit IDC Physical AI Resource Center for more resources or contact us for an in-depth discussion with IDC analyst team.
Navkendar Singh is a Associate Vice President with IDC India, based in Gurgaon. His research domains encompass deep-dive research and insights in and around mobile devices, smart homes, PCs, tablets, wearables, and the printing market in India, Bangladesh, and Sri Lanka.…
Zhenya Sun is a research manager for the IDC team focused on exploring the application of technology and industrial development of AI and AI agents. He is also responsible for providing clients with consulting services on technologies, products, and markets…
Global shipments of XR headsets and glasses rose 35.3% year over year in the second quarter of 2026, strong growth but a significant moderation from the 130.2% increase IDC tracked in the prior quarter. Much of that slowdown reflects tougher comparisons and a pause between major product cycles rather than any softening in consumer interest. Growth should pick back up as the next wave of product launches arrives later this year.
Audio glasses, the display-less category that includes devices like Ray-Ban Meta, represented the largest portion of shipments, capturing 70.3% share during the quarter, up from 61.9% a year ago. Display glasses represented 14.3% share, up from 11% a year ago, while headsets held the remaining 15.4%. Glasses overall have turned a corner and are quickly being recognized by a mainstream audience. Recent privacy backlash over always-on recording shows not all of that attention is flattering.
Who’s winning right now: Q2 2026 market share
Meta continued to dominate the market with 68.7% share. Its growth this quarter came from pushing into two additional segments: prescription eyewear, with the launch of its Blayzer and Scriber Optics lines, and lower-cost options that skip the fashion branding EssilorLuxottica normally provides. That expansion is only part of the story. Meta’s lead also rests on distribution scale, brand recognition, and AI features built across its product line, advantages that are harder for challengers to replicate than any single hardware launch.
RayNeo ranked second with 3.6% share, up 83.3% year over year, on the strength of its low-cost, personal-theater-style devices. Alibaba, a relative newcomer to the category, ranked third at 2.6% share thanks to the popularity of Qwen and the company’s already-established presence in China. XREAL and Xiaomi rounded out the top five, though Xiaomi’s share nearly halved from a year ago as competition in its home market intensified.
What’s coming next: The launches that could reshuffle the board
A lot is going to change in the remaining months of 2026 as next-gen products arrive from multiple vendors, each chasing a similar set of goals: more capable AI experiences, lighter hardware, and use cases that go beyond entertainment into everyday productivity. Those shared priorities, more than any single launch, will shape competition through the rest of the year.
Snap is launching its Specs, which bring genuine AR capabilities packaged into the most consumer-friendly design the category has seen yet, backed by a marketing campaign built around fashion icons.
Samsung and XREAL are both readying Android XR products. XREAL’s Aura pairs the company’s personal-theater-style hardware, already strong for content consumption, with Google’s Android XR platform, putting productivity use cases on equal footing with entertainment. Samsung’s audio glasses, meanwhile, bring Google’s Gemini assistant together with the distribution and design sensibility of Gentle Monster and Warby Parker.
Meta’s upcoming Connect event is widely expected to launch a more premium mixed reality headset with better visuals and a slimmer, lighter form factor that should appeal to enthusiasts. IDC also anticipates new display and audio glasses at the show, with the display glasses aimed at broader availability and a more accessible price point.
Beyond these headline launches, products from Pico, RayNeo, Viture, and a growing list of other brands will help drive further growth in 2026 and into the years ahead.
The road ahead: Forecast 2026–2028
IDC forecasts total unit shipments will grow 26.3% in 2026, then accelerate to 40.5% growth in 2027 and another 26.4% in 2028. Audio glasses will keep leading the category, though display glasses and headsets will continue to ramp alongside them.
For consumers, that growth will be driven by a wider range of products, price points, and channels, plus the spread of AI and friction-reducing use cases like easy photo and video capture. Among businesses, training and design use cases will keep driving adoption, since IDC has tracked ROI gains in early enterprise pilots, and more businesses continue to start them.
Growing pains: Privacy and business-model tension
There are also growing concerns behind the scenes that need to be addressed, as they stand to reshape the adoption curve going forward.
Privacy and shifting consumer attitudes. Many products and services surrounding XR glasses have clear, tangible benefits, though IDC has tracked growing concern over the need for privacy controls. IDC has also observed a shift from early jokes about social acceptance to more serious concerns about the lack of meaningful notice and consent mechanisms while recording, along with AI-enabled data collection, raising the stakes for how vendors respond. Meta, the current leader, has taken action to reduce misuse of its products, but those steps came only after public backlash forced its hand. That leaves room for a competitor willing to build privacy safeguards in before launch, not after a headline forces the issue.
Competing business models. XR glasses are a relatively new category, and tech companies are quickly partnering with fashion companies to leverage their expertise in design, manufacturing, and distribution. There’s tension between these camps, though, as fashion companies often operate on higher margins while tech companies are willing to sacrifice margin in favor of ongoing subscription or advertising-based models, where the hardware can be offered at a lower upfront cost to keep the consumer inside the ecosystem. This is likely one reason Meta launched glasses without EssilorLuxottica’s branding. It also puts smaller players at a disadvantage, since they face pricing pressure on hardware from incumbents like Meta and potentially Google and Samsung, and will likely have to adjust their own business models to offer subscription services alongside their XR products going forward.
What this means for the industry
Smart glasses are genuinely being worn now, not just tested, and that changes the competitive picture. Meta still holds the lead, but the next round of launches from Snap, Samsung, XREAL, and Meta’s own Connect event will show whether that lead holds up. The rest of 2026 will be shaped as much by these launches as by the numbers themselves. Even with this quarter’s slower growth, consumer awareness keeps building and AI is unlocking new use cases — the vendors that move first on privacy may be the ones who convert that awareness into share.
Jitesh Ubrani - Director, Consumer Devices Research
Jitesh Ubrani is a Director at IDC leading a team of analysts within the Worldwide Consumer Device Trackers group, covering wearables, augmented reality (AR), virtual reality (VR), tablets, phones, PCs, gaming, and smart home devices, with a focus on market…
Every SaaS vendor just had its head chopped off, and Salesforce went first. It voluntarily stepped up to the guillotine and let its own head go. Yes, that sounds a bit savage, but don’t worry. It’s wonderful. The entire SaaS industry is about to go headless, and I couldn’t be more excited.
For thirty years, the interface has masqueraded as the product. That disguise just came off. The UI was always just the delivery mechanism, and it has quietly become one of the most expensive parts of enterprise software ownership.
Think about what a typical knowledge worker actually does in a day. They log into an ERP system to check a budget, then into a CRM to update an opportunity, then into an expense tool to file a report, then into an HR system to approve a request. Each application has its own navigation logic, its own field names, its own permissions quirks, and its own learning curve. Most of these systems are also loaded with three or four times the functionality any single user needs, which means the interface is optimized for the vendor’s full customer base, not for the person actually sitting in front of it. The result is a tax on productivity that has compounded for years. Time is lost to switching, time is lost to relearning, and time is lost to hunting for the right screen inside the right app. This was never a minor annoyance. It was one of the largest hidden costs in enterprise software.
The UI was never the product
Oracle was among the first major vendors to say this out loud in a meaningful way. With its agentic applications announced earlier this year (one of the first live market examples of cross-application agents as explained in IDC’s Agentic Evolution of Applications framework), Oracle began dynamically assembling the interface itself, pulling the data, functionality, workflows, and logic a user needed from across whichever applications were relevant, rather than forcing the user to go find them. That was among the first real cracks in the old model. It correctly suggested that the fixed screen was a legacy constraint, not a design requirement.
Salesforce has now taken that idea and extended it a step further. At Dreamforce 2026, held September 15 through 17 in San Francisco, Salesforce unveiled AIforce, which it is calling a live interface layer. AIforce does what Agentforce already does inside Salesforce (dynamically composing the data, workflows, and business logic a user needs on the fly), but it goes a step further. It extends that same capability outside of Salesforce entirely, into whatever interface a person already happens to be working in. Salesforce launched this with three surfaces at once: Claudeforce, Slackforce, and Agentforce Coworker, meaning the same trusted enterprise data and governance can now show up inside Claude, inside Slack, or inside a dedicated coworker agent, not just inside Salesforce’s own screens.
Meeting users wherever theyare
This is precisely why AIforce matters more than another feature release. The goal is to help customers break free of a shared user interface, so that every individual gets an intelligent, dynamic interface that comes to them, wherever they are, instead of forcing everyone into the same fixed screens. That is not a UI update. It is an admission that the UI was the obstacle all along.
What this means for the rest of the market
Oracle and Salesforce arrived at the same conclusion from opposite ends of the market, and that convergence is the real signal, not either company’s product name. When two competitors this large independently decide that the fixed screen is disposable, the SaaS UI is not being tweaked. It is being retired.
Buyers should not mourn it. The interface was never where the value lived. The value lived in the data, the workflows, and the logic sitting underneath it, and buyers have been paying a productivity tax for thirty years just to reach that value through a screen. That tax is now optional.
For vendors across ERP, HR, finance, SCM, and every other enterprise application category, the imperative is not subtle:
Stop pricing and marketing the interface as the differentiator. It never was.
Open the data, workflows, and business logic underneath the UI to whatever surface the customer already lives in, whether that is Claude, Slack, Teams, ChatGPT, Outlook, Office, or any other work environment.
Build the governance and permissions layer first. A composable interface without composable trust is a liability, not a feature.
Assume the next RFP will not ask what your UI looks like. It will ask whether your platform can show up anywhere.
The UI is not being replaced by a better UI. It is being replaced by the absence of one. That is not a loss. It is the correction the market has needed for thirty years. I never thought I’d see the day when I applaud a beheading, but that day has arrived, and I hope it continues.
Eric Newmark - Group Vice President & General Manager of IDC's SaaS, Enterprise Software, CX and Workplace Solutions Division
Eric Newmark is Group Vice President & General Manager of IDC’s SaaS, Enterprise Software, CX, and Workplace Solutions Division, which includes several teams of analysts covering SaaS, 18 enterprise application markets, software monetization, business platforms, marketplaces, and services firms focused…
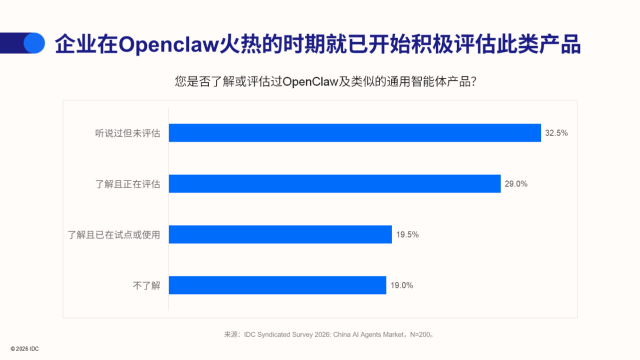
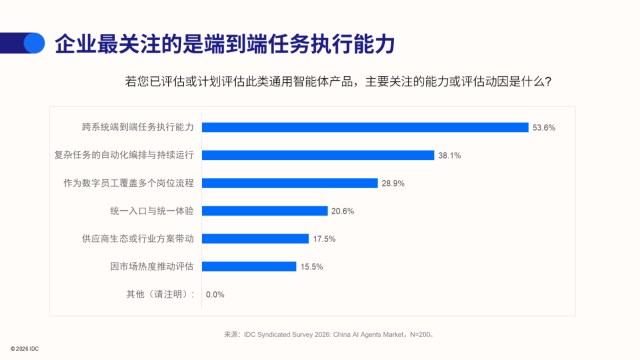
AI PCs have been on the market for a couple of years now, with applications and use cases progressively finding ways to put local AI models to work. China’s version of that story looks different from the rest of the world’s. Since earlier this year, interest in OpenClaw-like AI agent harnesses has driven a wave of ultrasmall desktop PCs there, and unlike the high-end, DGX Spark-class boxes getting attention elsewhere, most of these are inexpensive, modestly specced machines built to host an agent rather than run a large model locally.
Where the lobster talk comes from
All of this traces back to a single piece of open-source software called OpenClaw, an autonomous AI agent that can be given a task in plain language and left to carry it out on its own, browsing the web, editing files, and calling other tools as needed. Its logo features a lobster-like claw, and Chinese users picked up on that and started calling the software 小龙虾, or crayfish, a nickname that stuck to everything that followed, including the hardware people bought to run it. Naming for that hardware hasn’t really settled, but some call it 龙虾盒子, so we’re calling them lobster boxes here for simplicity.
OpenClaw’s rise from around February through April 2026 drove a hardware surge, and it was global rather than a China-only phenomenon. Mac mini sold out in multiple markets because the software simply worked better on macOS, with tighter access to the operating system’s own apps and a quiet, low-power, always-on form factor well suited to running an agent around the clock. What was distinctive about China is how quickly it moved past that Mac dependency. Chinese startups and retailers began shipping their own inexpensive, purpose-built boxes within weeks, and those boxes worked despite modest specifications because they were calling cheap, cloud-hosted AI services rather than running a model locally, so most of them never needed the expensive memory that on-device inference requires.
Tencent and Baidu both ran free installation clinics at their headquarters in Shenzhen and Beijing, drawing crowds in the hundreds as company engineers set up the software machine by machine for anyone who showed up.
Tokens that are cheap
Part of why this took off in China specifically comes down to what it costs to keep an agent thinking. Western AI subscriptions have generally settled around $20 a month for services like ChatGPT Plus or Claude Pro. Chinese equivalents often run under $10 a month, and a large share of casual use runs through free consumer apps entirely, with paid tiers unlocking higher concurrency rather than gating basic access. There are some indications that pricing could increase soon, but this new class of hardware emerged without needing much memory in the first place, precisely because cloud-based models were affordable enough to lean on.
The rise of the OPC
Chinese researchers and businesses have started using a formal term, OPC, short for one-person company, to describe a business built around a single person making the decisions while a cluster of AI agents handles the execution and the day-to-day output. It is a notable enough trend that Lenovo’s own marketing for its lower-cost Baiying-branded AI PC, a roughly $560 Windows box, describes the product as built for OPC operators, sometimes called super-individuals, with use cases like AI content creation, e-commerce operations, and market analysis.
There is also a cultural aspect to consider. Much of the anxiety Chinese workers have felt about AI replacing their jobs pushed people toward learning to run the tool themselves, which helps explain why installation clinics and DIY tutorials found such a ready audience. That desire to learn the tool fits naturally with the OPC idea, since China already has a way to turn it into a business.
Where the growth is headed
Most of these agent-hosting devices are what IDC classifies as ultrasmall desktops, which we expect to top one million units in China in 2026 and grow to roughly 1.8 million by 2027. That is a small slice of China’s overall PC market, which IDC expects to total around 51 million units in 2026, so this remains a niche category. Lenovo has been the most visible vendor building for this category specifically, with its lower-cost Baiying and Tianxi-branded AI hosts, and Xiaomi joined in August with its own prototype, the AI Cube, built around three of its own chips. Many of the units behind that growth today are still the cheap, low-end boxes that lean on cloud AI rather than local processing, but interest in local token generation is picking up, and that points to some shift toward pricier, more capable hardware.
Likely to stay a China story
These low-end boxes look likely to stay a China phenomenon, since the conditions behind them are not really present in the same combination elsewhere. The rest of the world is increasingly exploring NVIDIA’s DGX/RTX Spark, AMD’s Ryzen AI Halo-based systems, and Microsoft’s Project Zenith, announced together with AMD at IFA earlier this month, which are all aimed at running large models locally. These are on the other end of the price spectrum but are based on the premise that generating tokens locally will be more economically effective than paying for cloud-based tokens.
Bryan Ma is Vice President of Client Devices research, covering mobile phones, tablets, PCs, AR/VR headsets, wearables, thin clients, and monitors across Asia as well as worldwide. Based in Singapore, Bryan provides insights and advisory services for both vendors and…
Only 3.1% of organizations worldwide have reached the most mature stage of AI adoption. Sixty-one percent are still stuck in the two least mature stages, with the broad middle barely moving in a year. Most technology leaders can’t say with confidence which group they’re in.
That uncertainty is landing at the worst possible moment.
Right now, technology leaders are making three decisions at once, with no established playbook for any of them.
Whether to keep trusting the vendors and platforms already in place, or bring in new ones.
How to control AI costs that scale differently than traditional IT costs ever did — IDC projects 1.3 billion active AI agents worldwide by 2029, executing 240 billion actions a day, with annual agent-action delivery costs approaching $53 billion.
And how to defend a capital allocation decision to a board that’s asking harder questions every quarter, then prove it’s still paying off the next time they ask.
None of these are once-a-year exercises. They come up in board meetings and budget reviews, frequently colliding with a renewal deadline nobody flagged in advance, and a technology leader without an outside reference point is making each one on internal conviction alone.
These three are just what’s most urgent right now. Whatever the decision, the same grounding applies: independently verified market intelligence, benchmarked against real peer data, available exactly where the decision is happening.
Built for the decisions your team is making
IDC Quanta gives IT leadership, security and operations, and finance and procurement that same grounding, including but not limited to the three decisions above.
IT Leadership: build a credible technology and AI roadmap and make faster, more confident vendor and platform decisions, grounded in data instead of vendor pitch decks.
Security & Operations: get ahead of where AI cost and risk exposure is building before it becomes a board-level problem, backed by the same peer-benchmarked evidence driving every other decision here.
Finance & Procurement: present a capital allocation case finance can stand behind, on spend and vendor pricing, and walk into every renewal with a stronger negotiating position.
What holds up under scrutiny
IDC Quanta backs each of those decisions with specifics beyond general research access:
The largest peer universe available: draws on 404,000 enterprises across 52 countries, giving every benchmark real market breadth.
Your own data, benchmarked instantly: upload an IT budget, an AI cost export, or a vendor contract, and Quanta benchmarks it against IDC’s data in the same conversation, with no analyst re-keying and no separate tool required.
No separate portal, no new login: IDC Quanta reaches your team inside email today, with Teams, Slack, and MCP-enabled tools next, so sourcing, budget, and renewal intelligence shows up where the work already happens.
Get flagged before the deadline, not after: anonymized peer signals surface contract renewals, budget-cycle openings, and board-review dates as they approach.
Make the case before someone else asks you to
The gap between the 3.1% of organizations that have actually reached AI maturity and the ones that only believe they have is exactly the kind of thing a board finds out about the hard way, usually during a budget review, not before one. IDC Quanta gives a technology leader the evidence to walk into that conversation already prepared.
Ryan Smith is the Director of Content Marketing at IDC, where he leads brand-level content and social media strategy, aligning research insights with compelling storytelling to engage technology decision-makers. With a background in both IT and marketing, Ryan brings a unique blend of technical understanding and creative strategy to his work. He’s also a seasoned storyteller, speaker, and podcast host who believes the right message, told the right way, can drive both trust and transformation.
Christina Cardoza - Content Marketing Manager - IDC
Christina Cardoza is a Content Marketing Manager at IDC, where she specializes in brand content and social media strategy. With a background in journalism and editorial leadership, she has a proven ability to transform complex technology topics into clear, actionable insights.
For a few years now, sustainability leaders have asked a fairly narrow question: how can AI help us hit our targets? That question still matters. It’s just not the only one anymore. The sharper version asks two things at once: how can AI drive business value with sustainability built in as an outcome, and what is AI’s own footprint, and who’s accountable for it?
IDC’s research points to the same conclusion from both directions: AI and sustainability have become one conversation, told from two sides: AI for Sustainability (using AI to drive sustainability outcomes) and Sustainable AI (managing the sustainability of AI itself). Here’s what our latest published research says about both, and why the organizations that treat them as one strategy are already pulling ahead.
It’s also what our sustainability research team (Bjoern Stengel, Amy Cravens, and Dan Versace) will be on the ground discussing at Climate Week NYC 2026 (September 20–27), meeting with IT infrastructure, cloud, software, and consulting clients and prospects across the city. If you’re there too, we’d love to compare notes.
AI for sustainability: Software grows into the operating layer
Sustainability software isn’t just a database where companies simply calculate their emissions; it’s becoming the operating layer for how they run leaner, cleaner, and smarter… For vendors, the mandate is clear: integrate the data, go deep by industry, and prove the return..
The market is voting with its budget. IDC forecasts the worldwide sustainability and ESG software market growing from $5.98 billion in 2024 to $12.36 billion by 2029, a 15.6% CAGR. And buyers aren’t just adopting AI features because they’re new: 71% say they’re willing to pay a premium for AI-enabled sustainability capabilities, and 80% are increasing their spend. Vendors call that a repricing of what “good” sustainability software looks like, and the buyer data backs them up.
Sustainability strategy is no longer a compliance checkbox; it’s the new engine of enterprise value, capital allocation, and operational resilience. In 2026, the winners will be those who embed sustainability into the P&L, harness AI as a core enabler, and transform ambition into measurable business outcomes.
Where the value shows up: Carbon, energy, circularity, and integrated ESG/sustainability data
Talk to buyers long enough and the abstraction falls away. The value shows up in a handful of concrete places.
Carbon and energy management is the clearest one. IDC’s 2026 sustainability/ESG predictions research projects that by 2027, 40% of manufacturers will use AI-driven analytics and automation to optimize energy efficiency, cutting carbon emissions by up to 30% in the process, through predictive load forecasting, real-time monitoring, and automated adjustment rather than manual intervention. On the software side, vendors are already applying AI directly to carbon accounting: streamlining data ingestion, catching errors, and turning what used to be a quarterly scramble into something closer to a running total. In the datacenter, our Building Blocks of a Sustainable Datacenter report tracks the same pattern showing up in energy and carbon triage: dynamic workload management and grid-carbon-aware scheduling have moved from pilot projects to standard operating practice.
Circularity is the fastest-growing piece of the picture. IDC research shows the share of organizations tackling circularity through their sustainable AI strategy rising from 22% in 2024 to 29% in 2026, a 32% jump, outpacing most other environmental categories, driven largely by the unit economics of AI hardware itself: refurbishment, redeployment, and high-value materials recovery pencil out better for AI accelerators than for general-purpose IT. Zoom out further and the trend holds at the enterprise level too: IDC projects that by 2028, 75% of enterprises will set formal IT asset circularity goals, with 90% of retired assets returned to the circular economy and 20% of new IT sourced as refurbished.
And underneath all of it sits the data problem. Amy Cravens’ AI-Enabled Sustainability Software survey found that ESG data readiness (data quality, integration, and standardization) is the primary constraint to scaling AI for sustainability, with data accuracy ranked the single most urgent issue organizations want AI to fix. Dan Versace and I called this out directly in Navigating the New Sustainability Services Landscape as “ESG Data Management 2.0.” Sustainability data has become mission-critical enterprise data, subject to audit and financial disclosure. Closing the gap between what regulators require and what most organizations’ data infrastructure can actually deliver is one of the most concrete, high-value opportunities in the market right now.
The maturity divide: Why some organizations capture 26x more value
Here’s the number that ties all of this together. IDC’s 2026 AI and Sustainability Survey segments organizations into three maturity cohorts, and the spread between them is enormous: only 3.3% of beginner-stage organizations report significant business value from AI-enabled sustainability, rising to 31.8% at the intermediate stage, and 84.6% among advanced organizations, a 26-fold gap between the least and most mature. As I wrote in my Sustainable Business Value Creation in the Era of AI Everywhere report:
“
The sustainability maturity divide is no longer a future risk — it is today’s competitive reality. The organizations capturing 26 times more business value from AI are not doing something fundamentally different. They are doing the same things at a fundamentally different level of integration, automation, and strategic commitment.
The stages map cleanly onto the examples above. Beginner organizations are still consolidating fragmented ESG data for compliance and disclosure, exactly the data readiness gap Amy’s research flags. Intermediate organizations move into operational efficiency, where AI-driven energy and carbon management start generating hard, CFO-legible savings. Advanced organizations push into circularity, product-level life-cycle design, and ecosystem data-sharing, the territory where sustainability stops being a cost center and starts showing up as revenue premium and lower cost of capital. The gap tracks how deeply AI is embedded into operational decisions and how tightly sustainability data connects back to the maturity cohorts above.
Sustainable AI: The bill comes due
Here’s the part that gets less airtime: AI has a resource cost, and buyers are starting to ask about it directly. As I noted in IDC’s Sustainability/ESG 2026 Predictions:
“
IT is a critical enabler for organizations shifting from ESG compliance to the operationalization phase of sustainable transformation. However, IT’s footprint can also hinder these ambitions. The era of AI everywhere creates exciting new possibilities to accelerate change, and it makes sustainable IT adoption more crucial than ever.
This is the flip side of the framework: IDC distinguishes between Sustainability through AI (using AI as a lever for broader sustainability goals) and Sustainability of AI (managing AI’s own environmental footprint), plus a third, adjacent lens, AI for Good, where AI is applied directly against societal and SDG-aligned goals. Our Building Blocks of a Sustainable Datacenter, 2026 update tracks how organizations are responding at the infrastructure layer: liquid cooling is now a baseline requirement for AI workloads, and AI-specific ITAD (secure data sanitization for accelerators and recovery of the high-value metals inside them) is now a distinct discipline in its own right. As I put it in that research:
“
AI has changed what it means to build and operate a sustainable datacenter… Operators and suppliers that internalize these shifts now will be the ones with credible sustainability stories and resilient business models by the end of the decade.
The two questions are converging
Split into two workstreams, “AI for sustainability” and “sustainable AI” can pull in opposite directions: one team pushing to scale AI faster, another asking what that scale costs. IDC’s research on the highest-maturity organizations shows something different. They’re running one capability, AI-enabled data infrastructure accountable for the value it creates and the resources it consumes, and that’s the same pattern showing up in the datacenter and circularity data above.
That’s the real signal underneath all three of our research streams this year. Software vendors are building the operating layer Amy Cravens describes in her research above. Services are repositioning around AI-enabled infrastructure and provable outcomes. Carbon, energy, and circularity have moved from side projects to line items CFOs read every quarter. Infrastructure itself is now being asked to justify its own footprint.
For buyers, the practical takeaway is simple: the sustainability maturity conversation and the AI investment conversation are the same budget line now. Treat them separately, and you’re optimizing half the equation. Treat them together, and the value multiplies. That’s the maturity gap from Bjoern’s data, playing out at portfolio scale.
If you’re at Climate Week NYC this September, Bjoern Stengel, Amy Cravens, and Dan Versace will be meeting with clients and prospects across the city all week. Reach out if you’d like to talk through where your organization sits on this curve.
Bjoern Stengel - Global Sustainability Research and Practice Lead, Sustainable Strategies and Technologies
Bjoern Stengel is IDC’s global sustainability research lead. His research focuses on how environmental, social, and governance (ESG) topics impact and shape business strategies and technology usage. He provides insights into market opportunities, adoption strategies, and use cases for sustainability-related…
AI is rapidly transforming how B2B tech buyers evaluate vendors and make purchase decisions. The closest comparison we have to this moment is 1996, when we entered the digital era, a revolution that massively changed customer behavior, markets, and entire go-to-market strategies and activities.
What’s different today is that growth is exponentially faster and greater. At this speed, technology vendors can no longer build assumptions based on what happened last year, last quarter, or even last month.
That means as we enter the AI and agentic era, CMOs and senior marketing leaders must rethink the way they plan. There’s incredible incentive to do so right now. Your buyers have already moved. They’re not only relying on AI to research and prioritize vendors, but they’re also using agents to act on their behalf. In fact, 80% of B2B tech buyers say they would use an agent in a complex transaction like responding to an RFI, IDC research shows.
Now is the time to transform your marketing plan and adapt to the new AI-mediated buyer journey.
With the market moving rapidly, CMOs and marketing leaders have a CEO-driven imperative to integrate AI and use it to drive growth. They’ll have to fill gaps in AI expectations between the C-suite and technology operations, but with careful planning they can advance their marketing strategy. As discussed in the webinar, there are several important trends CMOs must understand.
The rising importance of timely market assessments
To meet the CEO’s growth expectations, CMOs need to understand where they should place their bets. That’s especially tough in an AI-driven market, where intelligence ages fast. What was accurate six months ago could be false today, so they need to understand and validate findings continuously.
AI is ideal for this, and it’s what IDC Quanta is designed to deliver. CMOs can ask questions about market potential, sizing, and benchmarks, and receive a comprehensive overview about what the market looks like and where the opportunities are – all with just a single conversation.
Built primarily on IDC data and analyst intelligence, IDC Quanta can be layered on top of an organization’s proprietary data to get a more precise and accurate view. It will synthesize all of the information and create a detailed narrative quickly. CMOs can validate further and get advice from IDC analysts to fine tune the assessment and tailor it to their businesses.
Don’t wait for last quarter’s playbook to catch up. Watch the full webinar replay for the strategy built for a market that won’t hold still.
The evolution of the new buying committee
New buyers are emerging – and CMOs will need to be prepared with new messaging and new types of content to win them over. It’s no longer just the CIO or IT leader. In the AI and agentic era, full organizational orchestration is a priority, so the COO has significant sway over buying decisions. In addition, 42% of CEOs say they plan to hire a Chief AI Officer in the next 12 months.
As the focus increases on business process transformation, business leaders from across the organization are gaining a seat at the table. Security and governance concerns are also pulling the CISO back into the buying committee, as AI governance becomes core to the purchase decision.
Each buyer will have their own concerns and objections, which will require marketing teams to develop and personalize messaging and content for each.
Trust stalls AI adoption
Trust is one of the top barriers to AI adoption. Less than 5% of CXOs find fully autonomous agentic AI to be appealing, IDC’s research shows. There’s a certain level of caution that technology vendors must overcome to move buyers.
To do so, they will need to reframe how they position their solutions. CMOs can address the trust issue by focusing on innovation, strategic value, and how their technology will drive business transformation. It’s crucial to emphasize that agents will collaborate with humans. Messaging should also build confidence in how governance will be overarching, encompassing autonomous agents.
The AI-mediated buyer journey changes marketing
As B2B tech buyers integrate AI into more of their journey, CMOs need to orchestrate both human and AI interactions across the entire experience. Already, 63% of buyers say they always and often use AI to discover and evaluate vendors, and 80% say they trust information they receive from their AI-mediated journey to make sound business decisions. They’re even using AI for research typically conducted by humans in the past: 68% say they use AI to gain deeper technical understanding of how products and services work.
Technology vendors are finding that buyers are rewriting the rules for marketing. Today, they must market to both humans and AI. That means creating new content to meet the need of human buyers and attract the attention of AI engines. In this AI-mediated buyer journey, marketing teams need an entirely new content playbook: prioritizing interactive content over static, developing immersive content that allows buyers to experience your products, and creating hyper personalized content for a variety of personas.
This new AI-mediated buyer journey with both humans and AI means marketers need to rewire how they think about how things get done. Buyers are using AI to research and compare vendors. Technology vendors also need to integrate AI into their marketing process. And CMOs become the orchestrator of a combined human and AI workforce.
The characteristics that define leaders
A small cohort of technology vendors are adapting to the new journey faster than any of their competitors. These leaders that are transforming their global marketing organizations have the following characteristics in common:
Strategy: Comprehensive AI marketing strategy backed by strong executive sponsorship.
Focus: Innovation over efficiency, with humans and AI working together.
Workforce: AI-enabled teams supported by ongoing change management.
Foundation: Automated workflows built on advanced data and a real-time MarTech stack.
How to build an intelligence-led marketing strategy
So, what are the steps for building your 2027 intelligence-led marketing strategy and framework to keep pace with a rapidly changing buyer journey?
Plan. IDC Quanta can help you quickly identify and understand growth and market opportunities.
Assess. Evaluate your organization’s maturity across five areas: strategy, people and organization, processes, governance, data and technology. How far have you integrated or transformed your marketing process?
Sequence your 2027 investment. Build a phased roadmap based on your readiness. Don’t fund everything at once.
Our webinar covers each of these steps in greater detail. If you’re ready to jumpstart your strategic marketing plan and begin orchestrating the AI-mediated buyer journey,watch the replay of the full webinar today.
Christina Cardoza - Content Marketing Manager - IDC
Christina Cardoza is a Content Marketing Manager at IDC, where she specializes in brand content and social media strategy. With a background in journalism and editorial leadership, she has a proven ability to transform complex technology topics into clear, actionable insights.
IDC Environmental Policy
International Data Group is committed to protecting the environment, the health and safety of our employees, and the community in which we conduct our business. It is our policy to seek continual improvement throughout our business operations to lessen our impact on the local and global environment. We are committed to environmental excellence, pollution prevention and to purchasing products that reduce the use of natural resources.
We fulfill this mission by a commitment to:
Encouraging all partners to share in our mission
Understanding environmental issues and sharing information with our partners
Recognizing that fiscal responsibility is essential to our environmental future
Instilling environmental responsibility as a corporate value
Developing innovative and flexible solutions to bring about change
Using our platforms and position in the IT industry to promote sustainability
Minimize air travel to help reduce our impact on the environment
Minimize use of materials and energy consumption in our offices
Create a working environment that efficiently uses our office space
Develop and maintain a hybrid working model that benefits both our employees and business partners
Encourage employees to measure, minimize and collaborate on reducing energy consumption at home and in the office
Engaging employees and promoting active participation in environmental and sustainability initiatives
Leaving?
You are about to leave this section. Do you wish to continue?