国内AIインフラ市場は、いま大きな転換点を迎えています。これまで市場の成長を牽引してきたのは、AIモデルの「学習」を支えるAIインフラ投資でした。しかし今後は、推論を軸とした社会実装フェーズへの移行が進むとIDCではみています。AI活用がPoC(概念実証)から本番運用へと広がる中で、AIインフラの役割や求められる要件も大きく変化しつつあります。IDCでは、2026年を学習から推論への転換点と位置づけています。

1. 急成長する国内AIインフラ市場と「学習中心」からの転換

ここ数年、国内AIインフラ市場は急速な拡大を遂げました。ハイパースケーラーや国内クラウド事業者による大規模投資を背景に、2023年、2024年は共に前年比100%以上の成長を記録し、市場規模は2年連続で倍増以上となりました。国内AIインフラ市場の支出額は2025年には6,946億円に達し、今後は年間平均成長率(CAGR:Compound Annual Growth Rate)7.3%で成長し、2030年には約1兆円規模に迫るとIDCでは予測しています。

一方で、今後の成長を牽引する要因は大きく変化します。これまで中心だった学習用途に加え、業務の中で継続的にAIを活用する推論需要が拡大し、市場の主軸が移行していきます。IDCでは、2027年には国内AIサーバー市場において推論向けの支出が学習向けを上回ると予測しています。また、2025年から2030年のCAGRは推論向けが学習向けを10ポイント以上も上回る予測です。

2. 推論の拡大がもたらすAIインフラ利用の変化

IDCによる最新の調査「Japan Digital and AI Infrastructure Strategies and Investment Survey 2026」では、推論用途で利用予定のAIインフラはパブリッククラウドが過半を占める一方で、専有型インフラやエッジ環境といった「プライベートAIインフラ」も20~30%台に達しています。

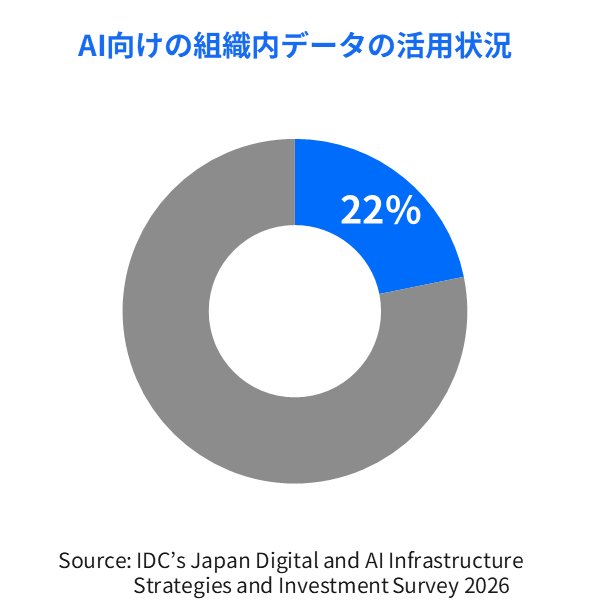
一方で、AI向けに組織内データを本格的もしくは高度に活用している企業は22%にとどまっています。現在は先行企業が中心となって、機密情報や個人情報を含む組織内データの AI での活用に取り組み始めている段階にあることを示しています。

IDCの調査では、こうした先行企業は今後、プライベートAIインフラを利用する意向が強くなっています。その背景には、自社のニーズに最適な構成の採用や、可用性やコストの予測可能性の高さ、さらに、法規制やソブリンAIへの対応を重視していることがあります。事業の安定的な継続性を考慮したうえで、コスト競争力と信頼性の高いAI基盤の整備を進めています。

  • AI向けに組織内データを本格的もしくは高度に活用している企業は22%にとどまっている。
  • 組織内データ活用の先行企業は、コストの競争力と予測可能性を向上し、ソブリンAIも考慮した信頼性の高いAI基盤の整備を進めるために、今後、プライベートAIインフラを利用する意向が強い。

AIインフラが国家戦略や企業競争力にも直結する基盤となるにつれて、ソブリンAIやデータ主権への対応も重要視されます。データの保護や所在管理、地政学リスクへの備えといった観点から、専有環境やソブリンクラウドの活用も拡大する見通しです。

3. AIインフラ向けサービス市場の拡大と競争軸の変化

AIインフラの導入拡大に伴って、構築・運用・保守を担うITインフラサービス市場も急成長しています。国内AI向けITインフラサービス市場は2025年の957億円から2030年には2,320億円へと拡大し、CAGRは19.4%に達する見込みです。AIインフラは設計や運用が高度化しており、液冷対応やデータセンター設備を含めた専門的な対応が求められることが、サービス需要を押し上げています。

市場の競争軸は、従来のハードウェア性能中心から、柔軟なインフラ選択やサービス提供能力、AIの本番実装を支援する総合力へとシフトしています。これまでは高性能GPUを軸としたAIインフラ製品や構築・運用サービスで先行したベンダーが市場を牽引してきましたが、今後はAI導入からアプリケーション開発、ハイブリッド環境の構築・運用、さらにはソブリンAI対応までを包括的に支援できる企業が競争優位を確立するとIDCはみています。

IDCが提供するレポートのご紹介

IDCでは、国内AIインフラ市場の変化を詳細に分析したレポートを発行しています。

本調査レポートでは、国内AIインフラ市場の構造変化を把握するため、2025年から2030年の市場予測をセグメント別に分析しています。サーバー/ストレージ別、サービスプロバイダー/エンタープライズ別、配備モデル別、産業分野別に加え、AIサーバー市場について、学習/推論別やアクセラレーテッド/ノンアクセラレーテッド別に予測しています。

また、国内AI向けITインフラサービス市場についても、顧客タイプ別およびサービスタイプ別に予測しています。さらに、AIインフラ需要の変化や主要ベンダーの動向も整理しており、今後の市場機会や競争環境の変化を明らかにしています。

これらの分析によって、学習から推論へのシフトに伴うAIインフラの需要構造の変化や、サービスプロバイダーとエンタープライズの投資動向の違い、今後拡大するサービス市場の機会を包括的に把握できます。

関連する調査やご相談について

より詳細なインサイトや市場動向については、当社アナリストへお気軽にご相談ください。

Yukihisa Hode - Research Manager, Infrastructure & Devices, Research, IDC Japan - IDC Japan

Yukihisa Hode is a research manager covering digital infrastructure strategies as well as AI infrastructure, IT infrastructure services, IT operations, hybrid/multicloud and hyperconverged infrastructure (HCI). He leads the research program on digital infrastructure strategies, providing insight and advice on the digital infrastructure through research reports, marketing content, and presentations to support IT and digital decision-making.

Geopolitical crises rarely arrive with clear warning. When they do, the pressure on digital infrastructure, supply chains, and technology operations becomes immediate. 

The war in the Middle East is a structural stress test for the modern digital economy and for the CIOs responsible for keeping businesses running through disruption. 

Unlike earlier periods of conflict, today’s enterprise IT environment depends heavily on cloud infrastructure, subscription-based services, and globally interconnected supply chains. Disruption is no longer contained. It can extend quickly across regions, systems, and partners. 

For CIOs, the challenge is not only managing risk. It is sustaining operations while adapting to changing conditions and maintaining the ability to support the business.

IDC Perspective: From Conflict to Continuity: How CIOs Can Respond to Disruption from the Middle East War.

Why this crisis is different for CIOs 

Enterprise IT has shifted from internally controlled environments to highly distributed ecosystems. 

Organizations now depend on: 

  • Cloud providers and platform services  
  • Distributed infrastructure and operations  
  • Global supply chains for technology components and delivery  

This dependency introduces new forms of exposure. 

Regional instability can affect: 

  • Application availability and performance  
  • Hardware deployment timelines  
  • Cyber threat activity  
  • Infrastructure and energy costs  

These pressures are already testing the assumptions built into many digital strategies. 

The priority for CIOs is to understand where exposure exists and how it could affect operations. 

Start with exposure mapping and scenario planning 

The first step is to identify where the organization is most exposed. 

CIOs should map dependencies across four dimensions: 

  • Employees and contractors located in or near affected regions  
  • Customers and revenue streams tied to impacted markets  
  • Suppliers and logistics routes connected to disrupted corridors  
  • Applications, data, and support operations dependent on regional infrastructure  

This exposure map becomes the foundation for decision making. 

Scenario planning builds on that foundation. It provides a structured way to prepare for multiple outcomes rather than relying on a single forecast. 

IDC outlines two scenarios that CIOs should actively consider: 

  • A period of sustained regional instability  
  • A broader escalation that introduces energy and cyber shocks  

Each scenario changes how organizations prioritize resilience, security, and investment decisions. 

See how the Middle East conflict is reshaping global IT spending.

What CIOs should prioritize now 

CIOs should focus on five immediate priorities. 

Revalidate cloud and infrastructure resilience 
Assess dependency on single regions or providers and identify gaps in failover readiness. 

Strengthen cyber readiness 
Expect increased threat activity and reinforce detection, response, and recovery capabilities. 

Diversify technology supply chains 
Identify potential points of disruption and reduce reliance on single suppliers or routes. 

Review data sovereignty and compliance exposure 
Geopolitical tension often accelerates data localization and regulatory requirements. 

Prepare workforce continuity plans 
Ensure employees and teams can continue operating under disrupted conditions, including remote work and alternative communication channels. 

These priorities are not new. What is changing is the need to address them simultaneously and at speed. 

Leading through disruption 

Resilience is not only a technical challenge. It is a leadership challenge. 

CIOs must provide clarity and direction during periods of uncertainty. The organizations that respond most effectively are those where teams understand the mission and are able to act quickly. 

Effective leadership actions include: 

  • Establishing a clear operational focus on protecting critical systems  
  • Enabling faster decision making across teams  
  • Breaking large challenges into manageable objectives  
  • Identifying opportunities to simplify and strengthen existing environments  

Periods of disruption often accelerate changes that were already needed. They expose technical debt, operational inefficiencies, and gaps in resilience. 

The organizations that make progress during these moments treat disruption as a point of action rather than a pause. 

Explore the Middle East conflict resource center.

From disruption to operational readiness 

The current environment reflects a broader shift in how geopolitical events interact with digital operations. 

CIOs are no longer preparing for isolated incidents. They are operating in conditions where disruption can affect multiple parts of the enterprise at the same time. 

This requires a more continuous approach to resilience: 

  • Ongoing visibility into dependencies and risk exposure  
  • Planning that accounts for multiple possible outcomes  
  • Integration of resilience into everyday operations  

Organizations that build this capability will be better positioned to sustain performance through uncertainty. 

Explore the full scenario framework 

Understanding exposure is the starting point. Acting on it requires a structured approach. 

The IDC Perspective expands on these scenarios and outlines how CIOs can translate them into operational decisions, including: 

  • Scenario-specific implications for IT spending and AI investment  
  • Infrastructure, cybersecurity, and workforce continuity considerations  
  • Key risk signals to monitor as conditions evolve  

Want deeper insight into how these shifts are affecting technology investment? Watch how the Middle East conflict is reshaping global IT spending.

Rick Villars - Group VP, Worldwide Research - IDC

Rick is IDC's chief analyst guiding research on the future of the IT Industry. He coordinates all IDC research related to the impact of Cloud and the shift to digital business models across infrastructure, platforms, software, and services. He helps enterprises develop effective strategies for using their diverse portfolio of cloud investments and applications. He supplies early guidance on implications of critical innovations such as the shift to cloud-based control platforms for deploying/managing infrastructure, data, and code delivery as well as the emergence of AI as a critical IT workload and part of all IT products/services.

Daniel Saroff - GVP, Consulting and Research Services - IDC

Daniel Saroff is Group Vice President of Consulting and Research at IDC, where he is a senior practitioner in the end-user consulting practice. This practice provides support to boards, business leaders, and technology executives in their efforts to architect, benchmark, and optimize their organization's information technology. IDC's end-user consulting practice utilizes our extensive international IT data library, robust research base, and tailored consulting solutions to deliver unique business value through IT acceleration, performance management, cost optimization, and contextualized benchmarking capabilities.

Lars Goransson - Vice President, Research, Worldwide Services - IDC

Lars Goransson is Vice President of Research, Worldwide Services at IDC. He leads IDC’s global research and advisory for IT and business services, focusing on how technology suppliers and buyers can navigate market shifts, innovation, and business transformation. Lars’s research explores the evolving dynamics of the worldwide services landscape, providing clients with trusted tech intelligence and evidence-based insight to make confident decisions in a fast-changing digital economy. His work illuminates the path forward for organizations seeking to anticipate demand, validate investments, and seize new opportunities.

Linus Lai - Group Vice President, Research - IDC

Linus Lai is a distinguished member at IDC Asia/Pacific, in which he spearheads research in digital business, trust, infrastructure, and services. With over 25 years of industry experience, Linus is based in Sydney and serves as the chief analyst for Australia and New Zealand (ANZ). He is a founding member of IDC's Emerging Technology Advisory Council and a respected senior member of the region's CIO100, CSO, and Future Enterprise awards. In his role, Linus provides strategic insights for digital leaders and the technology sector, focusing on sourcing strategies and emerging technology across Asia/Pacific. His expertise has earned him numerous accolades for his contributions to country, regional, and quality research. Previously, as the head of research in Southeast Asia, Linus was instrumental in expanding IDC's presence and influence in the region. His thought leadership is frequently sought after through regular features in various publications and media outlets. He is also a prominent speaker at industry forums, keynote events, and strategy workshops. Before joining IDC, Linus worked with a leading outsourcing service provider with a digital banking focus. He holds a Master of Science degree from the University of Lincoln, United Kingdom.

Mary Johnston Turner - Research VP - IDC

Mary Johnston Turner is Research Vice President within IDC's worldwide infrastructure research organization and global research lead the Digital Infrastructure Strategies practice. Mary's coverage tracks enterprise tech buyer sentiment related to compute, storage, edge, operations and cloud platforms and deployment models. Current research priorities emphasize the impact of rising requirements for data-driven AI-Ready Infrastructure, Fit-for-Purpose Hybrid and Multicloud Architectures, Autonomous Operations, Edge Integration, and collaborative business and IT governance. Her practice emphasizes the voice of the enterprise customer, based on surveys and in-depth analysis of best practices and infrastructure investment priorities. Mary's research emphasizes consideration of topics related to AI-ready infrastructure, tech debt avoidance, data center modernization, mainframe modernization, infrastructure governance, staffing and skills priorities, and infrastructure operating models. Within the infrastructure research organization, Mary collaborates with other practice leads to ensure coherency and alignment of insights and published research.

Laurie Buczek - GVP, Research - IDC

Laurie Buczek is the Group Vice President of Executive Insights at IDC, where she spearheads the global research initiatives that shape the industry's understanding of digital business transformation, evolving buying behaviors, and technology investments. She leads IDC's premier research practices, including the CMO Advisory Practice, C-Suite Tech Agenda, and Digital to AI Business Transformation. As the principal analyst for the CMO Advisory Practice, Laurie advises senior marketing leaders on driving business growth through deeper customer connections and the strategic evolution of the marketing function, with a keen focus on AI's transformative impact. Her expertise and thought leadership empower executives to navigate the intersection of technology, business strategy, and customer engagement in today's dynamic digital landscape.

Michelle Abraham - Sr. Director, Research Cybersecurity - IDC

Michelle Abraham is a Senior Research Director in IDC's Security and Trust Group responsible for the Security Information and Event Management (SIEM), Exposure Management and Related Artificial Intelligence Technologies practice. Ms. Abraham's core research coverage includes SIEM platforms, exposure management platforms, attack surface management, breach and attack simulation, cybersecurity asset management, and device vulnerability management alongside AI-related security topics.

Craig Robinson - Research Vice President , Security Services - IDC

Craig Robinson is a Research Vice President within IDC’s Security Services research practice, focusing on managed services, consulting, and integration. Coverage areas include Managed Detection and Response services, Cyber Resilience, and Incident Readiness & Response services.

Each year, IDC’s Smart Cities North America Awards provide a unique window into how cities are evolving—not just in ambition, but in execution. This year’s entries, finalists, and winners tell a clear and compelling story: Smart Cities are no longer conceptual. They are operational, integrated, and delivering measurable impact in communities of all sizes.

At their core, Smart Cities have always been about using technology to improve the quality of life for residents, businesses, and visitors. What stands out in 2026 is how firmly that vision has translated into action.

From experimentation to execution

One of the most striking trends across this year’s submissions is the level of operational maturity. Projects are no longer exploratory pilots or isolated proofs of concept. Instead, they are focused on execution and performance.

We saw widespread adoption of technologies that enable cities to function more effectively every day, including digital procurement and workflow automation, GIS and data integration, real-time monitoring and dashboards, and AI-enabled analytics. These capabilities are not just enhancing services—they are transforming how cities operate at a foundational level, particularly in critical systems such as public safety, fire response, and water management.

Another notable trend is the growing—but pragmatic—use of AI. Rather than being positioned as a standalone innovation, AI capabilities are embedded within broader solutions to analyze data, support decision-making, automate workflows, and improve service delivery. We saw this in projects focused on procurement automation, real-time analytics, and operational intelligence, as well as in Scottsdale’s AI-powered real-time crime center.

AI in Smart Cities is not experimental or abstract—it is being applied in targeted ways to solve specific problems and deliver measurable outcomes. This was also reflected in the many panels at the Smart Cities Connect conference, which showcased how cities are using AI in defined use cases to achieve concrete results.

This shift signals an important milestone: Smart Cities have moved beyond experimentation and into sustained, real-world delivery.

Breaking down silos: The rise of systems thinking

Another defining characteristic of the 2026 entries is the move toward integrated, multi-domain approaches. Cities are increasingly designing solutions that cut across traditional silos, embracing systems-thinking models rather than isolated implementations.

Many of this year’s projects span multiple functional areas or departments, with common combinations including public safety, infrastructure, and transportation; administration, civic engagement, and digital equity; and urban planning paired with resiliency initiatives.

This evolution reflects a growing ability to collaborate across departments and address challenges in an interconnected way, using coordinated solutions that bring together data, technology, and stakeholders. Key to this shift is the increasing influence of innovation teams, leaders, and smart city directors acting as city-wide coordinators.

Technology in service of community priorities

Across all categories, one theme was consistent: technology is being applied to clearly defined community needs.

Projects focused heavily on areas such as flood mitigation and environmental monitoring, community resiliency, accessibility and digital inclusion, and public safety innovation. Many also emphasized strong cross-sector partnerships, bringing together government agencies, private sector partners, nonprofits, and academic institutions.

This alignment between technology and community priorities reinforces a critical principle of Smart Cities: technology is not the goal—it is the enabler. The most impactful projects start with a clear understanding of local challenges and apply technology deliberately to address them.

Innovation that is scalable, agile, and inclusive

Another encouraging finding from this year’s awards is how accessible Smart City innovation has become.

A significant number of projects were delivered with relatively modest budgets, with 37 initiatives under $100,000 and only a handful exceeding $10 million. At the same time, most projects were implemented in less than two years.

This demonstrates that meaningful innovation does not require massive, multi-year capital investments. Instead, cities are embracing modular, agile approaches that allow them to move quickly, scale solutions, and deliver results.

Equally important, innovation is no longer concentrated in large metropolitan areas. This year’s submissions highlight strong participation from mid-sized cities and regional communities, underscoring that Smart City capability is widely distributed across North America.

Celebrating the 2026 finalists and winners

At the heart of the Smart Cities Awards is the recognition of the cities and partners leading this transformation.

This year’s awards highlight the breadth of innovation happening across North America. The finalists and winners exemplify what is possible when vision meets execution and demonstrate the diversity of approaches organizations are taking. A few examples include:

  • The City of Boston, advancing both digital equity and operational efficiency through initiatives such as Green Light for Education, which addresses student access and transportation challenges, and BidBot, an AI-enabled tool transforming municipal procurement.
  • The City of Pittsburgh, driving climate-focused urban planning through initiatives like Planting with Purpose, using data and partnerships to strengthen community resiliency and guide sustainable development.
  • Austin Water, modernizing infrastructure through advanced metering initiatives that improve water management, operational visibility, and customer service.
  • New Jersey Transit, enhancing resiliency and infrastructure intelligence with its Storm Surge Early Warning System, using real-time data to anticipate and respond to flooding risks.
  • The City of Phoenix, pushing innovation across multiple fronts, particularly in public safety—from its Unmanned Aerial Systems (UAS) program to broader efforts in real-time operations and community engagement.
  • The City of Scottsdale, recognized as the overall winner for its AI-powered real-time crime center and drone-as-first-responder program, highlighting the power of integrated, data-driven approaches.

Each finalist and winner represents not just a successful project, but a model for others to learn from and build upon.

Looking ahead

One of the most compelling aspects of Smart Cities is that while the definition continues to evolve, the purpose remains constant: improving communities and addressing complex urban challenges through technology.

Today’s Smart Cities are practical, multi-domain, partnership-driven, and deeply focused on outcomes. They are powered by technology, but centered on people—the practitioners, innovators, and leaders working every day to make their communities better.

As we celebrate this year’s winners and finalists, we are also recognizing a broader movement—one that is steadily transforming how cities operate and how they serve their residents.

Ruthbea Yesner - Program VP - IDC

Ruthbea Yesner is the Vice President of Government Insights at IDC. In this practice, Ms. Yesner manages the US Federal Government, Education, and the Worldwide Smart Cities and Communities Global practices. Ms. Yesner's research discusses the strategies and execution of relevant technologies and best practice areas, such as governance, innovation, partnerships and business models, essential for government and education transformation. Ms. Yesner's research includes analytics, artificial intelligence, Open data and data exchanges, digital twins, artificial intelligence, the Internet of Things, cloud computing, and mobile solutions in the areas of economic development and civic engagement, urban planning and administration, smart campus, transportation, and energy and infrastructure. Ms. Yesner contributes to consulting engagements to support K-12 and higher education institutions, state and local governments and IT vendors' overall Smart City market strategies.

Alison Brooks - Research Vice President, Smart Cities Strategies, Public Safety - IDC

As Research Vice President for IDC's Worldwide and US Public Safety practice, Dr. Alison Brooks focuses on public safety and first responder research and advisory services, with a specialization in Smart Cities and Communities. Dr. Brooks' research provides detailed analysis on the digital transformation of public safety and first responders, covering topics such as digital evidence management, integrated physical security solutions, intelligence-led policing, advanced analytics, video surveillance and visualization, first responder communications and alternative policing frameworks. Dr. Brooks has held a number of positions with IDC over the past 15 years, previously working as IDC Canada's Director of public sector research.

Agentic AI is moving from experimentation toward enterprise orchestration. Early deployments emphasized efficiency. As systems scale, the more significant shift lies in how enterprises redesign value creation, capture, and long-term advantage.

IDC’s FutureScape 2026 predictions identifies this transition as one of four strategic imperatives shaping the agentic future. Unlocking innovation beyond productivity defines how organizations translate AI maturity into new business models, revenue streams, and sustained competitive position.

Innovation beyond productivity refers to the structural redesign of business models, industry boundaries, and economic logic enabled by agentic AI operating across enterprise portfolios and ecosystems. It reflects how organizations convert AI maturity into scalable growth, differentiated customer value, and durable competitive advantage.

This is the focus of Pillar 4 within FutureScape 2026.

The productivity plateau

The first wave of AI delivered measurable gains. Contact centers reduced handle times. Back-office operations automated repetitive tasks. Sales and marketing teams improved throughput. These gains were important because they made AI investment tangible.

However, efficiency advantages diffuse quickly. What creates competitive differentiation in one quarter becomes standard capability the next. Productivity improvements, when layered onto existing operating models, eventually reach saturation.

Productivity-first strategies constrain long-term impact in three ways:

  1. They reinforce functional silos. AI is deployed by department, and each team optimizes local objectives.
  2. They lock in current assumptions. Optimization strengthens workflows designed for earlier market conditions.
  3. They produce linear gains. Efficiency improvements reach saturation when underlying structures remain unchanged.

The constraint is not AI capability. The constraint is operating design. When AI is layered onto legacy structures without structural redesign, outcomes remain incremental.

Innovation as the structural payoff of agentic AI

Innovation occurs when AI reshapes enterprise structure rather than simply accelerating task execution. Agentic AI enables coordinated decision-making across marketing, supply chain, finance, service, and ecosystem partners. Systems move from isolated automation toward orchestration embedded in enterprise operating models.

Innovation beyond productivity highlights three requirements for structural innovation in the agentic era:

  • Redefined industry boundaries. Agentic AI facilitates collaboration between domains that previously operated independently, reshaping competitive landscapes.
  • New economic logic. When agents operate autonomously at scale, assumptions about capacity, cost, and output change. Business cases designed for linear improvement do not capture compounding value created through coordination.
  • Governance as infrastructure. Governance must support cross-domain orchestration while embedding accountability into operating design.

Where value models are being rebuilt

FutureScape research identifies structural pressure points where value creation is already evolving. These signals reflect changes in pricing structures, industry organization, and coordinated delivery models.

Pricing model evolution
Traditional pricing frameworks were built around human labor and seat-based licensing. As agent interactions increase, value shifts from access to measurable outcomes. Enterprises and providers are redesigning pricing logic to reflect agent-mediated execution and results. This indicates a change in value capture, not simply a change in delivery.

Life sciences reinvention
Agentic AI is transforming pharmaceutical research and development. By 2030, 80 percent of pharmaceutical companies are projected to partner with TechBios, leveraging agentic AI and quantum computing to reduce R&D costs and failure rates. This signals new industry architectures built on coordinated discovery and ecosystem collaboration.

Healthcare system coordination
Healthcare has traditionally operated through linear care pathways. Agentic AI enables continuous orchestration across diagnosis, treatment, monitoring, and escalation. By 2030, one in three top-tier hospitals is expected to deploy AI agents delivering real-time decision support and autonomous workflows with high levels of accuracy. Clinical value becomes embedded in system coordination rather than isolated interventions.

Consumer ecosystem realignment
Immersive digital environments and gaming platforms are evolving into coordinated ecosystems for engagement and commerce. By 2026, two-thirds of Gen Z and Gen Alpha are projected to spend more time gaming than on social media. This signals movement toward platforms designed for persistent interaction and orchestrated value creation.

Rethinking AI ROI

As AI becomes integral to enterprise operating logic, traditional ROI metrics require reassessment. Leaders must reconsider three assumptions:

  • Short-term cost savings do not define strategic value.
  • Pilot programs do not create durable advantage without integration.
  • Model accuracy does not guarantee enterprise impact if objectives remain unchanged.

Legacy metrics focus on time saved and expenses reduced. Structural innovation requires evaluation of adaptability, cross-functional coordination, and long-term growth potential.

This shift aligns AI outcomes with enterprise design and economic logic, not isolated task performance.

Innovation as portfolio and ecosystem strategy

Agentic AI generates the greatest impact when managed as a coordinated portfolio rather than discrete initiatives. Each deployment should strengthen enterprise adaptability, improve cross-functional coordination, and expand future strategic options.

Unified governance frameworks support this model by embedding oversight into operating systems and enabling autonomous action within defined boundaries.

As agents operate across organizational and ecosystem boundaries, value creation becomes interdependent. Competitive advantage becomes systemic and embedded within enterprise design.

Defining the next horizon

Productivity remains necessary. Structural innovation determines sustained advantage.

The transition highlights a pivotal transition within the agentic journey. Agentic AI is redefining economic models, industry boundaries, and enterprise architecture. Organizations that redesign for orchestration, portfolio coordination, and ecosystem alignment position themselves for long-term growth in the AI-fueled economy.

Explore innovation beyond productivity in depth

FutureScape 2026 includes detailed research, analyst perspectives, and events that expand on the innovation beyond productivity theme.

Core Research

Analyst perspectives

On-demand webinars

IDC - -

International Data Corporation (IDC) is the premier global market intelligence, data, and events provider for the information technology, telecommunications, and consumer technology markets. With more than 1,300 analysts worldwide, IDC offers global, regional, and local expertise on technology and industry opportunities and trends in over 110 countries. IDC’s analysis and insight help IT professionals, business executives, and the investment community make fact-based technology decisions and achieve their key business objectives.

随着生成式AI、大模型及Agent能力持续演进,围绕“AI是否会取代SaaS”的讨论正在快速升温。基于当前企业采用进度、软件支出变化、AI规模化落地情况以及企业工作方式转型趋势的综合观察,IDC的判断是:AI不会在中短期内取代SaaS,但将推动SaaS进入新一轮结构性重构周期。 企业软件市场未来的主要变化,不是SaaS的消失,而是SaaS从“功能交付工具”向“智能执行平台”演进。

当前,AI与SaaS之间并非替代关系,而更接近于“能力叠加”与“价值重定义”关系。随着企业客户从模型试点走向业务落地,从当前市场需求变化看,企业对软件平台的要求,正在从基础数字化和AI集成能力,进一步延伸至以AI Agent为代表的智能能力,包括任务执行、流程协同、系统连接、治理承接及业务结果支撑。

在明确 AI 与 SaaS 并非替代、而是能力叠加的核心关系后,我们可以从企业预算与市场结构的维度,进一步拆解这一演进趋势的现实表现 ——AI 技术的渗透并未削弱软件市场的基本盘,反而在重构企业对软件价值的判断标准与采购逻辑。

观点一:AI预算快速增长,但软件支出并未被替代

IDC数据显示,2025年全球生成式AI支出将达到 1843亿美元,同比增长151.6%。与此同时, 2025年全球IT总支出将达到 6.8万亿美元,其中软件支出将达到1.3万亿美元,同比增长 14.2%。这表明,AI投资扩张并未系统性挤压企业软件预算,反而正在推动企业重新定义软件的能力边界。

从市场结构看,企业并没有因为AI出现而停止采购软件,而是在加速采购“具备AI能力的软件”。这意味着,SaaS的需求基础并未减弱,但产品标准正在提升。未来,缺乏智能能力、缺乏AI与业务流程融合能力以及缺乏数据壁垒的传统SaaS产品,竞争压力将加大;而能够承接AI任务并支撑流程执行的平台型软件,战略重要性将持续提升。

观点二:AI采用率提升很快,但规模化价值兑现仍处于早期阶段

IDC的数据显示,2025年,亚太地区企业平均每年开展17.9个生成式AI概念验证(PoC)项目,PoC转入生产环境的比例为34.5%,也就是说,每10个PoC项目中约有3至4个最终进入生产阶段。在KPI达成率方面,亚太地区平均为36.8%,意味着进入生产环境的GenAI服务中,约37%能够实现预期业务目标。这些最新数据表明,企业对AI试点的热情依然高涨,但从PoC走向规模化生产的转化率,以及业务成效的实际达成率,仍有较大提升空间。

这表明,AI要从“具备生成与回答能力”进一步走向“具备执行能力、可审计性、可复制性和规模化应用能力”,仍需经过持续的场景验证与业务实践。仅依靠AI模型本身,尚不足以形成完整的企业级价值闭环,企业仍需要由业务系统与平台能力持续提供数据访问、权限控制、复杂流程编排、主数据管理及合规治理等关键支撑能力。也正因为如此,SaaS在AI时代并不会被削弱,反而将在任务执行、流程承接与治理支撑等方面承担更加重要的角色。

观点三:AI正在改变企业应用软件的交互方式与价值交付逻辑

传统SaaS的核心价值,在于以模块化、标准化的方式承载企业流程,并通过菜单、表单、权限和审批机制推动业务数字化落地。但随着生成式AI和AI Agent能力不断渗透,企业软件的交互逻辑正在发生明显变化:从过去的 “用户操作功能” , 逐步转向 “用户提出需求、系统理解意图并执行任务” 。在这一变化过程中,软件价值的衡量标准也在同步改变。企业关注的重点,正在从功能是否齐全,转向任务完成效率、流程自动化水平,以及对实际业务结果的支撑能力。

IDC预测,到2027年,约有50%的企业将在核心业务流程中引入AI agents,重塑人与机器之间的协作方式。这一趋势表明,AI agents正在从辅助工具逐步演变为企业工作体系的重要组成部分,而不再只是单点能力的补充。这也意味着,未来的软件平台,无论是SaaS还是企业级PaaS,都不再只是承担数据录入和流程流转的基础角色,而将进一步承担任务编排、系统集成、过程留痕和治理支撑等职责,成为AI执行任务时所依赖的业务底座。

与此同时,AI也正在重塑企业软件的交付方式与商业模式。基于用量的定价、智能体驱动的交互界面,以及基于结果的价值衡量,正在对传统的按席位订阅模式形成冲击。这种变化并不只停留在概念层面,而是已经在市场中逐步发生。

观点四:将被替代的更可能是低壁垒、浅流程的SaaS产品

从竞争格局变化看,AI对SaaS市场的影响并非均匀分布。预计首先受到冲击的,将是那些功能相对单一、流程嵌入程度有限、差异化不足,且主要依赖界面交互提供价值的轻量型SaaS产品。随着AI Agent逐步具备任务理解、流程拆解与自动执行能力,这类产品的独立价值空间可能被进一步压缩。

相比之下,深度嵌入企业核心流程、掌握关键业务数据、具备权限控制与合规支撑能力,并拥有行业知识积累的平台型软件,在AI时代更可能提升其战略重要性。这类平台不仅更有条件承接AI Agent的任务执行与流程协同,也更有可能在未来企业软件架构与采购体系中占据核心位置。

IDC中国企业级应用软件市场高级研究经理徐文婷认为,未来2-3年,企业将不会简单以AI替代现有软件系统,而是要求软件平台具备AI原生能力,并能够支撑AI Agent在业务场景中的应用。预计市场竞争焦点将逐步从功能覆盖转向任务执行、流程自动化和业务结果支撑能力。对SaaS厂商而言,关键不在于是否面对AI技术本身,而在于能否将AI有效嵌入企业级数据、业务流程和治理框架。从当前市场发展看,AI正在重塑SaaS的产品定义,但尚未改变企业对系统平台的根本需求。随着AI Agent从试点走向生产环境,SaaS将进一步向平台化和智能化演进,并承担更多任务执行与治理支撑职能。

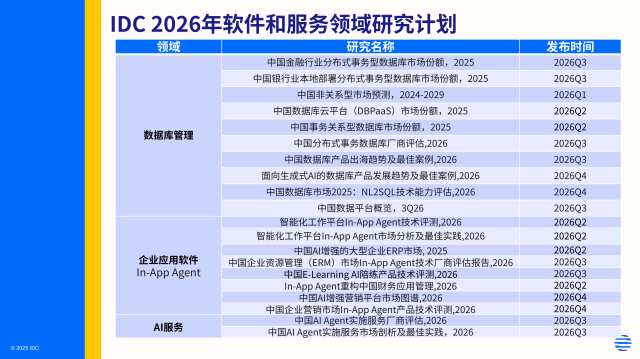
为了更好的帮助用户了解企业级软件AI的发展动态和未来趋势,IDC正式启动《中国AI-Enable ERP市场份额研究,2026》报告、《中国企业资源管理(ERM)市场AI Agent技术厂商评估报告,2026》报告研究,欢迎大家与我们保持沟通交流,与IDC共同开展更多前瞻性与实践性研究。

IDC相关研究报告:

Worldwide AI and Generative AI Spending Guide 2025

Worldwide Black Book 2025

Automation, AI, and Agentic AI for FoW: Worldwide Tech Buyer Perspective Doc#:EUR154249426

IDC Survey: Enterprise AI Trends – the Latest Survey Insights Doc#:AP53632426

IDC 2026年软件和服务领域研究计划:

如需进一步了解与研究相关内容或咨询 IDC其他相关研究,请点击此处与我们联系。

2026 年 3 月,“算电协同” 首次被写入《政府工作报告》,标志着算力与电力系统的深度融合正式上升至国家战略层面。当前全球 AI 产业竞争正从技术赛点转向成本赛点,这一战略落地不仅能化解算力快速增长与能源供给之间的结构性矛盾,更可依托 AI Token 跨境服务输出带动电力资源数字化出口,推动我国算力竞争迈入电力系统调度与协调能力比拼的全新阶段,为数字经济出口打造新增长极。

战略落地:政策沉淀与能源转型的必然结果

算电协同升级为国家战略,是长期政策铺垫与内需驱动的必然结果。早在 2023 年 12 月,“算电协同” 概念首次出现在《关于深入实施 “东数西算” 工程加快构建全国一体化算力网的实施意见》中;2024 年,国家发改委、能源局等部门在《加快构建新型电力系统行动方案(2024—2027 年)》中,为算电协同配套项目制定了具体实施纲领,其推进节奏与我国新型电力系统建设、能源转型的时间线高度契合。

从能源供给端来看,2025 年底我国风电光伏装机占比达 47.3%,首次超过煤电;非化石能源发电量占比升至 42.9%,风光新增发电量占全社会新增用电量的 97.1%,新能源已成为用电增量的核心供给主体。但现阶段能源与算力布局仍存在明显矛盾:一方面存在结构性、时段性供电紧张的时间错配问题,另一方面是东部算力需求旺盛但绿电资源稀缺,西部绿电富集但算力需求不足的空间错配问题。算电协同不仅是解决时空错配的抓手,更承担着推动区域协调发展、保障国家算力安全、完善新型电力系统、落地 “双碳” 目标的多重使命,其核心是将我国电力系统的产业优势转化为数字经济的竞争优势。

全球竞争:算力竞争的终局是电力系统综合实力的较量

全球 AI 产业规模化落地,推动算力需求呈指数级增长,算力消耗与电力供给的强绑定成为行业发展的核心特征。IDC 数据显示,2023-2028 年全球智能算力五年复合增长率达 46.2%,2025 年我国智算规模达 1037.3EFLOPS,同比增长 43%,这背后是 AI 大模型训练与推理规模化落地带来的算力需求爆发。算力需求的快速攀升直接推高电力消耗,2025 年我国 AI 数据中心 IT 能耗预计达 77.7 太瓦时,2027 年将增至 146.2 太瓦时,五年实现 6 倍增长,电力供给端的压力持续加大。

全球 AI 产业竞争已出现阶段变化,上半场竞争聚焦芯片等核心技术突破,下半场则转向电力系统综合实力的较量,成本竞争趋势显现:低成本、稳定且绿色的电力供给是核心竞争力。

模式创新:AI Token 开创电力出口新模式

算电协同将继续推动我国电力出口模式转型。通过 “电力转化为算力、算力生成 Token”,实现电力资源的数字化跨境服务输出。与 2000 年后我国电子家电、智能手机、新能源汽车等实体商品出口不同,AI Token 属于数字服务贸易范畴,依托 API 电子传输实现跨境交付,且受 WTO 电子传输关税豁免规则保护,形成了数字经济领域的 “免税高速公路”,降低了跨境服务输出的成本与壁垒。

当前全球 AI Token 产业竞争呈现明显的层级特征,表层是 AI 模型技术的比拼,中层是算力服务能力的竞争,而底层则是电力体系综合实力的较量。在全球 AI Token 竞争中中国拥有四大核心优势:

1. 电力规模优势:2025 年全国用电量突破 10 万亿千瓦时,电力供给能力稳居全球前列;

2. 成本优势:中西部地区拥有丰富的低成本绿电资源;

3. 布局优势:“东数西算” 与 “算电协同” 双战略加持下,我国算力布局与能源布局的协同性提升;

4. 技术优势:我国 AI 模型性价比高、开源生态强大,为算力服务与 AI Token 产业提供有力支撑。

未来方向:电力和算力的双螺旋演进

未来,算电协同发展将聚焦三大核心方向——推动实现电力服务算力、算力反哺电力的双向赋能、提升能源与算力资源的配置效率。

1. 持续推进 “算力跟着电走”,推动算力设施向绿电资源集中区域集聚,最大化利用低成本绿电;2. 推动算力错峰用电落地,将非实时性算力任务合理安排在电力低谷时段;

3. 推动算力成为电网可调节资源,助力电网实现削峰填谷,提升电网运行的稳定性。

产业机遇:算电协同背景下,IT 供应商迎市场新空间

算电协同战略落地为 IT 技术供应商打开了新市场空间,IDC认为有四个机会窗口:

1. 算力电力协同调度系统开发需求爆发,全国一体化算力监测调度、源网荷储一体化管控等场景,亟需能实现算力负荷与电力供应动态匹配的智能调度平台;

2. 绿色算力基础设施技术升级需求凸显,液冷温控、高密度供电、低 PUE 数据中心改造等技术成为算力设施建设标配,绿电直连配套的数字化适配技术也迎来蓝海市场;

3. 跨域融合技术服务空间广阔,算力枢纽与新能源基地协同布局背景下,数字孪生、AI 能效优化、跨境算力服务 API 搭建等技术服务需求快速增长;

4. 中西部算力基建配套市场持续扩容,“算力跟着电走” 的布局思路下,中西部新能源富集区的算力集群建设,将带来服务器部署、算力网络搭建、边缘计算节点建设等大量项目机会。

IDC 认为,未来全球算力竞争不再局限于规模比拼,而是转向算力、电网、储能、调度的系统能力综合较量。算电协同作为我国新型基建的重要组成部分,其深度推进不仅能推动新能源高效消纳、降低数据中心运营成本、提升我国 AI 产业全球竞争力,更能优化电网资源配置、稳定居民用电成本、推动绿色 AI 服务普惠化。而以 AI Token 为纽带的电力数字化出口,也将成为我国数字经济出口的全新增长极。对于 IT 技术供应商而言,当前正处于算电协同领域的市场窗口期,企业需紧密关注国家及地方政策导向,积极融入行业生态,与电力运营商、发电集团、电力设备商、综合能源服务商等主体深化合作,才能把握产业发展机遇。

IDC相关研究报告:《IDC Perspective 电力算力协同发展趋势预测与市场研判,2025》(Doc#CHC52926825)

算电协同正在成为数字基础设施与能源体系深度融合的重要方向,也将重塑全球算力产业的竞争格局。围绕这一趋势,IDC已在算力基础设施、数据中心能源管理、电力数字化以及绿色算力发展等领域持续开展研究。未来,IDC将持续发布相关研究成果与产业洞察,深入解读算电协同的发展趋势与市场机遇,欢迎持续关注IDC在数字能源与算力产业领域的最新研究与观点。

如需进一步了解与研究相关内容或咨询 IDC其他相关研究,请点击此处与我们联系。

2026年全国两会释放明确信号:“深化拓展人工智能+”与“打造智能经济新形态”,正成为ICT市场增长的双引擎。政府工作报告中强调的“促进新一代智能终端和智能体加快推广”、“推动重点行业领域人工智能商业化规模化应用”以及“实施超大规模智算集群、算电协同等新基建工程”,为企业级ICT市场的持续扩张提供了明确的政策方向。IDC基于最新发布的2026年V1版《全球ICT支出指南:行业与企业规模》(Worldwide ICT Spending Guide Enterprise and SMB by Industry)及《中国IT市场省级及云解决方案支出指南》(China Provincial Cloud Solutions Spending Guide),对中国ICT市场的结构性机遇进行了梳理。

基于上述指南的数据分析,IDC从市场格局、技术演进、行业赛道等维度,提炼出中国ICT市场的五大核心洞察:

洞察一:市场稳健增长,“深化拓展‘人工智能+’”成核心引擎

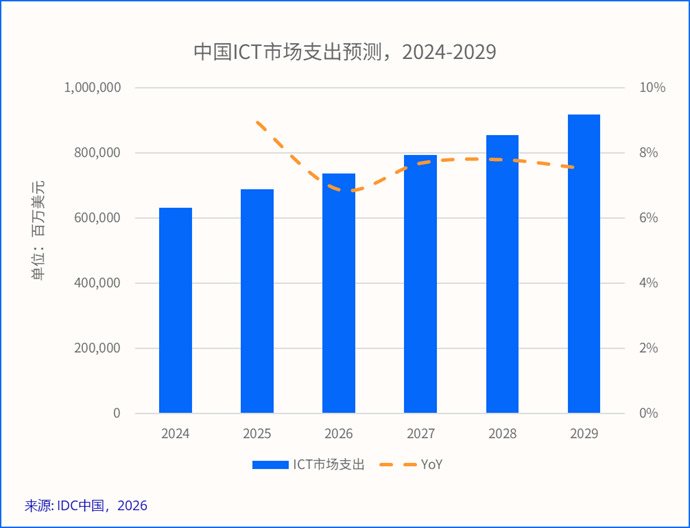
IDC《全球ICT支出指南:行业与企业规模》数据显示,2025年中国ICT市场投资规模为6889亿美元。展望未来,中国ICT市场支出将以7.8% 的五年复合年增长率稳步增长,到2029年有望突破9187亿美元。

从企业级视角来看,这一增长态势更为强劲。企业端的“‘人工智能+’深化拓展”战略正驱动着从基础设施到应用服务的全链条投入。IDC《全球ICT支出指南:行业与企业规模》预测,到2029年中国企业级ICT市场规模将达到5120亿美元,五年复合增长率13.3%,高于整体市场增速,成为推动新质生产力发展的关键力量。

洞察二:硬件为基,软件与服务引领智能化转型

IDC《全球ICT支出指南:行业与企业规模》数据显示,中国企业级ICT市场在硬件、软件、IT服务等多个领域展现出差异化的发展前景。

硬件:规模最大的“压舱石”。作为数字化转型的核心基础设施,硬件市场依然是当前中国企业级ICT支出中规模最大的组成部分,2025年占比超过五成。值得注意的是,AI训练和推理需求的爆发直接拉动了对GPU服务器、高性能存储及相关网络设备的投入,服务器和存储市场的投资到2029年有望实现24.4%的五年复合年增长率,成为硬件领域中增长最快的子市场。

软件:智能化转型的核心引擎。随着生成式AI的加速落地,软件正在成为企业智能化决策、业务流程自动化和数据治理的核心载体。IDC预测,2029年中国企业级软件市场规模预计达到933亿美元,五年复合增长率13.6%。其中,受到大模型发展的驱动,应用开发与部署市场成为软件市场中增长最快的子市场。

IT服务:不可或缺的赋能者。无论是在企业架构优化、系统集成,还是在智能化技术落地等关键环节,IT服务都扮演着至关重要的角色。IDC预测,2029年中国企业级IT服务市场规模将接近750亿美元。

洞察三:云部署模式分化,公有云领跑、私有云稳增

两会提出的“深化拓展人工智能+”行动正深刻影响企业技术路线的选择。IDC《中国IT市场省级及云解决方案支出指南》数据显示,2025-2029年间,三大部署模式的结构性变迁趋势愈发清晰。

公有云:增速领跑,占比突破四成。公有云是三大部署模式中增长最快的板块。IDC预计,2025年公有云支出规模达1018亿美元,占中国企业级IT市场总规模的44.2%;到2029年,这一规模预计将增长至2144亿美元,五年复合增长率高达23.4%。这一增长的核心驱动力首先来自互联网行业的持续投入,2025年其在公有云市场中的贡献占比超过50%;与此同时,传统行业的数字化转型也在加速推进,正在成为公有云市场增长的新动能。

私有云:规模持续扩大,占比稳步提升。私有云是中国企业级IT市场中占比持续提升的部署模式,2025年占比16.8%,到2029年预计提升至18.9%。私有云市场的高速增长,得益于AI工作负载的私有化部署需求激增。此外,数据安全政策的驱动,正推动大型国央企、金融机构等将核心业务系统向云原生架构加速演进。

传统IT:存量巨大,占比逐年收窄。尽管云计算的浪潮席卷各行各业,但传统IT部署模式依然在中国企业级IT市场中占据重要地位。2025年传统IT支出规模达900亿美元,占市场总规模的39.0%;到2029年,这一规模将增长至1193亿美元,但占比下降至29.0%。

洞察四:互联网行业领跑,企业级IT投资结构性分化

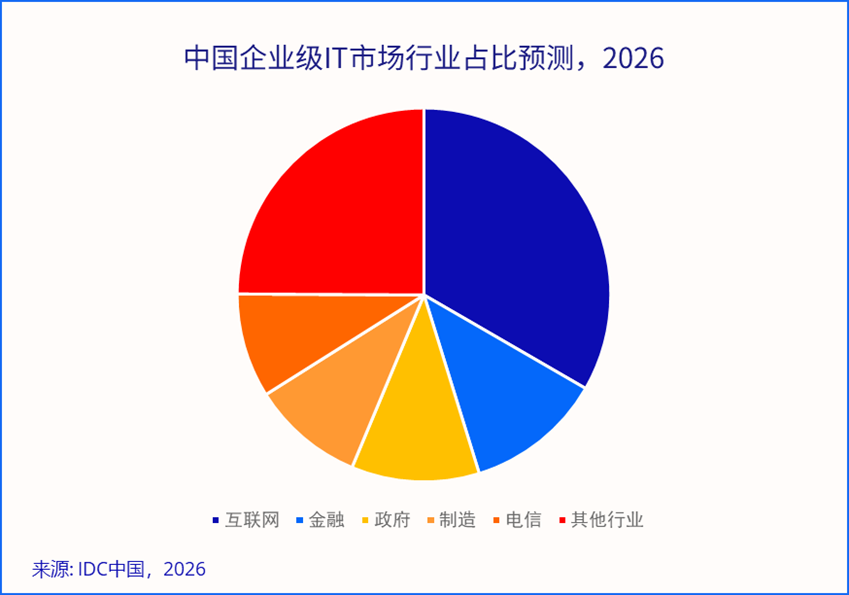
从行业维度看,IDC《中国IT市场省级及云解决方案支出指南》数据显示,互联网、金融、政府、制造、电信等行业的IT投资规模均位居前列。其中,互联网行业占据规模优势,金融与政府行业稳步推进数字化转型,而制造业则在政策强力驱动下,成为增长动能较为突出的领域之一。

互联网:份额领跑,AI驱动高增长。互联网行业依然是中国企业级IT市场投资占比最高的行业,2025年占中国企业级IT市场总规模的33.1%,并以25.2%的五年复合增长率高速增长,在各行业中增速最快。随着生成式人工智能进入商业化落地关键期,互联网企业从模型训练走向应用创新,对GPU服务器、AI加速芯片、高性能存储的需求持续井喷。

金融与政府:科技金融与数字政府双轮驱动。金融与政府行业在市场规模和增长态势上较为接近,2025年企业级IT支出规模分别占中国企业级IT市场总规模的12.3%和11.1%。在“科技金融”和“稳妥推进数字化转型”的导向下,金融机构正积极探索智能客服、风险管理、智能投研等AI在业务端的应用;政府行业则围绕“数字政府”建设,从政务云基础设施向“一网通办”、“一网统管”等创新应用持续延伸。

制造:增速领先,智能制造催生多元需求。两会报告中, “因地制宜发展新质生产力”及“实施新一轮制造业重点产业链高质量发展行动”被置于突出位置。制造业IT支出规模的五年复合增长率达13.3%。IT技术正在渗透到制造业全价值链,包括研发设计端的仿真软件,生产制造端的工业机器人、智能产线,经营管理端的ERP,以及产品服务端的远程运维等。

洞察五:区域与规模分化,超大型企业主导市场

两会报告中明确提出“深入实施区域协调发展战略、区域重大战略”,支持京津冀、长三角、粤港澳大湾区打造世界级城市群。IDC《中国IT市场省级及云解决方案支出指南》的分省数据,为量化评估这一战略下各省的数字经济活力提供了一把标尺。

从区域分布看,中国企业级IT市场呈现明显的梯度格局。中国七大区域中,华北、华东、华南三大区域在2025年的企业级IT投资规模合计占比超过85%,构成市场主力。聚焦省份层面,北京市以2025年33.4%的企业级IT投资占比成为全国企业级IT市场的绝对龙头;上海市在软件、IT服务、人工智能平台等投入上遥遥领先;广东省在电子信息制造业、智能硬件等领域积淀深厚,其中深圳IT支出五年复合增长率达15.2%。

从企业规模看,IDC《全球ICT支出指南:行业与企业规模》数据显示,超大型企业(1000+人)仍然是企业级ICT支出的主要力量,2025年占据超过五成的投资份额。超大型企业在智能算力、云原生平台、大数据平台等前沿领域的投入持续加码,为市场增长注入核心动力。

【IDC分析师观点】

IDC中国分析师张文蕙认为,2026年是“人工智能+”行动全面落地的关键之年。政策持续加码与市场需求释放形成合力,为技术供应商和行业用户创造了广阔空间。AI不再只是技术热点,而是重塑硬件、软件、服务及云部署模式的核心变量。展望未来,市场竞争将不再局限于单一产品的性能比拼,而是上升为算力、平台、生态的综合能力较量。对企业而言,既要把握AI赋能的确定性趋势,也要将AI能力与自身业务场景深度融合,在算力投入与价值实现之间找到平衡点。

IDC中国高级研究经理郭越认为,当前中国ICT市场保持稳健增长、结构升级、智能驱动的整体态势,在政策与产业双轮驱动下,AI 成为核心引擎,推动硬件、软件、服务协同共进,行业热点清晰聚焦。中国ICT市场中软件与信息技术服务业、云计算、智算中心等板块领跑增长,企业数字化与智能化需求旺盛,市场韧性强劲。人工智能从技术探索走向规模化落地,大模型、智能体、端云协同快速普及,带动芯片、服务器、操作系统、数据库、行业解决方案全栈升级,形成 “硬件筑基、软件赋能、服务变现” 的一体化发展格局。

备注:IDC《全球ICT支出指南:行业与企业规模》及《中国IT市场省级及云解决方案支出指南》数据中不包含企业运营技术支出(Operational Technology Spending)数据。

IDC《支出指南》致力于为IT厂商、行业用户和投资/金融机构在战略规划、产品研发、IT支出及投资规划等方面提供数据支撑。《支出指南》系列产品聚焦IT热门领域,从多个维度预测市场规模和增速,助力厂商发掘市场潜力;引导行业用户根据热点技术及应用场景进行IT规划;通过分析特定市场的发展前景,帮助投资和金融机构更好地做出决策。

IDC《支出指南》相关研究:

China Provincial Cloud Solutions Spending Guide

Worldwide ICT Spending Guide Enterprise and SMB by Industry

Worldwide AI and Generative AI Spending Guide

Worldwide Software and Public Cloud Services Spending Guide

Worldwide Security Spending Guide

如需进一步了解与研究相关内容或咨询 IDC其他相关研究,请点击此处与我们联系。

Wendy Zhang - Market Analyst - IDC

Wendy Zhang is a research analyst in the Data and Analytics group at IDC China. She is responsible for business operations and spending guide in China Enterprise Team. She provides dynamic forecasts of future China and global ICT market development. Wendy previously held research positions at ByteDance and Kingsoft Office, where she worked on global payment products and the WPS Cloud Platform, respectively. She conducted research on landscape and competitors of corresponding markets to provide market entry strategies. Prior to that, she was responsible for industry research for TMT companies at Capital Securities, providing stock price prediction and investment advice. Wendy graduated from the University of Wisconsin-Madison with an M.S. in Business Analytics and earned a B.S. in Economics from Beijing Normal University. She is an active leader in programs, including Deloitte data analysis program and entrepreneurship program. She speaks fluent English and Chinese.

AI is no longer an experiment. It is becoming the operating system of the enterprise.

IDC Directions 2026 is designed for leaders who need to move from AI pilots to coordinated, enterprise-wide execution with clarity, confidence, and evidence behind every decision.

On April 8 in Boston, senior technology and business leaders will come together to distill IDC’s global research into the signals that matter most now and pressure-test their strategy directly with the analysts shaping the conversation.

Why IDC Directions Matters Now

In the AI era, competitive advantage will belong to organizations that orchestrate intelligence not just deploy it.

Organizations are navigating converging pressures: economic volatility, regulatory scrutiny, workforce disruption, and the shift from AI experimentation to agentic execution.

The risk is not lack of information. It is misalignment.

When AI initiatives scale without orchestration:

  • Infrastructure fragments
  • Data governance lags
  • Security gaps widen
  • Value becomes difficult to prove

IDC Directions 2026 is structured to eliminate that drift. It brings together macro-level intelligence and practical dialogue so leaders can align architecture, data, governance, and business outcomes before decisions harden.

From Hundreds of Reports to Clear Priorities

IDC publishes hundreds of research reports each year across AI, infrastructure, data, security, services, telecom, devices, industries, and more.

That depth is a strength. But for executives, the question is focus.

  • Which signals require action now?
  • Where should you go deep?
  • What research should guide your next investment decision?

Directions distills that portfolio into one concentrated experience built around strategic decision areas.

The day opens with exclusive keynotes that frame the enterprise challenge:

  • Lorenzo Larini, IDC CEO will outline how IDC is transforming tech intelligence for the AI economy, delivered at AI speed, embedded into workflows, and grounded in research rigor.
  • Meredith Whalen, Chief Product & Research Officer will demonstrate how IDC’s product and platform innovation is translating research vision into applied value.

This sets the context: insights must move at the speed of AI without sacrificing credibility.

What Technologies Will Define Competitive Advantage?

In the morning Lightning Round, IDC analysts provide a curated scan of what is approaching enterprise relevance.

Expect rapid insights on:

  • Agentic AI platforms
  • Quantum computing pathways
  • Robotics and edge intelligence
  • Advanced connectivity and intelligent networks
  • The evolution of consumer engagement in an AI-driven world

This is not speculation. It is research-backed perspective designed to help leaders separate signal from noise.

Four Tracks. Four Strategic Decision Areas.

The afternoon breakout sessions are organized around distinct enterprise priorities so you can go deep where it matters most.

Track 1: AI-Ready Infrastructure

How organizations are modernizing compute, storage, networking, and cloud operations to support agentic workloads at scale. Sessions address ROI tradeoffs, deployment models, silicon strategy, security, observability, and AI-ready data centers.

Track 2: Emerging Tech

How agentic AI, quantum computing, advanced connectivity, robotics, and intelligent devices are reshaping industries and competitive dynamics.

Track 3: Putting Data to Work

How trusted data foundations enable AI value. Explore governance, event-driven architectures, data products, integration, and risk mitigation strategies required for autonomous execution.

Track 4: Marketing & Business Growth Strategies

How AI is transforming marketing from campaign execution to continuous intelligence reshaping discovery, brand relevance, and C-suite alignment.

Each track reflects areas where IDC has produced extensive research and where leaders are facing immediate decisions.

Direct Access to 100+ IDC Analysts

What differentiates IDC Directions is not just the content; it is the dialogue.

More than 100 IDC analysts across AI, infrastructure, security, data, enterprise applications, services, public sector, manufacturing, retail, financial services, telecom, and sustainability will be onsite.

This breadth matters because AI investments are cross-domain decisions.

Attendees can schedule dedicated 1:1 meetings to:

  • Pressure-test investment strategies
  • Validate architectural assumptions
  • Understand peer approaches
  • Identify relevant IDC research for deeper follow-up

In a year defined by agentic orchestration, synthesis across disciplines becomes a competitive advantage.

How Do You Turn AI Investment into Durable Value?

Enterprises turn AI investment into durable value by aligning infrastructure, trusted data, governance, security, and measurable business objectives before scaling initiatives. Architecture and oversight must be designed early — not retrofitted after pilots show promise.

Across the agenda, a central question drives discussion:

How do enterprises move from AI pilots to scalable, governed, value-producing systems?

Leaders are confronting practical challenges:

  • How do we operationalize agentic AI responsibly?
  • What infrastructure is required to support autonomous workflows?
  • How do we measure ROI realistically?
  • How do we maintain governance and compliance at scale?

IDC analysts will provide research-backed guidance grounded in real-world implementation patterns.

The focus is pragmatic: aligning architecture, data, governance, and business impact so AI initiatives do not stall between pilot and production.

A Concentrated Way to Gain Strategic Clarity

IDC Directions 2026 is not a replacement for IDC’s research portfolio. It is a catalyst for using it more effectively.

In one day, you can:

  • Understand macro forces shaping the AI-driven economy
  • Go deep into priority areas aligned to your role
  • Engage directly with leading analysts
  • Identify which research should guide your next decisions
  • Experience the AI Lab and emerging intelligence tools
  • Build peer connections facing similar inflection points

In an AI-fueled economy, clarity is a competitive advantage.

Leaders who align architecture, data, and governance early will scale faster and with fewer costly missteps.

IDC Directions 2026 is built to help you navigate your next move with confidence.

IDC Directions 2026
April 8, 2026 | Boston, MA

Explore the agenda and register at:
https://www.idc.com/events/directions/

Ryan Smith - Content Marketing Director - IDC

Ryan Smith is the Director of Content Marketing at IDC, where he leads brand-level content and social media strategy, aligning research insights with compelling storytelling to engage technology decision-makers. With a background in both IT and marketing, Ryan brings a unique blend of technical understanding and creative strategy to his work. He’s also a seasoned storyteller, speaker, and podcast host who believes the right message, told the right way, can drive both trust and transformation.

Boards are asking tougher questions. Investors are testing AI claims. Growth forecasts are being scrutinized line by line. And volatility is no longer episodic. It is structural.

IDC’s FutureScape Field Manual: CEO / CFO Edition — Navigating the Crosscurrents reframes this reality with clarity. Today’s enterprise leaders are not managing isolated disruption. They are operating inside persistent crosscurrents: economic uncertainty, geopolitical shifts, regulatory acceleration, and the rapid move from experimental to enterprise-scale AI.

This is not a passing cycle. It is a leadership test.

Volatility Now Lives on the Balance Sheet

One of the Field Manual’s most powerful reframes is simple: volatility now lives on the balance sheet.

When AI investments scale faster than governance frameworks, exposure shifts from the innovation lab to financial reporting. When automation assumptions underpin growth forecasts that have not yet been validated, credibility becomes fragile.

In this environment:

  • Growth ambition cannot outpace capital discipline.
  • Innovation strategy cannot detach from governance design.
  • Competitive speed cannot override fiduciary responsibility.

The CEO mandate is to move decisively and signal competitive intent.

The CFO mandate is to ensure that those moves remain explainable, auditable, and defensible under scrutiny.

These are no longer sequential conversations. They are simultaneous commitments.

Growth Ambition Meets Capital Credibility

AI has intensified the collision between ambition and accountability.

Boards expect measurable impact. Markets expect productivity gains without margin erosion. Stakeholders expect transformation with guardrails.

The question is no longer whether to invest in AI.

The question is how to defend those investments under scrutiny.

This is where CEO–CFO alignment becomes strategic, not operational. Growth strategy and financial discipline must be integrated by design. Competitive positioning and exposure modeling must move together.

The Field Manual clarifies the shared questions leaders must now co-own:

  • What volatility are we underwriting versus absorbing?
  • How do we preserve optionality without weakening discipline?
  • Which decisions must remain explainable five quarters from now?

Confidence today is not built on speed alone. It is built on decisions that hold under examination.

Governance Is a Steering Function, Not a Brake

In previous cycles, governance often operated as a checkpoint after execution. That sequence no longer works.

Under persistent volatility and agentic AI, governance must operate at decision speed.

This does not mean heavier process. It means embedded oversight.

As AI systems increasingly influence operational outcomes, accountability concentrates. Leaders are judged not only on results, but on whether those results can be defended.

Governance is not the constraint on transformation. It is the mechanism that makes transformation durable.

Agentic AI Raises the Cost of Being Confident but Wrong

As enterprises embed AI deeper into workflows, the stakes escalate.

Earlier technology missteps could often be isolated or reversed. Agentic systems propagate decisions at scale. Errors compound quickly.

The risk is not moving too fast.

The risk is being confidently wrong at scale.

For CEOs, decisiveness must now include defensibility.

For CFOs, oversight becomes inseparable from enablement. AI-driven revenue projections, cost structures, and compliance posture must withstand board and regulatory review.

Exposure is no longer theoretical. It is immediate.

Financial Leadership as Navigation

Under structural crosscurrents:

  • Capital allocation shapes strategic outcomes in real time.
  • Governance design determines both speed and credibility.
  • AI oversight defines whether innovation strengthens or destabilizes trust.

Financial leadership is not downstream of strategy. It is integral to direction.

IDC’s role as The Navigator is rooted in this reality. Trusted tech intelligence does more than describe market shifts. It illuminates the terrain so leaders can move with confidence.

For CEOs, this means aligning competitive ambition with disciplined execution.

For CFOs, it means reinforcing the financial backbone while enabling innovation responsibly.

The tension is not a liability. Properly integrated, it becomes a capability.

Why This Field Manual Matters Now

This Field Manual does not offer abstract commentary. It surfaces the structural decisions CEOs and CFOs are already making, often implicitly:

  • How much volatility the enterprise will tolerate.
  • What investment discipline means in an AI-embedded organization.
  • Where governance must accelerate momentum and where it must constrain it.
  • How to prepare for board-level scrutiny before it arrives.

These are not theoretical debates. They are active boardroom conversations.

If you are pressure-testing AI investments, rebalancing capital allocation, or preparing for deeper investor scrutiny, this Field Manual provides a structured lens for those decisions.

Because in the crosscurrents, confidence is not certainty.

It is the ability to make bold moves that remain defensible — under pressure, under scrutiny, and over time.

Ryan Smith - Content Marketing Director - IDC

Ryan Smith is the Director of Content Marketing at IDC, where he leads brand-level content and social media strategy, aligning research insights with compelling storytelling to engage technology decision-makers. With a background in both IT and marketing, Ryan brings a unique blend of technical understanding and creative strategy to his work. He’s also a seasoned storyteller, speaker, and podcast host who believes the right message, told the right way, can drive both trust and transformation.

Growth creates momentum, but it also introduces pressure. 

For technology vendors scaling quickly, the decision to enter new markets or move upmarket often arrives earlier than expected. Boards want evidence of expansion. Investors look for signals of long-term opportunity. Leadership teams feel the urgency to act. In that environment, go-to-market decisions carry more weight and less margin for error. 

IDC analyst Roger Beharry Lall sees this moment frequently. In one recent engagement, a high-growth marketing technology company faced a familiar challenge: how to expand from an SMB-focused business into the enterprise market without losing the foundation that made its growth possible. 

The challenge of moving upmarket 

The organization understood that change was necessary. Growth expectations made that clear. The open question was how to evolve its go-to-market approach in a way that translated existing strengths into enterprise relevance. 

This was not a matter of rebuilding the product or abandoning its core market. It was about understanding how current capabilities should be positioned differently, which buyers actually mattered in the enterprise segment, and where the company’s value would resonate most. 

That kind of clarity is difficult to achieve internally, especially when teams are moving quickly and interpreting market signals in different ways. 

Why this moment mattered

For fast-growing vendors, go-to-market shifts are not abstract strategy exercises. They are closely tied to credibility, momentum, and long-term growth narratives. 

Leadership teams are often under pressure to demonstrate progress into new markets through launches, positioning changes, or expanded offerings. That pressure can compress decision timelines and increase the risk of moving forward without a shared understanding of where demand actually exists. 

IDC frequently works with organizations at this stage. Expansion into enterprise or adjacent segments is common, but success depends on identifying the right subsegments, personas, and verticals rather than treating the market as a single opportunity. 

The risk of getting a go-to-market pivot wrong

The most significant risk in a go-to-market pivot is not missing the new opportunity. It is weakening the business that already works. 

Organizations can lose focus on their anchor revenue if new positioning creates confusion or dilutes the value customers already recognize. Growth initiatives that are not grounded in market reality can introduce friction rather than acceleration.

In this engagement, a critical priority was ensuring that enterprise positioning did not undermine existing strengths. The work focused on translating what the company already did well into a new context, rather than redefining the business altogether. 

This balance is often where go-to-market strategies struggle, particularly under time pressure. 

When internal alignment slows progress 

In high-risk go-to-market pivots like this, internal alignment becomes just as important as identifying the right market opportunity. 

Although the decision to move upmarket had been made and early traction existed, progress stalled for a different reason. 

Teams across marketing, product, executive leadership, and the board did not share a consistent understanding of what the enterprise market required. Assumptions varied, priorities differed, and discussions lacked a common reference point.

This situation is common. Without an external source of validation, internal conversations can circle without resolution. The issue is not disagreement about goals, but uncertainty about how to move forward with confidence. 

Shifting from assumptions to validation 

The engagement with IDC evolved as the organization’s needs became clearer. Rather than relying on a predefined approach, the work focused on bringing together existing research, market data, and analyst interpretation. 

What mattered most was not the volume of information, but the ability to contextualize it. Insights drawn from extensive end-user conversations helped clarify what enterprise readiness actually required, where expectations differed from assumptions, and which paths introduced unnecessary risk. 

This shift allowed the organization to move from analysis into decision-making. 

How the organization engaged with insight 

What mattered next was not just the insight itself, but how the organization chose to work with it. 

One of the strongest indicators of progress was how the organization engaged with the insights themselves. 

The teams did not accept findings at face value. They challenged conclusions, asked questions, and worked through implications together. That interaction helped turn data into understanding and understanding into action.

As a result, insights became inputs for leadership discussions rather than static outputs. 

What changed in how decisions were made 

As shared understanding improved, decision-making became more efficient. 

The organization was able to align internally on priorities, refine target segments, adjust messaging, and focus roadmap discussions. Board-level conversations shifted from whether to move forward to how best to do so. 

Confidence came from alignment, not from certainty about outcomes. 

Early signals that mattered 

While it was still early to measure full market impact, initial signals showed that the strategy was taking hold. 

Messaging and positioning were reworked. Channels were reprioritized. Roadmap considerations, particularly around compliance, became more central to planning and communication. These were meaningful changes that reflected a deeper understanding of enterprise buying dynamics. 

They also indicated that the strategy was being operationalized, not just discussed. 

A takeaway for leaders rethinking go-to-market strategy 

For leaders facing similar decisions, the lesson is clear. 

Speed alone does not create momentum. Alignment does. Independent validation helps organizations move forward with shared understanding, reduce internal friction, and make decisions that hold up under pressure. 

When growth depends on getting go-to-market right, assumptions are rarely sufficient. Market truth provides the foundation for confident execution.