当生成式 AI 从“技术试验”走向“业务核心”,企业真正面临的挑战已不再是模型能力,而是如何高效、可控地规模化落地。训推一体化优化,正在成为企业构建竞争壁垒的关键抓手。

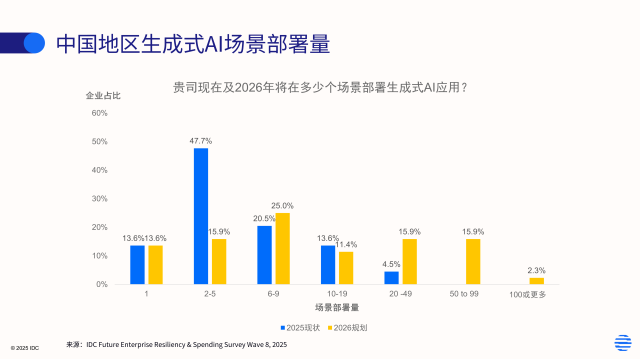
生成式 AI 正在加速向企业核心业务渗透,其价值重心也从“功能创新”转向“效率重构”。IDC研究显示,到2026年,近半数中国企业将部署超过10个生成式 AI 应用场景,这意味着AI已从探索阶段进入规模化应用阶段。在这一过程中,企业逐渐意识到,大模型的真正挑战并不在于“是否拥有”,而在于“是否能够稳定、高效、低成本地运行并持续优化”。
一、生成式 AI 进入规模化落地阶段

从行业演进来看,生成式 AI 正在经历从“点状应用”向“系统性重构”的关键跃迁。早期应用主要集中在内容生成、电商营销等互联网场景,而当前则加速渗透至金融、制造、医疗等核心行业,并逐步深入到采购、销售、财务以及IT运维等企业关键流程之中。这一变化意味着AI不再只是提升局部效率的工具,而正在成为重构企业运营模式的重要基础设施。

与此同时,用户侧的使用习惯也在发生根本性变化。生成式 AI 的使用频率不断提升,越来越多用户已经形成日常依赖,这从侧面推动了企业对AI系统稳定性和响应能力提出更高要求。在此背景下,智能体(Agent)逐渐成为新的应用形态,其“认知—决策—执行”的闭环能力,使AI能够直接参与业务流程,而非仅提供辅助支持。IDC认为,智能体将成为企业数字化转型的核心驱动力之一。

二、Scaling Law 之下的工程复杂性挑战

虽然大模型能力仍然遵循Scaling Law,即通过增加数据规模、模型参数和算力投入来持续提升效果,但在实际落地过程中,这一规律正面临越来越明显的工程约束。随着模型规模扩大,企业不仅需要应对训练成本的指数级增长,还必须解决推理延迟、系统吞吐以及服务稳定性等问题。

更重要的是,系统瓶颈正在发生转移。在早期阶段,算力是主要限制因素,而在当前阶段,跨节点通信、数据传输以及系统调度能力逐渐成为新的瓶颈。特别是在多节点、多GPU环境下,网络带宽和通信效率直接影响整体性能,使得“等数据”而非“等算力”成为常态。

因此,大模型优化已经从单一算法问题,演变为涵盖计算、存储、网络和软件栈的复杂系统工程问题。这一转变也意味着,企业竞争的焦点正在从模型能力本身,转向整体工程能力和架构设计水平。

三、训推一体化成为主流优化路径

在上述背景下,企业逐渐倾向于采用端到端的训推一体化框架,以降低系统复杂度并提升整体效率。这类框架能够贯穿模型生命周期,从数据处理、模型训练到推理部署,实现统一管理与持续优化,从而显著缩短模型迭代周期。

在训练阶段,优化重点已经从“增加算力投入”转向“提升算力利用效率”。通过多维分布式并行策略以及混合精度训练技术,企业可以在有限资源条件下显著提升训练效率,并降低硬件成本。同时,显存优化和通信优化技术的应用,使得大规模模型训练逐渐具备可扩展性和可持续性。

进入后训练阶段,模型优化的重点转向业务适配能力。通过参数高效微调、模型蒸馏以及强化学习等技术,企业能够在控制成本的同时提升模型在特定场景中的表现。尤其是在智能体应用中,强化学习成为提升复杂推理能力的关键手段,但其高计算成本和系统复杂度也对企业提出了更高要求。

在推理部署阶段,优化的核心目标则是实现性能与成本之间的动态平衡。随着模型规模和上下文长度不断增加,推理系统需要同时满足低延迟、高吞吐以及高并发需求。在这一过程中,KV Cache优化、动态批处理以及低精度量化等技术成为关键手段,而PD分离架构(Prefill与Decode分离)及其配套的缓存管理机制,已逐渐成为行业共识。

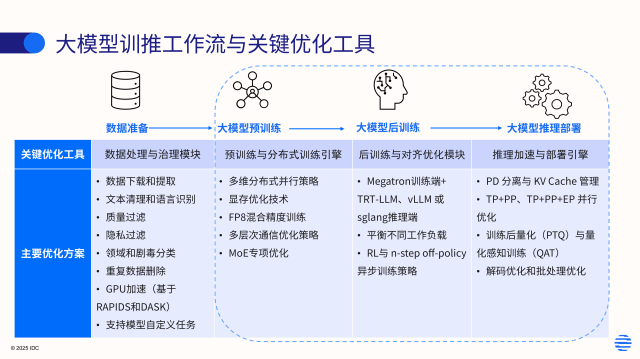
在当前主流的大模型开发框架中,通常会提供覆盖模型训练与推理全流程的多种优化模型与工具。下图展示了在一个典型的大模型应用流程中,这类框架所包含的核心优化工具及其对应的主要优化方案。
四、基础设施成为新一轮竞争焦点

随着大模型应用规模的扩大,底层基础设施的重要性显著提升。IDC数据显示,中国生成式 AI 基础设施市场正处于高速增长阶段,预计未来几年将保持超过60%的年复合增长率。这一趋势表明,企业对算力资源、存储能力以及网络架构的需求正在快速提升。

更深层次来看,AI竞争正在从“模型竞争”转向“基础设施与系统能力竞争”。高性能GPU、低精度计算能力、多级缓存体系以及高速互联网络,正在共同构成新一代AI基础设施的核心。这些能力不仅决定模型训练效率,也直接影响推理成本和服务质量,从而成为企业构建长期竞争优势的重要基础。

五、对技术决策者的关键建议

大模型正在快速迭代和扩展,在训练和推理阶段都面临算力成本和数据质量的挑战。随着模型规模的增长和新技术的涌现,如何在提高训练效果和推理效率的同时,确保模型的稳定性和可控性,是技术提供方需要解决的重要问题。

模型训练阶段:采用多维分布式并行(如数据并行、张量并行、流水线并行)和混合精度训练(BF16/FP16),可大幅提升训练效率,缩短开发周期,降低硬件资源消耗。利用高效的数据管道和动态负载均衡,确保算力利用最大化,减少资源闲置。

后训练(微调/蒸馏)阶段:应用参数高效微调技术(如LoRA、Prefix Tuning)和模型蒸馏,可在保持模型性能的同时显著降低部署成本,提升模型适应性。结合自动化超参搜索和增量训练,提升模型在特定业务场景下的表现。

推理环节:采用低精度量化(FP8/INT4)、内核融合、KV Cache优化和动态批处理等技术,能有效提升推理吞吐量和响应速度,降低显存和算力需求。部署高效的服务架构(如PD分离、异步调度),保障高并发场景下的稳定性和可扩展性。

结论

大模型技术正在快速走向成熟,但真正拉开企业差距的,未来将不仅仅是模型本身,更是围绕训练、后训练与推理的系统化优化能力,这也决定了基础设施是否能输出高质量、有效Token。实践表明,通过构建统一的优化框架并持续迭代技术栈,企业不仅能够加速AI应用落地,还能够显著降低创新成本,提升整体业务价值。

本文IDC相关报告:

  • IDC《大模型训练推理优化部署的最佳实践》

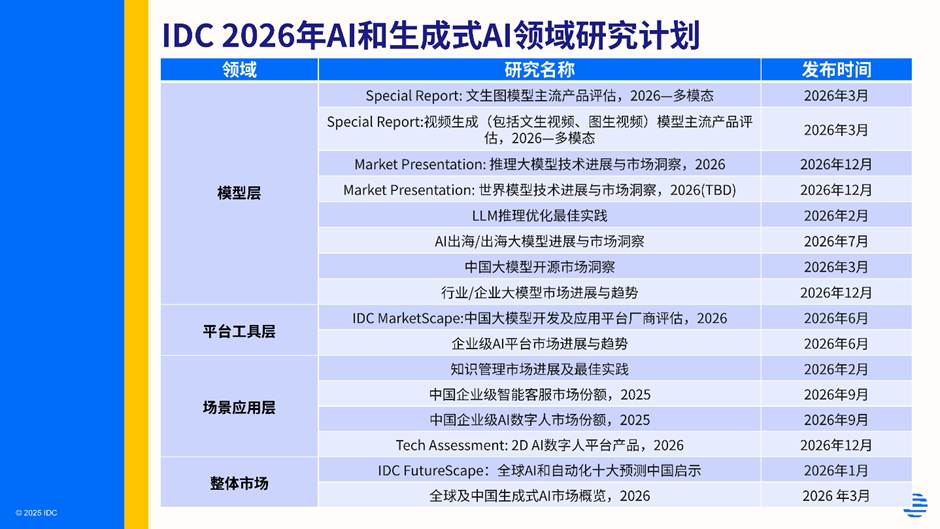
基于上述分析,IDC在大模型、生成式AI以及智能体等领域已形成系统化的研究体系。围绕中国AI与GenAI市场、智能体与自动化应用、以及Data+AI与Data Agent等方向,IDC持续发布涵盖市场规模与预测、技术趋势洞察、厂商竞争格局评估(如MarketScape)、产品与能力评测(Tech Assessment / ProductScape),以及最佳实践与行业案例等多类型研究成果。同时,IDC还可为企业提供定制化咨询服务,包括技术选型与架构规划、市场进入与竞争分析、产品策略与生态评估,以及行业应用落地路径设计等。

请点击此处与我们联系。
随着Sora的退场,全球多模态大模型竞争格局正在发生深刻变化。从“技术标杆”到“商业现实”的转折,不仅意味着AI视频赛道进入理性发展阶段,也对中国厂商提出更高要求。在多模态能力加速突破与产业应用持续深化的背景下,中国大模型正从追赶走向引领,但在算力成本、商业化闭环与合规安全等方面仍面临关键考验。IDC基于最新实测结果,对中国多模态大模型的发展现状、竞争格局与未来趋势进行了系统解析。

Sora落幕并非可以放慢脚步的信号,中国多模态大模型更需加速前行

近日,OpenAI宣布关停旗下视频生成模型Sora,曾被视为AI视频标杆的产品正式退出市场。这一事件引发全球AI行业震动,也让国内多模态大模型领域迎来新的思考:外部标杆退场,并非可以 “躺平” 的理由,反而意味着中国多模态大模型技术必须持续坚持自主创新,在技术、生态与商业化上走出自己的道路。

Sora的关停,源于高昂算力成本、版权合规压力与商业化困境,这也为全球多模态赛道敲响警钟:炫技时代结束,实用、可控、可落地才是核心竞争力。依赖外部模型、简单对标模仿的路径已不可持续,自主创新的技术架构、合规安全的数据体系、高效普惠的产业价值,将成为下一阶段竞争的关键。

面对行业变局,中国多模态大模型已展现强劲势头,从文本、图像到视频、3D、语音的全域融合,正在重构内容生产与产业效率。Sora的离场,清空了浮躁的对标焦虑,却也让全球赛道进入更残酷的“自研淘汰赛”。对中国而言,这既是窗口期,更是压力测试:算力底座、算法创新、数据安全、伦理合规、商业闭环,缺一不可。

2026年3月,国际数据公司(IDC)发布《中国多模态大模型市场主流产品评估》报告,全面评估了国内主流厂商在图像生成、图像理解、视频生成等三大多模态大模型核心领域的技术实力与产品表现。报告显示,中国多模态 AI 产业正迎来高质量发展新阶段,使用多模态大模型构建的应用可以处理和整合多种类型的数据,这些数据更丰富、更能感知上下文,从而大大提高准确性、效率和用户体验。随着技术不断成熟,多模态 AI 也将进一步渗透到个人生活、办公场景,企业级应用场景,推动人机交互方式的革命性变革。

中国多模态大模型迈入加速迭代期:IDC 2026年3月实测结果揭晓

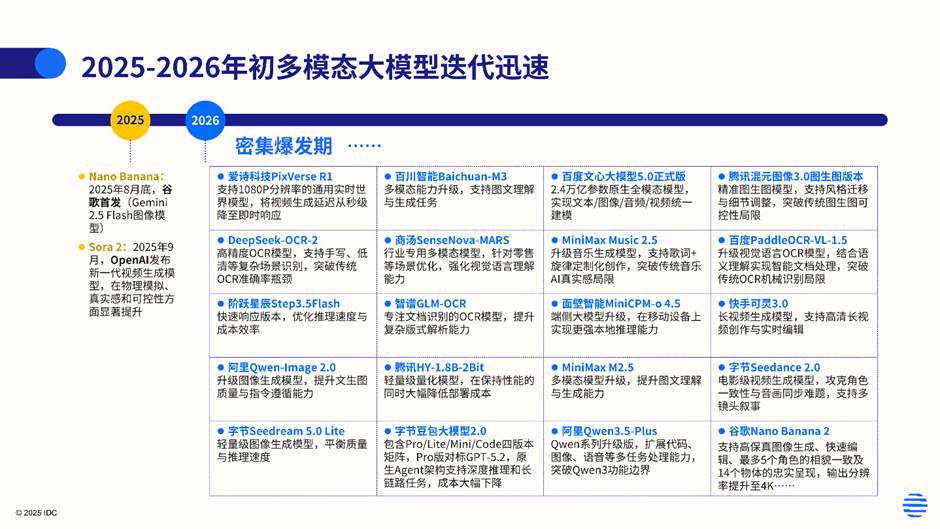
2025年至2026年初,中国多模态大模型领域迎来前所未有的迭代浪潮,新一代模型在文本、图像、音频及视频的理解与生成上实现了质的飞跃。技术供应商竞相发布具备更强逻辑推理与长上下文能力的旗舰产品,使得AI不仅能 “看” 懂复杂图表,也能实时创作高清视频。如字节跳动、阿里、快手、腾讯等旗下产品,在多模态大模型关键指标上持续突破,逐步形成 “技术突破—产业应用—生态反哺”的正向循环。

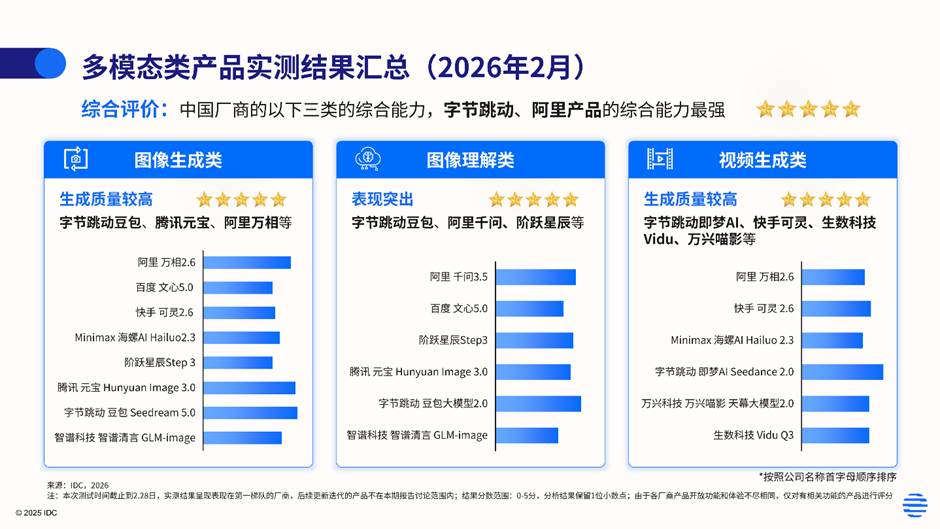
IDC在2026年1-2月对市面上主流的多模态大模型产品进行了实测,本次实测覆盖了国内多家头部技术供应商的代表性产品,测试时间截至 2 月 28 日,对象为公开的网页版产品,实测问题涉及图像生成类、理解类、视频生成类。打分标准主要考察生成/理解内容的质量,从指令遵循与幻觉、逻辑性、鲁棒性、质感及细节、生成时间与稳定性、可用/创新性、 内容安全性/公平与隐私保护等方面综合展开。主要研究结论如下:

图像生成类:字节跳动豆包 Seedream 5.0、腾讯元宝 Hunyuan Image 3.0、阿里万相 2.6 凭借出色的生成质量位居前列。这些产品在语义理解、细节还原、风格多样性等方面表现突出,能够精准匹配用户创作需求,同时在生成效率与画质稳定性、内容安全性上实现平衡。

图像理解类:字节跳动豆包大模型 2.0、阿里千问 3.5、阶跃星辰 Step3 表现最为亮眼。这类产品在复杂场景识别、跨模态推理、细粒度语义解析等核心能力上优势明显,能够高效处理图文混合输入,为多场景应用提供有力支撑。

视频生成类:字节跳动即梦 AI Seedance 2.0、快手可灵2.6、生数科技 Vidu Q3等产品视频生成表现极佳,凭借优质的生成质量与高效的生产效率成为行业标杆,推动国产视频生成技术在短视频创作、影视特效、虚拟数字人等领域的落地应用。

把握多模态技术发展趋势,中国多模态大模型未来仍需审慎推进

IDC 报告指出,未来,随着多模态技术与各行业深度融合,中国厂商有望在全球市场占据更重要的地位,为数字经济发展注入新动能。未来在图像和视频模态,IDC认为重要的技术趋势有:

图像模态:从生成到理解,走向统一与可控——未来更注重生成质量与可控性跃升、理解与推理深度化、架构统一化、轻量化与端侧部署、3D模型生成等方向发展。

视频模态:时序建模突破,走向长视频与实时交互——未来将更注重长上下文与时空一致性、生成质量/成本与效率、视频深度理解与多模态交互、3D 与世界模型融合等方向发展,更好地服务于个人生活以及影视娱乐、游戏、媒体、教育等行业应用。

中国多模态大模型市场头部厂商当前商业化路线以 ‌B端+C端全面展开‌,一方面通过借助C端流量与生态基础,另一方面聚焦于将多模态AI能力深度嵌入企业工作流,打造“模型即服务”(MaaS)与针对在媒体、短视频创作、影视特效、虚拟数字人、电商、文旅等行业定制化解决方案。有一部分具有生态优势的国内头部厂商已形成内容-流量-变现的商业闭环,用户使用量与付费转化率均领先海外同行。但多模态大模型技术供应商仍需持续监控未来转化与留存指标,部分中国市场C端产品定价并不普惠。

另外,B端场景的全面渗透也仍需时间。Sora近期关停也给中国多模态大模型技术供应商带来启示,仍需警惕以下风险:

内容安全与深度伪造风险:超逼真图像、视频易被用于虚假信息传播、金融诈骗、人格侵权,对社会信任与公共安全构成威胁。

监管政策、版权与法律合规风险:训练数据多来自未授权的图片、影视、短视频素材,生成内容版权归属模糊,易引发诉讼与监管处罚。全球各国对AI生成内容的监管趋严,可能限制真人素材生成、内容传播等核心功能,影响产业扩张。

技术与算力成本风险:多模态大模型的算力成本,是文本大模型的数十倍甚至上百倍,以致训练与推理算力成本高昂,中小厂商难以负担;同时存在算法偏见、模型幻觉等技术缺陷。

商业化可持续性风险:C端用户付费意愿、转化与留存需要密切监测,B端场景渗透仍需时间,警惕内容同质化与可持续性发展风险。

IDC中国研究经理程荫表示,本次实测结果反映出中国多模态 AI 产业已从技术追赶转向创新引领阶段。头部厂商在技术迭代与产品落地方面持续发力,不仅在基础能力上实现突破,更在商业化场景探索中取得进展。技术竞争没有终点,标杆退出不代表终点线前移。中国多模态大模型仍需深耕技术底座、贴近产业需求、筑牢安全底线,才能在全球AI格局中占据主动,真正实现从跟跑到并跑、再到领跑的跨越。

IDC长期深耕人工智能与生成式AI领域,围绕技术演进、竞争格局与商业落地构建了系统化研究体系。基于持续的一手实测与行业跟踪,IDC不仅提供权威数据与趋势判断,更可为技术供应商、行业用户及投资机构输出面向实际决策的策略建议,助力识别关键技术路径与商业化机会。

在多模态大模型加速演进的关键阶段,欢迎与我们联系,获取完整研究成果、报告解读及定制化咨询服务,抢占下一轮AI发展先机。请点击此处与我们联系。

Anne Cheng - Research Manager - IDC

Anne Cheng is a research manager in IDC China whose research focuses on the AI and big data markets. She collaborates with IDC's regional and global consulting teams and is involved in the business development of related markets. Prior to joining IDC, Anne had nearly four years of working experience in the IT/ecommerce and consulting industries, serving as consultant and business analyst. Her experiences made her familiar with industry data/customers and helped her gain deep insights into the business application scenarios. Anne holds a master's degree in Statistics from the University of Missouri Columbia.

Cyber risk is no longer just a technical issue, it is a core business concern discussed at the highest levels of the organization. Across EMEA, boards are demanding clearer visibility into risk exposure, regulatory impact, and resilience. This blog explores the latest IDC insights on how CISOs can translate cyber risk into business language, align with board expectations, and strengthen decision-making in an increasingly complex threat and regulatory landscape.

How cyber risk became a board-level business risk

IDC research confirms that cyber risk has become a top board-level concern across EMEA and globally. Boards increasingly recognize that cyber risk is synonymous with business risk, prompting them to ask CISOs to translate the risk of cyber compromise into tangible business and compliance impacts.

As highlighted in IDC’s perspectives, board members are no longer satisfied with technical metrics alone they want to understand how cyber threats could affect organizational resilience, regulatory standing, and overall business continuity.

Cyber risk appetite vs. security investment: Key EMEA trends

Cybersecurity remains the primary barrier to CIO success in Europe, with 16–18% of organizations identifying it as their top challenge. Despite ongoing economic volatility, security budgets are generally protected, though not immune to cuts. IDC’s EMEA Security Tech and Strategies Survey reveals that 33% of financial services organizations kept their security budgets flat, 29% increased them by less than 10%, and 14% decreased them by more than 10%.

Boards are demanding greater clarity on risk acceptance, transfer, and mitigation strategies. A common pitfall is treating security metrics as mere program performance indicators rather than as expressions of risk and compliance management. Boards are now asking, “What is the risk cyber presents to the organization, and how well are we positioned to address it?”

CISO best practices for communicating cyber risk to the board

IDC recommends that CISOs translate cyber risk into financial terms, expressing exposure as realistic cost-of-breach scenarios rather than relying solely on severity labels. Structured exercises should identify which risks threaten financial stability and which are critical for certification or compliance. At the board level, metrics should focus on governance, risk, and compliance trends, answering questions such as: “What are our minimal viable operations? Are we cyber crisis ready? How resilient are we? How long will our business, systems, and production be offline in the event of a severe cyber compromise?”

A robust risk management framework can address 70% of board questions by identifying mission-essential assets, evaluating threats, monitoring controls, and clarifying risk ownership. While boards seek benchmarks and industry comparisons, they are cautioned against adopting a “do $1 more than our competitor” mentality.

IDC advocates for quarterly red teaming and realistic tabletop exercises to educate boards and executives, clarify escalation policies, and better identity and assess third party risk. Boards are also increasingly interested in the impact of AI and emerging technologies such as quantum key encryption and Model Context Protocol (MCP) deployment on organizational risk posture. CISOs should review use cases, implement human-in-the-loop controls, assess data security, and continuously audit AI assets.

Cyber risk and regulation in EMEA: Key insights for CISOs

Regulatory pressure is intensifying in Europe, with frameworks like NIS2, DORA, and the EU AI Act resulting in governance, risk, and compliance (GRC) as the top security technology priority for large organizations. Over 40% of these organizations now place GRC at the forefront, with liability for infringements increasingly assigned to senior management.
In European financial services, cyber security for clients (59%) and internal cyber security (57%) are the primary drivers of risk management investment. But only 43% of CISOs in large UK enterprises report having monthly board engagement, while 48% engage on an ad-hoc basis. IDC recommends establishing regular, structured communication to align risk appetite and investment decisions.

Practical steps to improve cyber risk management and board engagement

To enhance board engagement and risk management, IDC advises quantifying risk in business terms using financial impact, loss scenarios, and regulatory exposure. Cyber risk management should be continuous, using process automation where possible.
Boards must align security investment with risk appetite, and balance resilience, compliance, and operational priorities. Regular, meaningful engagement beyond ad-hoc updates is essential, as is benchmarking against peers while avoiding herd mentality. Integrating GRC platforms to automate reporting, audit, and compliance can support board-level visibility and informed decision-making.

Key takeaways for CISOs and boards in 2026

IDC’s EMEA and worldwide research underscores that effective cyber risk assessment and CISO-board communication require translating technical risk into business impact, quantifying risk appetite, and aligning security investment with strategic objectives.
Boards seek clarity, context, and actionable insights not operational minutiae. CISOs must become influential partners, guiding risk acceptance, transfer, and mitigation in a language the board understands. As regulatory and threat landscapes evolve, disciplined, data-driven communication is essential for resilient, compliant, and secure organizations.

Join the conversation: Deep dive in our upcoming webinar

Want to go beyond the headlines and understand what these shifts mean for your organization? Join our upcoming IDC webinar on May 12 to hear directly from our analysts as they break down the latest EMEA cybersecurity trends, evolving board expectations, and what it takes to translate cyber risk into business impact. Gain practical insights, benchmark your approach, and learn how leading organizations are aligning security strategy with business priorities.

Joel Stradling - Senior Research Director, European Security - IDC

As senior research director for IDC's European Security practice, Joel Stradling leads the content and analyst team for tracking the European security segment. His main focus areas include Zero Trust Network Architecture, Managed Security Services, and Cyber Risk and Resiliency. Stradling has 22 years of experience as an analyst of cyber security, and international managed enterprise network and IT services. He is a regular speaker at major industry conferences talking about security and privacy, Digital Trust and Managed Security Services in B2B enterprise services. Joel is a well-known and highly regarded expert in the industry, offering insight and advice to C-level executives on security technology competitive landscapes and evolving security market segments including: managed security services ZTNA, cloud security, risk and compliance, end point, identity and access management, IT/OT security, secure IoT and 5G, and secure operations.

David Clemente - Research Director, European Security - IDC

Dave Clemente is a Research Director in IDC's European Security practice, with a focus on security services (including managed services and professional services). He is a research professional with more than fifteen years of experience in cyber security, including in think tanks (Chatham House and the International Institute for Strategic Studies), professional services (PwC and Deloitte), and market analysis. Dave is a regular conference speaker and media contributor, and has authored numerous publications on topics including C-suite technology and security priorities, security policy and governance, risk management, and data protection.

What is really shaping IT investment across EMEA in 2026? 

Across EMEA, IT spending continues to grow, but the forces shaping that growth are becoming more complex. Geopolitical tensions, regulatory developments and economic uncertainty are increasing the pressure on organisations to prioritise resilience and operational stability, even as executive expectations around artificial intelligence continue to rise. Many enterprises are now moving beyond experimentation and beginning to explore how AI can be operationalised at scale. The question for 2026 is not simply whether AI investment will continue, but how organisations balance innovation ambitions with resilience priorities in a rapidly evolving market environment. 

Growth remains stable but increasingly concentrated 

IT spending across EMEA is expected to grow by 7% in 2026, driven primarily by the continued double‑digit expansion of the software market. While 2025 was marked by a surge in the Service Provider segment, 2026 shows a more balanced outlook, with both Enterprise and Service Provider spending following similar growth trajectories. The only exception is the Consumer market, which remains flat (Source: IDC Worldwide Black Book, March 2026). 

Geopolitical tensions, supply chain disruptions and an increasingly complex regulatory landscape continue to reshape investment priorities across EMEA. As explored in our recent analysis of how ongoing conflicts are stress-testing the digital economy, organisations are placing greater emphasis on resilience, operational continuity and regional autonomy in their technology strategies. IT spending is therefore not slowing, but becoming more deliberate and selective, with investment increasingly directed toward capabilities that strengthen stability and long-term adaptability in an uncertain global environment. 

Executive expectations are raising the bar 

At the same time, executive ambition around AI continues to intensify. IDC research indicates that 50 percent of CEOs believe AI will offer their organisation the opportunity to reinvent its business model within the next three to five years. 

This signals a shift in how AI is positioned within enterprise strategy. AI is no longer viewed primarily as a tool for experimentation or incremental efficiency gains. Instead, it is increasingly expected to deliver tangible transformation, automation and competitive differentiation. 

However, survey data also shows that some organisations are reassessing elements of their AI programmes. Concerns around return on investment, governance, data readiness and skills availability are influencing decision-making across the region. The result is a more demanding environment in which expectations are rising but scrutiny is increasing as well. 

From experimentation to operational AI 

Across EMEA, AI maturity is evolving. The early phase of generative AI experimentation is giving way to a stronger focus on operational deployment. 

Organisations are now moving beyond isolated pilots towards integrating AI capabilities into core workflows, enterprise applications and decision-making processes. This transition reflects a broader shift towards operational AI and the emergence of more agentic enterprise models. 

At the same time, scaling AI requires far more than access to models. Infrastructure readiness, data management capabilities, governance frameworks and organisational skills are becoming decisive factors in determining whether organisations can move from experimentation to sustained operational impact. 

Resilience, governance and execution will define the next phase 

The evolving EMEA technology landscape is therefore shaped by a combination of innovation pressure and structural constraints. Geopolitical uncertainty, regulatory requirements and resilience priorities are increasingly influencing technology investment decisions. 

For technology providers operating in the region, understanding these dynamics is critical. Growth opportunities remain significant, but they are tied more closely to execution readiness, operational maturity and the ability to support organisations as they scale AI responsibly. 

Join the conversation

In our upcoming webcast on April 28, IDC analysts Andrea Siviero, Stephen Minton, and team will explore what these shifts mean for the EMEA IT market in 2026, including: 

  • How geopolitical developments and resilience priorities are influencing IT investment across the region 
  • Where growth is concentrated across EMEA markets and industries 
  • How organisations are moving from AI experimentation to operational deployment 
  • What the rise of more agentic enterprise models means for enterprise technology environments 

Register for the webcast here.

Got a question? Drop it in here.

Andrea Siviero - Senior Research Director, MacroTech, Digital Business, and Future of Work - IDC

Andrea Siviero leads IDC's European Digital Business and Future of Work Research group. The group provides market research insights to foster a purposeful and fair adoption of technologies supporting digital societies, businesses and workforce and empower tech providers in strategic decision making, planning and go-to-market activities. Siviero also co-leads the IDC Worldwide MacroTech Research program, focused on the intertwined connection between the Economical and Digital worlds - analyzing the impact key MacroEconomic factors have on the digital landscape and viceversa, how technologies are impacting economies around the world.

The market leadership imperative in the agentic economy

In the agentic economy, where autonomous AI systems increasingly act on behalf of the business, market leadership depends on an organization’s ability to orchestrate AI-driven decisions, workflows, and governance at scale. As autonomous agents increasingly shape how work gets done, leaders must shift from controlling systems to navigating interconnected, AI-enabled operations with confidence, trust, and strategic clarity.

This is the central message of IDC’s FutureScape Field Manual: C-suite Edition — The Market Leadership Imperative: Creating Advantage in the Agentic Economy. Rather than focusing on AI as a standalone capability, the ebook examines how agentic systems are reshaping decision-making, operating models, and leadership responsibility across the enterprise.

From control to navigation

For decades, leadership in technology-driven organizations was rooted in control: standardizing systems, optimizing processes, and reducing variability. In the agentic economy, that model no longer holds. AI agents introduce autonomy, interdependence, and speed at a scale that challenges traditional command-and-control approaches.

IDC frames this shift as a move from control to navigation. Leaders are no longer steering isolated systems; they are guiding dynamic networks of human and machine decision-makers. Success depends on understanding how these systems interact, where governance must evolve, and how trust is established when decisions are increasingly made by software acting on behalf of the business.

The implication is sobering: leaders can have the right strategy and still drift if they fail to account for these forces. The field manual positions leadership not as command and control, but as navigation, continuously adjusting course with insight, governance, and alignment across the C-suite.

The crosscurrents reshaping enterprise strategy

A core section of the ebook examines the major forces converging around agentic AI. Rather than treating them as separate issues, the analysis shows how they reinforce one another.

Economic volatility is forcing tighter capital discipline just as AI investments accelerate. Geopolitical realignment and digital sovereignty are reshaping where data, models, and infrastructure can live. Regulatory pressure is increasing faster than many organizations’ readiness. At the same time, the workforce is being redefined as human–AI collaboration replaces task-based automation.

The takeaway is clear: in the agentic economy, technology strategy now intersects directly with geopolitical strategy, talent strategy, and trust strategy. Leaders who address these dimensions in isolation risk fragmented adoption and rising complexity.

Four pillars of the agentic future

To help executives make sense of this environment, the field manual introduces four leadership pillars that serve as a shared compass for decision-making.

The first focuses on navigating disruption itself, recognizing that volatility is now structural, not episodic. The second addresses the shift from AI pilots to enterprise-wide orchestration, in which agents operate across systems rather than within silos. The third centers on trust, resilience, and transparency, positioning governance not as a constraint but as a source of confidence and differentiation. The fourth looks beyond productivity, exploring how agentic AI unlocks new forms of innovation, growth, and value creation.

Each pillar is framed with IDC research, executive-level implications, and reflective questions designed to spark discussion across leadership teams.

Trust as an operating discipline

One of the most distinctive elements of the ebook is its treatment of trust. Instead of positioning trust as an abstract value, the field manual treats it as an operational capability.

It introduces the idea that transparency, explainability, accountability, and governance must be embedded into daily operations as AI becomes more autonomous. Trust becomes measurable, visible, and actionable — not just a compliance requirement, but a leadership behavior that directly affects resilience, innovation, and stakeholder confidence.

A shared language for the C-suite

What sets this field manual apart is its intent. It is not written for one role or function. It is designed to create a shared language between CEOs, CIOs, CFOs, CMOs, COOs, and CHROs at a moment when decisions about AI can no longer be delegated or deferred.

The ebook connects near-term realities with longer-term consequences, helping leaders understand not only what is changing, but what they need to be discussing next. It invites dialogue rather than prescribing answers, a deliberate choice in an era where certainty is rare, but informed navigation is essential.

Why this matters now

The agentic economy is already taking shape. Organizations that move deliberately, align strategy with governance, and treat AI as a leadership issue will be positioned to turn disruption into advantage.

This field manual offers a clear-eyed view of that challenge, and a structured way for leaders to begin navigating it together.

For those ready to move from insight to impact, the full eBook provides the depth, context, and questions needed to chart a confident path forward.

Ryan Smith - Content Marketing Director - IDC

Ryan Smith is the Director of Content Marketing at IDC, where he leads brand-level content and social media strategy, aligning research insights with compelling storytelling to engage technology decision-makers. With a background in both IT and marketing, Ryan brings a unique blend of technical understanding and creative strategy to his work. He’s also a seasoned storyteller, speaker, and podcast host who believes the right message, told the right way, can drive both trust and transformation.

Work in 2026 is being rewired around human-AI teams, where people who learn to collaborate with intelligent systems are gaining a clear edge in productivity, creativity, and career growth. IDC’s latest FutureScape and Future of Work insights show that this is no longer a distant trend but the operating reality for leading organisations worldwide.

The new shape of work

According our 2026 Futurescape for the AI-enabled Future of Work around 40% of roles in the G2000 will involve direct engagement with AI agents by 2026, fundamentally reshaping how entry, mid-level, and senior jobs are designed. In Europe specifically, we expect around 70% of new positions to be directly influenced by AI, blending technical fluency with human-centred capabilities like problem solving, empathy, and domain expertise.

AI is simultaneously and subtly absorbing much of the background work. Our analysis suggests AI tools can save workers over 40% of their typical workday, with IT workers gaining up to 45% of their time back as routine tasks are automated. Instead of spending hours on status reports, basic analysis, or rote documentation, employees can focus more on designing solutions, making decisions, and collaborating with customers and colleagues.

Agents as instruments, not co-workers

One of our most important messages though is that AI agents should be treated as instruments that extend human capability, not as synthetic co-workers to be managed like people. When AI is framed as a powerful tool in a human-led process, organisations are less likely to over-automate and more likely to invest in skills, governance, and thoughtful workflow redesign.

This mindset shift is already visible in how leaders talk about AI “co-pilots” across development, operations, and knowledge work. We predict  that as agentic AI matures, organisations that focus on measuring and improving AI–human collaboration, rather than just raw productivity, will see margin gains of up to 15% by the end of the decade.

The skills crunch: $5.5 trillion on the line

The biggest drag on this transformation is no longer the technology but the skills to use it well. Our data shows that over 90% of global enterprises will face critical skills shortages by 2026, with AI-related gaps alone putting up to $5.5 trillion of economic value at risk through delays, missed revenue, and quality issues. Yet in our Global Future of Work Decision Maker only about a third of organisations say they are fully ready for AI-driven ways of working, and just a similar share of employees report receiving any AI training in the past year.

This imbalance is already reshaping labour markets. The 2025 IDC Employee Experience survey shows that that 66% of enterprises are reducing entry-level hiring as they deploy AI, and 91% report roles being changed or partially automated. Routine-heavy junior tasks are disappearing fastest, while demand grows for roles that can design, supervise, and continuously improve AI-infused workflows.

How to ride, not resist, the wave

For leaders and professionals, the 2026 question is not “Will AI take my job?” but “How quickly can my organisation and my skills adapt to human–AI collaboration?”. Our research into AI, automation, and Future of Work points to a few practical priorities that separate frontrunners from the rest.

  • Build AI literacy for everyone, not just specialists: core skills now include prompt design, interpreting AI output, and knowing when to override or escalate decisions.
  • Redesign roles around human strengths: shift job descriptions toward judgment, creativity, relationship-building, and cross-domain problem solving, with AI handling repeatable analysis and orchestration.
  • Invest in trustworthy data and governance: companies that neglect high-quality, AI-ready data will see productivity fall behind as they struggle to scale agentic solutions.
  • Measure collaboration, not just output: by 2029, organisations that track and optimise human–AI collaboration are projected to enjoy up to 15% higher margins than those that chase automation alone.

Work has been rewired, but the most valuable node in the system is still the human at the centre of an intelligent network of tools, agents, and collaborators. In 2026, the winners will be those who treat AI not as a threat or a crutch, but as a force multiplier for distinctly human ambition.

To watch our EMEA FutureScape predictions presentation, click here.

If you have any questions, please drop them in this form.

Meike Escherich - Associate Research Director, European Future of Work - IDC

Meike Escherich is an associate research director with IDC's European Future of Work practice, based in the UK. In this role, she provides coverage of key technology trends across the Future of Work, specializing in how to enable and foster teamwork in a flexible work environment. Her research looks at how technologies influence workers' skills and behaviors, organizational culture, worker experience and how the workspace itself is enabling the future enterprise.

After 38 years with IDC, I have decided that it’s the right time to step into the next chapter of my career. Beginning in January, I will transition out of my current role into supporting the company as a Special Advisor, where I will continue to champion IDC and the critical role we play in guiding the technology community forward. 

When I joined IDC as an associate research analyst, I could not have predicted the opportunities and experiences that would follow. I was drawn to IDC because of its unique vantage point on the technology industry, and I stayed because of two things: the constantly changing nature of technology and its impact on the world, and the opportunity to learn from some of the smartest people in the industry—across IDC, our customers, and the broader market. 

Throughout my career, I’ve had the privilege of working with exceptional colleagues and leaders who shaped IDC’s global research and data offerings. Together, we created, honed, and strengthened IDC’s position as the trusted source for technology intelligence used by organizations around the world. 

What’s next 

During my time here, IDC has evolved through multiple technology cycles—from client/server, to mobility and cloud, and now AI. With strong leadership, a talented global team, and a clear vision for what trusted tech intelligence looks like in the AI era, IDC is stronger than ever. 

To my colleagues: thank you for your dedication, your partnership, and the professionalism that defines IDC. 

And to our customers and partners: thank you for trusting us with your most important decisions and challenging us to continuously raise the bar. 

IDC’s future is bright and I am excited to support it.  
 

Crawford 

Crawford Del Prete - President - IDC

Crawford Del Prete was appointed President of IDC in February 2019. Prior to his current role, he served as IDC's Chief Operating Officer. Through his leadership, IDC has established a leading position as the world's most prominent and trusted technology market intelligence provider. Crawford joined IDC in 1989 as a research analyst. Throughout his IDC career, he has grown multiple IDC businesses to industry leadership positions. He was instrumental in creating IDC's high visibility research and data tracking products which are used daily in the IT industry for strategic planning. Crawford is a leading authority on the IT industry and has completed extensive research on the structure and evolution of the information technology industry. He advises technology and business leaders on how to adapt and change in a time when technology is changing the world. He is frequently quoted in publications such as The Wall Street Journal, The Financial Times, The New York Times and other leading media sources. He is a regular guest on Bloomberg Technology TV, offering insight and perspective on daily technology events. He was awarded The Patrick J. McGovern Award for Management Excellence in 2014. In 1995, he was awarded IDC's James Peacock Award for research excellence, IDC's highest research honor. He holds a B.A. from Michigan State University and in 2012, he was named a Distinguished Alumni of the University. Follow Crawford on Twitter @craw.

As the IDC Government Insights team developed this year’s IDC FutureScape: Worldwide Smart Cities and Communities 2026 Predictions, one trend became clear: cities of all sizes are rapidly adopting LLM-driven AI tools. As cities confront tighter budgets, rising public needs, and the accelerating pace of AI adoption, two predictions stand out: One prediction on Agentic AI and workflow orchestration, and the other on unlocking the value of government data through fine-tuned large language models (LLMs).

Together, these prediction signal a shift from technology-as-a-tool to technology-as-a-teammate (or as “a personal intern”)— where intelligent systems collaborate with humans to simplify complexity, bridge data silos, and elevate service delivery. For mayors, CIOs, and innovation officers, this is more than automation, it’s a reimagining of how government works.

Agentic AI Connects the Dots Across City Systems

By 2027, 65% of cities will deploy AI agents across systems and data to orchestrate end-to-end workflows and reduce workloads while addressing risks of misuse and overreach and “process debt.”

Local governments have long wrestled with what IDC has termed “process debt” — the accumulated workflow inefficiency of fragmented systems, redundant data entry, and manual workarounds. Agentic AI changes that equation. Unlike traditional AI models built for narrow tasks, AI agents can understand goals, coordinate across systems, and execute full workflows — from processing applications to reconciling budgets to automating permit approvals.

But this evolution demands groundwork. Before AI agents can drive real impact, state and local governments must map workflows, clean data, and redesign processes that currently constrain efficiency. As we often discuss, automating broken processes “rarely delivers better outcomes.” Instead, success depends on combining automation with human oversight, workforce readiness, and transparent governance.

Human + Machine Collaboration

Agentic AI will shift how public sector teams work — not by replacing people in the near-term, but by augmenting their capacity. Entry-level clerical roles may evolve, but new opportunities will emerge for “AI process managers,” ethics officers, and cross-agency data specialists. IDC emphasizes that HR must be a strategic partner in this transformation, guiding reskilling and maintaining morale during rapid change.

The payoff? Smarter workflows, faster decisions, and lower service delivery costs. When AI agents manage the repetitive, city staff can focus on what humans do best — strategic decisions, innovation and empathetic human interactions.

Unlocking the Hidden Value of Government Data

By 2026, 50% of state and local governments will invest in fine-tuning LLMs on data the models have never seen, unlocking value from decades of protected records and siloed systems.

Every city sits on a goldmine of data — from zoning and traffic to health, housing, and economic development. Yet much of it is trapped in systems that don’t talk to each other; not only that, this data is private and has not been used to train the LLMs that are serving up GenAI results.

The next wave of Smart City innovation will come from fine-tuning LLMs on this untapped data. Cities will begin training models on internal records — with strict governance — to capture local context and institutional knowledge. The result: AI systems that “speak government”, understand regulatory nuances, and generate insights and recommendations grounded in real municipal operations. This provides faster insights for planning decisions and actions that support mission outcomes.

From Locked Archives to Living Intelligence

Imagine an AI system trained on decades of urban planning documents, council minutes, and building permits. It could summarize past precedents for new zoning requests, detect policy inconsistencies, or surface patterns in infrastructure maintenance failures. Or consider a model fine-tuned on social services data — capable of predicting which households may need early intervention to prevent homelessness.

These capabilities hinge on one foundation: responsible data governance. IDC advises governments to invest in “AI-ready data” — standardizing formats, labeling metadata, and implementing data governance technologies to ensure security and trust. As models become more specialized, leaders must also modernize infrastructure, upgrading government clouds and integrating intelligent computing power to support large-scale inferencing.

Bringing It Together: The Convergence of Agentic AI and Data Intelligence

The two predictions are two sides of the same coin. Agentic AI depends on data liquidity; data intelligence depends on intelligent orchestration. Together, they form the digital nervous system of the future city.

As IDC’s broader FutureScape 2026 report underscores, the Smart City of the near future is not just connected — it’s context-aware. AI agents will move seamlessly across departments, drawing on fine-tuned LLMs to provide decisions informed by a city’s own history and conditions.

The FutureScape highlights key trends:

  • Agentic AI is the next leap in digital government, transforming automation into orchestration across workflows.
  • Fine-tuned government LLMs will unlock decades of hidden data, fueling more contextual and accurate decision-making.
  • Responsible governance is the foundation — without ethical frameworks, AI progress can erode rather than build trust.
  • The future is collaborative: Humans define intent and context; AI executes and optimizes — together delivering public value faster and smarter.

Guidance for City Leaders

Smart City success depends not just on adopting AI, but on designing for agility, responsibility, and inclusion. Based on Predictions 1 and 6, here are three critical actions:

  1. Modernize the Data Core
    Build secure, interoperable data platforms that connect siloed systems. Invest in metadata management, data lineage, and ethical AI governance frameworks that prepare your data for fine-tuning and automation.
  2. Pilot Agentic Workflows in High-Impact Areas
    Start small but strategic — automate processes where the value is measurable (e.g., licensing, fleet maintenance, or procurement). Use sandboxed environments to test AI agents safely before scaling.
  3. Center People in the Process
    Partner with HR to redefine job roles and develop AI literacy. Transparent communication and change management are essential to maintain public trust and employee confidence.
  4. Design for Accountability and Transparency
    Incorporate audit trails, explainable AI, and citizen feedback loops. The legitimacy of AI-driven decisions will determine long-term success more than the sophistication of the technology.

The FutureScape 2026 predictions make one thing clear —when agentic AI and data governance converge, cities can be better proactive orchestrators of well-being, equity, and sustainability.

Cities like Boston, Singapore, and Barcelona are already using AI-powered urban planning platforms to integrate policy, climate, and citizen feedback — showing how government-specific data can supercharge innovation responsibly. These early movers demonstrate what’s possible when leaders treat AI not as a black box but as a civic partner.

As Smart City leaders plan their 2026 strategies, now is the time to evaluate your readiness for agentic AI and data-driven transformation.

If your city is already advancing innovative, AI-enabled initiatives, consider submitting your project for the IDC 2026 Smart Cities and Communities North America Awards, now open for nominations.

Ruthbea Yesner - Program VP - IDC

Ruthbea Yesner is the Vice President of Government Insights at IDC. In this practice, Ms. Yesner manages the US Federal Government, Education, and the Worldwide Smart Cities and Communities Global practices. Ms. Yesner's research discusses the strategies and execution of relevant technologies and best practice areas, such as governance, innovation, partnerships and business models, essential for government and education transformation. Ms. Yesner's research includes analytics, artificial intelligence, Open data and data exchanges, digital twins, artificial intelligence, the Internet of Things, cloud computing, and mobile solutions in the areas of economic development and civic engagement, urban planning and administration, smart campus, transportation, and energy and infrastructure. Ms. Yesner contributes to consulting engagements to support K-12 and higher education institutions, state and local governments and IT vendors' overall Smart City market strategies.

AI will continue to shape the enterprise communications landscape in 2026, with organisations seeking practical value while navigating cost, governance, and deployment constraints. Interest in AI is high, but companies still face gaps around affordability, readiness, and real-world use cases. As a result, the market will progress through grounded, incremental steps, supported by stronger data foundations, evolving pricing models, and greater collaboration across ecosystems and service partners.

1. AI Adoption Will Remain Pragmatic and Focused on Clear ROI

AI will continue to gain momentum, but organisations will prioritise capabilities that deliver immediate, measurable value, such as summarisation, transcription, call insights, and automated follow-ups.

While interest in agentic AI grows, mainstream adoption will be limited by cost and narrow use-case readiness. Vendors will increasingly focus on making agentic capabilities more affordable, modular, and easier to deploy.

2. Data Foundations Will Become the Enabler for Context and Automation

As organisations look into value extraction, data quality and connectivity become essential. AI will need access to contextual, structured, and cross-functional data to deliver accurate outcomes and automate workflows.

To meet these needs, vendors will open their ecosystems, deepen integrations with CRM, ERP, and workflow tools, and begin supporting agent-to-agent orchestration (A2A/MCP) across front-, mid-, and back-office processes.

3. Pricing Models Will Evolve to Reflect AI Consumption Patterns

As AI features become more widely used, traditional subscription pricing will feel less aligned with the way organisations actually consume AI. Vendors will gradually introduce usage-based or metered models, allowing customers to scale AI adoption at their own pace.

To ensure reliability, AI will increasingly blend generative and deterministic approaches, supported by stronger AI observability to maintain accuracy and trust.

4. Verticalisation and Professional Services Will Help Close the Adoption Gap

AI adoption challenges vary significantly by industry. In 2026, more vendors will develop vertical-specific UC&C solutions that reflect distinct workflows in sectors such as healthcare, retail, financial services, and manufacturing.

Because the gap between vendor innovation and customer adoption persists, vendors will collaborate more closely with professional services providers who can translate innovation into practical transformation through guided deployment and workflow redesign.

5. Europe Prioritises Hybrid Deployment and Democratized AI for SMBs

In Europe, concerns around data sovereignty and transparency will continue to influence technology decisions, prompting sustained interest in private cloud and selective retention of on-premises components. Most organisations will move toward hybrid models that offer both innovation and control.

At the same time, European vendors will intensify their focus on SMBs, which represent the bulk of the region’s economy. 2026 will see continued efforts to democratise AI, offering simpler, lighter-weight solutions—such as AI receptionists—as well as modular capabilities that make AI adoption accessible to smaller businesses via partner-led delivery.

Conclusion

In 2026, enterprise communications will move forward through practical AI adoption, deeper data integration, flexible pricing, verticalised innovation, and hybrid deployment models. Markets like Europe will emphasise sovereignty and SMB accessibility, but globally, success will depend on vendors balancing innovation with pragmatism—offering AI that is trustworthy, affordable, and genuinely transformative for how people and organisations communicate and work.

For more information, drop your question in here.

For more predictions, watch IDC’s EMEA FutureScape predictions webcast here.

Oru Mohiuddin - Research Director - IDC

Oru Mohiuddin is a Research Director in the European Enterprise Communications and Collaboration team. Based in London, she is responsible for IDC’s coverage of Unified Communications and Collaboration in the region. Her work focuses on tracking the markets for premise-based and cloud solutions and new developments and trends, particularly in the light of changing work patterns impacting the traditional mode of enterprise communication. Prior to joining IDC, Oru worked for Euromonitor International, where she focused on Future of Work and technology in the SMB context. She also worked in New York and Bangladesh and speaks English and Bengali. Oru was awarded Chevening Scholarship by the British Foreign and Commonwealth Office to pursue her MSc in International Development from the University of Birmingham. In addition, Oru has a BA from Marymount Manhattan College in New York.

Graham Fruin - Senior Research Analyst, European Enterprise Communications and Collaboration - IDC

Graham Fruin is a senior research analyst in IDC's European Enterprise Communications and Collaboration team. Based in the U.K., his primary focus is on the voice and data connectivity markets. His work has a particular emphasis on the migration from legacy voice solutions to IP-based platforms and the way they are used in conjunction with unified communications. In addition, he analyzes the evolution of the internet access market, which includes the rapid proliferation of Fiber to the Premises (FttP) across Europe.

Since the arrival of ChatGPT in late 2022, the dominant AI technology narrative was that large, general-purpose “foundation models” could serve many use cases: everything from writing software code to creating marketing plans, summarizing meetings, analyzing contracts, and more.

But as we approach 2026, the tide is shifting, and it is becoming apparent that to serve targeted business use cases optimally, AI models work best when they are at least somewhat specialized. What’s more, even providers of state-of-the-art AI models are actually delivering their products and services as “mixtures of experts” (MoEs): collections of task-specialized models hidden behind a unified front-end, where each request (prompt) is routed to the specialized model that fits best.

The shift: From model selection to model orchestration

Before the rise of GenAI, choosing the best AI model architecture was a key step to success in driving an effective outcome. Even now, in GenAI implementations, many teams spend significant time trying to find the “best model” to serve a given use case. Teams scour model benchmarks, run tests, compare outputs, select a winner, and optimize around it.

However we are currently seeing an explosion of innovation and engineering advances in AI models, and what might be “best” today might very well not be best in six months (or even next month). What’s more, agentic AI systems demand flexibility. Different tasks that agents are being called on to execute are likely to require different kinds of capabilities.

Model routing enables teams to build systems that evaluate incoming requests and automatically route them to the model best suited to the job; or even combine models in sequence to produce an optimal outcome.

Why this matters: Performance, cost, and trust

The value of model routing is about more than insulation from technology entropy; it’s also about optimizing performance, cost and trust.

  • Performance: Model routing enables systems to boost accuracy and reliability by dynamically selecting the most context-appropriate model rather than forcing a generalist to handle every request. In addition, models can be selected based on where they run – at the edge, on premises, in a public cloud, for instance – due to the impact on latency as well as cost.
  • Cost control: With routing, workloads can be distributed intelligently between premium proprietary models, where needed, and efficient open-source alternatives.
  • Governance and trust: Enterprises can enforce compliance and sovereignty by ensuring certain data types are always processed by approved, region-specific, or private models.

How leaders should prepare

So what does all this mean for leaders trying to put model routing into practice? It starts with shifting mindset, strengthening oversight, and designing for flexibility from day one.

  • Adopt a multi-model mindset. Stop optimizing around a single model and start designing architectures that can host and switch between many.
  • Invest in AI governance and observability. Model routing introduces another layer of technology, and you will need monitoring systems that track system performance, quality, and cost across every route and over time.
  • Explore blends of open and proprietary models. Understand that state-of-the-art proprietary models can deliver great results, but cost and flexibility can suffer. Open models – which are massively easier to specialize, and offer deployment flexibility – may fit individual use cases very well.

IDC perspective: Routing is the road to scale

For businesses, delivering AI value at scale is about using a variety of levers to optimize results – it’s not about leveraging ever-larger models. Model routing is one of the main levers that will become increasingly important.

As businesses confront the crosscurrents of data sovereignty, compute costs, and model diversity, routing architectures provide a key tool to navigate complexity. Model routing helps organizations treat AI-powered automation as a distributed, orchestrated capability, rather than a monolith. Those who master routing will move faster, spend less, and innovate more safely. Those who don’t will watch their single-model strategies stall under the weight of their own limitations.

Download IDC FutureScape 2026: AI & Automation Predictions to explore how routing, orchestration, and agentic architectures will redefine the enterprise technology stack.

Neil Ward-Dutton - VP AI, Automation, Data & Analytics Europe - IDC

Neil Ward-Dutton is vice president, AI, Automation, Data & Analytics at IDC Europe. In this role he guides IDC’s research agendas, and helps enterprise and technology vendor clients alike make sense of the opportunities and challenges across these very fast-moving and complicated technology markets. In a 28-year career as a technology industry analyst, Neil has researched a wide range of enterprise software technologies, authored hundreds of reports and regularly appeared on TV and in print media.