As geopolitical tensions continue to rise, the global semiconductor supply chain must add new locations outside of existing ones to meet customer requirements. In the past, semiconductor manufacturing was concentrated in the Greater China region (China and Taiwan). However, under the trend of de-risking and globalization, the demographic dividend and cost advantages in Southeast Asian (SEA) countries and India, which are also mostly members of multilateral trade agreements such as the RCEP and CPTPP, have made it the next important semiconductor development base.

With its strengths in packaging and testing, Malaysia is actively expanding into semiconductor manufacturing and design. Singapore is the only country in SEA with foundry manufacturing and the most complete semiconductor supply chain. Vietnam and the Philippines have a competitive advantage in terms of cost and labor and have been in recent years actively developing their testing and packaging capabilities, among other areas. India has a large domestic market to attract investments and strong capabilities in design, innovation, and talent. The governments of these countries also have lucrative incentive programs to get the attention of semiconductor market players. Overall, SEA and India have built a solid foundation in the semiconductor supply chain and are aggressively looking to expand into high-value-added areas such as wafer fabrication and design.

But, do Southeast Asia and India have the right conditions to capitalize on semiconductor market opportunities in the future? IDC believes that to develop its foundry industry, six major challenges need to be addressed in the short term:

  • Infrastructure – At present, the primary issue for the development of the industry in SEA countries is the availability of adequate infrastructure, including reliable power supply, water resources, transportation networks, and telecommunications, all of which are critical to semiconductor fabrication. Compared to other electronics manufacturing industries, the semiconductor industry’s technical operations and manufacturing are more complex and problems such as power outages will result in huge losses. Among SEA countries, Singapore is the only one that is currently attracting fabs with its well-developed hydroelectric infrastructure and high degree of coordination in power supply. Vietnam’s power shortage has led to discussions between Samsung and power companies to cushion the impact, leading the government to emphasize that it will strengthen research spending and investments in power plants. Malaysia has also stressed the importance of infrastructure investment in its newly released National Semiconductor Strategy.
  • Talent/Labor Force – The availability of skilled and well-trained labor has always been critical to the development of the semiconductor manufacturing industry. Fabs need to have a strong talent pool in engineering, materials science, and electronics. In foundries, semiconductor process engineers are at the center of this demand. Engineers need to be able to manage the entire process of wafer/chip manufacturing, improve processes, assess and manage risks/problems, perform testing and monitoring analysis, and introduce new processes. They also need to build analytics, provide analytical data, and help integrate requirements and material selection to establish the optimal balance between quality, yield, and cost. The knowledge and experience of engineers definitely affect the outcome of the entire manufacturing operation and obviously, the cultivation of relevant talents cannot be accomplished overnight.
  • As talent is key to semiconductor development, Malaysia has planned to train and upgrade the expertise and capabilities of 60,000 highly skilled engineers. The Vietnamese government is expected to allocate USD1.06 billion (VND26 trillion) to implement a semiconductor talent training program for 50,000 semiconductor engineers. India’s Semiconductor Incentive Program also plans to train 85,000 engineers in the next 10 years.
  • Customer and Supply Chain Ecosystem – Proximity to key customers, supply chains and target markets reduces transportation costs, lead times and transportation risks, and allows for faster response to customer demand and supports just-in-time production. Semiconductor supply chains require an ecosystem of raw materials and logistics to support local investment. In foundry, for example, a fab with a capacity of 30,000-40,000 wafers/month will need at least 10 nearby material suppliers, even if they are not in the vicinity of the fab. To support this supply chain, it must have a strong/efficient port or air cargo system with high throughput. An end-to-end semiconductor supply chain and a well-prepared ecosystem is important and takes time to build.
  •  Geopolitical Stability – In the past, the semiconductor industry emphasized the division of labor among specialties, but with the tense U.S.-China relationship, customers are more concerned about the resilience of the supply chain than ever before. Today, countries are actively developing their own self-sufficient semiconductor supply chains to reduce dependence on others. With geopolitical factors interfering, the location of production and the stability of the supply chain have become important considerations.
  •  Tax Incentives and Government Regulations – Since semiconductor is a capital-intensive industry, local government tax credits will be one of the main incentives for fab companies to consider investing in a country, which is currently one of the tactics used by SEA and India to attract foreign investors.
  • Semiconductor Manufacturing Working Culture – Different parts of the semiconductor industry chain have different operating mechanisms and cultures. In the case of chip manufacturing, which SEA and India semiconductor manufacturers are actively looking to develop, the production line usually operates 24/7. Employees must not only be willing to work in shifts but should also possess a culture of “immediate response” when problems arise. In a high-yield, high-productivity fab, where process engineering/operation and quality are the top priorities, line management is very stringent because any small mistake can result in a huge loss (e.g., lead to wafer scrap) or a safety issue. Engineers and production line personnel need to ensure smooth operations and to be on-call even during off hours. Although SEA and India already have more manufacturing experience and talent than the U.S., where most of the talent is oriented to software, IDA/IP, and Fabless, it may still be difficult to establish the talent and cultural mindset for semiconductor manufacturing in this sub-region in the short term.

Chip Design Challenges: Talent and Innovation Capabilities

In addition to chip manufacturing, IC design is also an area that SEA and India are looking to develop. Increasing the number of chip-relevant start-ups is undoubtedly a key driver in attracting global semiconductor companies. India, Malaysia, and Vietnam have set up different incentive programs or established parks in the hope of attracting and expanding innovation and design capabilities.

In terms of long-term development, IDC believes that an entrepreneurial ecosystem needs to be established, which includes the government and venture capitalists that will support R&D capacity, without which, it will be difficult to attract high-density capital. After the ecosystem is established, if vertical solutions (agriculture, health, payment, etc.) and automotive/electric vehicles, artificial intelligence, and its related applications can be built, SEA and India will be able to further synergize the development of semiconductor chips, which is probably one of the advantages that can be developed in the sub-region, especially with the support of its huge domestic demand market.

However, it will take time to build semiconductor industry talent and ecosystem. IC design engineers need to have a university degree in Electronics Engineering, Electrical Engineering and information software development. Logic IC engineers may learn faster with the help of EDA/IP tools, but Analog IC engineers who must deal with noise (e.g., automotive, Internet of Things), will need to rely on experience. It takes at least 3-5 years for an IC design engineer to be able to run a project independently, and an even longer learning curve for an analog IC design engineer.

At present, Malaysia, Vietnam and India are working towards the development of their chip design capabilities by attracting foreign investments and overseas start-ups, which I think is a very smart approach. As it takes a long time to train relevant talents, it will be more effective to train them through foreign aid rather than locally. Because of its higher salary, immigration policy, and tax advantages, Singapore has developed faster than other South Asian countries in acquiring outstanding overseas engineers.

Challenges for Packaging and Testing and OSAT: Further Expanding Capabilities

Compared to chip manufacturing, packaging and testing/OSAT is more labor-intensive, an advantage for these countries. However, to expand on existing foundations, more consideration is needed to attract chipmakers. Often, OSAT vendors follow the lead of foundry’ locations to ensure logistics and operating costs remain low. In the future, if SEA and India can establish or attract chipmakers locally, it will help to improve their OSAT environment. Of course, it is also important to attract IDMs to set up packaging and testing plants, which is also the development direction in most of these countries.

Conclusion

Under the influence of geopolitics, the U.S., Europe, China, Japan, Korea, and Southeast Asia are beginning to launch their own semiconductor policies, placing more emphasis on the autonomy, security, and controllability of their own supply chains. Under the “push” and “pull” strategies of governments, the traditional market-based competition model for semiconductors is changing, and Southeast Asia and India have been recognized as an important potential base for the next stage of development. Semiconductor is a highly capital and technology-intensive industry, and its R&D and manufacturing require the support of a complete supply chain. Infrastructure, utilities, technology, capital, talent, and ecosystems are all long-term challenges for Southeast Asian countries to successfully develop their semiconductor design and chip manufacturing sectors beyond testing and packaging.
Helen Chiang - Country Manager - IDC

Helen Chiang is the lead of Asia Semiconductor research and the general manager of IDC Taiwan. She is responsible for analysis, forecast, and research of semiconductor supply chain sectors such as IC design, OSAT, and Asia IC design, AI and automobile semiconductor. Since joining IDC in 2007, Helen conducted numerous research and consulting projects about semiconductor, cloud, AI, IoT, security, emerging technology and vertical market in Taiwan and across Asia Pacific region. She also provided professional market analysis and high-value consulting strategy to C-level managers. She not only leads the team to develop new market opportunities successfully, but also to provide customers with long-term growth capabilities.

Building strong detection and response capabilities is vital for organizations seeking to improve their cybersecurity posture and business resilience.

Many organizations do not have the in-house skills or resources to make the required improvements in detection and response. For example, just 15% of large organizations in Europe have sufficient security operations center (SOC) analyst skills in house, and churn and burnout among these analysts are often high. These challenges can have a strong negative impact on a company’s cybersecurity posture.

Consequently, many organizations are turning to service providers to fill specific gaps in their detection and response capabilities or are outsourcing their requirements in full.

The high level of interest in managed detection and response (MDR) has led to many service providers entering the market, which has now become highly competitive, providing customers with a greater range of services. This is not always the case for IT services markets, some of which are dominated by a handful of players.

The choices for detection and response include telecom and network players, IT services companies, systems integrators, cybersecurity specialists, professional services companies, and vendors with services offerings. Each has something different to offer enterprises.

Many of the service providers in this market have a global presence, others have a more regional focus. Service providers have different types and levels of skills and knowledge, and so there are differences in the ways they can support the unique needs of European organizations.

Europe is a complex patchwork of numerous factors, including cultural, language, economic, and regulatory  factors (among others)meaning that in-region (and sometimes in-country) capabilities are vital to meet customers’ objectives.

The IDC MarketScape: European Managed Detection and Response Services 2024 Vendor Assessment examines the strengths and weaknesses of leading providers of European MDR services. We have identified eight leaders and nine major players in this market, providing a detailed analysis of the services offered by each; this is aimed at providing European organizations with clear guidance to assist them in their purchasing decisions.

There are marked differences between providers in terms of target customers, technical capabilities, and detailed expertise in addressing the needs of European organizations. Organizations should evaluate all these aspects carefully to ensure they choose a service provider that delivers on their business and technology objectives. This will include making optimal decisions that relate to technical capabilities, services and skillsets, target markets, and strategic roadmaps.

One critical area to consider is onboarding and time-to-value. Customers should ensure they are clear on delivery capabilities and the desired operating model. They should be fully informed by their provider in advance how they will be onboarded and the timing of key steps.

As the threat landscape is becoming ever more complex, with a growing ecosystem of actors, the need for proactive detection and response capabilities is becoming essential for all organizations across the region. According to IDC’s EMEA Security Services Survey, MDR is now a priority for 65% of organizations, with the market in Europe forecast to record a compound annual growth rate of 29.2% from 2022 to 2027.

IFA has traditionally been a home entertainment and appliances show targeting the European market, but this year there were a lot of global PC announcements as vendors were eager to get the word out on AI PCs, particularly after Computex in Taiwan a few months ago. We were excited to be on the ground in Berlin this month to catch the action.

Chip vendors led the charge, with Intel providing more details for Lunar Lake, now officially named Core Ultra 200V, with the “V” designating a premium against Meteor Lake. One of the most important details provided was around battery life, which looks more promising now than what was discussed at Computex. If real-world tests hold true when shipments commence later this year, Intel will be on better footing, especially given its competitive advantage with developers. Qualcomm didn’t stand by idly by though; it also released its lower-tier Snapdragon X Plus in both 8 and 10-core variants, allowing OEMs to target the US$700 range that Lunar Lake isn’t addressing yet.

With new chips comes new design wins with PC OEMs, who showcased an array of models, as well as a number of attention-grabbing concepts. My teammates Tom Mainelli and Linn Huang will be diving deeper into some of these developments in a dedicated report, but there were some high-level highlights, including some other devices at the end for good measure:

  • Lenovo introduced its Intel-exclusive Aura Edition products within the ThinkPad and Yoga lines, featuring Smart Modes that adapt device settings based on usage, Smart Share that leverages Intel’s Unison phone sharing, and Smart Care that provides a nice feed into Lenovo’s services arm. Lenovo separately talked up its AI PC Fast Start, which is not about boot speeds like the name might suggest, but instead, a lifecycle service to help organizations deploy AI. What might have garnered the most attention though – and such differentiation is important in such a crowded week of launches – was Lenovo’s voice-driven Auto Twist AI PC, which was a concept only but nonetheless elicited oohs-and-ahs.
  • Acer talked up battery life on its new Swift notebooks powered by Intel, AMD, and Qualcomm, while also diving into gaming, including a 600 Hz monitor, a detachable controller in its Project DualPlay concept, as well as its Nitro Blaze 7 handheld gaming PC. We are concerned that the Windows-based handheld market doesn’t have room for so many vendors yet, but we also think that existing designs have plenty of room for improvement, so Acer’s entry in this segment is a welcome one in that regard.
  • ASUS rolled out updates to its consumer product lines as well as a new P-series in its commercial ExpertBook lineup, focusing on SOHOs and creators and leveraging ASUS’ consumer-leaning strengths. Its newly acquired NUC team also showed off its ultrasmall desktop lineup, including a Lunar Lake-based one with a Copilot+ button and fingerprint readers.
  • Honor rolled out its Magic Notebook Art 14 featuring a detachable webcam that comes with a built-in storage bay on the side. Pogo pin-based webcams are not new in the industry (Lenovo has a range of Magic Bay accessories for its ThinkBooks), but this nonetheless is in character for Honor, which isn’t afraid to use its engineering skills to differentiate its hardware. Indeed, Honor also showcased its impressively thin yet durable Magic V3 foldable phone, which is now ready for overseas markets rather than being China-only. In the process, Honor unveiled more progress on Yoyo, its AI agent in China, which can take over a user’s screen to automate application tasks like a human would.
  • Phones were not a major focus at IFA, but Google had its Pixel lineup on-site, and HMD presented samples of its Barbie phone off-site. TCL and Transsion’s Tecno brands had booths on the show floor, with TCL advertising its Microsoft-powered AI features on its phones and Tecno interestingly veering into PCs with an ultrasmall form factor gaming desktop loaded with an RTX 4060. Smaller Chinese phone brands like uleFone, Cubot, Oukitel, and Doogee also maintained booth presences, similar to their participation at shows like MWC.
  • Chinese wearables vendors were present, with earwear being a significant focus given IFA’s consumer electronics legacy. Hisense showcased its TVs, leveraging its official marketing partnership with the recent hit game Black Myth: Wukong. Appliances like smart vacuums and electric scooters were prominent, especially from Chinese vendors. But AR/VR headsets were limited, and there was only one AI pin that we noticed: the Plaud NotePin notetaker, which was featured at a small media-only event the night before the show floor opened.

The momentum around AI PCs has continued to build, which is a good thing for the sake of generating awareness. And software like Lenovo’s Creator Zone and Intel’s AI Playground that make a range of multimodal models easy for users to access is a good thing. Unfortunately, there is still a lack of big use cases otherwise, which means that much of the upcoming 4Q24 device launches will be more of a supply-side push of the latest processors. The good thing though is that battery life comparisons are now crystallizing, and this may very well be the more important thing given the industry’s ongoing struggles to compete with the perception of MacBooks lasting all day.

Bryan Ma - Vice President - IDC

Bryan Ma is Vice President of Client Devices research, covering mobile phones, tablets, PCs, AR/VR headsets, wearables, thin clients, and monitors across Asia as well as worldwide. Based in Singapore, Bryan provides insights and advisory services for both vendors and users, and coordinates his team of analysts in building IDC's core market data, analysis, and forecasts in these sectors. Bryan has been quoted in a number of publications, including The Wall Street Journal, The Economist, The Financial Times, BusinessWeek, The South China Morning Post, and The New York Times. He has been a featured speaker at numerous industry conferences and appears frequently as a guest commentator on television networks such as CNBC, Bloomberg, and the BBC.

Climate Week

From September 22-29, New York City hosts Climate Week, an annual event that brings together global leaders, policymakers, businesses, and civil society to tackle the pressing challenges of climate change. The week features a series of conferences, workshops, and exhibitions to promote sustainable practices, address climate justice, encourage international cooperation, and raise public awareness. Each year, we are reminded that the past 12 months have marked yet another “Top 10” high for global temperatures, emphasizing the urgent need for action—though the pace of change remains frustratingly slow.

The Data Center Dilemma

The data center industry has come under increasing scrutiny for its environmental impacts and rapid growth, driven partly by AI technologies’ energy demands. For example, in its sustainability report released in May, Microsoft said its emissions grew by 29% since 2020 due to the construction of more data centers designed and optimized to support AI workloads.  Likewise, Google reported increased electricity demand driven by artificial intelligence, and its growing fleet of data centers has caused the company’s greenhouse gas emissions to grow by 48% above its 2019 baseline, creating a challenge for the tech giant in meeting its carbon neutrality goals by 2030.

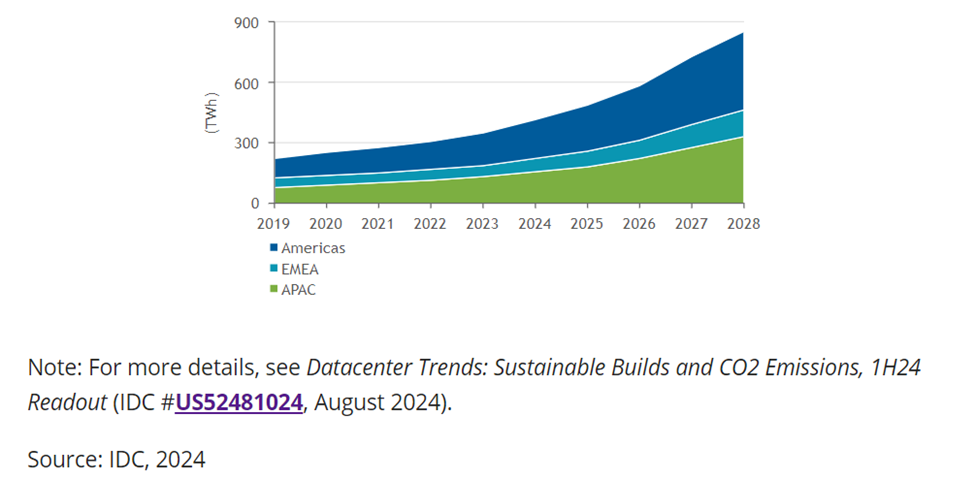
These companies should be applauded for their transparency and courage to tell the facts as they are.  It demonstrates leadership, promotes learning and improvement, encourages industry standards, and, most importantly, highlights the problem. This ever-increasing facility growth and electricity consumption poses a significant struggle as data centers strive to balance the need for increased computational power with the imperative to minimize their environmental footprint. IDC calculates worldwide data center energy consumption for 2023 to be 352TWh and projects a 19.5% CAGR, growing to 857TWh by 2028.

While harder to quantify due to of a lack of standards and available information, scope 3 emissions from constructing and outfitting data centers with IT equipment also contributes to industry emission growth.  

Why Aren’t We Seeing More Progress?                               

While AI garners most market attention, when surveyed, datacenter operators indicated that improved environmental sustainability was their second-highest initiative, ahead of AI, but behind business and financial management.

So, if the data center operators know and prioritize the problem, why isn’t more progress being made?

Like most complex problems, there are a multitude of factors that contribute to it. 

  • Demand – The first is the demand for digital services.   As enterprises pursue digital transformation and invest in artificial intelligence to create unique value, the demand for data centers and the associated electricity consumption is rising substantially.  Organizations are unwilling to sacrifice operational improvements and gains they expect from these efforts to meet sustainability goals.  
  • Global political cooperation and policy. It will take a combination of political agreements, like the Paris Agreement, and stricter local regulations on emissions to drive the change in behavior and investment in renewable energy infrastructure.
  • Transition to Renewable Energy. As governments and businesses set ambitious targets to reduce carbon emissions, the demand for renewable energy is outpacing supply, and globally, electric demand is outpacing new generation supply.  Many electricity grids were built for centralized, fossil-fuel-based power generation and are not yet fully optimized to handle the decentralized and intermittent nature of renewable sources like wind and solar.

Taking Immediate Steps on Energy Efficiency

The phrase “Think globally, act locally” has been part of our collective consciousness since the 1970s, resonating across various societal challenges due to its timeless relevance. Today, this principle particularly applies to datacenter operations. While most datacenter operators may not have the influence to shape global policies or invest directly in large-scale renewable energy initiatives, they can drive change by focusing on energy efficiency at a local level to reduce demand.

While some companies or individual executives prioritize sustainability metrics, viewing environmental responsibility as a critical driver of their decisions, others see these efforts as secondary or “soft” benefits. For this latter group, decision-making is anchored in hard financial metrics, focusing on return on investment (ROI). Energy efficiency initiatives appeal to both types and are aligned with top datacenter priorities.

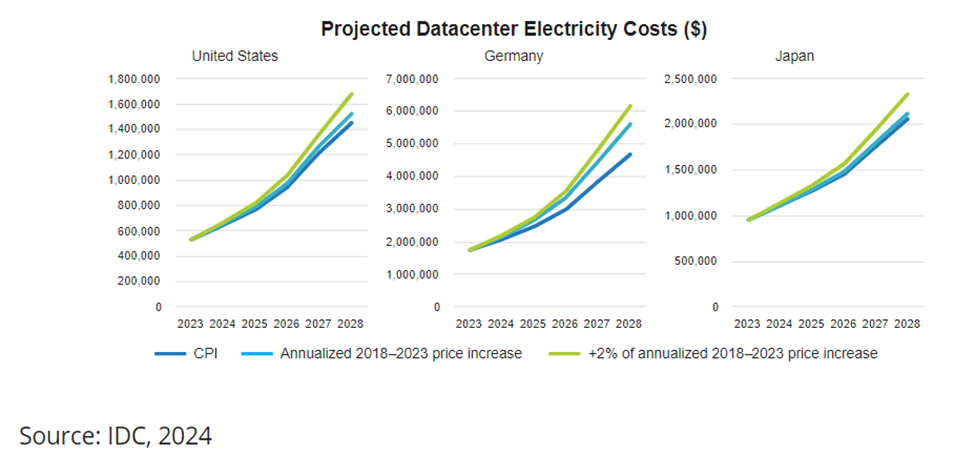
Electricity costs account for the most significant portion of data center facility operating expenses—ranging from 45% to 60%—depending on location and data center type.  Simultaneously, growth in industrialization and electrification have led to higher electricity demand, outpacing generation, which is expected to cause electricity prices to increase. The combination of rising electricity prices and increased electricity consumption is poised to make data centers significantly more expensive to operate.

To assist organizations in understanding the potential impact, IDC published The Financial Impact of Increased Consumption and Rising Electricity Rates in Data Center Facilities.  The research includes scenario planning for a 1 MW data center in the United States, Germany, and Japan.   IDC projects that a typical 1 Megawatt data center consumed 6.6 Gigawatt hours (GWh) of electricity in 2023 and will grow to between 13 to 16 GWh by 2028 through capacity expansion, increased utilization, and higher density deployments. Simultaneously, IDC expects energy costs to continue to grow above historical levels.  The percentage growth in electricity spend will exceed a CAGR of 15% in all cases, with most scenarios showing growth of over 20%. When measured in absolute spending increase, it is expected to near or exceed $1,000,000 annually.

While the model assumes energy efficiency improvements, an organization can expect to save between $500K and $1,900K with energy efficiency improvements that are 10% greater than the industry average.

Conclusion

Prioritizing energy efficiency in data centers is no longer just a matter of environmental responsibility—it’s essential for sound datacenter financial management. As the demand for digital services, AI, and cloud computing continues to soar, the pressure on organizations to minimize their carbon footprint while managing rising electricity costs will only intensify. By taking action now—investing in more energy-efficient technologies and optimizing operations- organizations can reduce their environmental impact and significantly cut operating expenses, their top two priorities. The financial and environmental stakes are clear, and the time to act is now. Energy-efficient data centers are essential for the future of business and the planet.

The digital economy is frequently regarded as a beacon of innovation and growth, both influencing and being influenced by ICT spending. Today, there is increasingly more impact on the economy from the digital world. However, the digital economy itself is a complex ecosystem, influenced by countless macroeconomic factors that shape its development and trajectory. There are global economic trends in inflation and overall technology, “background” developments in raw material supply chains that influence technology hardware procurement, and ongoing, fast-paced advancements in emerging technology. Understanding these influences is crucial for uncovering the full picture of the digital economy’s potential and challenges.  

Understanding the economic impact of new technologies and quantifying it is not immediate. IDC’s Worldwide Digital Economy Strategies Program, in collaboration with IDC’s Data & Analytics team, developed a Digital Economic Impact model over the years and recently applied that to the key technology of the moment: artificial intelligence (AI). We chose AI, as it is not only on everyone’s mind, but is also a paradigm shift that’s reshaping industries, economies, and societies at an unprecedented pace. As we explore the macroeconomic factors influencing the digital economy it becomes clear that AI is both a product of these factors and a key driver of change within this dynamic landscape.  

According to our model we found that Business AI (consumer excluded) will contribute $19.9 trillion to the global economy and account for 3.5% of GDP by 2030. You can read the report or press-release for full details, but how did we calculate this? Our economic impact analysis leveraged data from our Spending Guide and other sources to help understand both the immediate impacts of AI spending and the interaction with broader economic forces at play which we explain below. 

Understanding How AI Impacts the Economy: Economic Impact Models 

As aforementioned, AI will account for 3.5% of GDP by 2030. To estimate the overall impact of a technology product or service, IDC developed an economic impact methodology that combines IDC’s knowledge of the market and internal data with a standard analytical framework that leverages the most updated countries input-output (I/O) tables.  

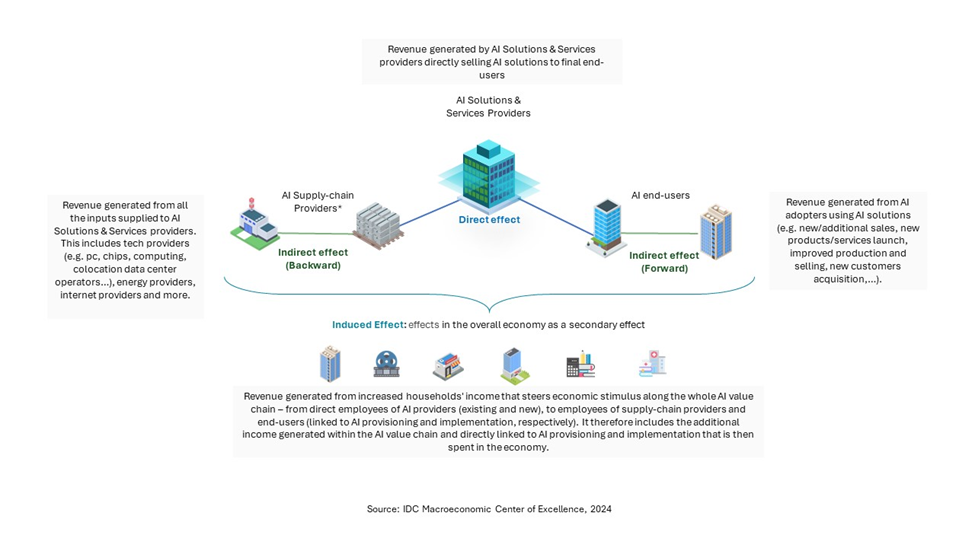
In brief, the economic impact of AI can be sub-categorized into direct, indirect, and induced effects. 

Direct Effects

Direct effects refer to the income generated by providers of artificial intelligence solutions or services from their direct sales to customers. In other words, it is the revenue of solutions/services providers when directly selling their products to end users. Essentially it is the revenue of an AI vendor when selling their solutions or services.

As a concrete example let’s take the case of a company that develops and sells AI-driven customer service chatbots. When this company successfully sells its chatbot solutions to online retailers, that revenue generated from these sales represents the direct economic impact of AI.

Indirect Effects

Indirect effects involve the economic impact related to the AI supply chain and the advantages gained by entities that adopt AI, such as enhancements in productivity and revenue growth. This category also includes the influence that organizations or technology providers exert on a regional or national level through their AI-related operations. Indirect effects are further divided into “backward” and “forward” categories. Backward indirect effects refer to the economic effects on supply chains and industries that provide inputs to AI-driven sectors, in other words, revenues generated in local industries impacted by AI. Forward indirect effects refer to effects on AI adopters that benefit from the adoption of AI technology in terms of productivity, revenue growth, and other business parameters.

More concretely, backwards indirect effects include all inputs supplied to AI solutions from the backend: including PCs, chips, computing, colocation datacenter operators, energy providers, internet providers, and more.

On the forward effects side, this includes concretely any increase in revenue coming from different factors such as the introduction of enhanced products or services, improvements in production and sales processes, or gains in customer acquisition that result from the implementation of AI.

Induced Effects

Induced effects stem from increased household income due to AI-related activities, leading to higher consumer spending and broader economic benefits. These are secondary effects, referring to economic stimulus coming from increased household income, including existing and new employees linked to the AI value chain across direct and indirect effects layers. People will spend part of their new wages in the economy, thus generating additional economic impact.

For example, let’s take a manufacturing company with an ambitious AI strategy that has installed a dedicated AI team, hired specialists, etc. This company may pay higher salaries to this AI team due to the increased demand and profitability of AI products. As these engineers receive higher incomes, they have more disposable income to spend on goods and services within their community, perhaps buying a car or dining out more frequently. These purchases inject additional money into the local economy, benefiting various sectors such as the automotive industry, restaurants, and construction businesses. It serves as a “ripple effect” of increased consumer spending stemming from AI-related economic activities.

Things To Watch Out For

These numbers, however, do not mean the journey from investment to monetization and economic impact is straightforward. In the case of AI, many companies are starting to question which use cases truly add value, and we are also seeing that regulation and questions about the ethical use of AI are increasingly important topics. From our Global Future Enterprise Resiliency & Spending Survey, tech decision makers (IT and LoB) reported an overage of 37 GenAI PoCs in the last 12 months, with only 5 making it into production, on average. Out of these 5, they reported a 68% success rate. That means a lot of PoCs failed, a testament to the long road ahead for AI’s real impact. While it is true that AI doesn’t necessarily guarantee immediate returns, AI’s economic impact will play out over time as the market matures. It is also crucial to keep this long-term perspective in sight while making executive decisions on implementation and deployment.

Going Forward

The interplay between AI and the broader macroeconomic factors is reshaping the digital economy in profound ways. Direct, indirect, and induced effects of AI all underscore AI’s role as a transformative force within the global economy. The model we applied here can also be applied to other kinds of transformative technologies.


Contributing Authors:

Elisabeth Clemmons - Research Analyst - IDC

Elisabeth Clemmons is a Research Analyst for IDC's Worldwide Small and Medium Business Markets program, where she covers the technology priorities, needs, challenges, and goals of small and medium businesses across the globe. Leveraging primary and secondary SMB research, she provides insights into technology trends and developments, buying patterns, market segmentation, and more. She additionally serves as an analyst for the Digital Economy Strategies research theme, covering the interrelationship between geopolitics, macroeconomics and the technology industry.

Digital business is just standard business in 2024.

Companies striving to participate in the digital economy are looking to invest in technology that fits the needs of their company size, employee personas and functions, industry verticals, and current level of technology maturity. Vendors hoping to sell and implement digital technologies need to consider all these factors when meeting with a potential customer. Segmenting and grouping customers by all these factors can help technology vendors provide the best messaging and service.

At IDC, we do research that considers the impacts of all these factors, and that gives us insight behind the tech buying curtain into the needs and wants of buyers at all stages of their digital journeys.

The Small and Medium Business Market

In the recent IDC Webcast, “Behind the Tech Buying Curtain: What Vendors Need to Know,” Katie Evans, IDC Senior Research Director for Worldwide Small and Medium Business Markets, said there are three key topics keeping SMB tech buyers up at night: AI/automation, macroeconomic woes, and heightened security concerns largely fueled by AI, remote work, and the moving to the Cloud.

The forward-looking investment priorities for SMBs are all automation and AI related—process automation, connectivity automation, AI (non-GenAI), and GenAI, according to IDC’s Worldwide Small and Medium Business Survey. Rising energy prices highlight SMB’s top macroeconomic woes in that survey, while implementing technology securely is the largest technology challenge.

Macro Factors Impacting Investment

IDC’s Digital Economy Strategies research, led by Research Analyst Elisabeth Clemmons, focuses in part on the macro landscape impacting businesses, even those focused in specific countries or localities. Impactful events and trends include skills shortages, inflation, supply-chain constraints, energy crises, tensions between countries and war, and elections around the world. These events impact technology buying patterns, causing companies to be more cautious with their investments.

AI is the technology most likely to persevere and be prioritized in the face of these macro impacts, with AI spending, the AI provider supply chain, and the economic stimulus among AI adopters is projected by IDC’s Macroeconomic Center of Excellence to be 3.5% of global GDP by 2030.

The heightened impact of and investment in AI is contributing to two more macro trends impacting businesses: digital regulation and potential raw materials shortages. Data and AI is a top regulatory target with governments taking diverse approaches, while the sheer amount of data in the world is expected to more than triple by 2028—necessitating over 50 times the current annual production levels of neodymium and other critical raw materials.

C-Suite Leaders Increase Focus on AI

Despite any concerns and challenges that AI my pose, CEOs are scaling AI initiatives, dedicating budgets to AI, and ensuring AI projects receive greater visibility, according to Nupur Singh-Adley, Research Manager leading IDC’s C-Suite Tech Agenda research.

As C-suite leaders focus on building digital businesses buoyed by AI technology, they are also mindful of managing risk, including heightened cybersecurity threats and regulations. This is leading to prioritized spending on security, risk, and compliance technologies and greater scrutiny of cybersecurity and risk management at the board level.

Along with considering risk, CEOs are also prioritizing responsible AI while building digital businesses that are focused on trust, critical evaluation of tech vendors, and sustainability.

Digital Capability Perception vs. Reality

While companies of all sizes are facing challenges both internally and externally and they digitize, it’s important for technology vendors to consider that many are also overestimating their digital capabilities. In IDC’s Digital Business and AI Transformation Strategies research, we conduct an annual Digital Business Scorecard that measures the digital capabilities of businesses in four areas: Digital Business Models, Data, Operational Processes, and Organization.

Overall, when asked to assess themselves, 41% of those surveyed in IDC’s Digital Executive Sentiment Survey believed they were a “mostly digital business.” However, when applying our Digital Business Scorecard methodology, which correlates investments and strategies to business outcomes, only 11% of that same survey sample were categorized as “Digital Business Leaders.”

Digital Business Leaders are taking holistic digital strategies and have implemented world-class technology. They view data as a top AI priority while also expanding its use in core operational processes. They have a digital technology architecture that is in lockstep with IT strategy and are focused on improving recruiting and employee engagement.

These are the standards that many of those companies that think they are digital aren’t quite achieving—often finding themselves bogged down by inferior technology, not focusing on capitalizing on the value of their data, not looking to automate and standardize processes, and not taking the view of technology as a competitive advantage.

The Important Role of Technology Vendors in the Digital Economy

Technology vendors are key to digital business and AI transformation strategies—and many companies need vendor expertise and guidance to help them become digital business leaders. Vendor messaging to these companies can be challenging—but it helps to know how company size, macroeconomic impacts, C-suite leadership, and digital capability and perception impacts buying conversations.

It’s helpful for vendors to segment their customers, and specialize their strategy and messaging to those individual segments. That’s beneficial for all parties and will help companies succeed in the digital economy.

Learn what matters most to your customers with IDC’s AI Use Case Discovery Tool—find out more.

When something breaks in your home, your office, or in a venue you frequent what is your expectation? Is it that you will just deal with having a broken product, offline printer, or down elevator? Most of us would expect a service technician will show up to the rescue to return the given product or asset to operations so we can get back to productivity.

In IDC’s recent Product Innovation and Aftermarket Services Survey, service leaders noted a priority to improve service (quality and speed) to customers. But too often, aftermarket service organizations have focused on just ensuring a warm body arrives on a customer site within the service level agreement (SLA) with little importance put on actually achieving resolution or enhancing the customer experience.

As customers explore options for the services they receive, aftermarket service providers will need to get better at delivering more than just the minimum to enable the field service team to become experts on engaging a customer in a special and personalized way. Field service and the aftermarket are too often driven by meeting a SLA. This minimum requirement of meeting a service window of 4-8 hours after a failure has been reported, or processing a warranty claim within 30 days, or ensuring an asset is available 80% of the time has long been the norm. Meeting minimal requirements is quite profitable for the service organization, but can be short-sighted as competitors enter the market and begin to offer service, support, and enhanced experiences of the same or better quality.

To address this pending disruption of competitive factions and heightened customer expectations, field service organizations will need to prioritize value and not just meeting an SLA. This will raise the cost to serve in the short term but in turn result in having the right to request more share of customer wallet as value delivered improves for the customer or operator. This shift to value and enhanced/personalized experiences will ultimately require better quality data, contextualized customer insights, and freed up time to focus on delivering value. Artificial intelligence (AI) provides an opportunity to close the gap between data and insights on the front line. IDC defines AI as the ability of computers to learn without being programmed, applied to large sets of data for business advantage. But how should field service organizations reconcile the hype around AI to usher in the era of intelligence at the point of service? Field service organizations should prioritize the following as they explore the potential of AI in the coming weeks, months, and years:

  • Understand the pulse of your employees and customers. Voice of customer and voice of employee activities often are established for the primary benefit of the organization (i.e., increase sales/margins, increase retention rates). In this new era of AI, field service organizations will need to listen to the needs and concerns of customers and employees. As AI becomes more pervasive across industries, field service organizations must tackle the elephant in the room around AI – privacy, and job displacement. Too much of the discussion around AI in the B2B world has been the fear that it will replace jobs or result in IP theft. This view of potential negatives neglects to amplify all of the potential positive outcomes of what AI can offer, Educating customers and service employees about the value of AI and how these technological capabilities can improve the service experience, customer outcomes, and employee productivity is crucial to adoption and comfort. Without understanding customer and service employees’ fears about AI, organizations will struggle to maximize the opportunities that will come with this innovative technological advancement.  
  • Shift the KPI that measure success in the field. The promise of AI in field service revolves around improved operational efficiency, predictive/prescriptive service outcomes, and improved productivity of the team. However, there is a bit of a gap between the current metrics that are being measured and what should be measured in the AI era. If AI is to improve the speed of service, technicians should be measured on the value they are providing to the customer and not on how many more jobs they can complete. The improved speed of issue resolution as a result of AI providing better answers to the reason for failure should allow the humans on the service team to focus on the customer. This shift in what role a field service technician can play in customer outcomes is profound, no longer is the technician solely in place to turn a wrench but to prioritize customer engagement. Therefore, the KPI that matter aren’t work orders closed in a given day but experiential and value based. These new metrics may be more difficult to measure but will tell a better story of customer impact, future revenue opportunities, and lifetime value.
  • Highlight the positive and address the (potential) negatives. Right now, there are too many field service technicians that can efficiently get on site in front of a customer or asset but fail to resolve the issue on a first visit. Issue resolution is becoming more and more complex as assets are smarter, supply chain networks struggle with resiliency, and the field force ages out. The ability to have the right part, right skills, right insights, at the right time is becoming a fairy tale for too many service organizations. On the front line is the field service engineer who has to advise a customer or operator in need that service cannot be completed resulting in assets, products, and equipment remaining down. Service leaders must communicate to the field service team both the in office planning/dispatching teams and the engineers in the field the ability for AI to drive insights and efficiency while reducing non-value added task work. The skepticism of technology from service teams has preceded the AI era, but the AI conversation brings with it the fear of machines taking over to the detriment of the humans. However, fear comes from a lack of communication, visibility, and buy-in around strategy and execution. AI can enable service workers to be the expert in a time of customer need and also free up their time from rote administrative tasks. AI must become an opportunity for the service team and not a murky monster.

Artificial intelligence will have a large impact on the field service organization and the customer experience. Service leaders need to understand the opportunity, embrace the challenge, and educate customers and employees to ensure the AI era is a net positive driving growth of the organization.

For more information on CX and AI, read our other blogs:

Learn what matters most to your customers with IDC’s AI Use Case Discovery Tool—find out more.

Aly Pinder - Research Vice President - IDC

As Research Vice President, Aftermarket Services Strategies, Aly Pinder Jr leads IDC research and analysis of the service and customer support market for the manufacturer, which includes topics such as field service, warranty operations, service parts management, and how these service areas impact the overall customer experience. Mr. Pinder Jr. establishes a roadmap for organizations to better understand how technology can transform service and support functions to drive exceptional customer experiences and customer value, profitable revenue growth, and improved efficiency in the field.

Faced with the need to staff up quickly to carry out a generative AI initiative, Sanjay Srivastava did the logical thing. “We brought in kindergarten teachers to do prompt engineering,” says the chief digital strategist at Genpact, a professional services firm. Although the decision might appear unorthodox, it’s consistent with Srivastava’s fundamental outlook. He is a strong believer in hiring people from a variety of backgrounds who possess a vital trait: the ability to learn.  

“My whole view of life is that we cannot know the skills we will need tomorrow. So we need curiosity, humility, and the desire to learn the answers, not to already know them,” he explains. “The people we hired from a very different walk of life worked out the best,” he adds.  

Srivastava has discovered what many IT leaders are learning: that in a time of rapid technological change, traditional hiring practices — posting job openings, sifting through reams of resumés for relevant experience, making offers, and waiting for counteroffers — are falling short.  

“To stay competitive in the midst of widening IT skills shortages, enterprises must ensure a culture of continuous learning. All employees from entry- to C-level must have the drive and capability to keep learning, to keep stretching,” says Gina Smith, IDC research director, IT skills for digital business.   

Melissa Swift, vice president for workforce and organizational change acceleration at Capgemini Invent agrees. “You’re on a conveyor belt. Things move. If you take six months to hire someone, you might only have six months to use those treasured skills,” says Swift,  who counsels clients on how to rebuild their workforces to reengineer transformation.  

Like Srivastava, Swift asserts that the ability to learn is more valuable than what a person already knows. But finding a “learn-it-all” rather than a “know-it-all” is not a simple matter.  

“You have to be willing to tolerate a bit of non-linearity. When you don’t understand how they went from there to here [in their work history], that might be an indicator of learning agility,” she suggests.  

Trust Your Gut?  

Where seeming intangibles, such as curiosity, are concerned, you might think that gut instinct would play a large role. But, according to Swift, that can lead to bias when hiring managers gravitate to an applicant because they appear outwardly similar to a previously successful hire. When traits are difficult to measure, objectivity becomes more important. Swift recommends carefully evaluating for learning agility. “Look for a test that has been psychologically and statistically validated. It needs to have research-driven rigor,” she advises. 

Because the ability to solve business problems is the most desirable trait, Srivastava says interviewers should ask applicants direct questions like, “Tell me about three problems you ran into and how you solved them.” He says interviewers should seek affirmative answers to these questions: “Are you seeking insights from others? Are you interrogating data? Are you testing your own hypotheses or assumptions? Are you fundamentally reexamining your point of view?”  

Hidden Passions, Overlooked Winners 

Swift says unusual passions outside of work can be a tip-off to learning agility. “Are they into reading about Teddy Roosevelt? Do they like crochet or horseback riding?” She adds that some jobs, like sales and teaching, inculcate traits such as the ability to think positively and communicate clearly that pay off in many different fields.   

She also advises looking closely at a company’s current employees, some of whom may have the requisite learning agility but remain undiscovered because of the penchant of hiring managers to look outside for talent. “It’s the shiny object syndrome. Internal talent pools are chronically neglected,” says Swift.  

And internal employees who don’t call attention to themselves could be overlooked difference-makers. “Look for introverts; there is something in our culture that does not value introversion,” she says. In her experience, one woman was very introverted in meetings, but afterward would come up with ideas that were clearly “better and smarter” than what other team members offered.  

It’s Not About the Money  

There are cases in which hiring for potential can generate significant savings. Data science, for example, is an area in which experts are demanding, and getting, inflated salaries. “People are asking seven figures; however, you might be able to upskill people into those roles,” says Swift.  

While some might think that hiring for potential would save money compared with hiring the person with the longest resumé, Srivastava says cost savings are beside the point. “What is the opportunity cost of having the wrong person on the job? If you’re not going to be part of the new economy, you have already lost the game. I would change the metrics of how we measure success from the cost of compensation to the opportunity cost of missing the next wave.”  

Srivastava has learned the lessons of outside-the-box hiring from first-hand experience — his own. “I never went to school to become a CDO,” he says. Born in India, he studied aerospace engineering, then moved to the U.S. to take a sales job. However, he decided to become a technology entrepreneur, building several startups that were acquired.  

GenAI is a perfect example of a technology that seemingly came out of nowhere, he says, a harbinger of future transformational waves that will make today’s expertise obsolete. “The skills we will need for the future, we don’t know what they are,” says Srivastava. “Look at prompt engineering. Who knew we would have to hire for it?”  

Learn how three IT organizations are modernizing their skills and talent development practices.

Stanley B. Gibson - Adjunct Research Advisor - IDC

Stanley B. Gibson is an adjunct research advisor with IDC's IT Executive Programs (IEP), focusing on digital transformation, IT leadership, IoT, cybersecurity, and data management. An award-winning technology journalist and an experienced speaker at worldwide industry events, Gibson has been executive editor at eWEEK and PC Week, news editor at Communications Week, and software and systems editor at Computerworld. Gibson writes regularly for CIO, Tech Target, HPE enterprise.nxt, and Broadcom Community. Recent articles cover the convergence of IT and OT in industry 4.0, the rapid rise of industry-specific clouds, how to create a corporate culture for digital transformation, the "death" of IT infrastructure, the impact of COVID-19 on enterprise networks, the surprising endurance of the mainframe, the emergence of 5G networks, zero-trust cybersecurity strategies, and the impact of Amazon's sustainability initiatives.

The way businesses transact with one another is transforming. This presents an opportunity for vendors to develop innovative solutions that meet the needs of the modern B2B landscape.

The Emergence of a New Transaction Ecosystem

After decades of paper-based dominance, business-to-business (B2B) transactions are digitalizing and digitally transforming. e-Invoices and digital networks are streamlining accounts payable and receivable processes, enhancing efficiency and accuracy. Transactions are becoming enriched with data, especially to display sustainability-related information.

Spurred by new regulation, digital-first thinking, and good corporate governance, these developments are changing how businesses collaborate and transact with one another. Vendors have the opportunity to seize the moment and develop innovative solutions that meet the needs and requirements of today’s B2B landscape.

Transformation Drivers

What’s driving the transformation of business transactions? What is the future of the transaction?

Some 70% of businesses regard e-invoicing as an opportunity that goes beyond compliance and can unlock benefits like greater efficiency and faster payments.

According to IDC, regulations, digitalization, and sustainability are the three primary drivers of B2B transformation.

  • Regulation: The introduction of e-invoicing regulations is accelerating the shift toward digital processes in B2B interactions. European and global businesses will need to adopt new technologies and workflows to ensure compliance with current and future regulations. The EU is already mandating the use of e-invoicing in business-to-government (B2G) transactions through Directive 2014/55/EU. The directive aims to streamline public procurement processes, reduce administrative loads, and improve transparency. Countries like Italy and Hungary already require e-invoicing for B2B transactions. Other member states like Germany are steadily advancing their frameworks for eventual legislation. 
  • Digitalization: Digitalization is the process of converting analogue data into digital formats. Automation and AI tools are helping organizations digitalize and transform the way they handle external transactions, increasing the accuracy, speed, and real-time visibility of transactions.
  • Sustainability: The environmental impact of delivering products and services accumulates along the value chain. For most European organizations, much of the environmental impact of their products occurs upstream in their supply chains. European organizations are now beginning to record ESG (environmental, social, and governance) data associated with their purchases. Invoices will start to feature financial and ESG data, with ESG metrics specific to individual products.


“New transaction ecosystems will make B2B transactions faster, more secure, and efficient while enhancing transparency and compliance.”

Tom Seal, Senior Research Manager, IDC


IDC’s Recommendations

The digital transformation journey, while indeed complex, unlocks a future of frictionless information sharing between businesses. The transition to business networks presents a prime opportunity for vendors.

The Future of B2B Transactions is Digital

  • Organizations that share an increasing amount of data with their customers will require a new array of data from vendors to track sustainability performance.
  • Much of the new data that will be shared among organizations will follow the existing transaction pathway. However, this pathway must be updated to meet new demands.

Transactions Will be Data-Rich

  • e-Invoicing and other pressures will compel organizations to move beyond “paper thinking” during the 2020s.
  • A new transaction ecosystem will evolve, enabling organizations to build a transaction workflow that meets the needs of their industries, operations, and legislative requirements.

Network-Enabled

  • Future transactions will rarely be point to point. Rather, they will typically occur over a platform or network.
  • The future will be a network of networks, rather than an array of competing networks.

What It Means for Vendors

  1. Beyond complying with legislation, application vendors must develop strategies that help them thrive within the new transaction ecosystem.
  2. Application vendors have an opportunity to win the race to be the conduit for new data flows, capitalizing on the growth opportunities they represent.
  3. Every application vendor must think about their networks or network connectivity. Network access will be critical but equally commoditized. 

Conclusion

The new transaction ecosystem offers significant benefits, and organizations will increasingly rely on vendors to provide the necessary expertise and solutions to unlock these advantages. For tech vendors, the future of e-invoicing and B2B transactions is not just about compliance — it’s about leading digital transformation and setting new standards of efficiency and sustainability in the industry.

Watch out for Part 2 of our Blog Series on e-Invoicing in the coming weeks.


Ready to elevate your solutions and empower your teams? Contact us for a deeper dive on how IDC can help.

In the five-year span between 2016 and 2021, the average amount of data that organizations managed grew by 10 times, from 1.45PB in 2016 to 14.6PB in 2021. 

We are extremely adept at generating data, not so much at extracting value from those data, and very challenged to destroy any data at all. Data hoarding, data sprawl, and data decay are all significant problems for contemporary companies, and these issues can create legal liability risk and operational inefficiencies. Yet data minimization efforts tend to be difficult from the start, mainly due to the fear of deleting something that may be of value at some point in the future. 

The Data Problem 

An academic doctoral study released in 2020 included several statistics highlighting the fact that data generation has increased exponentially in recent years, with no signs of this trend stopping. Among those metrics was the estimate that globally we are generating around 2.5 exabytes of new data per day, as well as the prediction by the U.S. Government Accountability Office that by 2025 there will be between 25 and 50 billion devices connected to the internet and actively generating data. That same study reported that organizations effectively use less than 5% of their available data. There are three potential problems that could cause this situation: Companies don’t know how to analyze the data they have, they don’t know what insights they could gain by analyzing the data, or they simply don’t know that they have the data in the first place. 

One study found that nearly 85% of Fortune 500 organizations are unable to use their data effectively. Yet companies continue to store data in the hope that one day they might be able to analyze it appropriately and somehow extract insights from the “gold mine” of hoarded data they have accumulated. In thinking this way, they disregard the fact that most data have a shelf life that will reduce its viability before the company is able to extract valuable information from it. 

When data is not properly curated or updated, it becomes outdated, inconsistent, and potentially unreliable. Data hoarding exacerbates each of these issues — resulting in lower data quality and accuracy — as it becomes exponentially more difficult to maintain, clean, and manage data as it constantly grows within the enterprise over time. Given the recent regulatory focus on data privacy, much of this data are not only pure tech debt but also increase liability for the company. 

Analyzing rogue (incomplete, inaccurate, irrelevant, corrupt, incorrectly formatted, or duplicative) data is so problematic that the data science community says that a “rule of 10” applies to it. The rule states that it will cost 10 times more for a data scientist to complete a unit of work when the data is unclean compared with when the data is perfect.  

Why Do We Need to Be Concerned About Data Minimization? 

An IBM survey found that poor data quality costs the U.S. economy approximately $3.1 trillion annually and that companies are losing up to 12% of their potential revenue due to rogue data within their business processes. 

Storing unnecessary data can expose an organization to security and compliance risks and lead to compliance violations, especially under regulations like GDPR or CCPA. This is why these privacy laws have requirements for data minimization. According to the Colorado Privacy Act, the processing of personal data “shall be solely to the extent that the processing is necessary, reasonable, and proportionate to the specific purpose or purposes.” Similar verbiage exists in all other privacy laws. Regardless of where you do business, it is highly likely that at least one, if not many, of these laws apply to your business. 

What Is Data Minimization and How Is It Accomplished? 

At its foundation, data minimization means adherence to two basic principles: Only collect the data that you actually need to provide your services, and don’t keep data any longer than you need. 

To minimize your data, you should do the following:  

  • Evaluate your data storage processes and align data retention policies and practices with the principles outlined in the various privacy laws that your company is subject to. 
  • Implement data destruction policies and follow them. 
  • Use data classification and data discovery tools to scour your current data sets.  
  • Remove data that hasn’t been accessed for years and that you are storing for no valid business reason. 

Adhering to data minimization principles will not only help you remain in compliance with privacy laws, but it will also reduce your attack surface; improve your operational ability to analyze the information you do have; and improve your ability to make data-driven decisions based on current, clean, minimal data.