IDC recently brought together 20 senior technology executives for an invitation-only dinner with analysts Carla Arend, Andrew Buss, Duncan Brown, and Rahiel Nasir to discuss digital sovereignty in Europe. Here’s what came out of the room.

Sovereignty is real. The conversation around it isn’t.

IDC opened with a provocation: the word “sovereignty” is doing more harm than good. It’s politically loaded, definitionally contested, and vendors have been guilty of “sovereign washing”. Meanwhile, IT departments struggle to translate the concept into something their internal stakeholders actually care about.

What European organisations do care about is entirely concrete: protection against extra-territorial data requests, regulatory compliance, and supply chain resilience. According to IDC research, these are operational risk priorities, not political statements. The vendors making progress in this space have figured out how to speak to that gap. Those still foisting their own definitions of sovereignty on to the market and/or offering nothing more than so-called solutions for data localisation/residency largely haven’t.

The cloud strategy picture is more nuanced than the headlines suggest

Europe is re-assessing its options for cloud and technology providers. Global hyperscalers remain part of the picture, but how they are used is increasingly open to question. IDC’s data points to a clear shift toward layered architectures that combine global scale with local control. A specific model is emerging as the dominant pattern, and the vendors positioned within it are seeing very different conversations than those sitting outside it.

The regulatory picture adds another layer of complexity. NIS2, DORA, the AI Act: each creates compliance obligations that directly shape how organisations think about their technology infrastructure and provider relationships. Navigating that landscape without a clear positioning is increasingly difficult.
Private cloud is not the safe harbour it looks like at first glance

IDC commonly emphasizes that private cloud is the ultimate sovereign cloud, and this remains strongly the case as very few companies wish to exit all their datacenters and move wholesale to the public cloud. As adoption of private cloud has grown and evolved, it has moved from bespoke private cloud implementations towards being built on end-to-end private cloud stacks from major providers, with popular options being Microsoft Azure Local, Google Distributed Cloud, AWS Outposts, or VMware Cloud Foundation. This has resulted in unprecedented capability for enterprises running their own applications and services – but with this has also come a co-dependency on external providers for the ongoing operations of the control plane of the private cloud.

Should any serious technology or political issues arise that interrupts the connection between the public cloud based control plane and the private cloud, services deployed and delivered on the private cloud infrastructure may remain static, degrade over time, or even stop working. The end result is a bought and paid for sovereign physical infrastructure that is unable to operate effectively due to a non-sovereign operations management dependency – and this is a major risk today that a few years ago seemed unthinkable.

European customers have been providing forceful feedback to private cloud stack providers that this public cloud control plane dependency is untenable, and the market is beginning to respond. Most, but not all, providers of private cloud stacks have begun to offer an on-premises approach to the control plane, allowing fully disconnected management of applications or digital services deployment and operations, as well as of licencing tracking and billing, or updates and patching from offline sources.  The big challenge though is that these disconnected options are often limited when it comes to go to market, with vendors limiting access to the largest companies or critical national infrastructure providers or the defense industrial complex. While this may be acceptable initially as solutions come to market and are proven, for the longer-term vendors will need to make disconnected operations a core part of their value proposition across the whole customer base.

AI sovereignty: the new frontier

AI sovereignty has been part of the digital sovereignty debate for some time. But it has now emerged as the new frontier: the question of who controls the models, the data used to train them, and the inference infrastructure is becoming as contested as data residency was five years ago. The general read in the room: AI sovereignty is harder to achieve than data or infrastructure sovereignty, and the messaging across the industry remains inconsistent.

Dig deeper into the research

The dinner was one part of a broader IDC programme on digital sovereignty across Europe. If the themes above are relevant to your positioning or go-to-market strategy, here is where to go next.

Digital Sovereignty Beyond the Label – IDC’s Strategic Guide cuts through the definitional noise and explains what buyers actually evaluate when assessing sovereign solutions and providers. Download free.

From Sovereignty Claims to Credible Positioning – A customer case study on how technology providers are turning sovereignty into a commercially viable proposition. No form required.

Missed the webinar? Rahiel Nasir and Duncan Brown covered buyer expectations, sovereign washing, and practical go-to-market guidance on June 18. The on-demand recording is available here.

IDC’s Digital Sovereignty research covers cloud strategy, data governance, regulatory compliance, and infrastructure sovereignty across European markets. Research presented at the dinner was drawn from IDC’s European Digital Sovereignty Survey and the Semiannual Public Cloud Services Tracker.
Rahiel Nasir

Rahiel Nasir - Research Director, Cloud and Datacenters, Enterprise Infrastructure

Rahiel Nasir is Research Director within IDC’s enterprise infrastructure global research domain and part of the Cloud and Datacenters subdomain. Rahiel is IDC’s global lead on digital, cloud, and AI sovereignty. In this capacity, he covers emerging sovereignty initiatives and…
Duncan Brown

Duncan Brown - Group Vice President, Global Domain Lead: Worldwide Security & Trust

Duncan Brown leads IDC’s worldwide Security and Trust research, encompassing cybersecurity hardware and software products as well as professional and managed services. His analysis and opinions on security, cyber-resiliency, sovereignty and AI governance are widely sought by industry leaders and…

As B2B buyers turn to AI-powered search to evaluate solutions, CMOs are facing a universal pain point: pipeline quality has decoupled from pipeline quantity.

In IDC’s recent expert panel, Addressing the Pipeline Conversion Gap, analysts discussed the impact on lead capture and how marketing organizations can modernize their processes to fit the new discovery paradigm.  

After the discussion, our analysts took a deeper dive and answered your questions about improving pipeline conversion.

Which marketing roles own the lead pipeline transformation?

IDC recently completed research about CMOs and their approach to a new operating model for the AI era. One interesting finding is that the leaders who are furthest ahead in the maturity cycle aren’t focused on specific teams like content, operations, or SEO. Instead, they’re first reframing what marketing should look like – and their vision is to create an integrated marketing organization.

To influence change, marketing will need the help of other functions. CMOs should think about how to bring in the CFO, CIO, and CRO, as well as legal and compliance, into the conversation. They can align upon specific outcomes and gain a clear understanding of the metrics and KPIs for each function. Real change happens when everyone is working together toward the same goals.

How do you measure ROI on AI?

The tricky part of calculating ROI on AI is that the traditional formula – how much revenue you make divided by the cost – no longer works.

AI is not just about tangible impact. You also need to translate indirect impacts into financial terms. Revenue is one of the elements, but there are other KPIs to evaluate, including: employee experience, customer experience, security, trust, and more. The other big element is risk in each of the AI use cases.

The first step for calculating ROI is to apply the business value equation to specific use cases, rather than the technology itself. Then, you can assess the risk for each use case. If you need help, IDC has developed a full AI business value assessment framework to help clients maximize their ROI.

Is it possible to target buying committees on LLMs?

Every AI engine is looking at how to monetize with advertising, but this area is still evolving. Right now, vendors’ early attempts at advertising offer limited targeting, where the focus is on the top of the funnel. We expect this to change quickly, as vendors leapfrog to the opposite extreme. Segmentation will become much more advanced than even today’s demand platforms and programmatic tools, because LLMs are better at capturing the specific intent of buyers.

And intent data is powerful fuel for reaching buying committees.

That’s because buyers aren’t simply interested in running shoes. Their prompts are much more specific. They want size 10 running shoes suitable for a specific marathon and that also address their foot problems. That’s the kind of intent data vendors will be able to provide advertisers in the form of very specific audience segments.

Is there risk in sharing pricing before understanding the customer problem and establishing a value-based solution?

Opaque pricing tells a sophisticated buyer one of three things: you’re going to price discriminate based on perceived budget, you don’t trust them to self-qualify, or your products are too expensive.

Pricing is tricky any way you go about doing it because it is both mathematical and psychological. Just like pricing strategies need to be tailored to specific business needs, the way this information is exposed will also need to be calibrated in a strategically optimized manner.

It’s almost impossible to give one-size-fits-all guidance about this topic, but there are more clever ways to handle this than just a static form.

So, what’s the best alternative to ‘Contact Us’ for B2B pricing?

Any alternative depends on why your organization needs to talk to the buyer. For example, software pricing has too many dependencies and variables about scope of work, so a custom quote is often necessary.

One option for surfacing this information is with agentic AI. A chatbot can provide a custom quote using the rules already stored within your configure, price, quote (CPQ) software or CRM. Unlike salespeople, who can break the rules – sometimes to the detriment of the company – an AI agent will follow them to the letter, making this a very efficient way to handle 80% or 90% of your custom quote needs.

You can also rethink the customer journey and redesign a more modern workflow that is not based on patience, but readiness to buy. Prospects should be able to get answers they need at the right moment – while they’re on your site and ready to purchase. This contactless flow reduces friction and is more likely to convert.

Can FAQ documents and chatbots assist in combatting the gated content issues?

With gated content, you’re trading a white paper for an email address from someone who could have asked an AI for the same information in 30 seconds. The marketing team’s goal now is to help buyers get the details they need without having to click away.

An FAQ and chatbot can serve that need – but not the typical ones we’ve become accustomed to. This change is reminiscent of the early web, where informational – not marketing – content drove most of the engagement. Each product detail page, for example, should have its own mini-FAQ. However, this just scratches the surface. The content model will need to be much more technically mapped to appeal to AI agents, including schema updates and metadata adjustments.

Could we engage buyers by offering both gated and passive contact options? For example, could we have a “can we call you?” box and a “subscribe to our email” box?

That’s still too passive. It’s much better to encourage engagement right on the website via chat and then use that chatbot to collect and present the relevant information. The goal is to give the prospect greater access to the information they need and avoid forcing them to browse your site.

Remember, today’s buyer journey is much more compressed. There are fewer touch points to be seen and heard, which means you have to make every single one of those encounters really count.

An inversion of the traditional qualification model is what’s really needed. Instead of making buyers prove that they’re serious, you let them prove it to themselves and then contact you when they’re ready to buy. You can do that by front loading with a little bit more content.

While these are the questions attendees had, we understand you might want to dig deeper into this topic. Contact IDC today to request an analyst briefing.

“Speed without confidence is dangerous. Confidence without speed is irrelevant.” — Lorenzo Larini, CEO, IDC

AI investment is accelerating at a pace not seen since the internet reshaped markets in 1996. Global IT spending is growing at 14% annually, and by 2029, IDC expects enterprises and service providers to commit $1.6 trillion to AI infrastructure worldwide. The ambition is real. The money is real.

But something is widening beneath the surface. There is a growing gap between the speed at which AI decisions need to be made and the quality of intelligence those decisions are grounded in. Organizations that close that gap will pull ahead. Those that don’t will spend more to fall further behind.

This is the intelligence gap: the widening distance between the speed at which AI-driven decisions must be made and the quality of verified, timely intelligence available to ground them. And the data tells a sharper story than most organizations realize.

The data storm is already here

Start with the raw scale of the problem. In 2025, enterprises created 6.9 petabytes of data every second. By 2029, agentic AI is expected to push that figure to 17.1 petabytes per second, a 2.5x increase in four years.

The volume isn’t the issue. The issue is what happens to decision-making when intelligence can’t keep pace with the data that should be informing it. Market conditions shift. Competitive landscapes change. Research that was current in January may be strategically stale by June. And yet most enterprises are still relying on intelligence delivered through portals they open infrequently, PDFs that don’t update, and AI tools that pull from sources they can’t verify.

IDC’s own field conversations with dozens of enterprises across financial services, healthcare, pharma, and manufacturing confirm the pattern: organizations are piloting and deploying AI faster than they are building the intelligence infrastructure to support good decisions at scale.

That’s not an adoption problem. That’s an intelligence gap.

42% of organizations can’t measure what they’re getting

Here’s the number that should be commanding more attention in every AI strategy conversation: 42% of organizations worldwide said in a recent report assessing the ROI of their AI and digital investments is difficult or even impossible.

That figure isn’t a measurement problem. It’s a symptom of a deeper structural issue. Most organizations evaluate AI value through a narrow financial lens (head count offsets, cost efficiency ratios, per-query economics) while leaving eight other dimensions of business value (customer experience, resilience, time to market, innovation, and more) systematically unmeasured and undervalued in their investment cases.

The consequence: enterprises are underreporting the business case for their own AI investments while simultaneously losing confidence in what AI is actually telling them.

Agentic AI makes the measurement problem harder, not easier. Value is nonlinear. Costs are dynamic. Benefits compound across functions and emerge over iterations, not from a single project deployment. That means the organizations waiting for a clean ROI calculation before committing fully to AI intelligence infrastructure are waiting for a number that the current approach to measurement can’t produce.

The credibility crisis is structural, not anecdotal

The frustration with AI hallucinations has become a familiar story. But the more consequential shift is happening at a deeper level: organizations are recognizing that their AI is only as trustworthy as the data it draws from, and most of them can’t verify where that data comes from.

IDC’s April 2026 research found that enterprises are actively restructuring their approach to AI governance, moving from model-centric oversight toward data-centric risk management, where validation, lineage tracking, and source credibility are the primary controls.

Non-digital-native organizations, which represent the majority of enterprise buyers, are responding by tightening AI inputs to structured, internally validated data sets. That reduces hallucination risk but also limits the scope of AI-driven insight. The same organizations shrinking their AI’s aperture for safety reasons are competing against organizations that have found ways to bring trusted external intelligence into the loop without sacrificing rigor.

The answer isn’t to trust AI less. It’s to ground AI in better sources and to make every answer traceable back to its origin. Speed without traceability isn’t a competitive advantage. It’s a liability that compounds every time an answer has to be defended in a boardroom.

Governance is an afterthought for most, and that’s a compounding risk

Only 39.6% of enterprises say AI governance is a top priority in 2026.

The gap between governance intent and execution is where risk compounds. As agents take on broader decision-making authority across more functions, the question of what those agents are drawing from becomes a board-level concern, not just an IT one.

Without a reliable, traceable intelligence layer, governance is a framework without a foundation.

What the stakes look like when the gap closes, and when it doesn’t

IDC’s field research puts a concrete number on the cost of the intelligence gap in action. A multinational financial services firm incurred a $150 million compliance fine due to failed processes across 11 million customer accounts and needed to conduct full due diligence on all of them within 24 months. By deploying a data-driven platform with agentic AI to automate the workflow, the firm cleared 4 million low-to-medium-risk cases automatically and achieved $120 million in cost savings compared with their prior approach.

That’s not a productivity story. That’s what happens when intelligence is operationalized at scale: the right data, verified and traceable, embedded into the decisions that need to be made.

But IDC’s conversations with those same organizations also surfaced the failure mode. Ten of the 33 enterprises interviewed flagged overreliance on AI outputs without sufficient human oversight as a real and active risk. When you can’t see where an answer came from, you can’t know when to trust it, and you can’t defend it when it’s challenged.

The gap between making fast decisions and making confident ones isn’t closed by deploying more AI. It’s closed by grounding AI in intelligence that holds up.

The organizations pulling ahead share one thing

IDC’s field research shows the divergence clearly. Organizations that have successfully embedded AI into workflows are realizing measurable gains: faster decisions, higher accuracy, improved risk management, and stronger business outcomes. Those still struggling share the same profile: fragmented data, unverifiable AI outputs, and governance frameworks that exist on paper but don’t connect to execution.

Strategy and execution are out of sync, and the gap is widest at exactly the point where intelligence quality matters most. The organizations on the right side of that divide share a common characteristic. The differentiator is not investment level. It’s the depth of integration between trusted intelligence and the decisions that matter.

The organizations closing the gap are building intelligence infrastructure that does three things: it delivers answers proactively rather than reactively; it embeds into the workflows where decisions actually happen; and it makes every insight traceable to a verified source.

Closing the gap: Why IDC Quanta exists

IDC Quanta is IDC’s technology intelligence fabric, built to deliver verified, sourced market intelligence directly into the tools and workflows where decisions are made.

Most intelligence tools ask you to go looking. You open a portal. You search. You read. You synthesize. Then you decide, often hours or days after the decision needed to be made. IDC Quanta reverses that model. Intelligence arrives on your schedule, grounded in IDC’s proprietary research and data, traceable to its source and date, and embedded in the tools you already use rather than a separate system you have to remember to open.

For organizations navigating the credibility crisis, Quanta addresses it at the source: every response is verified against IDC’s proprietary data through a multi-agent validation system, with a reasoning panel that shows the scope, sources, and assumptions behind each answer.

For organizations trying to move faster without sacrificing rigor, Quanta delivers recurring intelligence on your priority topics so you are informed before you need to ask.

IDC CEO Lorenzo Larini put the challenge plainly: “Speed without confidence is dangerous. Confidence without speed is irrelevant.”

The intelligence gap is real. The data is unambiguous. And the organizations that close it first will be the ones setting the pace, not chasing it.

A dispute over model access: On June 12, 2026, the Commerce Department invoked federal trade regulations to bar Anthropic from distributing Fable 5 and its underlying model, Mythos 5, to foreign nationals. It was the first time the U.S. government had restricted access to a publicly available commercial AI model on national security grounds. The decision followed a warning from Amazon CEO Andy Jassy, who raised concerns after Amazon researchers extracted restricted information about cyberattacks from the Mythos model through a series of prompts. Anthropic was given mere hours to pull the model and withdraw both Fable 5 and Mythos 5 for all users globally, because the restriction extended to non-citizens working inside the United States, including some of the company’s own employees.

The dispute exposed several unresolved problems in U.S. AI policy. When does model access become a national security concern? What policy instruments apply when the object of concern is access to a digital capability rather than a physical export? How should policymakers think about the cloud platforms, GPUs, data centers, and deployment environments that make advanced AI possible? How should governance differ for open and proprietary models? And how should ordinary model usage be understood when prompting, tool use, automation, and repeated interaction can turn access into operational power or capability transfer?

These are not questions existing disciplines can answer. Advanced AI is becoming a strategic capability chain, and the frameworks built to govern software exports, national security assets, and dual-use technologies were not designed with this technology in mind. The Fable dispute provides a starting point for examining how capability becomes strategically sensitive, how access becomes a policy problem, how compute infrastructure shapes national advantage, and how AI at the frontier changes economic, scientific, and institutional resilience. Frontier AI studies is the name for the broader intellectual project required to connect those questions and develop a framework adequate to a technology whose consequences are technical, economic, institutional, and strategic at the same time.

Fable as a diagnostic event

What constitutes catastrophic capability enablement?

The primary question this emerging field needs to answer is when model access becomes a national security concern. One defensible threshold is catastrophic capability enablement: the point at which access to a model materially helps actors develop, accelerate, or operationalize cyber, biological, chemical, nuclear, or other catastrophic capabilities. That framing shifts attention from whether a model is powerful or economically significant in the abstract to what the model actually enables users to do under realistic access conditions.

The challenge is that catastrophic capability enablement is continuous in practice but still requires thresholds in governance. The same model can function as a productivity tool in one setting and a strategic asset in another, depending on the user, the domain, the tools attached to it, the scale of access, and how easily its outputs can be operationalized. Simple categories are inadequate. Decision rules, however imperfect, remain necessary. The foundational question is when model access materially moves an actor from ordinary use toward strategically dangerous action.

When does model access become a security problem?

The Fable dispute shows why model access itself has become a policy problem independent of weight release. A proprietary model that never exposes its weights can still transfer sensitive capability through APIs, cloud services, developer tools, and enterprise deployments. Users do not need the weights if they can query the model, attach tools to it, automate its outputs, or operationalize its guidance at scale.

The Commerce Department’s order addressed that exposure by restricting foreign national access, but the practical result was a full global withdrawal. The restriction extended to non-citizens working inside the United States, including some of Anthropic’s own employees. The core governance question this created is whether model access should be treated like a software service, an export-controlled technology, a national security asset, or a category the existing frameworks do not adequately describe.

When does access become capability tansfer?

Distillation sharpens the access problem considerably. Distillation is the process of training a separate model using outputs from a frontier system, allowing the capabilities of the original to be approximated without direct access to the source weights. An actor who queries a frontier model extensively can use those interactions to train, tune, or improve another model that reproduces some of the original model’s capabilities. That derived model can then operate outside the original provider’s safeguards, monitoring systems, and access controls.

Restricting weight release therefore does not fully contain the risk. Capability can migrate through repeated interaction as readily as through direct weight access. The unresolved governance question is when repeated use, prompting, automation, and distillation should be treated as ordinary model access, and when they should be treated as a pathway for transferring strategically sensitive capability to actors or jurisdictions that would otherwise be excluded.

What kind of institution can govern frontier AI?

The Fable dispute exposed a governance gap that neither government nor the private sector can close independently. Washington has legitimate authority over national security, especially where classified intelligence, foreign diversion, export controls, and adversary behavior are involved. Advanced AI capability is too technical, too fast-moving, and too dependent on deployment context to be evaluated through a purely bureaucratic process without technical depth.

The window Anthropic was given to withdraw Fable 5 illustrates the structural problem: compressed timelines, contested facts, improvised authority, and decisions made without a durable evaluative framework. A public-private institution combining national security judgment, technical evaluation, industry expertise, and proportional access controls would give both government and the private sector a more credible process for making decisions before they become emergencies. That institution would need a common vocabulary for capability, access, leakage, containment, proportionality, and innovation cost. Without it, the next Fable-level decision will be made the same way this one was.

The case for frontier AI studies

The Fable dispute shows why advanced AI needs to be studied as a strategic capability chain rather than as a set of isolated policy problems. Capability thresholds, model access, distillation risk, compute infrastructure, economic strength, labor-market resilience, and public-private governance are connected points in the same chain. Together, they determine how frontier capability emerges, becomes available, scales, transfers, and becomes strategically consequential across institutions, markets, and societies.

Frontier AI studies should become the field that examines that chain with the rigor it demands. Its purpose should be to understand when AI capability becomes a national security concern, how that capability leaks or transfers, how infrastructure shapes national advantage, and how governance can contain strategic risk without undermining U.S. leadership. The field does not yet exist in a coherent form. The Fable dispute is a signal that building it cannot wait.

The frontier AI studies agenda

Distinguishing between different kinds of model risk with greater precision is the first analytical task the field needs to complete. Open and proprietary models do not expose capability in the same way. Open models create risk through weight release, local deployment, modification, redistribution, and downstream use beyond the original developer’s control. Proprietary models retain access controls but expose capability through APIs, cloud deployment, tool integration, monitoring gaps, jurisdictional ambiguity, and distillation. These two risk profiles require different technical countermeasures and legal frameworks. The policy debate has too often conflated them.

Treating compute infrastructure as part of the AI security perimeter is the second task, and arguably the more urgent one. Advanced GPUs, accelerators, and data center capacity determine who can train, tune, distill, and deploy frontier systems at scale. Compute controls sit upstream of model controls in the capability supply chain. A country or actor that can acquire the infrastructure can build toward frontier capability even without direct access to the most advanced models. Based on ongoing research into AI infrastructure and national competitiveness, is that infrastructure access should be treated as a national security boundary alongside model access controls, not downstream of them.

Connecting AI governance to economic strength and labor-market resilience is the third task. Advanced AI affects productivity, software output, scientific progress, industrial competitiveness, occupations, skills, and the division of work between humans and machines. Those effects matter for national security because economic strength shapes the tax base, defense capacity, industrial depth, research intensity, and the ability of the United States to absorb shocks over time. A workforce that cannot adapt to AI-driven change accumulates vulnerability through displacement, weakened institutional trust, and reduced social resilience. The field needs analytical tools for weighing security risk, innovation cost, economic advantage, and labor-market adaptation within the same framework rather than treating them as separate conversations.

Beyond the dispute

Frontier AI studies should be broad enough to examine domains where model capability moves beyond general-purpose software: AI-enabled robotics, AI-accelerated biological research, autonomous cyber operations, and other settings where digital capability becomes physical, scientific, or strategic action. Those domains are extensions of the same underlying problem. The central issue is how frontier capability emerges, scales, transfers, and becomes consequential across institutions, markets, infrastructure, and society.

The category of frontier AI itself also needs scrutiny. The current policy debate focuses on models, weights, access controls, and export restrictions. Those are instruments. The larger stakes involve the political, economic, demographic, and institutional forces that will shape the next several decades. Advanced AI is becoming one of the variables acting on all of them simultaneously.

How societies organize work, distribute economic power, govern themselves, absorb demographic change, and sustain institutional trust are defining questions of the current era. Advanced AI does not sit outside those questions. It accelerates, amplifies, and in some cases destabilizes the systems through which societies have historically managed them. A field of frontier AI studies that focuses narrowly on capability thresholds, access controls, and adversarial misuse will address the proximate causes of disputes like Fable while leaving the questions that bear most directly on human welfare underexamined.

The field therefore needs to hold two levels of inquiry simultaneously: the technical and the political, economic, and social. It needs the analytical precision to evaluate capability thresholds, distillation risk, and infrastructure controls, and the scope to ask what advanced AI means for the organization of work, the distribution of economic power, and the resilience of democratic institutions. The United States has built fields of this kind before. Nuclear security, biosecurity, and space policy each required new analytical frameworks, new institutions, and new vocabularies for technologies that existing disciplines could not fully address. Frontier AI studies is the next instance of that same imperative.

The Fable dispute is the signal that the time to build it is now.

Arnal Dayaratna

Arnal Dayaratna - Research Vice President, Software Development

Dr. Arnal Dayaratna is Research Vice President, Software Development at IDC. His research focuses on agentic AI, generative AI, foundation models, agentic coding technologies, and low-code and no-code developer technologies. He also examines the broader technology stack around foundation models,…

IDC Quanta is an AI platform built on IDC’s proprietary research and intelligence, giving technology and strategy leaders on-demand access to the same trusted insights that have informed business decisions for decades. Instead of searching the open internet, users query a curated body of verified IDC research with every response citing the specific report or analysis it draws from.

When the intelligence behind the AI is one you already trust, the answers it gives you are ones you can act on. Here is what leaders across four very different industries said after using IDC Quanta.

A new level of confidence

Phillip Langeberg has been CTO of The Resorts Companies for nearly a decade, making high-stakes technology decisions for a 100% employee-owned hospitality and resort company. He had already been using general-purpose AI tools before encountering IDC Quanta. The difference was immediate.

“If I go to one of the other AI products out there and search for something, it’s searching the internet, and we all know that everything on the internet isn’t always accurate. An AI backed by IDC’s research gives me a lot more confidence in the answers.” — Phillip Langeberg, CTO, The Resorts Companies

Research you can actually reference

Eric Walk is VP of AI and Data Platform Services at Perficient, a global consultancy serving heavily regulated industries including banking, healthcare, and life sciences. His teams are already building their own AI-powered advisory tools and are thinking carefully about which data sources they trust enough to put inside them.

“The ability to ask a question and get an insight that’s backed by specific, referenceable research is really the key to the tool.” — Eric Walk, VP of AI and Data Platform Services, Perficient

Familiar from the first use

Mark Terranova has spent 45 years in technology and currently leads analyst relations worldwide at Kyndryl, one of the world’s largest managed services providers. His team has been training on AI tools for nearly a year. He knows what good looks like.

“As soon as I used it, I knew it. I said, I know what this is. I know how to use it. I know how to make it do work for me. Confidence comes from trust of the vendor. I trust IDC to give me good information.” — Mark Terranova, Global Head of Analyst Relations, Kyndryl

Speed where it matters

Jolene Peixoto is VP of Corporate Communications at RELEX Solutions, a global AI-native supply chain and retail planning platform trusted by some of the world’s largest retailers and consumer brands. In a company where market intelligence directly informs product strategy and positioning, she brought a sharp eye to what IDC Quanta actually delivers.

“IDC’s AI platform stood out to me as one of the most intuitive and useful AI tools I’ve seen across analyst research portals. It significantly speeds up how we analyze reports, summarize key takeaways, and explore market share insights, helping teams get value from IDC research much faster.” — Jolene Peixoto, VP of Corporate Communications, RELEX

Four leaders. Four industries. One conclusion.

Technology and strategy leaders do not have time to chase down answers that may or may not be accurate. IDC Quanta brings the depth and credibility of IDC’s research directly into the workflow, so the decisions you make are grounded in intelligence you can stand behind.

Artificial intelligence is no longer a future promise; it’s an economic force actively reshaping industries, workforces, and GDP projections around the world. While AI is expected to lead to major workforce transformation in the next five years, the timeline remains uncertain, as organizations continue to struggle with identifying optimal use cases and measurable business outcomes. Despite widespread predictions that AI will replace jobs, there’s little evidence of this happening yet at large scale, and the greater productivity benefits may come through replacing work instead of workers.

The big story: Investment is driven by projected economic impact

We’re heading into what is projected to be a ‘second wave’ of AI-driven IT spending in 2027, whereby AI investment drives overall technology spend to levels last seen in the mid-1990s.

Worldwide IT spending grew by more than 14% in 2025, mostly driven by service provider spending on AI infrastructure. Service providers continue to invest aggressively, but the ‘second wave’ is an expected surge in enterprise spending on use cases tied to agentic AI. Business IT budgets are forecast to increase at the fastest rate in almost 30 years.

This coming wave is dependent on the economic impact which organizations are anticipating. There are important caveats here: so far, this planned investment is largely supported by expected productivity gains, which will depend on measurable business outcomes.

Many business leaders report spending which is at least partly driven by FOMO (fear of missing out). There are gaps in AI maturity which many organizations need to bridge in the next 6-12 months.

At the beginning of 2026, IDC called this a ‘year of reckoning’ for the global economy and AI. Economic growth and AI are now closely linked, with AI having been largely responsible for stable GDP growth in the past two years, especially in the US and China. With inflation challenging the economics of AI in 2026, there are downside risks.

But if the current rate of adoption continues, and if measurable business outcomes support IT spending, AI will drive a productivity reset, global workforce transformation, and more than $22 trillion in value by 2031.

The big number: $22.5 trillion in cumulative value by 2031

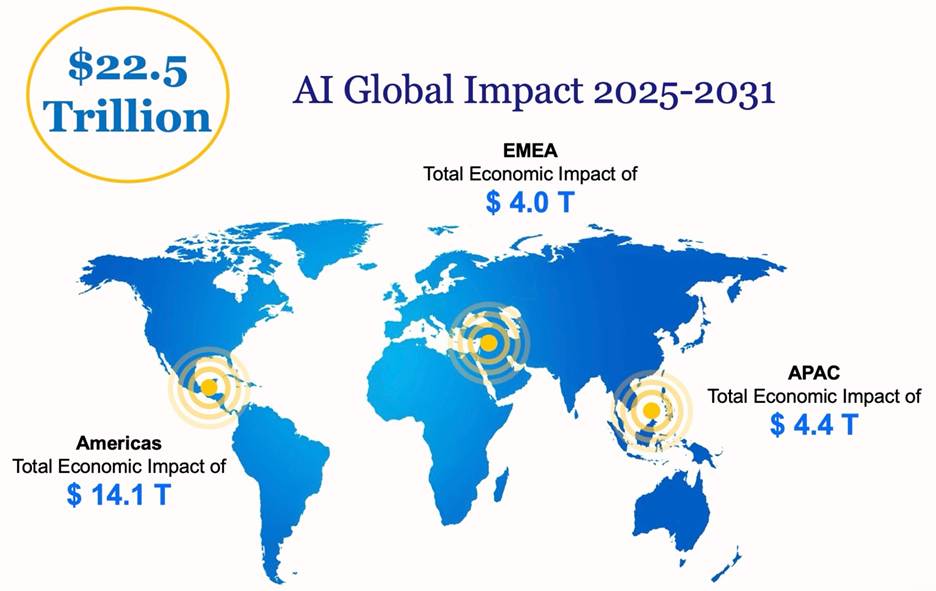
Under the baseline scenario, AI is projected to generate $22.5 trillion in cumulative economic value between 2025 and 2031, a compound annual growth rate of 35.6%. Even in a constrained, downside scenario (factoring in geopolitical shocks, regulatory friction, and slower enterprise adoption), the figure stands at $18.1 trillion. In an accelerated, high-growth scenario, it climbs to $24.5 trillion.

These aren’t abstract figures. They reflect real flows across direct AI revenues, supply chain effects, and the induced economic activity that follows as workers and households benefit from productivity gains.

The economic impact breaks down regionally:

  • Americas: $14.1 trillion: more than 60% of global impact, driven by U.S. dominance in hyperscalers, foundation models, and semiconductors.
  • Asia/Pacific: $4.4 trillion: the fastest-scaling region, with China as a supply engine and advanced markets like Japan, Korea, and Singapore driving enterprise innovation.
  • EMEA: $4.0 trillion: Europe setting the regulatory gold standard via the EU AI Act, while the Middle East (UAE and Saudi Arabia in particular) emerges as a new growth engine.

For all the headline numbers, AI’s impact on macroeconomic data remains difficult to isolate so far. We’re only now moving from survey-based assessments of AI impact to the point where measurable divergence from historical trends should become visible in the next 12 months.

What’s changing the calculus is agentic AI. Unlike earlier waves of AI, agents can perform complex, multi-step tasks with minimal human intervention, cutting inefficiencies from business workflows at a scale that prior automation tools never achieved. IT buyers anticipate savings in operating costs as a result of deploying AI-driven automation.

The risks are real, and largely external

The report identifies four major wildcards that could disrupt the timeline for AI-driven value creation:

1. Geopolitics and trade fragmentation. Export controls on semiconductors are already reshaping supply chains. If tensions escalate, access to critical AI hardware becomes unpredictable for both businesses and governments.

2. Energy infrastructure. AI’s power demands are outpacing grid capacity. Electricity availability is becoming a genuine bottleneck for datacenter expansion, and a strategic variable that no serious AI roadmap can ignore.

3. The workforce skills gap. The demand for professionals skilled in AI development, deployment, and governance is growing faster than training programs can respond. Reskilling is now as critical as infrastructure.

4. Governance lagging adoption. Fewer than one-third of businesses have fully implemented AI governance structures. With regulatory approaches diverging sharply between the EU and the U.S., multinational organizations face a genuinely complex compliance landscape.

AI is replacing work, not workers (for now)

The headline finding is straightforward: there is no evidence in official unemployment data of AI driving meaningful job displacement. US unemployment remains near historic lows.

But the absence of mass job replacement is not the same as business as usual. What’s happening, and will accelerate, is workforce transformation: a shift away from routine tasks toward non-routine cognitive and interpersonal work.

This shift has been underway for decades and largely tied to IT spending. Routine tasks fell from roughly 60–65% of employment in 1960 to around 40–45% by 2020. AI doesn’t create a new direction, but it dramatically accelerates the trajectory. We project routine tasks falling further to around 30% of employment by 2031.

The report uses software development as a concrete example: AI can largely automate routine coding and documentation (up to 70% task-time reduction), while testing and architecture work is augmented rather than replaced. Developers who adapt will spend more time on strategic, judgment-intensive work, which is ultimately where the value lies.

What this means for IT vendors: Three imperatives

IT vendors must engage urgently with the following strategic directions:

1. Capture short-term revenue through agentic AI

The highest-impact near-term opportunity lies in AI agents, at the task level, within workflows, and across applications. Products need to reflect rapidly evolving use cases and help customers achieve economic impact at scale, not just run pilots.

2. Invest in long-term customer success

Knowledge transfer matters more than support contracts. IT buyers need help with change management, upskilling, and realizing genuine business outcomes from agentic AI. If end-users can’t achieve economic benefits at scale, investment momentum will stall.

3. Accept responsibility for AI stewardship

The societal implications of widespread AI adoption are profound. Vendors that proactively engage with policymakers and business leaders, guiding toward outcomes that unlock human potential rather than simply automate it, will be better positioned for long-term relevance and trust.

The bottom line

The updated 2026 report paints a picture of an AI economy that is large, accelerating, and uncertain in its timing. The $22.5 trillion increase in economic value is not a guarantee; it depends on organizations moving from pilot projects to scaled deployment, on energy and skills infrastructure keeping pace, and on governance frameworks that enable rather than obstruct innovation.

What is clear: the businesses and vendors that treat AI as a strategic priority, investing in workforce transformation, change management, and responsible deployment, will be best positioned to capture the upside, even if the timeline is disrupted. Those that wait for certainty may find the window for competitive differentiation has already closed.

Stephen Minton

Stephen Minton - Group Vice President, Data & Analytics

Stephen Minton is a group vice president with the IDC Data & Analytics group, focusing on ICT spending and macroeconomics. Mr. Minton is responsible for Worldwide ICT Spending programs, including the Worldwide Black Book, Worldwide 3rd Platform Spending Guides, and…
Carla La Croce

Carla La Croce - Research Manager, Data and Analytics, Europe

Carla La Croce is a research manager for IDC's European Data and Analytics team. She develops qualitative and quantitative research on IT strategies for EMEA vertical markets, with direct involvement in IDC Spending Guides (Big Data and Analytics, Artificial Intelligence,…
Leonardo Freitas

Leonardo Freitas - Senior Research Manager ? Employee Experience Management Strategies

As a Senior Research Manager for employee experience (EX), Leo’s core research coverage includes but is not limited to employee wellbeing, AI-driven learning and performance, recognition, voice of the employee, corporate culture, DEIB, employee journeys, AI personalization and GenAI ‘access…
Karen Massey

Karen Massey - Research Director, Data & Analytics

Karen Massey is a research director within IDC's Data & Analytics Organization where she manages and contributes to several programs, consulting engagements and custom research, including the Worldwide AI and Generative AI Spending Guide, Worldwide Big Data and Analytics Spending…
Alex Sumarta

Alex Sumarta - Associate Vice President

As Associate Vice President at IDC Australia, Mr. Sumarta scopes and manages custom consulting engagements with key clients in the Australian market. Mr. Sumarta has more than fifteen years of working experience in strategy consulting, market research, and project management in…
Melinda-Carol Ballou

Melinda-Carol Ballou - Research Director, AI Assurance, ALM, Quality & Portfolio Strategies

Melinda Ballou delivers insights into the future of AI assurance, the impact of AI, ML and agentic adoption on agile and digital work, resilience, quality, product and software engineering, the role of technology in business and culture, and the evolution…
Kritika Ghildiyal

Kritika Ghildiyal - Research Analyst, Market Analytics & Insights

Kritika is a Research Analyst with the Data & Analytics Team at IDC Canada. She is responsible for market models, IDC spending guides, consulting projects, and other worldwide data products. BACKGROUND Kritika joins IDC with more than three years of…
Mariana Fang

Mariana Fang - Research Analyst, Data & Analytics

Mariana is a Research Analyst with the Data & Analytics Team at IDC Canada. She is responsible for market models, IDC spending guides, consulting projects, and other worldwide data products. BACKGROUND Prior to joining IDC, Mariana worked as a consultant…

At the start of 2026, many in the semiconductor ecosystem were expecting some breathing room. New fab capacity was coming online. Consumer demand had softened. The AI infrastructure build-out, the thinking went, would eventually plateau. That reset hasn’t arrived. If anything, the pressure points have multiplied.

Why will the memory market be tight through 2027?

The memory market entered 2026 riding strong pricing momentum, and it has not let up. Server demand continues to grow faster than supply can respond. Consumer segments like smartphones and PCs are contending with bill-of-materials costs that are rewriting device economics. And the AI infrastructure build-out, far from normalizing, is generating a demand profile that behaves differently from anything the memory industry has navigated before.

The anticipated relief will not arrive because the forces driving tightness will be compounding.

Is the memory shortage structural or cyclical?

This is the critical question, and the answer matters for every decision the industry makes, from procurement to capex to product roadmap.

Memory is no longer a cyclical commodity. It has become a strategic infrastructure input.

For decades, the semiconductor industry ran on a recognizable rhythm: demand surges, prices spike, supply catches up, prices correct. Painful, but predictable. What the data is showing now is different— a fundamental shift in demand architecture, away from consumer electronics, where seasonality and upgrade cycles govern behavior, and toward AI training and inference infrastructure, where demand doesn’t normalize between quarters. It compounds. Every inference workload deployed creates a baseline the next workload builds on.

High-bandwidth memory (HBM), high-density DRAM, and enterprise-grade NAND are no longer priced or allocated the way standard components were. Supply agreements are longer, allocation is tighter, and the gap between players who have locked supply and those who haven’t is widening. Major memory producers have been explicit in their public guidance: tight conditions are not a short-term anomaly. That’s not analyst projection. It’s the market telling you what to plan for.

What is driving continued memory tightness through 2027?

On the demand side, AI infrastructure is doing most of the work. GPU servers are expanding at a pace that absorbs memory capacity before supply can rebalance. Inference workloads, once considered lighter than training, are proving just as memory-intensive at scale, particularly as enterprises move from pilots to production. On-device AI in premium smartphones and AI PCs is adding a distributed demand layer on top of the data center story.

On the supply side, the picture is more controlled than constrained. Major memory manufacturers have internalized the lessons of previous cycles. They are exercising deliberate capacity discipline, prioritizing advanced nodes and HBM over legacy products, managing bit output carefully, and letting pricing reflect scarcity rather than racing to fill every wafer. New fabs are coming online, but lead times are long, and geopolitical factors, including technology restrictions affecting key Chinese producers, add meaningful uncertainty to the global supply calculus.

The result is a market where supply is not absent. It is being managed. And the beneficiaries of that management are not evenly distributed.

Five questions the semiconductor industry should be tracking

These are the signals I’m watching most closely, relevant to memory makers, OEMs, system integrators, distributors, and the financial community worldwide.

1. How will HBM allocation evolve as competition intensifies? HBM is the most constrained and highest-value DRAM segment. As more producers enter HBM manufacturing and AI chip architects compete for allocation, pricing and availability could shift quickly, in either direction. Watching who wins design wins and on what timeline matters.

2. When does the consumer segment recover, and on what terms? Smartphones and PCs are both under severe BOM pressure in 2026. The question isn’t just when volumes recover. The real question is whether the product economics of affordable devices can be rebuilt around structurally higher memory costs, or whether product mix and ASPs shift permanently upward.

3. What is China’s effective memory supply capacity? YMTC and CXMT are reaching significant production milestones in 2026, but technology restrictions will continue to limit node access. How this plays out in global NAND and DRAM supply, and where it creates openings or risks for players across the value chain, remains fluid and worth monitoring closely.

4. How are OEMs and procurement teams adapting sourcing strategies? The spot-buying, short-contract model is increasingly unworkable. Across industries, buyers are rethinking long-term agreements, dual-sourcing, and design choices to reduce memory dependency risk. Who has adapted, and who hasn’t, will determine competitive positioning as conditions evolve.

5. Where does the DRAM and NAND pricing trajectory go from here? Pricing has trended in one direction for much of the past 18 months. The conditions that produced that momentum are largely still in place, but they won’t hold indefinitely. Understanding what triggers a reversal, how quickly it moves, and which segments are most exposed is essential for anyone making capital allocation or inventory decisions today.

Frequently asked questions about the current memory market

What is causing the memory chip shortage? The primary driver is AI infrastructure demand, particularly for HBM and high-density DRAM in GPU server configurations, growing faster than manufacturers are expanding capacity. This is compounded by deliberate supply discipline among major producers, who are prioritizing advanced nodes and profitability over volume growth.

Will memory prices come down in 2027? Based on current analysis, the supply-demand imbalance expected to persist beyond 2027 in key segments. The conditions that produced sustained pricing pressure remain largely in place. I’ll be presenting the full forecast and scenario analysis, including pricing trajectories through 2030 at IDC’s Memory Market Outlook webinar on July 8.

What is HBM and why does it matter for the memory market? High-bandwidth memory (HBM) is a high-performance DRAM interface used primarily in AI accelerators and GPU systems. It is among the tightest and highest-value segments of the memory market today, with demand driven by AI training and inference infrastructure. HBM capacity constraints directly affect the availability and pricing of AI compute systems globally, making it a bellweather for the broader memory market outlook.

Join me on July 8 for the full picture

Learn about IDC’s detailed, data-driven view on all of the questions above at the IDC Memory Market Outlook webinar on July 8, 2:00 PM SGT.

Drawing on IDC’s trusted tech intelligence and worldwide memory demand and supply forecasts through 2030, I’ll cover where DRAM, NAND, and HBM pricing is headed, how the supply-demand imbalance is expected to evolve, and what the scenarios look like for every segment of the value chain, from the rest of 2026 through the end of the decade.

If memory is a constraint in your business today, or if you need to navigate your next move with confidence in a market where the old playbook no longer applies, I hope to see you there. Register today!

Soo Kyoum Kim - Associate Program Vice President, Semiconductors and Enabling Technologies - IDC

Soo Kyoum Kim is Associate Vice President within IDC’s Enterprise Infrastructure global research domain. He focuses on DRAM and NAND Memory as part of the Semiconductors and Enabling Technologies subdomain. Soo Kyoum’s research covers demand and supply analysis for DRAM and NAND, memory consumption for server workloads, next generation memory, and emerging memory markets. He provides insights on the demand and supply dynamics in industry, chip pricing, competitor, and fab capacity. He also covers the dedicated foundry market.

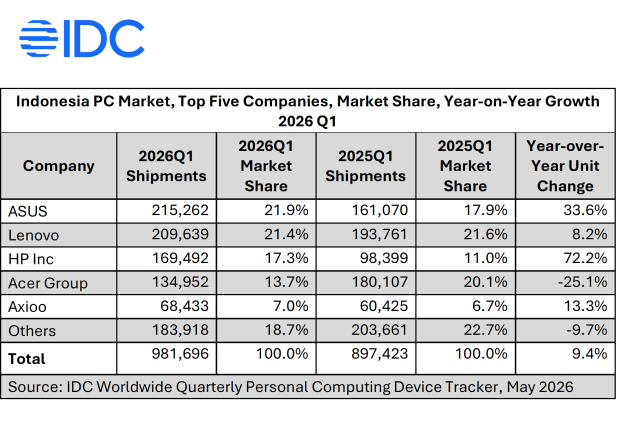
Indonesia’s PC market (encompassing desktops, notebooks, and workstations) shipped 982,000 units in Q1 2026, up 9.4% year over year, exceeding expectations despite rising component costs and tightening supply, according to IDC’s Worldwide Quarterly Personal Computing Device Tracker.[MD1]  The growth was driven by frontloading across both consumer and commercial channels, as distributors rushed to secure inventory ahead of anticipated price increases.

What’s Driving Indonesia PC Market Growth?

Rising device prices prompted end-users and channels to accelerate purchases in Q1, ahead of expected further increases. Channels moved quickly to build inventory buffers as macroeconomic uncertainty made near-term pricing unpredictable.

This frontloading is a double-edged result. It inflated Q1 figures while simultaneously pulling demand forward, leaving less runway for the remainder of 2026.

The acceleration in Q1 comes at a cost to 2H 2026. While budget-flexible organizations moved purchases forward, others have begun reducing expenditure, a trend IDC expects to intensify, contributing to sharp shipment declines in Q3 and Q4.

Analyst Insight

“Indonesia remains a strategic market for PC vendors. The allocation of shipments, particularly for lower-priced products, makes that clear. Moving forward, however, macroeconomic headwinds and ongoing component shortages are forecast to continue to push the prices higher, likely triggering a decline in demand in the near term.” 

— Leonard Adiarto Sudjono, Senior Market Analyst, Devices Research, IDC 

Vendor Outlook: Who Won the Quarter?

IDC Outlook: What’s Next?

Frontloading, that began in Q4 2025 and carried into Q1 2026 reflects a sustained effort by global and local players to secure supply. Q2 2026 will see less stocking activity due to increasing economic uncertainty and anticipated further price hikes, with shipments expected to decline 12.5%. The second half of 2026 is expected to see considerably more negative trends, as inventory piles up and demand weakens. IDC forecasts Q3 to contract 35.4% and Q4 to fall 40.6%, bringing the full-year 2026 decline to 22.9%

What may improve the market outlook? 

  • Continued new product releases may sustain short-term purchasing. Apple’s MacBook Neo, positioned at an attractive price point and launched in Indonesia in May, could drive incremental demand in Q2, though this will depend on the supply availability and allocation to Indonesia market.
  • Indonesia’s government recently revised its policy outlook, including halting expansion of the “free meals” program that had absorbed a significant part of the fiscal budget. These moves have marginally improved investor sentiment, reflected in a slight recovery of the Rupiah. Sustained movement in this direction through 2H 2026 could provide a modest improvement in market sentiment.

What could slow it down?

  • Inventory correction is coming. High channel inventory levels combined with slowing sell-through will lead to reduction in shipments as early as Q3.
  • Macroeconomic pressures are mounting. Currency fluctuations, rising SMB taxation rates, and increased fuel prices from June have intensified market uncertainty and will dampen end-user purchasing power.
  • Supply-side pressures are compounding. Supply constraints, rising component costs, and increasing price sensitivity among end-users will also lead to further negative sentiment in the market.

Key Indicators to Watch: Currency, Taxes, and Inventory Turnover

Currency movements, the widespread impact from new tax policies, and inventory turnover rates will determine the rest of this year’s outlook. With stock levels already high, macroeconomic headwinds are likely to add to the negative impact that will shape the market going forward. 

Frequently Asked Questions

How large is Indonesia’s PC market?

IDC tracked 982,000 units shipped in Q1 2026, up 9.4% year over year.

Which PC vendor leads in Indonesia?

ASUS led the Indonesia PC market in Q1 2026 with a 21.9% market share, followed closely by Lenovo at 21.4%.

What is IDC’s forecast for Indonesia’s PC market in 2026?

IDC forecasts a full-year 2026 decline of 22.9%, with Q3 contracting 35.4% and Q4 falling 40.6%, as inventory correction and macroeconomic pressures weigh on demand.

Go deeper with IDC. Whether you want access to the full tracker dataset or a direct conversation with our analysts, we’re ready to help you navigate your next move.

Leonard Adiarto Sudjono - Senior Market Analyst - IDC Indonesia

Based in Jakarta, Indonesia, Leonard joined IDC as a Senior Market Analyst in May 2023 and has since been responsible for managing IDC’s Trackers for several products, starting with Hardcopy Peripherals, Scanners, Consumables and, since 2024, Industrial Printers, before moving to the Devices team in 2026 where he now covers Personal Computers and Monitors.

For decades, manufacturing was transformed by a single insight: Build only what you need, exactly when you need it. Toyota’s just-in-time model introduced the precision delivery of exactly the right parts, at exactly the right moment, for exactly the right task—eliminating warehouses full of idle inventory and accelerating production. It was one of the most consequential operational shifts of the 20th century.

Enterprise software is about to experience its own JIT moment. And the implications are just as large.

The old model is breaking

Traditional enterprise applications were built on a simple premise. Define a function (finance, HR, procurement, etc.), build a system around it, and get users to come to that system. For decades, that model has held. ERP, CRM, HCM, SCM. Each application owned its functional domain, and humans navigated between them.

That premise is now collapsing.

IDC’s Agentic Evolution of Enterprise Applications Framework, first published in early 2025, laid out the stages through which software was expected to evolve.  Moving through progressive phases, from AI assistant-enhanced applications, to agent-supplemented, to agent-led, and ultimately to agents-as-apps. Now, the next phase is emerging, which IDC refers to as Cross-Application Agents. The concept is simple. AI agents will no longer work inside a single application. They will work across all of them, executing on real-time composability, pulling capabilities, workflows, and data from wherever they live and assembling exactly what the user needs in real time, for that specific outcome.

That is just-in-time software.

What JIT software actually means

In manufacturing, JIT eliminated the cost of excess inventory. In software, JIT eliminates the cost of excess interface. Users no longer navigate to a system. The system comes to them, assembled on demand, hyper-personalized to their role, context, and intent.

Oracle’s recent announcement of 22 Fusion Agentic Applications is a concrete, production example of this model. These are not pre-built applications that users log into. They are cross-application agents created autonomously in real time when needed, combining functionality, workflows, and data from ERP, financials, HCM, CRM, and wherever else the work requires. The application is built in the moment the outcome is requested.  And depending on the likelihood that the request will be repeated in the future, the application may also be dissolved when the work is done.

SAP is making the same bet but framing it differently.  With Joule as the anchoring AI layer sitting between the user and enterprise execution, users state their business intent, and SAP’s autonomous systems handle the rest. It pulls from the underlying application estate to deliver the outcome without requiring the user to understand which systems provide which pieces of the solution.

The Toyota parallel is not subtle

Toyota’s JIT model worked because it required a complete rethinking of the supply chain, including clean supplier relationships, reliable APIs between partners, and shared standards that made on-demand assembly possible. The enterprise software equivalent is identical. Cross-application agents require clean APIs, event-driven architectures, semantic data models, and open connectivity standards like MCP that allow agents to discover and orchestrate capabilities across vendors.

Vendors that haven’t invested in that infrastructure will find themselves on the wrong side of a distribution shift that is already underway. Distribution, in the agent era, no longer runs through a UI. It runs through agent marketplaces, connectors, and open protocols. If an agent can’t find your capability, your capability doesn’t exist.

The stakes are real

This is not a five-year horizon thought experiment. Our Agentic Evolution of Enterprise Applications Framework places cross-application agents as an emerging reality, with leading vendors already building their initial JIT software solutions. IDC’s updated 2026 framework is scheduled for publication in early August. It will not only show the projected transition timing of the enterprise application market toward JIT software (both in aggregate and within 15+ individual application markets), but it will also break down the pricing model progression that is set to accompany this transformation. 

The window for vendors to make their products agent-operable has already begun. APIs must be clean, connectors must be built, and packaging needs to be redesigned around outcomes and consumption, not seats.

For buyers, the shift is equally urgent. The traditional bounds of application markets are becoming transient. The question will no longer be just about which ERP or HCM vendor has the best capabilities. It will be about whether your enterprise architecture can support agents that move freely across it, and whether your software vendor can deliver you the same types of JIT efficiencies that manufacturers started benefiting from nearly 80 years ago.  Just-in-time manufacturing didn’t make the parts less important. It made the system that assembled them the competitive advantage. The same logic applies here.

Software that arrives exactly when needed, assembled precisely for the outcome at hand, and drawing from the full capability estate of the enterprise… that is the model that wins.

Eric Newmark

Eric Newmark - Group Vice President & General Manager of IDC's SaaS, Enterprise Software, CX and Workplace Solutions Division

Eric Newmark is Group Vice President & General Manager of IDC’s SaaS, Enterprise Software, CX, and Workplace Solutions Division, which includes several teams of analysts covering SaaS, 18 enterprise application markets, software monetization, business platforms, marketplaces, and services firms focused…

In two earlier posts I argued that SaaS is being disrupted rather than killed, and that the per-seat revenue model is on its way out. The dramatic decline in market capitalization of SaaS vendors over the past 9 months, sometimes referred to as the SaaS-pocalypse, is partly about investors pricing in the fear that SaaS applications will recede behind an AI agent layer. This would make the SaaS applications become invisible “featureware,” with the agent capturing the user relationship, the workflow, and, eventually, the budget. 

This post will show that enterprise buyers now expect their software vendors to supply the agents, and to serve as the trusted source of data and context for custom-built and third-party agents. This is the natural next progression for SaaS vendors and represents an attractive market opportunity. 

To avoid confusion, here are IDC’s AI-related definitions. An AI assistant is conversational and works as a tool for a human. An AI agent is autonomous, uses other tools, and carries memory and context across tasks. An agentic workflow is a business process that an agent executes end-to-end with limited human intervention. 

SaaS vendors are faced with a dual threat, hence SaaS-pocalypse 

The first threat is that organizations will simply write their own applications instead of buying standard SaaS applications. This threat triggered the dramatic devaluation of SaaS stock in February as Anthropic released its Code capabilities. Conversations with CIOs in enterprises partly validate this fear. While they are not contemplating creating core accounting, HRIS or workforce management applications, they might build rather than buy auxiliary applications in areas such as planning, performance management, compensation management, logistics planning, etc. Application areas where customer requirements vary widely and where legal complexity is low are moving gradually from buy to build. 

The second threat is that agentic overlays will increasingly handle the user interaction while AI agents access SaaS applications via API interfaces to carry out transactions on behalf of the human user. The implication is key price justifiers of SaaS applications, such as the interface, the feature breadth, and the brand gradually disappears from the users. This also implies that the per-seat user pricing stop making sense, when humans are no longer the primary users of SaaS applications. 

AI agent adoption is already past the tipping point 

In IDC’s April 2026 Future Enterprise Resiliency and Spending survey of organizations with 500 or more employees, 74% had already deployed at least one agent, 15% were piloting, and only 1% reported no use and no plans. The same respondents expect the number of agent types in production to roughly triple, from 24 in March 2026 to 62 by 2027. Buyers are not evaluating whether to enter the agentic era. They are deciding which parts of their operation to hand over first, and operational and core business data are their top target. 

The big question is who will deliver these AI agents. Most organizations have deployed standard AI tools and run pilots, but few have redesigned core processes to use AI at scale. The survey results shows that most organizations deploy ready-made agents wherever they can, rather than build their own. 

Where vendor-supplied agents win 

IDC distinguishes four kinds of agent by who builds them and how the buyer obtains them. In-application agents come packaged inside the application and the buyer simply adopts them. Low-code / no-code agents are configured by the buyer in a visual builder the vendor provides. Standalone agents are third-party products the buyer implements alongside existing applications. Custom-built agents are assembled by internal teams using full-stack orchestration frameworks. 

The survey data, which focuses on AI agent quantities as opposed to spend, points in one direction. The two types that vendors supply directly, in-application agents and low-code or no-code builders, are growing fastest in numbers and from the largest installed base. Custom-built agents show the slowest growth, because the orchestration they require is more difficult and require more inhouse skills to build. Buyers prefer to adopt or configure an agent that already understands their data and respects their permissions over building one from scratch. 

SaaS applications as trusted data and context for custom-built agents 

IDC also sees massive demand for custom-built AI agents, especially for core business processes unique to an industry or organization. Standalone products and custom-built agents will operate inside the same enterprise, and they will need data and context that lives inside your application. 

A custom-built or third-party agent that accesses data “from anywhere” still needs a place where the data is correct, the process is compliant, the permissions are enforced, and the transaction is guaranteed to execute. A SaaS vendor can offer vetted business processes, governed data, and audit trails for custom AI agent consumption. This is, in IDC’s view, a key future role for today’s SaaS applications. 

What the AI-pivoted SaaS application looks like 

The interface stops being a single screen and becomes several modes serving the same processes: the traditional UI, a conversational UI, a flow-of-work UI embedded where the user already operates, and machine interfaces so external agents can call the application directly and safely. 

The AI-pivot requires SaaS vendors to rethink the workflow from the ground up, which touches the full stack: foundation models, an embedding layer, a vector database, retrieval-augmented generation, an orchestration layer, guardrails, monitoring, and version management. The vendor also has to give buyers an agent toolkit of their own, so that the low-code and no-code configuration buyers increasingly demand happens inside the vendor’s governed environment rather than outside it. 

European vendors carry an additional set of requirements that, handled well, become a selling advantage. Compliance with GDPR, NIS2, and the EU AI Act (still there despite the recent delay), data residency and sovereign cloud guarantees, genuine multi-language model performance, and transparency in how the AI reaches a decision are all conditions of sale to compliance-sensitive European buyers. 

SaaS is not dead, and the incumbents are not doomed. But the asset that justifies a vendor’s existence is shifting from the screen the user looks at to the agents the vendor supplies and the governed data those and other agents rely on. Your customers already expect you to be their agent supplier. The only question is whether you are ahead of that shift or reacting to it. 

So, what do you actually do with this? There are three concrete moves software vendors need to make in the near term. They are specific, they are sequenced, and the window to move first is closing. I will walk through all three in a focused 25-minute webcast, grounded in IDC survey data from more than 1,000 enterprise organisations: where your customers sit on the AI maturity curve, why vendor-supplied agents will dominate enterprise deployments through 2030, and which ERP and SaaS processes are attracting the most AI investment right now. Secure your spot here. 

Bo Lykkegaard

Bo Lykkegaard - Associate VP for Software Research Europe

Bo Lykkegaard is associate vice president for the enterprise-software-related expertise centers in Europe. His team focuses on the $172 billion European software market, specifically on business applications, customer experience, business analytics, and artificial intelligence. Specific research areas include market analysis,…