Sometime in the next planning cycle, someone will ask you a question with no comfortable answer. Could you justify a double-digit increase in AI infrastructure spending to your board, and would your sovereignty audit back you up?

For a growing number of enterprises, the question is already live. IDC FutureScape 2027, IDC’s annual set of top technology predictions, places three decisions in the closing window, where the big decisions are nearly made and an opportunity is about to become a disadvantage. One of them: IDC predicts that by 2027, 45% of G2000 organizations will justify exactly that kind of increase.

The clock behind them is the first prediction in the Top 10. IDC predicts that by 2029, 60% of enterprises will run a majority of their business processes AI-first, up from 13% in 2026. AI-first means AI agents are the default starting point for how work gets done, with humans assisting and providing oversight. It is not full autonomy: IDC expects supervised autonomy, with defined escalation thresholds, to be the standard operating model for agents by 2028, so the tipping point is a governance event as much as a technology one.

Missed the webinar? Watch all ten worldwide predictions in the webinar replay.

That puts a short fuse on the calls you make now. The architecture decisions in this planning cycle are the ones you will be judged on in 18 months, and IDC predicts that by 2029, 40% of G2000 CIOs will be measured on AI unit economics.

This post extends our launch blog, IDC FutureScape 2027: The Great Rewrite Comes With Deadlines, which introduced the closing, open, and emerging windows. IDC’s Rick Villars, who presented the webinar, said the main task in the closing window is rethinking resilience, at the business level as well as the technology level. Each decision gets a section below, with clips from the live webinar. The open and emerging windows get their own posts next.

The bill: how is techflation changing AI infrastructure budgets?

Villars told webinar viewers that IDC research found over 62% of organizations saw double-digit price increases on their latest purchases in the prior three months. Software and services are starting to follow networking, storage, and processors. IDC calls this techflation: the sustained rise in technology costs driven by demand for processors, memory, and datacenter power and cooling that supply cannot match.

The techflation prediction turns that pressure into a budget decision. By 2027, IDC expects 45% of G2000 organizations to justify double-digit increases in AI infrastructure CAPEX, driven by data security and sovereignty compliance demands and by the expectation that hardware costs stay high. The bill is also getting harder to read: IDC predicts 55% of enterprises will see agentic bills rise with no published price change by the end of 2027, up from 20% today. For a CFO, that makes a baselined case, with cost and outcome measured before you commit, the price of entry.

Could you justify a double-digit CAPEX increase to your board this year, and would your sovereignty audit support it?

Organizations embedding AI into core processes will deploy more infrastructure in their own facilities, Villars said, and they are going to need to “get back into the CAPEX business.” IDC’s advice to CFOs: fund AI factories like warehouses, not incremental budgets, with multiyear committed spending plans before December 2027.

Start with an audit of security and data residency needs, within six months, so the commitment is sized to your requirements, and put legal, compliance, IT, and finance behind one sovereignty case. The multiyear hardware agreement follows, with price protection and with review and exit terms written in before you sign. CAPEX procurement cycles run longer than cloud activation, so start early, then recalibrate as costs and regulation move.

CAPEX is one answer to techflation, and sourcing is another. IDC predicts that by 2028, 50% of G2000 enterprises will adopt GPU-as-a-service over self-built infrastructure. Waiting carries a cost as well: IDC’s analysis of the macro drivers finds that delayed investment gets more expensive as costs rise.

Owners: the CIO and CFO lead, with the CTO sizing the architecture. A useful measure is IT spend as a share of revenue against your peers.

The exit: why are open models part of the cost answer?

Hardware is only half of the cost story; the other half is the model you run on it. By 2028, IDC expects enterprises to shift 60% of AI workloads from proprietary LLMs toward open-source models, using model routing (sending each workload to the model that best fits its needs) to reduce costs and hedge against vendor lock-in. This 60% counts workloads, while the AI-first figure above counts enterprises. IDC’s guidance projects AI operating costs falling 30% to 50% by 2028. Treat that as a projection that depends on routing working well, and net it against the skills and support costs the same guidance names.

Lock-in is the second driver. IDC’s FutureScape on sovereignty and regulations finds that 84% of enterprises rate freedom from AI vendor lock-in as important and that 38.8% already report switching costs and contractual lock-in. It projects that 48% of enterprises will run open source AI models in production by 2029, up from 30% today. Villars tied the two points together: cost predictability and flexibility belong in the same planning conversation, and model routing is part of how you control agent costs. IDC’s guidance is to balance lock-in against time to value, since flexibility has a setup cost.

Our read: open models are a negotiating position before they are a cost line.

A workload you can redeploy elsewhere changes your next renewal conversation. The harder part is the operating model. The guidance calls for routing that matches workloads on latency, accuracy, and cost, containerized multi-model capacity, and governance extended to open-source vulnerabilities and data residency. Procurement has to learn to evaluate open communities and support tiers, and IDC’s sovereignty research says model-serving and orchestration frameworks such as vLLM, Ray, and Kubernetes-based tooling need to be budgeted and staffed as a named 2027 item.

Owners: the CTO leads the routing architecture, with the CIO owning vendor terms and a named owner for agent knowledge standards. A useful measure is cost-to-value per workload, before and after a workload moves.

The factory: what does it take to treat the software factory as critical infrastructure?

The third decision starts with an image from IDC’s Katie Norton, who leads research on DevSecOps and software supply chain security. Picture a production line. “Every application a company ships inherits the trust of that factory,” she told webinar viewers, so a contaminated line makes everything it produced suspect and can force something like a recall.

In this prediction, the software factory means the pipelines, tools, plugins, and agents that create, build, and deliver code. IDC predicts that by 2028, 50% of large enterprises will treat those systems as critical infrastructure. AI changes the picture in two ways. It produces more code than human reviewers can absorb, and agents now take part in the factory themselves, opening pull requests, calling tools, and holding identities with access to build systems. Norton describes two ways a software factory can fail: it stops, which blocks fixes from shipping, or it is compromised, which means its output cannot be trusted. She sees the most urgency in connected products such as vehicles and medical devices, where an attacker could “ship a malicious update signed with the manufacturer’s own keys and every device will accept that as authentic.”

The risk is recognized. IDC’s DevSecOps and Software Supply Chain Security Survey from July 2026 found that 54.7% of U.S. organizations rate their business risk exposure from internally developed applications and the software supply chain as high or very high. Buyers are starting to act: IDC predicts that by 2029, 40% of critical infrastructure operators will make verified code origin and supplier control conditions of software procurement. Most still govern delivery systems as engineering productivity tools, a priority that made sense before AI multiplied the code and the agents in the pipeline.

Could you still ship a fix tomorrow if your build system were compromised or offline?

Norton’s starting advice for 2027 budgets has three steps, and the first sounds simple: “You can’t secure what you can’t see.” Inventory every pipeline, tool, plugin, and agent with access. Most organizations she talks to cannot produce that map today, so name an owner and a deadline. Add the factory to business continuity planning using the question above, and put third-party delivery tools under supplier risk management. On the budget side, she suggests consolidating delivery environments onto fewer, centrally managed platforms. Our read: consolidation concentrates risk in fewer, larger platforms, which is why the inventory comes first.

Owners: the CISO and CTO lead, with the CIO sponsoring the budget. A useful measure is the time it takes to ship a fix with the primary build system offline.

Before the window shuts: what should tech leaders do first?

Each decision has a first move that fits inside one planning cycle, and a gate that tells you when to take the next step.

  • AI infrastructure budget: audit security and data residency requirements and map sovereignty rules, then size a multiyear commitment from the result, with price protection plus review and exit terms. Recalibrate as costs and regulation move.

  • Open models: pilot routing on one workload class picked from an audit of migration candidates, and measure latency, accuracy, and cost before you fund the platform and skills at scale. Name an owner for agent knowledge standards now.

  • Software factory: inventory everything with build access and answer the ship-a-fix question before you decide on consolidation.

Villars closed the webinar with three priorities for the 2027 planning cycle: governance for agents and data, flexibility that makes cost more predictable, and leadership that can trust AI. The closing window decisions sit under the second and touch the first.

Want more FutureScape? Visit our dedicated website for FutureScape predictions, past and present.

What signals should you watch as the window closes?

Forecasts move as conditions move, so keep a short watch list. Start with memory pricing: IDC’s dedicated private cloud research expects memory prices to start easing in the second half of 2028. If supply loosens sooner or quotes soften at your next two purchases, revisit the terms of a price-protected contract, which is why review and exit terms belong in it. For open models, watch whether support tiers and communities mature, since routing savings grow with them. For the software factory, watch your inventory: consolidate delivery platforms once everything with build access is mapped.

Your IDC contacts are the fastest way to stay ahead of these signals. Ask your IDC account team to connect you with the analysts behind these predictions, and check in each quarter on what is shifting in pricing, supply, and adoption, so you can tell a blip from a change that should move your plan.

Where can you go deeper?

IDC Quanta lets you see the research behind a prediction alongside the follow-up questions it raises.

Explore the FutureScape 2027 reports at idc.com/futurescape.
Ryan Smith - Content Marketing Director - IDC

Ryan Smith is the Director of Content Marketing at IDC, where he leads brand-level content and social media strategy, aligning research insights with compelling storytelling to engage technology decision-makers. With a background in both IT and marketing, Ryan brings a unique blend of technical understanding and creative strategy to his work. He’s also a seasoned storyteller, speaker, and podcast host who believes the right message, told the right way, can drive both trust and transformation.

过去半年,生成式AI已经带来巨大变革:代码生成成为软件工程的标配环节,内容生产从“AI辅助”走向“人机协作”,智能客服、数据分析、营销创意等场景的渗透率快速攀升。随着企业需求从”试用尝鲜”转向”生产级部署”,承接大模型能力的主流公有云服务形态——MaaS,正成为云计算市场中最具确定性的增长方向。

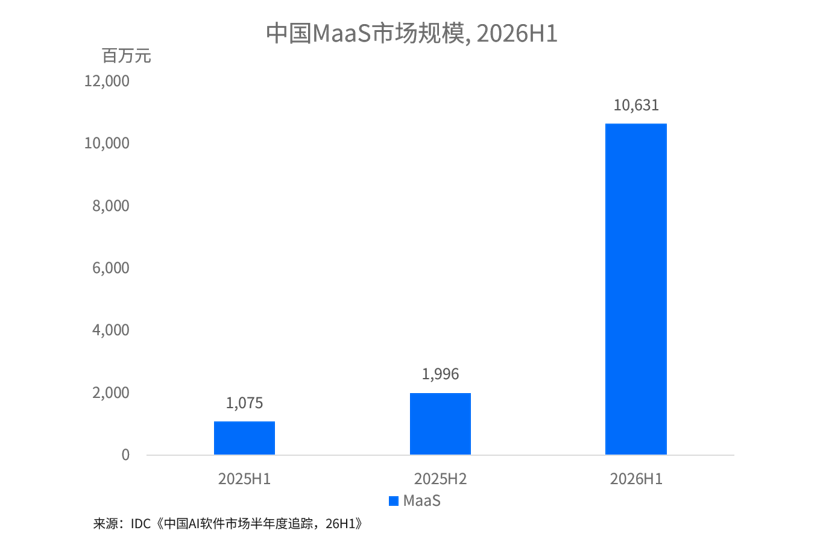
国际数据公司(IDC)于近日发布的《中国AI软件市场半年度追踪,26H1》报告显示,2026H1中国MaaS市场规模达到106.3亿元人民币,占中国公有云PaaS市场的比重从2025年下半年的5.2%升至21.0%,开始对既有市场格局带来颠覆性影响。

IDC认为,对于行业用户而言,MaaS已经从可选项成为业务标配。对于技术厂商而言,MaaS也正在成为不容失手的增长主阵地。

2026H1,中国MaaS市场规模及Token调用量呈现爆发式增长

2026上半年,中国MaaS市场延续并放大了2025年以来的高增长态势。按营收口径统计,市场规模达到106.3亿元人民币,同比增长889.4%。这一增速意味着市场在一年内扩张至近9倍体量,MaaS正式迈入百亿级赛道。

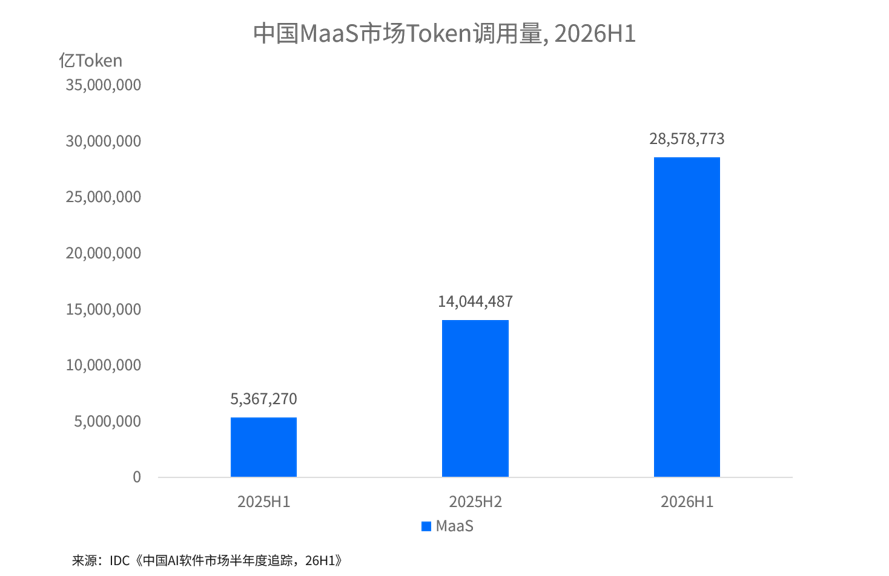
按调用量口径统计,2026H1全市场Token消耗量达到2,857.9万亿,同比增长约432.5%。

增长背后:模型升级、场景放量、模态扩容

·       模型迭代——旗舰升维、Flash 达标,行业渗透加速,用户盘持续扩大。​ 供给侧看,2026 上半年模型能力与成本两道门槛同步下降。旗舰层面,Qwen3.5 ,GLM-5.2等模型在推理、编程与智能体能力上持续升级,长上下文普遍迈入百万级,大模型得以进入更多行业的核心业务环节——从“辅助办公”走向“直接承担生产任务”;普惠层面,各家 Flash/轻量版本达到可用门槛,让原本对成本高度敏感的行业第一次具备了规模化调用模型的经济性。大模型的用户盘从互联网等先行行业,扩展至金融、零售、制造、政务等更广泛的行业腹地。

·       场景挖深——大并发筑底盘,三类场景接力放量。​ 互联网自身业务中的推荐系统、搜索、对话、Coding 等大并发场景,仍构成 MaaS 收入的底盘,贡献稳定。同时增量来自于三类接力场景:一是日常办公加速普及,既包括各行业的办公流程自动化,也包括以金融投研报告撰写为代表的内容生成场景;二是智能客服向更多行业渗透,其中电商与贸易企业尤为突出;三是智能终端助手、IT 自动运维等新型场景相继接入大模型。这些场景渗透率尚低、业务链条长,对更长上下文与更强推理能力的要求,使单任务调用量与客单价同步上升,正在接棒成为 MaaS 收入增长的主要来源。

·      模态扩容——视频生成模型成为MaaS市场重要第二增长曲线。​视频生成模型在上半年跨过商业化拐点:以 Seedance 2.0 为代表的新一代模型将 15 秒视频的可用率大幅提升,短剧、广告、电商内容等生产环节开始批量引入。这一趋势直接重塑了 MaaS 的市场结构:2026H1,在整体 MaaS 规模中,大语言模型占比为 47.0%,而视频生成模型调用产生的收入贡献已达 32.7%,其余“其他模态模型”占 20.2%。视频模态已实质性地成为拉动 MaaS 增长的第二极。

MaaS 已成为必争之地,各类型玩家加速涌入:

在这一背景下,2026 年各类型厂商依托自身禀赋加速涌入 MaaS 市场:

短短半年间,MaaS 在中国公有云 PaaS 市场中的份额从5.2%升至21.0%,开始对既有市场格局产生颠覆性影响。对云厂商和模型厂商而言,MaaS 已不再是云业务中的“可选项”:它既是未来几年最重要的增量来源,也直接决定下一轮云市场竞争的话语权分配——不参与,就意味着在云计算的核心地带缺席。

  • 云厂商以算力资源、完善的模型矩阵与成熟的工具链为底座,将模型服务全面纳入云产品体系,以“模型 + 算力 + 工具链”的整体方案锁定企业级市场;
  • 大模型公司凭借技术领先与快速迭代建立品牌心智,以密集的新品发布与激进定价切入企业客户,并以订阅制与生态合作将模型优势转化为平台流量;
  • 大模型推理服务商则聚焦多模型聚合与极致性价比,以推理效率和开放性卡位“多模型时代”的流量入口,承接来自头部模型的溢出需求;
  • 运营商携全国性算力布局与深厚的政企渠道资源进场,形成第四股不可忽视的力量。

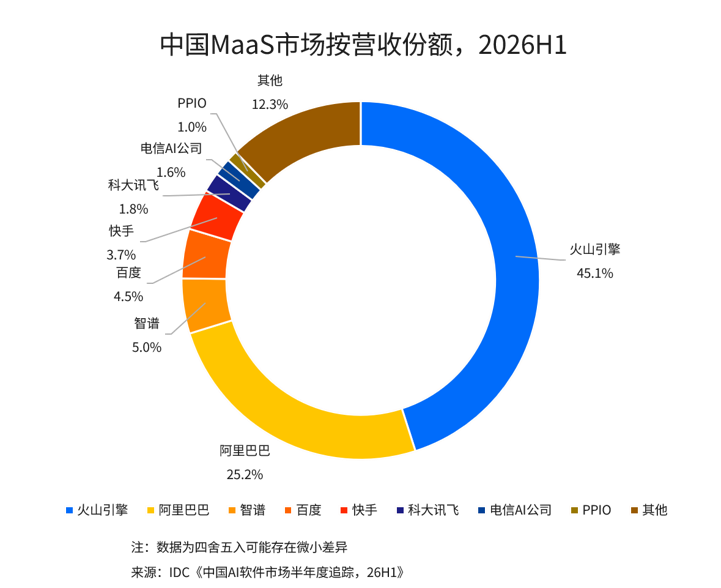
模型发布、API 降价、开源开放与算力扩容在上半年密集上演,市场竞争的烈度显著升级。凭借各自的基因优势,2026上半年,火山引擎、阿里巴巴、智谱、百度等厂商取得了优势与主要市场份额。

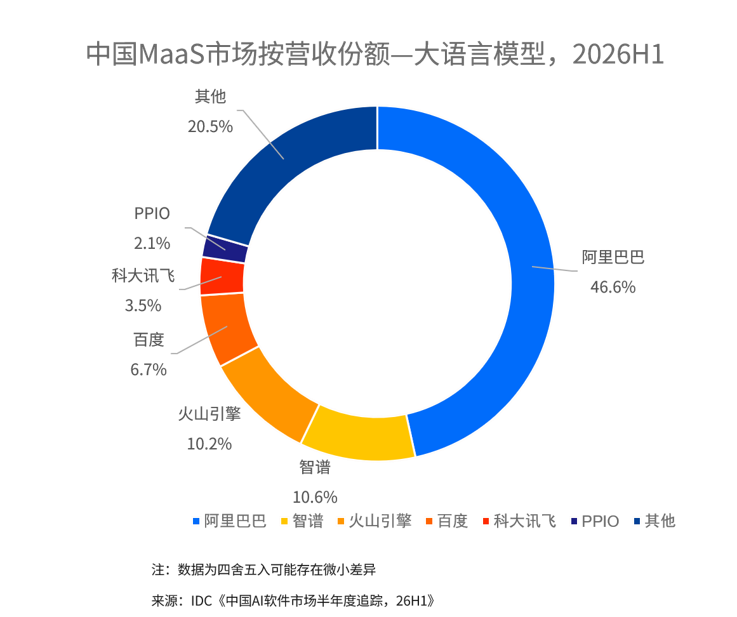
与此同时,大语言模型仍是主要模态。技术成熟度更高、推理成本下降更快,叠加当前企业侧需求(知识问答、代码生成、Agent 编排)大多以文本为中心,共同支撑了大语言模型在调用量与营收上的绝对主导地位。也正因如此,模态内部的竞争最为激烈,阿里巴巴、智谱、火山引擎、百度等厂商构成了大语言模型市场的主要竞争力量。

模型、推理效率构建短期壁垒,算力是长期核心护城河

MaaS 的市场前景得到数据验证,参与者类型快速扩容,竞争节奏明显加快。IDC认为,MaaS厂商的竞争要素可以分两个时间维度看:

短期看,模型能力与推理效率是最直接的抓手。一方面,旗舰模型的升级仍是获客的第一杠杆,模型的效果、迭代节奏与模型矩阵的完整度,直接决定平台流量;另一方面,在模型能力趋同的区间,推理效率成为决定性价比的关键——推理框架优化、PD分离与大规模集群调度能力,决定了厂商在同等算力下可对外供给的有效Token吞吐,也决定了价格战的底气。这一阶段的竞争本质是”效率战”。

长期看,算力是难以绕开的核心护城河:算力的获取规模、单位成本/算力性价比、异构适配能力与供应链确定性,构成了厂商最难被复制的能力。模型能力可以通过人才与资本追赶,工具链可以通过投入补齐,但大规模、低成本、可持续的算力底座需要长期资本开支与供应链关系的积累。可以预见,随着Token消耗量级继续攀升,算力话语权将向头部进一步集中,缺乏算力自主性的厂商将被迫向”轻资产模型授权+生态合作”模式迁移。

大模型平台私有化市场同步放量

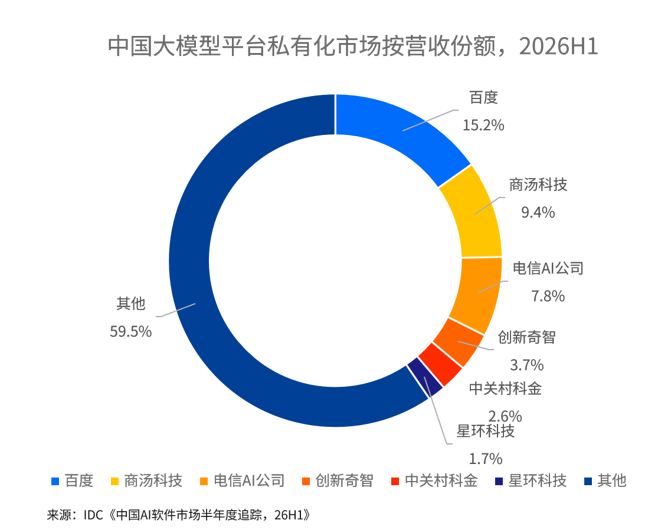
与 MaaS 公有云并行,大模型私有化部署市场同步进入放量期。​ 2026 H1,大模型私有化部署市场规模达到 28.8亿元,同比增长 108.4%。需求主要来自政府、制造、能源、金融等行业,驱动逻辑正从“IT 设施建设”转向“生产环境落地”:客户的关注点也从单点模型能力转向平台的完整能力——数据安全、业务定制、自主可控与信创适配缺一不可,工程化交付与长期运维成为项目成败的关键;同时更看重对业务的支持效果,以业务指标而非模型榜单衡量投入产出。“应用+模型”一体机等形态加速交付,头部客户多期复购显现,市场正从单点试点走向规模化复制。

未来展望

MaaS市场在视频生成和通用智能体/日常办公推动下,持续高速增长。一方面,视频生成尚处于商业化放量初期,随着单次生成时长向 30 秒量级突破、可用率持续爬升,广告、短剧、电商等有真实预算的需求将源源不断转化为收入,成为增长弹性最大的板块;另一方面,日常办公等场景仍处于渗透早中期,调用量与客单价均有充足的上行空间。

商业模式加速多元化:从“资源生意”到“价值分成”。

  • 与市场规模的扩张同步,MaaS 厂商的变现方式也在快速多元化。标准 API 按量计费仍是最主流的模式;在此之外,以 Coding Plan 为代表的订阅制套餐、预定资源、按效果付费、合作分润等模式在 2026 上半年快速起量,收入结构呈现“按量付费为主、多元模式加速渗透”的格局。
  • 商业模式创新的意义不止于收入本身,更在于客户关系的重构:按量计费以低门槛赢得“入口”,订阅制与预定资源以承诺消费沉淀“确定性”,按效果付费与分润模式则试图把 MaaS 从“资源生意”升级为“价值分成生意”——厂商的收入第一次与企业客户的业务成果直接挂钩。
  • 展望未来 18 个月,商业模式将加速向“价值锚定”演进:与业务成果挂钩的计费方式有望从探索走向主流,厂商与客户的利益绑定日益加深,多元模式的收入占比也将持续提升。

增长换挡:从存量挖潜到增量开拓。国内市场,Coding 等先发大并发场景的渗透已趋近饱和,继续在存量盘子里“内卷式挖潜”,边际收益正在递减。厂商需要把增长引擎切换到两个方向:一是转化“还没进场”的客户,比如金融、医疗、政务以及大型企业的核心业务系统,它们并非没有需求,而是此前不敢用、不便用;利用专有云推理、数据不出域等方案,将这部分客户转化为 MaaS 用户盘的下一批增量,是厂商获得增速的潜在机会;二是向海外要增量,海外市场对高性价比推理服务的需求旺盛、订阅付费习惯成熟,且 API 定价与毛利空间普遍高于国内,正成为头部厂商收入结构中的新变量。

分析师观点

IDC中国高级分析师洪婉婷表示,2026 上半年是中国 MaaS 市场的重要分水岭。模型升级、场景扩容与视频生成三股力量共同驱动市场爆发式增长。短短半年,市场规模突破百亿,在公有云市场中的占比显著提升,其重要性不言而喻。往前看,市场将从‘跑马圈地’进入‘价值经营’阶段:短期,模型效率与推理成本决定入场资格;长期,算力与体系化能力决定厂商能否持续交付高质量、可信赖、可计价的服务,而这将最终决定利润池的归属。

进一步交流

如希望就《中国AI软件市场半年度追踪,26H1》定义、厂商份额及采购评估框架进一步交流,欢迎与我们联系。请点击此处与我们联系。

Catherine Hong

Catherine Hong - Senior Market Analyst

Ms. Catherine Hong is served as the role of Senior Market Analyst in Emerging Technology sector for IDC China, and her main responsibility is conducting analysis and research for the China Blockchain market. She is also in support of regional…

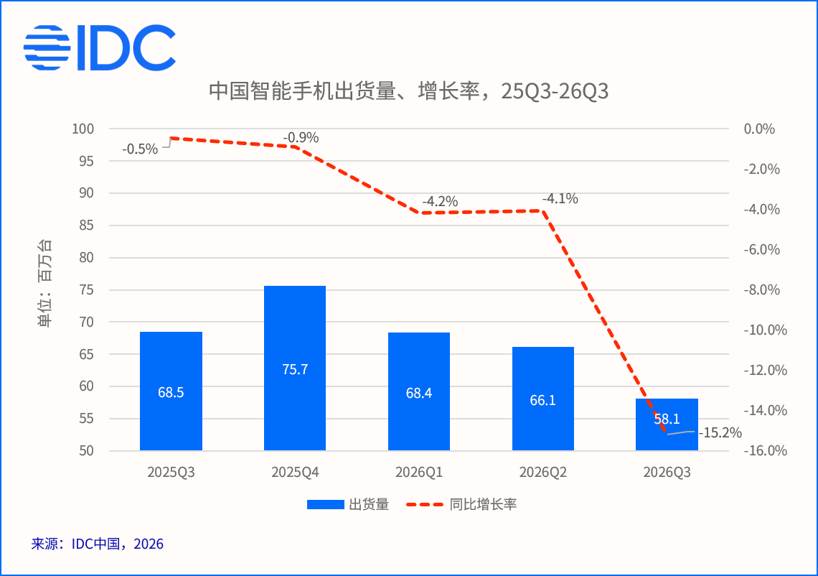
国际数据公司(IDC)最新手机季度跟踪报告数据显示, 2026年第三季度中国智能手机市场出货量约为5,806万台,同比下降15.2%。相较上半年约4%的同比降幅,下半年整体市场规模下滑速度进一步加快。存储及其他元器件成本大幅上升所引发的终端价格上涨与产品配置方案调整,已开始明显抑制消费需求,其中安卓厂商与长尾品牌承受的压力尤为突出。

本季度市场呈现“量跌价升”的典型特征。上游成本压力持续向终端传导,导致新品定价普遍上浮,同时厂商不得不调整产品配置组合以平衡成本。消费者面对价格上涨仍需时间适应,换机周期进一步拉长,直接拖累整体出货表现。这一趋势表明,成本压力已成为当前影响中国智能手机市场走势的关键变量。

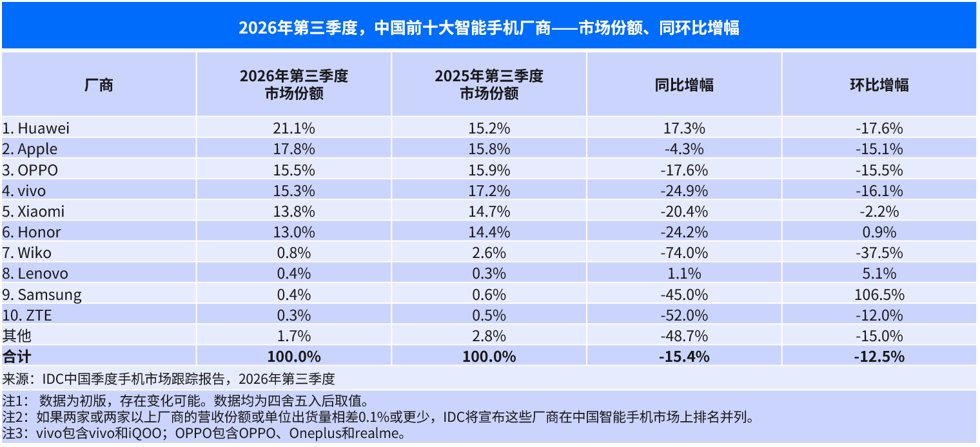
厂商格局:华为份额升至21.1%,荣耀环比微增

在整体低迷的背景下,华为凭借多样化的产品形态与相对克制的售价涨幅,延续了今年以来的强势表现,出货量实现同比两位数增长。苹果新品发布后市场欢迎度超出预期,但由于今年机型数量减少,出货量同比小幅下滑。其它中国头部品牌虽面临较大挑战,但依然展现出各自相应的承压能力。

OPPO连续四个季度稳居市场出货量前三。在 600 美元以上高端市场,Find X10登顶今年新旗舰产品标准版机型销量榜首,助力 OPPO 该价位段出货连续三个季度实现三位数同比增长。400-600 美元中高端市场,Reno 16 系列凭借均衡产品力与渠道深耕,稳居该价位段安卓单品销量第一,构成 OPPO 销量基本盘的核心支撑。子品牌一加是唯一自 2025 年至今年第三季度持续保持出货量同比正增长的品牌,为整体产品矩阵补充差异化增长动能。依托中端稳住大盘、高端持续突破、多价位段精准覆盖的产品布局,OPPO 在行业成本承压、需求放缓的周期中,展现出稳固的市场基本盘与可持续的市场抗风险能力。

vivo继续凭借稳健的产品竞争力保持稳定市场表现。历经多代产品迭代持续深耕移动影像赛道,vivo已建立起扎实的用户口碑与市场认知,全新旗舰X500系列进一步夯实高端影像旗舰的市场地位。子品牌iQOO精准瞄准年轻电竞人群,旗舰iQOO 15系列持续热销,新款iQOO 16上市后亦受到市场欢迎。主品牌和子品牌共同助力vivo在600美元以上高端市场位居安卓阵营第一。中端市场,S60系列市场表现好于上一代产品,帮助vivo位列400—600美元价位段第一,巩固销量基本盘。高端市场上影像与性能双线差异化突围使vivo在行业周期波动中展现出更强的经营韧性与市场竞争力。

Xiaomi重返折叠屏市场后,国产安卓首款阔折叠产品小米18 Fold凭借差异化形态与产品力快速打开市场,助力小米重返折叠屏市场第三;叠加全新旗舰小米18 Pro系列上市,推动小米在1000美元以上安卓市场份额位列第一。在行业上游成本高企、多数厂商收缩入门产品线的背景下,小米持续坚守普惠型市场,在 100 美元以下价位段保持市场首位,有效覆盖预算敏感型用户群体,稳固了整体销量基本盘。高端突破与普惠覆盖并行,形成差异化产品合力,使小米在成本压力与需求疲软环境中保持市场竞争力。

Honor成为本季度头部主流厂商中唯一实现出货量环比正增长的品牌,反弹态势清晰。全新 Magic 9 系列是今年新上市主流新旗舰中,唯一实现首销销量较上一代显著增长的产品。国庆假期期间持续稳居安卓旗舰销量榜首,成为高端市场增长的核心拉动力。中端市场,X80 Pro Max 系列上市后快速起量,登顶 200-400 美元价格段单品销量第一;多价格段、多产品线差异化协同发力、旗舰新品突破增量帮助荣耀在行业调整期展现出强于同业的抗风险能力与复苏动能。

价格体系:中低端市场份额持续收缩

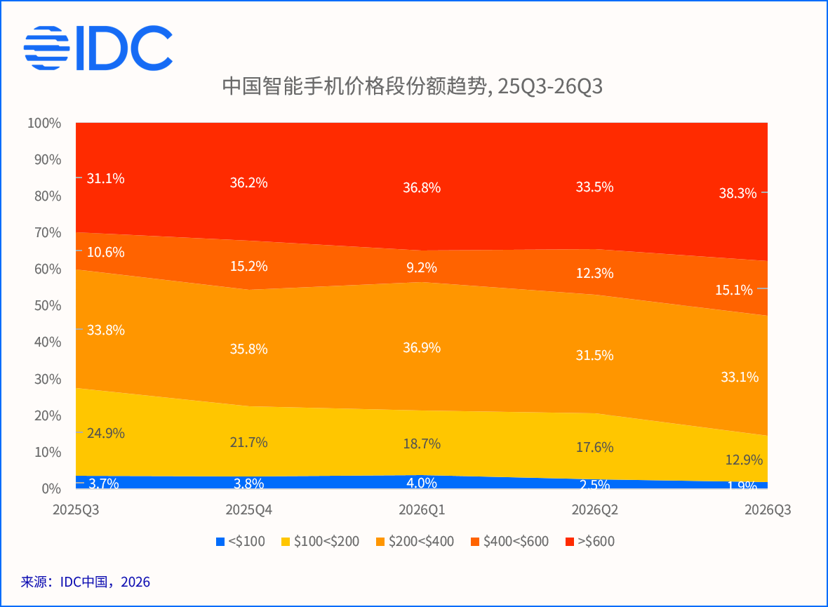
2026 年下半年,元器件成本快速攀升对终端价格的影响已完全显现,市场定价中枢持续上移,价格结构分化态势进一步加剧。分价位段来看,受头部厂商旗舰新品发布节奏前置、产品力升级共同拉动,600 美元以上高端市场份额同比扩张 7.1 个百分点,成为本轮结构升级的主要受益区间;400-600 美元中高端价位段同步扩容,份额同比提升 4.6 个百分点,部分中低端端产品涨价升档到该价位段;200-400 美元中端价位段运行基本平稳,份额同比微降 0.7 个百分点,为全价格带中波动幅度最小的区间;而200美元以下低端市场承压显著,份额同比下降13.9个百分点。整体来看,成本压力正加速推动市场结构向中高端集中,低端市场空间被进一步压缩。

折叠屏:连续四个季度出货下滑

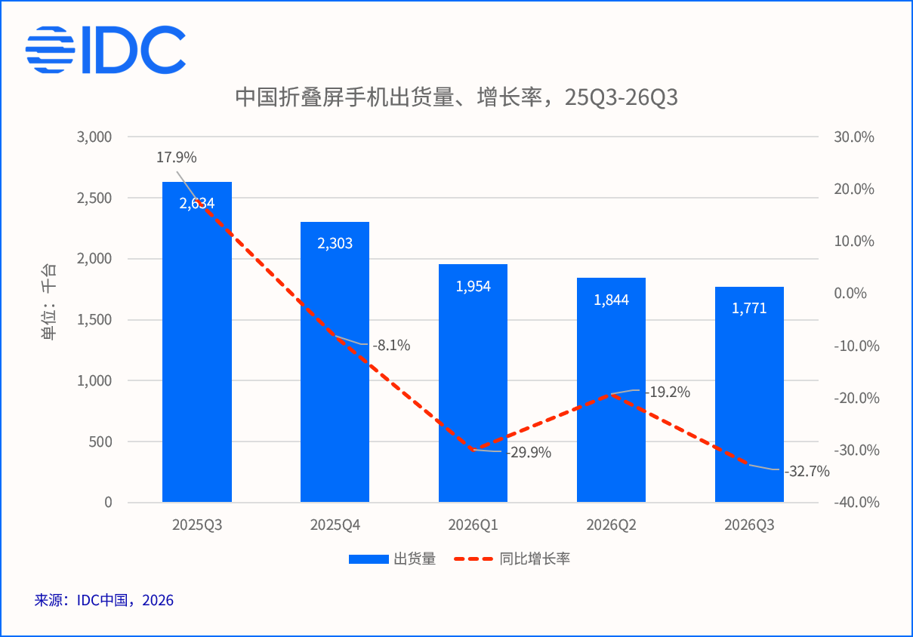
2026年第三季度,中国折叠屏手机出货量达到177万台,同比下降32.7%,市场已连续四个季度呈现同比下行态势。传统形态产品的创新边际效应持续递减,已难以继续激发消费者换机意愿;而率先落地阔折叠新形态的品牌,凭借差异化的产品体验取得更优的市场表现。随着苹果正式入局折叠屏赛道,叠加更多主流品牌将于 2027 年上半年集中推出阔折叠形态新品,市场关注度与消费吸引力有望逐步修复。预计国内折叠屏市场将从下一季度起止跌回暖,重新步入增长轨道。

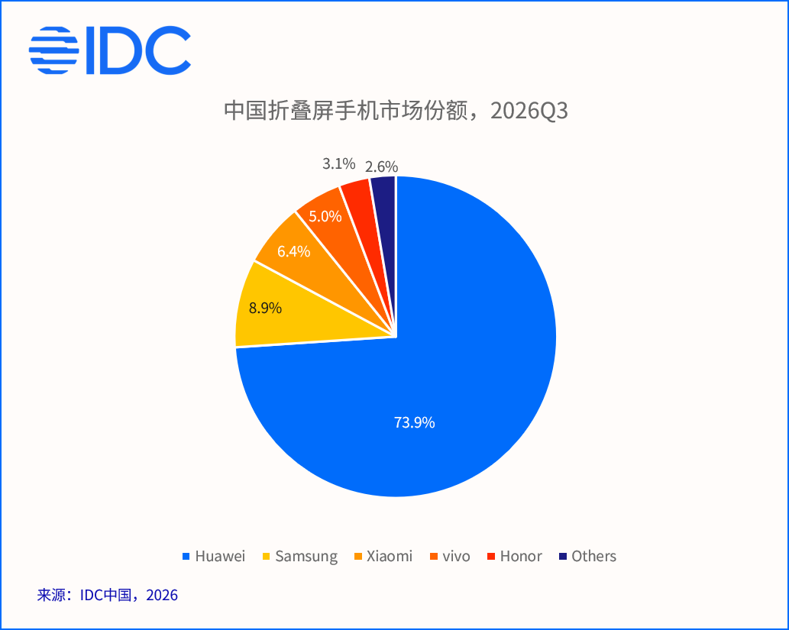
Huawei凭借产品形态最全面的布局依然占据绝对优势,市场份额超过70%;阔折产品Galaxy Z Fold8全球热销,帮助Samsung在折叠屏手机市场稳居第二位,份额8.0%;Xiaomi同样依靠阔折新品重返市场第三位,市场份额6.4%;vivo和Honor分居第四和第五位。

后市展望:价格体系重建前,市场难有起色

展望后市,预计存储及其他物料成本将在未来几个季度依然处于高位,手机产品价格将继续保持增长趋势。大部分消费者对价格上涨仍需接受与适应的时间,换机周期恐进一步拉长。因此,即便有大量各档位新品集中发布,预计2026年第四季度中国智能手机市场表现依然难有起色。甚至到2027年大部分时间,成本压力仍将存在,市场预计仍将延续明显下滑趋势。

不过,头部厂商凭借较强的品牌拉力与相比竞争对手更有限的涨价幅度,有望在存量竞争中抢夺更多消费者。随着时间的推移,消费者势必逐步适应并接受新的手机价格体系,待新的换机节点到来,仍将更换手中设备,届时其它品牌也将迎来更多市场发展机会。

进一步交流

除本次发布的季度核心数据外,我们还提供全维度历史数据回溯、细分市场交叉分析及定制化数据模型服务。如需获取完整版数据底表或探讨专属分析维度,欢迎随时联系,我们将为您提供深度数据支持。请点击此处与我们联系。

Arthur Guo

Arthur Guo - Research Manager

Arthur Guo is a research manager for the Client Devices group in IDC China. Based in Beijing, Arthur is responsible for research and analysis of market trends, market sizing, and provincial development trends in the China mobile phone market. His…

2026 年,生成式 AI 与销售管理深度融合,中国 AI 增强型销售管理 CRM 正从传统的信息记录、流程管控,向融合智能洞察、内容生成、预测分析与任务执行的全链路平台演进。企业选型逻辑已从比拼 AI 功能数量,转向关注产品能否嵌入真实销售工作流,在权限规则约束下产出可核验的业务结果,切实提升线索质量、商机推进与服务效率。

近日,国际数据公司( IDC) 发布了《中国 AI Enable CRM 市场份额,2026H1》报告,围绕上半年市场收入与竞争格局展开分析,为技术服务商锚定产品升级方向,也为企业用户更新 AI CRM 选型标准提供参考。数据显示,2026 年上半年市场收入达 5.971 亿元,同比增长 331.3%。头部阵营份额差距较小,前五厂商合计占据超半数市场,其余厂商贡献 47.2% 的收入,市场高速扩容的同时仍保持分散竞争格局。收入增长印证企业已开始为 AI 能力付费,但市场规模不等于场景成熟度,厂商仍需证明 AI 能力可持续嵌入销售流程,带来可量化的业务改善。

一个重要发现:2026年上半年中国AI Enable CRM市场收入同比增长331.3%,但厂商演示厅里“能跑通”的Agent,到了客户真实权限体系和异常接口面前,仍有相当比例跑不完一个完整任务链。市场在为AI能力付费,但付费的理由正在从“你有多少AI功能”转向“你的AI能不能在规则约束下把一件事做完、做对、留下可审计的痕迹”。换句话说,这一轮竞争的分水岭不是模型参数,而是任务闭环的完成率。

基于本次研究,我们梳理出行业五大核心趋势。当前市场仍处于从单点辅助向业务闭环演进的阶段,功能发布与真实落地效果尚存差距。企业选型应聚焦实际任务链表现、数据治理能力与投入产出效果,而非仅依赖功能演示。

趋势一:从记录系统到行动系统:Agent执行能力成为AI Enable CRM的竞争边界

统 CRM 以客户信息沉淀、销售过程留痕、流程管控为核心,云化阶段进一步打通了渠道与业务系统;生成式 AI 普及后,智能问答、内容生成、辅助决策开始嵌入销售工作流。进入 2026 年,AI 增强型 CRM 正向 Agentic 形态演进:智能体不仅能理解销售目标,还可直接调用 CRM 及外围系统,完成客户信息采集、商机判断、跟进执行与服务处理。系统价值正从 “记录已发生的业务” ,转向 “推动下一步行动并输出可审计结果” 。

验证真实的 Agent 能力,不能只看问答或推荐效果,需完整考察自然语言输入、任务拆解、工具调用、数据回写的全链路闭环,以及数据缺失、权限不足、接口异常等场景的容错机制。自主执行不等于全流程无人化,合同、报价、回款、客户风险等高影响动作,仍需人工确认或规则兜底。市场竞争的核心边界,已从功能覆盖广度,转向 Agent 执行范围、数据知识可用性、流程编排与治理能力的综合比拼。

趋势二:从功能堆砌到语义统一与能力复用,一致性决定规模化上限

用大模型与标准化接口的获取门槛持续降低,单纯接入模型、增加对话入口已难以形成长期差异化。销售流程中的客户、商机、合同、回款等核心对象,需要与企业组织架构、行业规则、指标口径、权限体系形成统一业务语义。行业方向正从按角色提供独立 Agent,转向打造统一 AI 工作台,将数据、业务与领域知识抽象为可复用能力模块,让智能体在全销售流程中统一继承上下文、调用权限与执行边界。

业务语义层的核心价值,是把 “能回答问题” 升级为 “知道该调用哪项业务能力、遵循哪套规则”。企业选型时,应核查同一业务对象的跨模块口径一致性、Agent 权限与现有体系的继承性,以及任务失败后的补偿、重试与人工接管机制;跨系统联动场景还需验证数据映射与全链路审计能力。只有能力可配置、可复用、可追溯,AI CRM 才能从标杆项目走向规模化复制。

趋势三:高频刚需场景率先规模化,自主决策类 Agent 仍待成熟

当前国内 AI 增强型 CRM 的落地呈现清晰的成熟度梯度:智能问数、知识库检索、坐席辅助、工单分类、合同审核、智能报价等高频、边界清晰的场景,已进入规模化应用阶段;销售预测、商机健康度评估、跟进内容生成、客户流失预警等场景已得到验证,但仍需结合企业数据质量与流程执行力持续优化。市场收入的快速增长,首先来自这些价值直观、落地门槛较低的场景。

线索挖掘、多语言内容生成、行业合规话术管控等仍处于试点阶段;营销全链路 Agent、深度办公生态融合、自主决策型智能体等方向潜力可观,但距离大规模落地仍有差距。场景数量不等于使用深度,企业应围绕解决率、处理时效、预测准确率、提效幅度、转化效果等指标建立评测体系,明确区分 “可演示” 与 “可稳定运行”,并按风险等级设置人工审核与流程回滚机制。

趋势四:生态协同、本地交付与合规能力成为选型核心考量

AI 增强型 CRM 的竞争已从单一产品能力,延伸至模型、云平台、办公入口与行业服务的生态协同层面。成熟的产品底座、存量客户基础与跨领域资源,正成为产品规模化扩张的重要支撑。与此同时,数据不出域、国产模型适配、多模型切换、私有化部署、数据脱敏、全链路审计、沙箱安全执行,已成为中大型企业采购的核心准入条件。

企业选型不宜仅凭 “支持私有化”“适配国产模型” 这类标签做决策,还需验证目标环境下的完整功能可用性、模型切换效率、系统集成难度与版本升级路径,明确实施交付、数据治理、模型调优与运维的责任边界。国际化产品的全球功能发布,不代表国内市场可直接落地使用,本地合规进度与交付节奏同样需要重点核查。

趋势五:商业模式多元演进,行业复用能力决定长期竞争力

AI 增强型 CRM 的商业化,正在传统席位订阅基础上,拓展出场景增值、资源用量、智能体调用等多元收费维度。厂商间的竞争差异,更多体现在行业流程理解、数据沉淀与交付能力上。按业务结果收费仍处探索阶段,供需双方需明确价值衡量指标,厘清各项成本的分摊规则。

规模化复制的核心,是将各行业项目经验沉淀为可复用的业务规则、流程模板与交付方法论,而非依赖定制化开发。企业采购时,应建立覆盖席位、资源消耗、系统对接、持续运营的总体拥有成本模型,并将线索质量、商机转化、服务效率等业务结果纳入续约评估。能否将项目经验沉淀为标准化产品、持续兑现可核验的业务价值,将直接决定厂商的长期竞争力。

IDC 给技术提供者的建议

建议一:以业务结果而非模型参数规划产品。围绕客户的销售目标、现有流程、量化指标和风险边界设计Agent,优先打通规则明确、风险可控的完整任务链,对合同、报价、回款和客户风险等高影响动作保留人工复核与程序兜底,并通过异常处理演示证明产品的执行可靠性。

建议二:将业务语义层和Skill复用能力作为产品底座。统一客户、商机、合同和回款等核心对象的口径,打通组织权限、数据血缘和审计机制,把可调用的业务能力标准化、服务化,避免统一交互入口与底层流程能力脱节,并将跨系统接入后的语义一致性和失败补偿纳入验证。

建议三:把数据治理和可信执行前置到项目初期。帮助客户厘清主数据、指标负责人和数据域边界,保障关键结论能够追溯至原始单据或交互记录。采用确定性程序与大模型协同执行,将置信度分流、人工审核、操作留痕、阻断回滚和持续回归测试纳入产品与交付流程,降低核心销售业务的运行风险。

建议四:按客户约束完善部署方案和生态协同。明确公有云、专属云、混合部署与纯私有化的实际支持范围,推进国产软硬件适配、多模型接入和办公生态连接器建设。对实施、系统集成、数据治理、模型调优及后续运维作出清晰约定,让客户能够判断上线条件、服务责任和持续运营投入。

建议五:以行业资产复用和可量化成效支撑规模化。聚焦两到三个核心场景及优势行业,将共创项目中的规则、流程和知识沉淀为可配置产品,合理控制定制范围并持续反馈产品迭代。建立清晰的订阅、用量与服务计费体系,帮助客户测算完整TCO,以问题解决率、处理时效、准确率和销售转化等可核验结果推动采购、续约与扩容。

IDC中国企业级应用软件市场高级研究经理徐文婷认为, 2026年中国AI Enable CRM市场进入从功能辅助向业务执行演进的关键阶段,问数、客服和合同审核等高频场景正在规模化,销售预测、客户洞察和跟进建议等场景持续验证,营销侧全链路和自主决策型Agent仍需突破。未来,厂商的竞争力将由模型接入能力转向可复用的业务语义、可治理的任务执行、合规的本地交付和可量化的销售成效。

AI Enable CRM的竞争正在从“场景覆盖竞赛”转向“失败场景治理竞赛”。高频场景之所以先规模化,本质上不是因为它们更“智能”,而是因为它们的错误可以被人工兜底、责任可以被追溯、风险可以被定价;而自主决策型Agent迟迟难以放量,核心卡点也不在模型能力,而在于失败后的归因、补偿与责任边界尚未形成可复用的机制。对厂商而言,下一阶段的差异化不在于多覆盖几个场景,而在于能否把“权限不足时的降级、接口异常时的补偿、跨系统映射失败时的审计”做成标准化能力;对企业而言,选型时应把压力测试从“功能演示”转向“异常路径演示”,要求厂商现场跑通数据缺失、权限冲突、回滚接管三类场景。谁能把失败场景治理好,谁才真正具备规模化复制的资格。

进一步交流
AI Enable CRM的选型与落地,最终要回到真实任务链和异常路径上验证。IDC将持续跟踪高频场景的规模化进展、Agent失败场景治理机制与按业务结果计费的演进。欢迎厂商与企业就产品能力验证、TCO测算与行业复用路径进一步交流,也欢迎提供真实落地案例,共同校准下一阶段的竞争坐标。请点击此处与我们联系。

Wenting Xu

Wenting Xu - Senior Research Manager

Wenting Xu, senior research manager with IDC China's Enterprise Application Research, focuses on research and analysis of the China enterprise system and software area. She provides intelligence and consulting services for local and multinational corporation IT vendors. Wenting has developed a deep…

随着大语言模型、多模态交互及端云协同架构不断成熟,智能语音、AI助手、导航问答、内容生成和个性化推荐等AI原生应用正加速上车。座舱交互体验也由此成为车企构建差异化竞争力的关键变量。AI座舱正从“功能集成”迈向“体验重构”,这一趋势首次有了可量化的市场刻度。国际数据公司(IDC)在《中国汽车云市场跟踪》报告中,首次将AI座舱解决方案作为独立附加(Add-on)市场开展系统跟踪,并从市场规模、竞争格局、技术路线和商业模式等维度发布首期研究成果。

IDC定义的AI座舱解决方案市场涵盖四个层面:AI开发平台/软件(模型开发、Agent编排、部署管理等)、模型服务MaaS(大语言模型、多模态模型及语音模型的云端、车端与端云协同调用)、AI应用(智能语音、AI助手、导航问答、内容生成等),以及AI运营服务(模型更新、知识库管理、运营监控与持续优化)。

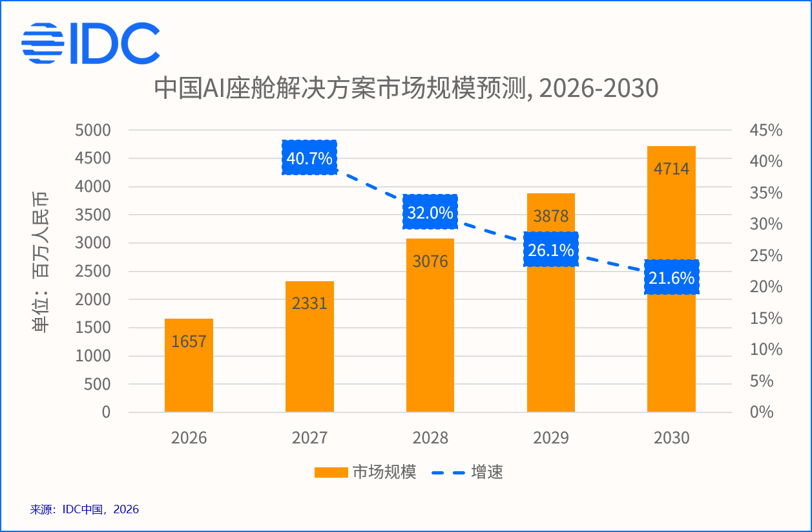
IDC数据显示,2026年上半年,中国AI座舱解决方案市场规模达到7.1亿元人民币。这一规模表明,AI座舱已进入规模起量阶段,市场需求与商业化进程同步提速,市场正由早期探索转向规模化量产与持续运营。IDC预计,2026年全年中国AI座舱解决方案市场规模将达到16.6亿元人民币,到2030年有望进一步增长至47.1亿元人民币,年复合增长率接近30%。

竞争格局浮出水面:第一名份额超四成,市场早期就呈现出高集中的特征

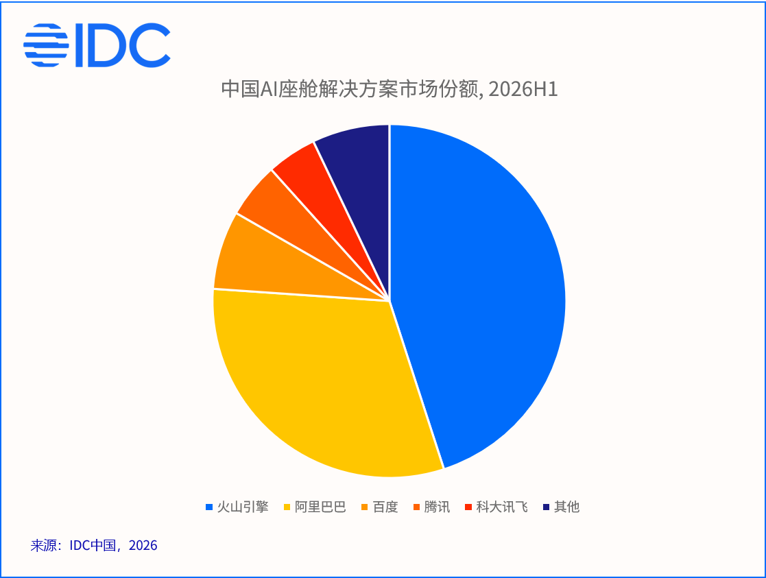
从竞争格局来看,市场头部聚集效应显著:2026年上半年,火山引擎以45%的市场份额位列第一,阿里巴巴份额位居第二。从优势来源看,头部厂商的领先主要建立在量产车型覆盖规模与头部客户项目经验之上,属于现阶段的市场身位,格局远未固化。第二梯队中,百度依托座舱业务存量与地图等既有能力保持市场参与;科大讯飞依托座舱域软硬件方案与既有客户基础,稳步推进AI能力升级;此外,阶跃星辰等模型创业公司也通过与车企及产业链伙伴的深度绑定切入市场,部分技术已实现上车。整体而言,市场格局仍处于动态演化阶段,量产项目经验、生态协同能力与C端品牌认知正在成为厂商竞争的关键筹码。

License授权与按量付费并行,商业模式向价值导向演进

从商业模式来看,当前AI座舱市场的计费方式呈现多元化特征:面向功能套件组合的License授权仍是主流模式,车企因选型范围不同,定价差异较为明显;针对自研能力较强、仅需基础模型能力的客户,按Token或调用量计费的公有云模式成为重要补充;端侧部署则普遍采用一次性激活计费并辅以年度技术支持与模型迭代维护费。

值得注意的是,车企对AI投入产出比的关注度显著提升,定价谈判愈发围绕实际使用效果与价值密度展开,深度赋能项目与基础功能授权之间的价值差异正在拉大。与此同时,部分厂商开始以标杆项目为抓手,探索从车企买单向C端用户订阅付费过渡的路径,为市场打开新的收入想象空间。

端云协同成为主流架构,交互体验竞争走向纵深

从技术演进来看,端云协同已成为行业共识:端侧模型承担高频简单指令的快速响应,云端大模型处理复杂推理与多模态交互,在体验、时延与成本之间取得平衡。端侧模型参数量持续提升,对高算力车载芯片的配套能力提出更高要求;在产业分工上,云与模型厂商普遍与Tier 1供应商合作,将软件能力集成至域控制器,实体多模态交互硬件亦已在部分车型开展试点。此外,跟随中国车企出海步伐,座舱AI能力的海外落地正在成为新的增长方向;具身智能等前沿领域的探索,也为座舱交互形态的中长期演进带来更多可能。

从被动应答到主动服务,Agentic AI重塑座舱交互范式

从交互范式来看,AI座舱正在经历从“被动应答”向“主动服务”的关键跃迁。上一代座舱语音助手普遍采用“意图分域+多Agent协同”的回合制架构,交互割裂、使用频次受限;2026年以来,多家头部厂商相继发布基于Agentic AI(代理式人工智能)架构的新一代座舱方案,技术路线的共同点在于以统一的AI中枢联动车控、导航、智驾等功能域,推动座舱交互从回合制问答向任务驱动的自主执行演进。

从厂商公开披露的信息看,头部厂商的大模型车型搭载量已达到数百万辆量级,日均座舱交互达到数千万次量级;尽管各家统计口径不尽相同,但座舱AI从低频的“尝鲜配置”逐步转变为用户高频使用的日常服务,已成为可观察的行业趋势。IDC认为,这一跃迁的商业含义同样深远:只有当座舱AI从低频功能进化为高频服务,围绕服务闭环的付费逻辑才能真正成立,车企与供应商才有基础探索从B端授权向C端订阅的收费模式迁移。交互范式升级与商业模式演进的叠加,将共同决定AI座舱市场未来五年的增长斜率。

IDC中国云计算产品高级分析师陈启今表示,AI座舱是汽车云市场中增长确定性较高的新兴板块。当前市场仍处于早期阶段,商业模式、技术架构与竞争格局均未完全定型,头部厂商的量产车型覆盖与标杆项目经验构成先发优势,而车企对成本与体验的平衡诉求、以及C端付费模式的成熟度,将在很大程度上决定市场从”配置竞争”走向”价值竞争”的速度。对于供应商而言,围绕真实用车场景打磨交互体验、构建端云协同的工程化能力、建立可持续的计费模式,是把握这一市场机遇的关键。

IDC 相关研究

围绕AI时代行业云市场的发展趋势、客户需求、技术应用与竞争格局,IDC将持续开展系统性研究,覆盖汽车、具身智能、金融、游戏、零售等重点行业,包括但不限于:

  • Market Analysis Perspective: 中国AI游戏云市场洞察,2025(已发布)
  • 中国具身智能云市场份额,2025(已发布)
  • 中国汽车云市场跟踪,2026H1(已发布)
  • 中国金融云市场跟踪,2026H1(即将发布)
  • 中国游戏云市场跟踪,2026H1(即将发布)

进一步交流
AI座舱的格局远未固化,价值竞争才刚刚开始。如果您对这份IDC首发的市场数据有进一步了解的需求,或希望就AI座舱的商业模式、技术演进与分析师团队展开探讨,欢迎随时与我们联系。请点击此处与我们联系。

IDC Quanta has been available in Claude since July, and IDC’s teams use Claude every day to drive speed and agility throughout the organization.

Recently, IDC and Anthropic shared a case study on how IDC is using Claude to extend IDC Quanta to customers and to change how the company works. This post adds detail on both.

IDC worked with Anthropic to connect IDC Quanta to Claude, allowing customers to describe the market, strategy, or purchase they are working on, and Claude draws on IDC’s forecasts and market data to answer. Each answer cites the IDC document or dataset it came from.

“We brought IDC Quanta into Claude because that’s where many of our customers already work,” said Meredith Whalen, IDC’s Chief Research and Data Intelligence Officer.

What customers can do with IDC Quanta in Claude

The IDC Quanta connector lets Claude reach IDC Quanta from the Claude app on desktop and mobile, and the Microsoft Office add-ins. The research stays with IDC. Claude connects when a customer asks a question, and the answer uses the same data and definitions an IDC analyst uses, so market share or growth rates match what IDC would publish.

Customers use it for questions like these:

  • Competitive briefs. They can do a day’s worth of research in minutes. A corporate strategy lead asks for a competitor brief and gets positioning, market share, product capabilities, and recent acquisitions, cited to IDC research.

  • Vendor shortlists. A CIO evaluating procurement software describes her architecture and business requirements. Claude returns the top three vendors from IDC’s procurement database and MarketScape research as an Excel scorecard for the evaluation team.

  • Analysis of their own numbers. A CFO uploads next year’s IT budget and asks how it compares to IDC’s forecast. Claude shows where the two differ and by how much, and the CFO’s data stays private to the customer.

The case study shows more of what customers can do with IDC Quanta and Claude.

How IDC uses Claude across the company

IDC’s own teams use Claude daily. Engineering adopted it first, and the rest of the company followed.

Engineers rebuilt the internal data repository analysts use for research in three weeks, down from an estimated three months. A code review that once filled five days now takes about 30 minutes.

Sales uses a tool built with Claude that reads a CRM export and shows each rep which deals have stalled, and which are worth following up.

The case study also covers how product, planning, and marketing teams use Claude.

Read the full case study to learn more about how IDC leverages Claude.

Getting started

IDC Quanta customers using Claude can add the IDC Quanta connector within Claude.

If you want to see IDC Quanta and Claude in action, contact IDC or book a demo.

Ryan Smith - Content Marketing Director - IDC

Ryan Smith is the Director of Content Marketing at IDC, where he leads brand-level content and social media strategy, aligning research insights with compelling storytelling to engage technology decision-makers. With a background in both IT and marketing, Ryan brings a unique blend of technical understanding and creative strategy to his work. He’s also a seasoned storyteller, speaker, and podcast host who believes the right message, told the right way, can drive both trust and transformation.

The logic is solid. Invest more in security, and you’ll reduce your risk.

IDC data suggests otherwise. IDC’s 2026 Worldwide Security Spending Guide (V2 release) forecasts that organizations will spend $310.42 billion on security this year, up 13.2% from 2025. Yet in IDC’s February 2026 CEO Survey of 492 CEOs, cybersecurity is still the highest-ranked anticipated technology risk, ahead of AI itself.

In the same survey, organizations have funded security and put governance around it, yet they still do not feel safer.

So why the mismatch between rising budgets and heightened concern?

Two IDC surveys, one of CEOs and one of security buyers, point to the same evidence gap: security spending isn’t following the risk data meant to justify it.

To meet CEO expectations for security, tech leaders need to find where the gap sits in their own organization. Start with these three questions.

1. Is your next AppSec purchase justified by a finding or by a feature?

At the buyer level, the top reason security buyers gave for their most recent application security (AppSec) tool purchase was adopting AI features (31%), followed by better integration (28%). Neither reason is about risk findings. Both figures come from IDC’s 2025 DevSecOps and Software Supply Chain Security Survey (n=511, fielded July 2025).

The same survey, of US-based organizations with more than 500 employees, puts the average 2024 AppSec budget at $2.3 million, and 61% of organizations raised it in 2025, with an average change of about +5% across all organizations.

2. How does your spend compare to organizations your size?

Endpoint security funding isn’t reaching every organization equally. Large organizations are raising budgets faster, while small organizations lag.

IDC’s 2026 Worldwide Modern Endpoint Security Survey (n=846, fielded March 2026) found that more than 60% of organizations raised their 2026 endpoint security budgets. More than 25% of large organizations (500–999 employees) raised them by 10% or more, versus only 12.9% of small organizations (1–99 employees).

The gap isn’t evenly distributed. Small organizations are often the ones with the least room to absorb a miss, so knowing how your spend compares with organizations your size is a useful first reference point.

3. Is security part of your AI funding conversation?

In IDC’s February 2026 CEO Survey, 50% of CEOs named advanced cybersecurity, and 52% named agentic and generative AI at scale, as a top-three investment area for the next 12 to 24 months. The two sit two points apart, which suggests CEOs weigh AI and security funding together.

CEOs link the two on risk as well. Asked what concerns them most about AI, they name data privacy (46%) and security (35%) as their top two risks.

How to close the evidence gap

If one or more of these questions hit close to home, you may be facing an evidence gap. The same question applies to AI. In IDC’s MaturityScape Benchmark: AI-Fueled Organization Worldwide, 2026 (n=1,900), 61.3% of organizations are still in the two earliest stages of AI maturity. Where do you stand?

The first step to closing the gap is knowing where you stand against your peers. IDC Quanta for Tech Leaders delivers sourced IDC research and peer benchmarks directly into the tools your teams already use, with no separate portal or login.

Christina Cardoza - Content Marketing Manager - IDC

Christina Cardoza is a Content Marketing Manager at IDC, where she specializes in brand content and social media strategy. With a background in journalism and editorial leadership, she has a proven ability to transform complex technology topics into clear, actionable insights.

When your board asks how you compare with peers, expect questions on AI transformation, IT spend, and governance maturity. IDC’s MaturityScape Benchmark covers the AI side of that comparison. 61.3% of organizations sit in the two earliest stages of AI maturity, and only 3.1% have reached the most mature stage (IDC MaturityScape Benchmark: AI-Fueled Organization, 2026, worldwide, n = 1,900).

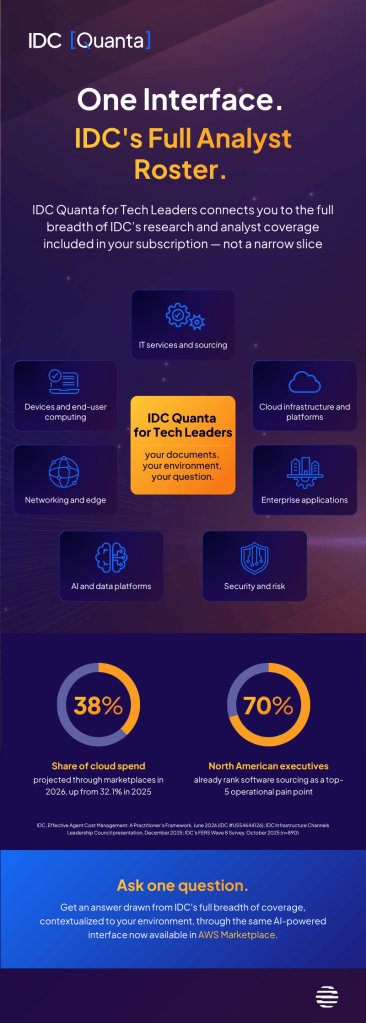
Which stage are we in, and what moves us to the next one? IDC Quanta for Tech Leaders connects you to IDC’s research across the seven areas below, including cloud, enterprise applications, and networking and edge, plus security and risk. Ask in your own terms and add your own documents, and the answer comes back set against your environment, inside the tools you already use. It is also available in AWS Marketplace, so you can buy it against existing AWS commitments.

Which stage are you in?

Christina Cardoza - Content Marketing Manager - IDC

Christina Cardoza is a Content Marketing Manager at IDC, where she specializes in brand content and social media strategy. With a background in journalism and editorial leadership, she has a proven ability to transform complex technology topics into clear, actionable insights.

On October 21, two critical flaws in PHP left organizations with a choice that cybersecurity authorities stated plainly: update affected systems immediately or take them offline. Known together as PHP2Shell, the flaws (CVE-2026-109618 and CVE-2026-109619) can allow attackers to run code on affected servers without logging in.

PHP runs websites and applications, including platforms such as WordPress and Drupal. But knowing that a company uses PHP is different from knowing every place it runs. A patch only helps once an organization knows where it is needed, who can apply it, and how to make the change safely. Those decisions are harder to make for the first time during an emergency.

IDC’s DevSecOps and Software Supply Chain Security Survey of U.S. enterprises illustrates the challenge. Asked to name their two hardest challenges if vulnerability discoveries rose sharply, respondents most often chose knowing where vulnerable software runs (30.7%) and deciding what to fix first (28.8%), ahead of fixing vulnerabilities quickly enough (23.6%). These findings suggest that faster remediation depends on work that begins well before a vulnerability is disclosed.

Inventory must connect software, ownership, and exposure

PHP can run inside vendor products, administrative tools, older internal systems, and websites managed by hosting providers. An application inventory may identify the website without recording the PHP version beneath it or who controls its updates.

Updating a website or its plugins is not enough unless the update also replaces the vulnerable PHP software. The fix may require action from an internal infrastructure team, a hosting provider, or a product vendor.

Log4Shell exposed the same gap in 2021, when Log4j turned up in applications whose owners did not know they contained it. The U.S. Cyber Safety Review Board found that the organizations that responded most effectively already knew where they used Log4j and had mature processes for managing assets.

No single inventory source should be assumed complete. Attack surface management and vulnerability management tools can help discover exposed services and identify affected software, while cloud security platforms can connect findings to deployed workloads and their exposure. Software bills of materials and provider confirmation can add component information. Organizations should verify that these capabilities also connect findings to accountable owners and business services.

An inventory must therefore answer more than “What applications do we have?” It must also show the software they depend on, its version, and the team or provider responsible for updating it.

AI adds urgency to a familiar problem

The researchers who reported PHP2Shell used frontier AI models to uncover flaws in PHP’s core that had been there for more than a decade. Models can read large codebases, follow how memory and errors are handled across many files, and, once they find one flaw, search for others that follow the same pattern. PHP’s security team now receives far more reports than it did before.

AI can also help attackers with the slower step that follows: turning a flaw into an attack that works against a particular system. That step has historically required skill and repeated testing; AI models can now compare a patch with the code it replaced, draft an exploit, test it, and adjust it after each failure. PHP developers spotted one of the PHP2Shell flaws in 2024 but found no concrete way to exploit it; with AI models, the reporting researchers built attacks that worked against several widely used applications.

More disclosures and a shorter path to attack leave organizations less time to act on each advisory, and PHP2Shell showed how little time that can be. The earliest reported exploitation attempt came four days before disclosure, and PHP moved its release up a day after news of the flaws leaked.

Confidence in the change sets the pace of the fix

Finding an affected system does not mean an organization can immediately change it. Operations teams need confidence that an urgent update will not cause an outage, but testing, scheduling, and approval can introduce delays when multiple teams or providers are involved. In the same survey, 20.4% chose coordinating fixes across application, infrastructure, and open source teams as one of their two hardest challenges.

Organizations can reduce avoidable delays by agreeing on emergency change procedures in advance. Those procedures should specify which updates qualify for a preapproved process, what testing is required, how a failed change will be reversed, and who coordinates the response. Providers of maintained software packages and container images can help by supplying updated components when vulnerabilities are disclosed, while patch management and deployment tools can support the rollout and verification of patches. Both work best when the path from provider to production is set before an emergency.

Compensating controls buy time but need an end date

When an update cannot be applied immediately, temporary protections such as restricting network access, changing vulnerable configurations, or blocking known attack patterns can reduce exposure, depending on the vulnerability and deployment.

For PHP2Shell, PHP’s maintainers state, “There are no complete mitigations, updating is the only safe choice.” Organizations need to verify what a control covers and take a system offline when the remaining risk is unacceptable.

That decision requires the same visibility and ownership needed for patching. Each temporary measure needs a named owner, a scheduled fix, and a review date.

Turn this response into preparation

Organizations responding to PHP2Shell should use the work to strengthen four practices:

  • Inventory: Find affected PHP installations, starting with internet-facing systems. Record each installation’s version and its source, such as an operating system package or a container image, because distributions can apply fixes to older versions without changing the version number.
  • Ownership: Identify who can authorize and perform each update, including external providers.
  • Patching: Follow current PHP and vendor guidance, verify that the fixed software is running, and investigate signs of compromise. Patching does not remove an attacker already inside.
  • Compensating controls: Verify the coverage of interim controls, isolate systems where necessary, and assign responsibility and a review date for every unresolved exposure.

No organization can control when the next critical flaw is disclosed. Each can control what the first hours look like: whether teams start patching systems they already know about, with owners and change procedures in place, or start searching for systems they did not know they had.

Michelle Abraham

Michelle Abraham - Research Vice President , Security and Trust

Michelle Abraham is a Research Vice President in IDC’s Security and Trust Group, responsible for the Security Information and Event Management (SIEM), Exposure Management, and Related Artificial Intelligence Technologies practice. Ms. Abraham’s core research coverage includes SIEM platforms, exposure management…
Katie Norton

Katie Norton - Research Director, Cloud Security

Katie Norton is a Research Director for IDC's Cloud Security research practice, covering the Cloud-Native Application Protection Platform (CNAPP) market and its adjacent technologies. She is responsible for researching, writing, and advising clients on market sizing, vendor positioning, competitive dynamics,…
Bobby Kuzma

Bobby Kuzma - Sr. Research Manager DevSecOps

Bobby Kuzma is a Senior Research Manager at IDC, where he runs the DevSecOps and Agentic Development Security program. He covers how teams build security into the software development life cycle: application security testing, software supply chain security, runtime protection,…

AI agents now act on behalf of organizations, and the work, the money, and the technology around them are being rebuilt to match. FutureScape 2027 calls this the Great Rewrite and sorts what is changing into three windows: closing, open, and emerging. IDC FutureScape 2027 begins rolling out today, with all 25 reports publishing October 27-29. Each report includes 10 predictions looking ahead up to five years across a wide range of industries and topics.

The windows show how much time is left to act on each shift, which changes which decisions come first.

What is IDC FutureScape, and who uses it?

IDC FutureScape is IDC’s annual set of predictions, written by the analysts who cover each market. Every prediction carries a time frame, so you can see what is likely to happen and roughly when. Two audiences put that to work in different ways.

Tech leaders use FutureScape to navigate the market they operate in. They look for which forces are building, how fast, and what the next budget cycle needs to account for. Tech suppliers use it to see where their customers are headed. That shows them where to develop solutions that help those customers find an advantage as markets shift.

See the IDC FutureScape top 10 worldwide predictions webinar hosted by Rick Villars, Group Vice President, Worldwide Research. 

What is the Great Rewrite?

Across FutureScape 2027, dozens of predictions from different practice areas reach the same conclusion. AI isn’t being added on top of how organizations work. It’s rewriting what sits underneath: the compute layer, the org chart, the balance sheet. The Great Rewrite is that shift, and it is reaching every organization whether or not that organization has planned for it.

The Agentic Economy is the operating environment the rewrite produces, and it is where winning and losing get decided. Pace is part of the story. IDC’s Future Enterprise Resiliency and Spending Survey (Wave 2, March to April 2026, n=1,009) shows the scale. Enterprises expect to nearly double the types of AI agents they run in production, from an average of 23.5 in April 2026 to 43.2 by year-end1. The deciding factor is the distance between how fast agents can act and how well organizations can govern what they do. That distance compounds with every agent type that goes into production.

Want more information about this year’s predictions? Visit our IDC FutureScape 2027 site.

What do the closing, open, and emerging windows mean?

The forces in the Great Rewrite do not move at the same speed. Each prediction lands in a window based on how settled the decision is: nearly made, still yours to shape, or only now taking form. Each window asks for a different kind of decision.

  • Closing: an opportunity is about to become a disadvantage. The big decisions are nearly made, and waiting means inheriting the outcome of choices others have already set.

  • Open: decisions you need to make today. These are still yours to shape, but the room to shape them is narrowing.

  • Emerging: advantages you can still influence. Nobody has captured these yet, so early moves can still change how the advantage gets built.

For tech leaders, the windows answer a practical question: which decisions belong in this planning cycle, and which can wait and be watched? Settle the closing decisions now, and use the open window to shape what is still undecided.

For tech suppliers, the windows show where buyers have already chosen, where they are still deciding, and where no direction is set yet. That is where new solutions can still change the outcome.

Hear Rick Villars sort the Top 10 Worldwide Predictions into these windows live on October 28: watch the webinar.

How can you hear the Top 10 Worldwide Predictions?

IDC’s FutureScape Top 10 Worldwide Predictions name the ten most notable ways the world is being rewritten. On October 28, Rick Villars, Group Vice President, Worldwide Research, walks through them live in the webinar The Great Rewrite: Winning in the Agentic Economy. He sorts each prediction into closing, open, or emerging. Then he shows how the ten play out across three threads that run through all of them:

  • Redefining Resilience: AI is redefining it, with real benefits, real pain, and consequences that reach the architecture you are planning today.

  • Creating Trust in Agents: Agents are already taking actions in your business, and trusting what they do is a long, complex, and uncertain journey.

  • Establishing New Leadership: Placing bets on independence comes with risks and rewards, and the harder call is where to play.

You will leave with the ten predictions ordered by how long you have to decide, ready for your next leadership or budget conversation. The session runs sixty minutes, with time for your questions, at 8 AM Pacific and 3 PM in London. Joining from the Gulf, live is 7 PM in Dubai. In Asia Pacific, live is 11 PM in Singapore, midnight Thursday in Tokyo, and 2 AM Thursday in Sydney, so the replay is the better fit.

If you set 2027 technology priorities or control the budgets behind them (CIOs, CTOs, CFOs, and heads of AI), or you build the solutions they buy, this one is for you.

Explore the FutureScape 2027 reports as they publish through October 29 at idc.com/futurescape.

Sources

  1. IDC Survey Spotlight: From Pilot to Production — How Rapidly Is AI Agent Adoption Maturing? (IDC #AP54627726, June 2026). IDC’s Future Enterprise Resiliency and Spending Survey, Wave 1 (February 2026, n=903) and Wave 2 (March to April 2026, n=1,009).

Ryan Smith - Content Marketing Director - IDC

Ryan Smith is the Director of Content Marketing at IDC, where he leads brand-level content and social media strategy, aligning research insights with compelling storytelling to engage technology decision-makers. With a background in both IT and marketing, Ryan brings a unique blend of technical understanding and creative strategy to his work. He’s also a seasoned storyteller, speaker, and podcast host who believes the right message, told the right way, can drive both trust and transformation.