Three key themes will dominate IT industry developments in the coming years:

  • Orchestrating a sustained expansion in AI agent use across the enterprise
  • Navigating major tech sector transformations driven by the IT industry’s own Agentic AI pivot
  • Taking early advantage of the fast-maturing technologies in quantum computing, next-generation connectivity, and physical AI devices to boost resiliency and business reach.

For CIOs, these converging forces signal a new leadership mandate.

IDC’s 2026 IT Predictions highlight ten developments that every enterprise should track closely. Together, they outline an ambitious yet attainable roadmap for the next five years.

1. From AI models to composite intelligence

By 2026, a renewed focus on explainability and reliability drives 70% of organizations to adopt composite AI, blending generative, prescriptive, predictive, and agentic technologies.

CIOs will need to integrate these diverse AI capabilities into cohesive systems that are transparent, auditable, and trustworthy. Building an AI governance foundation that tracks model lineage, set ethical guardrails, and ensures accountability is critical for scaling enterprise AI responsibly.

2. Orchestrating the agent explosion

By 2027, G2000 agent use will jump 10x and token/call loads 1,000x, making agent vetting, orchestration, and optimization essential IT responsibilities

The era of agentic orchestration is here. CIOs must prepare for exponential growth in autonomous agents that are interacting with individuals, critical data, and other agents. These agents will also be learning tasked with making more decisions, making continuous agent-vetting a vital task. Managing this complexity requires robust monitoring, explainability, and lifecycle control to prevent “agent sprawl” and ensure outcomes remain compliant and aligned with business goals.

3. Agents as the new interface

By 2028, 45% of IT product and services interactions will use agents as the primary interface for ongoing operations.

Agents are becoming the face of IT products and services, redefining how organizations consume technology. Procurement, service delivery, and user experience will be mediated by intelligent agents, transforming how value is assessed and measured. CIOs will need to lead on redefining enterprise architecture and user experience for this new agent mediated IT environment.

4. Measuring collaboration over productivity

By 2029, organizations that measure AI-human collaboration will have margins up to 15% higher than those focusing solely on productivity.

The leaders of tomorrow will not be those who automate the most, but those who collaborate the best. CIOs must foster environments where effective combined human creativity and agentic intelligence is critical. The leaders will those that prove best at defining collaboration metrics that quantify augmentation and innovation rather than simple cost savings.

5. Services become modular and autonomous

By 2029, 30% of global IT services will be delivered as modular, platform-enabled products, driven by demand for speed, transparency, GenAI, and Agentic AI-enabled autonomous service orchestration.

The services landscape is undergoing its own agentic transformation. Platform-enabled IT ecosystems with sophisticated AI orchestration will replace static service contracts with adaptive, API-driven delivery models. CIOs must evolve governance, procurement, and budgeting processes to support continuous, autonomous service improvement.

6. The cloud modernization imperative

By 2027, the massive computational and data demands of AI will compel 80% of organizations to modernize legacy cloud environments by shifting to new platforms specifically designed for AI workloads.

Legacy cloud environments—public or private—won’t sustain agentic scale. CIOs must migrate to AI-optimized infrastructure with GPU-rich, heterogeneous compute capacity and agile workload placement. The winners will be those who modernize their cloud strategy not just for scalability but for AI-driven elasticity and efficiency.

7. Data collaboration as the new competitive edge

By 2028, 60% of enterprises will collaborate on data via private data exchanges or clean rooms on a broad variety of use cases, including data federation for generative and agentic AI.

In the AI era, data sharing is no longer optional. It’s the foundation of competitive advantage. CIOs must identify and take full advantage of trusted data ecosystems from their tech partners. Prioritize solutions that balance sovereignty and privacy with the need for cross-industry innovation.

8. Quantum rediness becomes urgent

By 2030, quantum-accelerated supercomputing will be used by the US, EU, and China governments for solving 50% of complex defense and science-related problems, including breaking encryption schemes.

Quantum’s arrival will reshape the security landscape. CIOs must invest early in post-quantum resilience. Focus on testing hybrid encryption, revisiting identity and key management, and developing contingency plans for quantum-era threats.

9. Next-generation connectivity extends enterprise reach

By 2029, 75% of enterprises will adopt LEO satellite connectivity to complement terrestrial networks, enabling critical satellite D2C, D2D and highspeed broadband as part of a unified digital fabric.

Multi-orbit connectivity will define the next generation of connectivity for the distributed enterprise. CIOs should view LEO and 5G as strategic enablers of global edge-to-cloud integration—building network architectures that can adapt to dynamic workloads, accelerate geographic expansion, and reduce risks in a time of geopolitical instability.

10. Edge intelligence accelerates local decision-making

By 2030, 50% of enterprise AI inference workloads will be processed locally on endpoints or edge nodes, reducing cloud traffic and latency while supporting greater control over sensitive data.

As AI moves closer to the user, CIOs must rethink infrastructure, governance, and security models. Edge intelligence will reduce latency, enhance privacy, and create new opportunities for real-time, autonomous decision-making at the organization’s operational front line.

The CIO as navigator

These ten predictions reinforce a simple truth: the CIO is now the chief orchestrator of the intelligent enterprise. From agent governance to quantum readiness, success in this decade hinges on mastering the balance between innovation and integrity, automation and collaboration, scale and sovereignty.

The path ahead is complex but navigable. With a deliberate strategy, a modernized tech stack, and a workforce ready to collaborate with AI, CIOs can transform today’s turbulence into tomorrow’s advantage.

Rick Villars - Group VP, Worldwide Research - IDC

Rick is IDC's chief analyst guiding research on the future of the IT Industry. He coordinates all IDC research related to the impact of Cloud and the shift to digital business models across infrastructure, platforms, software, and services. He helps enterprises develop effective strategies for using their diverse portfolio of cloud investments and applications. He supplies early guidance on implications of critical innovations such as the shift to cloud-based control platforms for deploying/managing infrastructure, data, and code delivery as well as the emergence of AI as a critical IT workload and part of all IT products/services.

Beyond revenue: why telecom’s future depends on profitability, not just revenue

On 24 September 2025, I moderated a panel at Connected Britain titled “Monetising Your Network for a Better Tomorrow” — or, as Carlos Bock aptly put it, “Monetising Your Network for a Better Today.” The panel brought together influential voices from across the telecom ecosystem — Ronan Kelly (Managing Director, AllPoints Fibre), Stefan Stanislawski (CEO, Lightning Fibre), Carlos Bock (Executive Chairman, F&W Networks), Will Rhodes (Carrier Managed Service Consultant, Ciena), and Dan Bloch (Senior VP Global Solution, Calix) — to tackle one of the industry’s most urgent challenges: how to unlock new value in a market that’s saturated, commoditised, and fiercely competitive.

The answer, it turns out, isn’t about chasing revenue growth. It’s about profitability.

From ARPU to AMPU: a necessary shift in focus

For more than a decade, telecom operators have measured success by one metric above all others: average revenue per user (ARPU). But as competition intensifies and price wars continue to drive down returns, ARPU alone tells an incomplete story. Carlos Bock noted, customers today are getting a “Ferrari for the price of a Honda.” Ultra-fast, highly reliable connectivity is priced like a commodity — and operators have been complicit in that race to the bottom.

It’s time to shift the industry’s focus from ARPU to AMPU (Average Margin Per User). Understanding what customers pay is no longer enough — telcos must grasp what each user contributes to profitability. During the panel, Ronan Kelly posed a simple yet revealing question: “Who here knows their AMPU?” Out of more than 200 attendees, only two raised their hands. This striking moment underscored a critical gap — most operators lack visibility into per-user margin data, even though it’s essential for informed strategic decisions.

Ultimately, telcos are valued not by the size of their top-line revenue, but by their EBITDA margin — the efficiency with which they generate earnings, as measured by metrics like Discounted Cash Flow (DCF) and EBITDA multiples.

Beyond connectivity: monetisation through value creation

Connectivity will always be the bedrock of telecom. But as bandwidth becomes abundant and undifferentiated, telcos must move beyond selling “pipes” and start selling outcomes.

That means evolving from a product-centric mindset — faster speeds, bigger data packages — to a customer-centric value proposition that focuses on enterprises language and outcomes e.g., visibility, reliability, security, and predictability.

Monetisation isn’t just about launching new services; it’s also about repackaging and optimising what already exists. Whether that’s offering connectivity-as-a-service, bundling security capabilities, or embedding network insights into enterprise workflows, the goal is the same: deliver differentiated value that customers are willing to pay a premium for.

One example came from Stefan Stanislawski, highlighted how telcos can unlock profitability by embedding themselves in their communities. By supporting initiatives like the Heathfield Agricultural Show and enabling smart farming through real-time data transmission, remote monitoring, and IoT connectivity, Lightning Fibre is not just selling broadband — it’s solving real challenges for rural customers. This approach transforms the telco from a utility provider into a trusted local brand. As Stefan put it, “We want to build a community, we want to build a local brand, we want to connect to our customers in these rural areas, understand their challenges, and solve their problems.”

AI as a catalyst for profit growth

Emerging technologies — especially AI, GenAI and Agentic AI — will be the defining factor separating the winners from the laggards.

Ronan Kelly captured this shift bluntly: “there are two types of telcos — those that leverage AI, and those that don’t. The latter, are on a path to bankruptcy.” The industry is already bifurcating into two camps: those integrating AI deeply into operations and customer offerings, and those resisting it. The former will see margins expand, the latter risk irrelevance.

But AI adoption isn’t just a technology challenge — it’s a people challenge. Ronan highlighted the fear many employees feel about AI changing their roles (and how they feel as if they were cheating), Ronan linked this to the early days of Excel: “Did the person who switched from paper to spreadsheets feel like they were cheating?”

AI and automation have real impact on operational efficiency (driving down costs) and revenue enablement (enhancing targeting, personalising offerings, and uncovering new revenue streams). Operators that use AI to intelligently segment customers, tailor marketing, and optimise service delivery will achieve higher margins and stronger competitive positioning.

Dan Bloch added that AI’s real power lies in precision — enabling targeted marketing, customer segmentation, and focused sales strategies. Instead of casting a wide net, “Telcos can use AI to deliver the right message to the right customer at the right time, driving both relevance and profitability.“

Profit through partnerships and ecosystems

The B2B telecom ecosystem is undergoing significant disruption. Hyperscalers, system integrators, multicloud providers, and other non-traditional players are increasingly offering communication services — often with greater agility and deeper enterprise integration. This shift is intensifying competition and pressuring telcos in their core markets.

The result is a fragmented landscape where traditional telcos can no longer rely solely on infrastructure ownership or legacy relationships. Instead, they must rethink their role in the value chain — moving from isolated service providers to collaborative ecosystem partners. Sustainable monetisation will depend on telcos’ ability to co-create value with these emerging players, rather than compete against them in a zero-sum game.

Will Rhodes stressed that “no single operator can capture the full value chain alone. Sustainable monetisation will depend on ecosystem collaboration — where each player understands its value contribution and shares in the resulting margins.”

Whether it’s partnering with cloud hyperscalers for edge services, security vendors for managed offerings, or local organisations to build community-focused solutions, the future of telecom monetisation will be built on shared value creation rather than isolated competition.

What “good” looks like 

In this new era, successful telecom operators will:

  • Know their profitability at a granular level, including per-user margins.
  • Shift from network providers to value enablers, delivering capabilities and outcomes rather than just connectivity.
  • Use AI strategically to boost both efficiency and revenue.
  • Build ecosystems that expand value creation and customer relevance.

The operators that fail to evolve will continue competing on price — and in doing so, erode the very margins they need to survive.

Final thoughts

Telecom’s future growth story isn’t about adding more zeros to the revenue line. It’s about building a business that’s profitable, resilient, and indispensable. That requires a mindset shift — from chasing scale to maximising value, from ARPU to AMPU, and from selling bandwidth to selling outcomes.

To close the session, I asked each panellist to leave the audience with one word that captures their vision for the future of telecom:

  • Carlos → Optimise
  • Stefan → Relationship
  • Dan → Personalise
  • Ronan → Differentiate
  • Will → Partner

As the Connected Britain panel made clear, the telcos that embrace this transformation will not only monetise their networks for a better tomorrow — they’ll secure their profitability today.

AI in EMEA 2025, a recent eBook, features a section on telco. You can download it here.

For more information on AI, join our 2026 tech predictions webcast on Dec 3rd. The Agentic Business Future: Driving Resilience, Sovereignty, and Innovation in EMEA, IDC’s Tech Predictions for 2026 and Beyond.

Masarra Mohamad - Senior Research Analyst, European 5G Enterprise Strategies - IDC

Masarra Mohamed is a senior research analyst specializing in analysing the connectivity and communications services markets, focusing on the changing networking requirements, trends, and competitive dynamics that support enterprises in their digital transformation. She explores how enterprise network strategies evolve to enable cloud, AI, and security.

AI is no longer being used as just a tool to assist people. It’s becoming agentic across every industry, moving autonomously, learning adaptively, and embedding itself into the core of how organizations operate. This shift marks one of the most profound transformations in modern enterprise: the rise of agentic AI, where systems don’t just support decision-making, they make, orchestrate, and optimize it.

A recent IDC prediction reveals that by 2027, half of enterprises will be using AI agents to redefine how humans and machines collaborate. That single forecast captures what’s at stake for 2026: the agentic era. It’s an era where workflows, strategies, and even business models are being redefined by systems that learn, reason, and act across every layer of the enterprise.

The question is no longer whether AI will reshape businesses. It’s how quickly, how deeply, and how to prepare.

IDC’s 2026 FutureScape was built to answer exactly that. Through exclusive webinars, global reports, and analyst insights, leaders can see what’s next for their industries and what to do about it now.

To help organizations navigate these accelerating crosscurrents and chart a deliberate path forward, IDC’s 2026 FutureScape brings together the latest predictions, research, and foresight on the next phase of AI’s evolution.

Charting the next AI course

FutureScape 2026 is more than a collection of forecasts. It’s a navigation system for what’s ahead, a guide for leaders to anticipate disruption, steer through uncertainty, and turn turbulence into forward momentum.

Built on 35 global prediction sets across 12 industries, this year’s FutureScape explores how agentic AI will evolve from experimentation to enterprise orchestration, and what that means for strategy, technology, workforce, and trust.

Through IDC’s lens, the agentic journey unfolds as both a challenge and an opportunity:

  • Challenge: Economic volatility, regulation, and workforce disruption can quietly pull organizations off course. Fragmented AI adoption risks wasted investment and slower progress.
  • Opportunity: With deliberate navigation that aligns strategy, workforce, and tech stack, those same forces can become momentum toward resilience and growth.

FutureScape 2026 reframes disruption as a navigable current. The organizations that will thrive in the agentic era are those that see AI not as an experiment, but as the operating logic of the enterprise.

What you’ll gain from IDC’s 2026 FutureScape

Across every report and prediction, one truth stands out: AI has become the engine of enterprise transformation. The organizations that lead will treat AI as infrastructure, embedding it across decisions, operations, and customer experiences.

FutureScape 2026 identifies four powerful currents shaping this transformation:

  1. Navigating the crosscurrents of disruption
    Leaders are confronting economic uncertainty, regulatory shifts, and geopolitical turbulence. IDC’s research shows that governed, well-aligned AI can transform these disruptive forces into forward motion to fuel agility and growth instead of fragmentation.
  1. Charting the path to enterprise-wide orchestration
    Many organizations are still stuck in pilot mode. The winners will move from isolated experiments to enterprise-scale orchestration, where agentic AI operates seamlessly across data, applications, and workflows to drive continuous improvement and innovation.
  2. Building trust, resilience, and prosperity
    As AI assumes greater autonomy, trust becomes the foundation of long-term success. Responsible AI practices, transparent governance, and human oversight will differentiate the organizations that thrive from those that stall.
  3. Unlocking innovation beyond productivity
    The true promise of AI lies not in incremental efficiency but in new value creation. FutureScape 2026 highlights how agentic AI is redefining industries from healthcare to finance to manufacturing by powering new business models, products, and experiences.

Every prediction in FutureScape 2026 is grounded in IDC’s data-driven research and designed to help leaders move from insight to action.

Why the 2026 FutureScapes matter now

The 2026 reports arrive at a pivotal moment in the AI transformation journey.

According to IDC’s AI Maturity Model Benchmark, only 1% of organizations have reached the stage of an optimized, AI-fueled enterprise while over half remain in early stages of transformation.

At the same time, global AI investment continues to surge. Agentic systems are projected to account for nearly half of all AI spending by 2029, reflecting the rapid shift from tools that assist to systems that act autonomously and intelligently.

The message is clear: the future isn’t waiting. The gap between early adopters and laggards will widen quickly. Businesses that modernize their technology stacks, reskill their workforces, and embed agentic AI into strategy today will define the next era of innovation, trust, and growth.

How to access the research

IDC’s FutureScape 2026 program brings these insights to life through:

  • Global reports: Benchmark your organization against IDC’s global predictions and see where your industry is headed next. Become a subscriber to access the full reports.
  • Webinars: Join IDC analysts and explore how to make the agentic pivot and operationalize AI strategy across your enterprise.
  • Events: Connect with peers and IDC experts at regional FutureScape sessions worldwide to translate foresight into action.
  • Analyst commentary: Access quick takes, videos, and blogs linking FutureScape predictions to real-time market shifts.

Together, these touchpoints help leaders turn IDC foresight into measurable strategy, bridging the gap between understanding and execution.

Are you ready to chart the path forward?

The crosscurrents of disruption aren’t slowing down. Economic, technological, and societal forces are converging faster than ever. But with the right navigation, they can become momentum.

IDC’s 2026 FutureScape provides that compass. It reveals not only what’s coming next but how to prepare, equipping business and technology leaders with the confidence to steer through uncertainty and harness agentic AI as a force for innovation, trust, and prosperity.

Because the future isn’t being built somewhere else. It’s being built right now.

Be part of it with IDC’s 2026 FutureScape.

ROI Is the new mandate: Events are back at the center

B2B tech marketers are navigating tighter budgets and higher expectations in 2026. With ROI under the microscope, one strategy is emerging as both high-impact and measurable: events. IDC’s latest Sponsor Survey surfaces the data behind this shift, equipping marketing leaders with clarity on how and where to focus.

Events deliver real value at critical stages

This isn’t a return to events as usual. It’s a reimagining based on measurable business outcomes.

According to IDC’s 2026 Sponsor Survey of 150 senior marketers across the US, UK, Germany, and Singapore:

  • 67% rank brand awareness as a top priority
  • 53% are focused on generating qualified leads
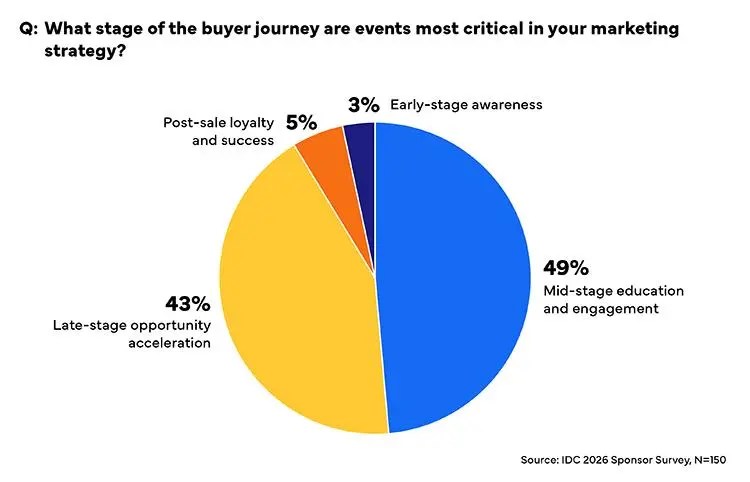
  • 90%+ say events deliver the most value in mid-to-late funnel stages

Hybrid takes the lead and the budget

The format matters, and hybrid is winning.

When asked which formats they’ll prioritize in 2026:

  • 57% of marketers chose hybrid events as their top format
  • 58% expect their event budgets to increate next year

This reflects a push for flexible, scalable, and inclusive experiences that can drive personalized engagement at scale.

What performance looks like in 2026

To prove impact, marketers are aligning event ROI with funnel-specific metrics:

Top success metrics:

  • Cost per opportunity (67%)
  • Lead quality and conversion (60%)
  • Deal influence in key accounts (43%)

Top challenges:

  • Complex execution (52%)
  • Delivering personalized experiences (42%)

Marketers aren’t just seeking impact, they need proof they can show upstream.

What marketers value most in event partnerships

Marketers aren’t just choosing events; they’re choosing strategic ecosystems. The IDC survey reveals a strong alignment between what drives investment and what defines a valuable partner.

What drives investment in third-party events:

  • High-quality lead generation (67%)
  • Credibility through association with analysts or peers (63%)
  • Expansion into new accounts or buying centers (47%)

These motivators point to one thing: marketers want more than visibility; they want validation and velocity. Events must open doors, fast-track trust, and spark meaningful conversations.

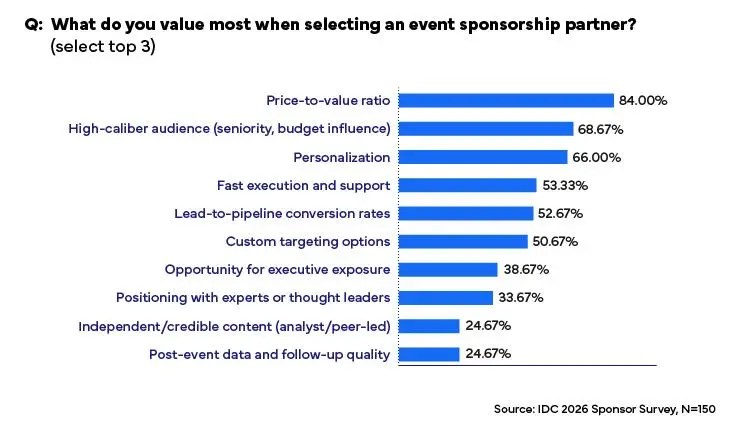
What defines the right partner:

  • Price-to-value ratio (84%)
  • High-caliber audience (seniority, budget influence) (69%)
  • Personalization (66%)
  • Fast execution and support (54%)
  • Lead-to-pipeline conversion performance (53%)
  • Custom targeting options (51%)

Insight-led content is the difference maker

The success of an event hinges on relevance. That’s why marketers are doubling down on partners who bring audience precision and analyst-backed content.

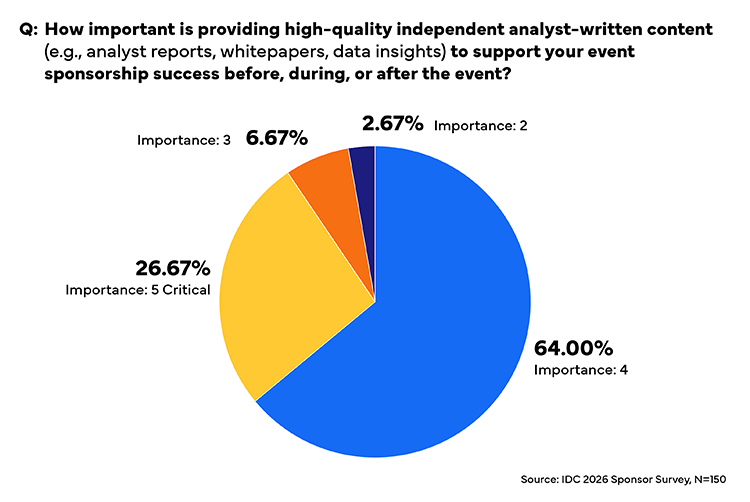
  • 91% say independent, analyst-led content is critical to event success
  • Trusted insight builds trust across every stage of engagement before, during, and after the event

Key takeaway: Price-to-value, audience quality, and credible content are top criteria when selecting event partners.

Navigate your 2026 strategy with confidence

Events are no longer standalone experiences, they’re central pillars in a broader B2B growth strategy. When backed by trusted tech intelligence, the right formats, and analyst-led content, events can help your team hit every metric that matters.

Whether you’re optimizing your event calendar or rethinking your demand strategy, IDC’s insights are here to guide your next move.

🗓️ Explore the IDC 2026 Events Calendar
Discover the best opportunities to connect with your audience with data, formats, and partnerships that work.

Jyoti Lalchandani - Group Vice President & Regional Managing Director (META) - IDC

Jyoti Lalchandani is a seasoned business executive with more than 25 years of experience in emerging markets across Europe, the Middle East, and Africa (EMEA). In his role as IDC's Group Vice President and Regional Managing Director for the Middle East, Turkey, and Africa (META), he has been instrumental in establishing IDC’s presence in the region – first, through the initial expansion of the Dubai headquarters and then by spearheading the development of IDC offices in Johannesburg, Istanbul, Riyadh, Casablanca, Lagos, Nairobi, and Cairo.

In today’s crowded tech market, features don’t sell. Value does. And yet, far too many sales teams are still stuck pushing product specs while their competitors walk away with the contracts. 

The truth? If your team can’t lead with business value, you’re already behind. 

High-performance sales teams are not created by chance. It’s not about having the loudest pitch or the biggest pipeline. It’s about building teams that can step into the boardroom as trusted advisors. Teams who can link your technology to measurable outcomes that your clients can’t ignore. 

And here’s the catch: most organisations think they’re doing this. Almost none are. 

What Does “Business Value” Really Mean in Sales? 

So, what does it really take to transform a standard sales team into a high-performing one? One that consistently sells business value as an outcome? 

In today’s technology landscape, having an innovative product is just the starting point. What truly sets successful tech vendors apart is their ability to demonstrate clear, measurable business value and return on investment (ROI) to their customers. 

To get there, marketing, sales, and sales enablement leadership must work together to build strong messaging, market insights, and client success stories that can be leveraged in customer interactions. Leading the discussion on what the company can do for the customer and then quantifying the value of that partnership, builds trust and sets a high-performance benchmark. 

How to Equip Sales Teams to Lead with Value 

Not all enterprises can align every salesperson to a consistent value message for each product or service. Salespeople bring a range of individual styles into their relationships, but what unites them is the focus on building trust and instilling confidence in their solutions.  

Despite this need, many organisations lack the experience to develop value-based messaging, collateral, and enablement programs that bring this confidence to life. Creating alignment across teams requires structure, expertise, and the right insights. 

How IDC Helps Sales Teams Sell on Business Value 

At IDC, we work with technology vendors worldwide to strengthen their ability to sell based on business value and tangible outcomes. Our analysts and consultants deliver market insights, benchmarks, and customer validation that empower marketing, sales, and enablement leaders to align around proven value delivery. 

Through tailored sales enablement workshops, value-based messaging frameworks, and analyst-led collateral, IDC equips teams to engage customers with confidence and demonstrate measurable ROI. Get in touch to learn more. 


Nathan Budd - Senior Director, Custom Solutions - IDC

Nathan Budd is a consulting director, working across strategic, market intelligence and go-to-market solutions. With experience across a spectrum of ICT projects and clients, he delivers a breadth of knowledge and insight to the IDC European consulting team. Over the years, Nathan has worked with CEOs, industry forums, executives and sales teams, to define market strategy, positioning and sources of revenue growth. He is an experienced speaker, project lead and facilitator, bringing energy and perspective, while maintaining the connect between strategic-level thinking and grass-roots action.

A market that demands its own perspective

IDC today published the European Contact Center-as-a-Service (CCaaS) MarketScape, recognizing that Europe’s contact center landscape is shaped by unique regional dynamics, stringent regulatory frameworks, and a more measured approach to adopting new technologies. These characteristics make it essential to evaluate Europe as a distinct market rather than as an extension of global models. Success in this region depends on understanding trust, compliance, and local engagement at a much deeper level.

A market defined by diversity and regulation

The European CCaaS market is expanding rapidly, projected to grow from US$1.5 billion in 2024 to US$3.7 billion by 2029. Yet, it remains highly diverse and fragmented. Differences in regulation, business culture, and language shape how contact centers operate and adopt technology. For example, priorities such as pricing, professional services, and data residency vary widely across key markets, underscoring the importance of regional insight and tailored strategies over a one-size-fits-all approach.

Why a European MarketScape matters

The IDC European CCaaS MarketScape provides an in-depth assessment of how vendors address this diversity. It evaluates how effectively they align their strategies and offerings with Europe’s regulatory, cultural, and operational realities.

It also considers how vendors demonstrate thought leadership — not by simply leading with innovation, but by helping contact centers modernize responsibly. This includes educating customers on the value of digital transformation, offering support to overcome adoption barriers, and using partnerships to bridge linguistic and cultural gaps while building trust.

By capturing these nuances, the IDC European CCaaS MarketScape delivers a region-specific perspective that reflects the complexity, diversity, and maturity of Europe’s contact center ecosystem — and highlights the industry’s steady evolution toward AI-driven, compliant, and customer-centric operations.

IDC MarketScape: European Contact Center-as-a-Service Applications Software 2025 Vendor Assessment is available now.

If you have a question about anything, please fill in this form.

Oru Mohiuddin - Research Director - IDC

Oru Mohiuddin is a Research Director in the European Enterprise Communications and Collaboration team. Based in London, she is responsible for IDC’s coverage of Unified Communications and Collaboration in the region. Her work focuses on tracking the markets for premise-based and cloud solutions and new developments and trends, particularly in the light of changing work patterns impacting the traditional mode of enterprise communication. Prior to joining IDC, Oru worked for Euromonitor International, where she focused on Future of Work and technology in the SMB context. She also worked in New York and Bangladesh and speaks English and Bengali. Oru was awarded Chevening Scholarship by the British Foreign and Commonwealth Office to pursue her MSc in International Development from the University of Birmingham. In addition, Oru has a BA from Marymount Manhattan College in New York.

In a world where tech decisions move markets, the analyst voice carries more weight than ever. But for many organizations, analyst engagement remains a missed opportunity; seen as a checkbox instead of a strategic lever. If you’re still treating analysts as one-way validators, it’s time to rethink your approach. 

Welcome to the new era of analyst relations: where influence is earned, insight is mutual, and every interaction can shape the market. 

Analysts don’t just observe the market, they help shape it

Analysts aren’t just keeping score. They inform buyer decisions, guide vendor roadmaps, and influence how innovation gets adopted. They hold the power to elevate your story or challenge it at critical moments in the buyer journey. 

Yet too many organizations treat analyst engagement as reactive—a scramble before a report, a briefing once a quarter, a missed chance to shape perception. 

Here’s the truth: Proactive analysts engagement shapes the market.

The risk of misalignment: When narratives don’t match

When your public story says one thing, but analysts say another, the disconnect stalls deals, confuses customers, and erodes trust. 

Why it matters: IDC research shows that C-suite buyers increasingly rely on analyst validation to guide high-stakes decisions. If analyst commentary doesn’t reinforce your core message, you’re not just invisible, you’re at risk of disqualification.

From engagement to influence: 3 rules for analyst relations that work

1. Lead with evidence, not ego

Skip the hyperbole. Analysts are data-driven thinkers. Give them what they need to validate your claims: proof points, customer results, trend alignment, and most importantly, the “so what.” 

2. Treat analysts as strategic allies

Briefings shouldn’t just be broadcasts. The best relationships are built on transparency and dialogue. Let analysts challenge your thinking; they’ll help sharpen your go-to-market message. 

💡 Use IDC’s Tracker® and Black Book data to anticipate market shifts before your competitors do, and invite analysts into the conversation early. 

3. Align internally first

Mixed signals across sales, marketing, and product derail analyst relationships. Build a unified, evidence-backed narrative that connects the dots between your product roadmap, market opportunity, and customer value. 

💡 IDC helps companies create that shared view, grounded in trusted tech intelligence and aligned across GTM functions. 

Why it pays off: Analysts influence in action

Organizations that invest in strategic analyst relations aren’t just better positioned in reports, they’re better aligned with buyer expectations, more credible in competitive cycles, and more confident in their decisions. 

And confidence is contagious. 

Get started: Make every analyst interaction count

You can’t control what the market says. But you can shape who says it—and how they say it. Engage analysts not as observers, but as partners in market influence. 

Let’s build your analyst strategy to win in 2026; on purpose, with purpose. 

Do you subscribe to Netflix or own a Labubu plush toy (or bought one for your kids)? The influence of Netflix is clearly pervasive now, thanks to its several blockbuster productions like the Korean-produced Squid Game. Meanwhile, Pop Mart’s Labubu is ubiquitous and sought by celebrities from K-pop BlackPink’s Lisa to David Beckham. But how does Netflix’s well-known subscription model relate to Labubu? The short answer is the Experience Economy, and we will dive deeper into that idea below.

The subscription model was successfully leveraged by Samsung and LG for their hardware businesses, moving beyond the traditional use in media and entertainment. The success was seen in both home appliances and consumer electronics. LG achieved more than one trillion Korean won (US$714.3 million) in global sales from its subscription programs in 1H25 for its white goods and PC products. Meanwhile, Samsung launched the “AI Subscription Club” and the “New Galaxy AI Subscription Club” in Korea. The former, which is designed for home appliances, PCs, and tablets, generated over 100 billion Korean won (US$71.4 million) in monthly revenue.

Admittedly, Samsung’s “New Galaxy AI Subscription Club” is not a traditional subscription program, but it serves a similar purpose, that is, prompting the users to return the used products. Here’s how it works. Consumers buy smartphones outright or with an installment plan, and they have the option to subscribe to the program with a monthly fee that ranges from 5,900 to 8,900 Korean won (US$4-$6). The program promises cash payment of 50% of the device’s reference price if consumers return their used smartphones after 12 months (40% if returning after 24 months). The subscription program also includes various perks such as repair services, accessories, and discounts from Samsung’s cooperating partners.

Despite its non-traditional attribute as a subscription program, Samsung correctly tapped into the opportunities of the Experience Economy, where consumers are shifting away from ownership and valuing experiences over the practical benefits of products. By paying less than 9,000 Korean won (US$6) per month, consumers can look forward to an “upgraded experience” with a new smartphone in one or two years, with the purchase price reduced by the promised cash payment for their used devices.

“Samsung’s New Galaxy AI Subscription Club allows consumers to return their smartphones for a promised cash payment. This blurs the concept of ownership by gradually building a habit of returning used devices, a practice to which consumers are increasingly adapting,” said Jihae Kang, research analyst for Client Devices at IDC Korea. “Experience Economy tells us that product ownership no longer assures high customer satisfaction. Instead, customers place greater value on the memories or feelings a product offers. Ultimately, this strengthens the shift toward experience-driven consumption.”

To be sure, many financing plans also make new smartphones more affordable by letting consumers pay in instalments over as long as 36 months. This raises the question: what are the differences between financing plans and subscription models? From the smartphone OEMs’ perspective, the benefit of a subscription is to shorten the replacement cycles by prompting subscribers to replace their phones earlier. A good way to illustrate it is to take an example of a 24-month financing plan and a 3-year smartphone replacement cycle. The user may continue to hold the device after paying off the instalments. Nevertheless, Samsung’s subscription programs will encourage a phone replacement in one or two years as users return the devices for the promised cash payment.

Furthermore, for consumers, it could be mentally easier for some of them to get a subscription instead of another “loan,” especially if they are already burdened by a mortgage and/or car debt.

In the increasingly saturated and highly competitive smartphone market, building brand loyalty has never been more crucial. What a subscription program could also potentially achieve is to help keep consumers excited by ensuring they have first-hand experience with the latest products and technology in a shorter cycle. Essentially, it’s about constantly offering emotional value, which is what consumers are seeking nowadays and which shapes the fundamentals of the Experience Economy.

Therefore, the ultimate goal is to create the “Labubu effect,” which keeps the excitement among consumers and, in turn, leads to stronger customer stickiness and ideally creates a word-of-mouth effect or social buzz. And the subscription model could be used as a tactic to ensure consumers personally experience the latest products instead of only being flooded with information from social media or news sites.

“The typical 3- to 4-year smartphone replacement cycles are creating challenges for the smartphone OEMs,” said Will Wong, senior research manager for Client Devices at IDC Asia/Pacific. “It’s not only about selling fewer devices, but it’s also hard to keep users captivated.”

Of course, it won’t be an easy task to initiate the subscription model, especially since it changes the business model and probably the cash flow timing. Nevertheless, the favorable uptake of Samsung’s subscription programs indicates a positive potential beyond Korea, especially since economic challenges are turning global consumers into value seekers and prompting them to seek comfort and excitement (i.e., emotional value). Furthermore, the smartphone OEMs could generate hardware revenue as long as the subscribers are using the devices, which optimizes the predictability of earnings and customer lifetime value. And the most compelling potential is its long-term effect in bringing the technology excitement to the users and ultimately creating the “Labubu effect.”

Jihae Kang - Research Analyst - IDC

Jihae Kang is an Research Analyst with IDC Korea. She is responsible for research on the tablet, mobile phone, and enterprise client device markets in Korea. Her research coverage includes market sizing and forecasting with analysis based on the market trends, and the macroeconomic and social factors. She is also involved with local report programs such as Smart Connected Device. In addition, Jihae engages in Future of Customers and Consumers, and provides insights into and analysis of consumer views in the digital transformation era.

As AI reshapes Martech and Adtech, pricing is shifting from technical inputs and usage metrics to measurable business outcomes. This isn’t just about covering AI’s costs, it’s a strategic opportunity to stand out in a crowded, commoditized market.

Legacy pricing models, flat-rate, usage-based, tiered, per-user, can’t keep up with AI’s compounding, often invisible value. AI automates, optimizes, and delivers insights in ways these models were never built to capture. In this environment, pricing itself becomes a competitive weapon.

For both buyers and vendors, this is more than a tactical adjustment. It’s a chance to redefine expectations, relationships, and what ROI really means in AI-powered marketing and advertising. This article breaks down why the old playbook fails, what’s replacing it, and how smart vendors can turn pricing into a market differentiator.

Why Traditional SaaS Pricing Breaks in an AI World

The familiar pricing playbook wasn’t built for AI:

  • Flat-rate models treat a static software package the same as one that’s constantly learning and optimizing, leaving both value and revenue on the table.
  • Usage-based models miss the mark because AI’s value isn’t about how many queries you run or emails you send. It’s in the decisions made, outcomes improved, and time saved.
  • Tiered pricing quickly becomes outdated as AI capabilities advance, creating misalignment between what customers need and what they’re paying for.
  • Per-user models overlook AI’s ability to amplify small teams. AI does much of its best work invisibly, unlinked to logins or headcount.
  • Feature-based and credit-based models struggle with AI’s unpredictability and variability. Locking customers into fixed credits or feature bundles risks alienating them when AI’s true value lies in flexibility and continuous improvement.

The bottom line: AI fundamentally changes how value is created, and old pricing models can’t capture it.

The Case for AI-Driven, Value-Based Pricing

AI fundamentally changes the economics of Martech and Adtech platforms, and pricing needs to reflect that shift. Traditional models charge by seats, queries, or feature bundles, but AI delivers value in compounding, often invisible ways: automating decisions, uncovering insights, accelerating campaigns, and improving business outcomes. Vendors that fail to align pricing with these benefits risk undervaluing their products and alienating customers.

Value-based pricing ties costs to clear, measurable business outcomes. Instead of billing by usage or features, vendors price based on metrics like:

  • Conversion rates and revenue growth
  • Customer engagement and retention improvements
  • Operational efficiencies and cost reductions
  • Faster time-to-market for campaigns
  • Risk mitigation and data accuracy gains

For example, a predictive AI personalization tool might charge based on uplift in campaign ROI or increase in customer lifetime value rather than by audience size or impressions served.

To support this, vendors should move beyond flat subscriptions and introduce AI-specific pricing tiers. Basic levels might cover standard automation, while premium options unlock advanced capabilities like real-time personalization, media mix modeling, or predictive lead scoring. This allows customers to scale investment in line with the value AI delivers.

Additionally, vendors should leverage dynamic pricing models that evolve alongside the customer relationship. AI-powered solutions improve over time, pricing should, too. Regularly reviewing customer outcomes, benchmarking against performance targets, and adjusting pricing accordingly ensures long-term alignment and value capture.

New pricing levers also come into play. Vendors can quantify AI’s contributions by measuring:

  • Net-new revenue opportunities unlocked by AI features
  • Productivity gains through automated workflows
  • Competitive advantages like faster insights or superior targeting
  • Customer loyalty improvements from AI-driven personalization

These are tangible, defensible metrics that buyers care about and that vendors can tie directly to pricing structures.

Ultimately, AI-driven, value-based pricing is a strategic weapon. It deepens customer relationships, differentiates vendors from commoditized competitors, and ensures that pricing keeps pace with AI’s accelerating impact.

What It Takes to Make Value-Based Pricing Work

Implementing value-based pricing requires more than clever packaging; it demands organizational change. Pricing strategy can’t live in finance alone. It belongs in customer success and strategy teams, focused on long-term outcomes, not one-off sales.

Continuous feedback loops are crucial. AI-powered solutions evolve fast and pricing must adapt just as quickly. Vendors need to regularly evaluate performance, update pricing as capabilities grow, and maintain open, outcome-focused customer conversations.

To support this, vendors should expand pricing levers beyond the usual suspects. AI’s ability to unlock new revenue streams, increase market share, and boost differentiation should factor into pricing. Vendors must account for AI’s impact on productivity, risk reduction, and loyalty areas traditional models often ignore.

Technology End User (Buyer) Considerations. 

For Martech and Adtech buyers, this shift means focusing on outcome alignment and vendor accountability. Buyers should prioritize:

  • Vendors offering outcome-driven pricing models — like Experience Level Agreements (XLAs) — that emphasize ongoing performance, not static commitments.
  • Vendors who demonstrate clear, measurable business value — whether through native features or integrated ecosystems.
  • Flexibility and transparency — no one wants to decode AI credits or compute hours. Vendors win by stripping away jargon and clearly stating what outcomes they deliver, and what it’ll cost.

Conclusion

AI is forcing both vendors and buyers to rethink value and pricing. Traditional models can’t keep up with AI’s dynamic, invisible, and compounding business impact. Outcome-based and value-driven pricing approaches are quickly becoming essential for anyone hoping to compete.

Vendors that treat pricing as a strategic lever not a back-office task will outpace competitors and lock in long-term advantage. The real winners in AI-powered Martech and Adtech will be those bold enough to rethink what customers pay for, why it matters, and how to turn pricing into a lasting market differentiator.

Roger Beharry Lall - Research Director, Marketing Applications for Growth Companies - IDC

With over 25 years' experience leading technology driven marketing programs, Mr. Beharry Lall is now a Research Director with IDC covering Advertising Technologies and SMB Marketing Applications. He brings a unique multidisciplinary perspective, evangelizing the innovative and pragmatic use of both martech and adtech solutions for companies of all sizes. Early in his career Rog worked with an IBM subsidiary expanding into the Asian Market and subsequently, he spent over a decade at RIM (BlackBerry) building marketing leadership across new industry segments, geographies, and product categories. This background fuels his perspective as he researches enterprise customers engagement tools and tactics across the unified omnichannel.

AI is no longer just a feature in your product. It’s part of how your buyers behave and interact with your brand.

While your team has been working hard to build AI into services and solutions, buyers have been sharpening their own AI skills too. AI is now embedded in how they research, evaluate, and validate decisions.

In this new landscape, it’s not the companies that simply offer AI that stand out. It’s the ones that know how to market it and use AI to their advantage.

So if your product is changing, and your buyers are changing, it is time for your go-to-market (GTM) strategy to change too.  

Why marketing feels the squeeze

This can cause a lot of pressure on marketing teams who are already battling against competing demands from executives:

  • CEOs expect bolder innovation and faster growth.
  • CFOs want clear ROI from AI investments.
  • CIO/CTOs demand secure integration aligned with technology roadmaps.

As a result, marketings role is expanding dramatically. Teams must now own buyer intelligence, ensure they stand out in a saturated market, and orchestrate a connected journey across digital and human interaction.

Without recalibration, these demands can overwhelm marketing. But with the right insights, the pressure cascade becomes a launchpad for momentum and leadership.

Your product changed. So did your buyer.

Once AI was built into solutions, buyers not only began to accept it, they started to expect it with competitors following suit. Now, with buyers leveraging AI on their side, the rules of engagement have shifted.

Sixty-nine percent of buyers will only engage with content that feels personalized. That means messaging and approach needs to change. It’s about creating the right messaging that reaches the right buyer, at the right time, in the right channel, and in the right format.

And it’s not only one buyer anymore. Modern buying committees can include VPs of customer experience, VPs of cybersecurity, heads of data and AI strategy, and IT procurement managers.

Each of these stakeholders approaches the journey differently and enters at a different stage. If your strategy doesn’t account for each one, it can derail the deal. Marketings job is to anticipate, tailor, and orchestrate messaging for all.

Understanding who is in the buying committee is only half the challenge. The other half is keeping pace with how they buy. AI has made the journey more fluid, more self-directed, and spread across countless touchpoints—all of which buyers expect to feel connected.

The AI-assisted buyer journey

Understanding who is in the buying committee is only half the challenge. The other half is keeping pace with how they buy. AI has made the journey more fluid, more self-directed, and spread across countless touchpoints—all of which buyers expect to feel connected.

Today’s buyer journey is fluid, AI-assisted, and omnichannel. IDC research shows that buyers seamlessly move between digital and human touchpoints: reading analyst reports, attending webinars, engaging with ads, visiting websites, and testing self-service tools.

At the same time, they use AI to weigh trade-offs, simulate outcomes, and filter vendors before sales ever enter the picture.

Success isn’t about being everywhere. It’s about making each interaction intentional. A diagnostic tool can help uncover a blind spot. A webinar can reframe strategy. And a sales conversation can build directly off of what buyers have already explored.

When every step feels orchestrated, you remove friction and create momentum in the journey.

Recalibrate your GTM journey

So what does that recalibration look like?

  • Build a buyer-first intelligence engine
    Move beyond assumptions. Use real-time signals and verified insights to guide your strategy.
  • Differentiate with outcomes, not features
    Everyone has AI. The winners will frame their solutions around measurable customer impact.
  • Orchestrate across personas and channels
    Ensure handoffs don’t become gaps. Design transitions that feel intentional, not accidental.
  • Align across the business
    Sales, product, CX, and marketing must share the same buyer narrative. Without alignment, execution fractures. With alignment, you unlock momentum.

Those who start recalibrating today won’t just keep pace with change, they will define it.

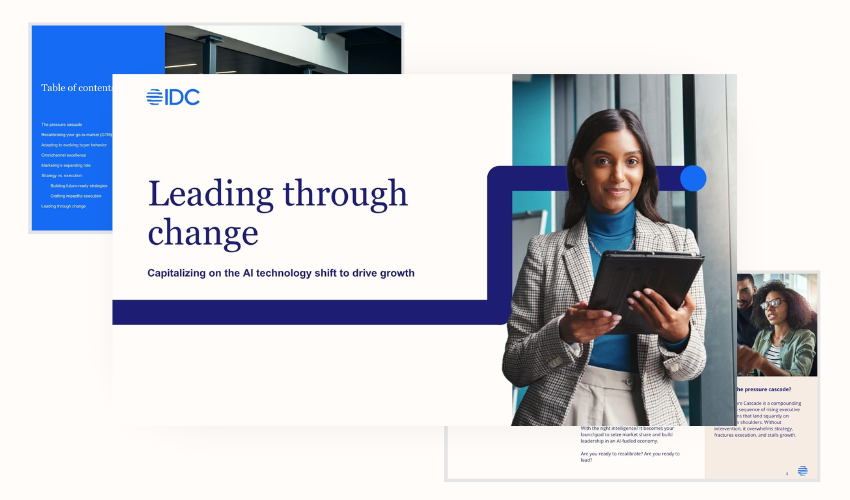
Download the IDC eBook Leading Through Change to learn how to recalibrate your GTM with real buyer intelligence, omnichannel excellence, and outcome-driven differentiation.

Christina Cardoza - Content Marketing Manager - IDC

Christina Cardoza is a Content Marketing Manager at IDC, where she specializes in brand content and social media strategy. With a background in journalism and editorial leadership, she has a proven ability to transform complex technology topics into clear, actionable insights.