Today we launched IDC Quanta. I led the strategy behind it, working closely with our product, research, and engineering teams to turn a point of view into something real. I want to share what building it taught me about the state of AI adoption, not just at IDC, but everywhere.

The number that started it

By 2029, there will be a billion AI agents running inside enterprises worldwide. That translates into an enterprise running thousands of agents. The investments to prepare for that future are already taking place. Hyperscalers are increasing AI infrastructure spend from $54 billion in 2023 to $800 billion by 2029 to create inference capacity at that scale. Enterprises are spending $400 billion on AI platforms, apps and services this year, headed toward a trillion by 2029.

Most enterprises can’t orchestrate at that scale today. Most vendors can’t fully support it yet either. A billion agents means the entire IT industry, vendors and enterprises together, has a massive amount of infrastructure, governance, and orchestration work still ahead of it before that number is something to be excited about instead of something to be worried about. We didn’t want IDC standing outside that work, measuring it from a distance. We wanted to build the intelligence layer that helps our clients get through it. That’s the thinking behind Quanta.

The gap we kept running into

Earlier this year, we ran our global AI maturity benchmark. In the U.S., the largest single group of organizations, 39%, sits at what we call the AI Pivot stage. They’ve moved past ad hoc experimentation. They have momentum and intent. But they’re still reacting to use cases as they surface instead of executing against one enterprise strategy.

That gap comes down to a problem our team designed against from the start: islands of AI. Fragmented experimentation across functions that makes enterprise-level orchestration nearly impossible. Half of organizations have an AI roadmap defined at the functional level. Finance has one. IT has one. Marketing has one. They don’t connect. There’s no shared prioritization and no way to see where one function’s work could accelerate another’s.

The reason this is more than a coordination problem is because agents don’t respect functional boundaries. A customer service agent needs data from CRM, from order management, from your knowledge base. An operations agent touches supply chain, finance, and procurement. The moment you deploy agents that work across functions, a fragmented roadmap becomes an architectural blocker. It’s why 42% of CEOs plan to hire a Chief AI Officer in the next year. They’re looking for someone who can see the whole board, not just their own function’s piece of it.

We had our own version of this problem to solve. For decades, IDC’s model was research in one place and data in another, and clients had to hunt across both to get a full picture. Quanta brings our research and our data together in a single platform, so that fragmentation stops being something you have to solve every time you come to us.

The curve nobody wants to admit they’re on

For the past three and a half years, enterprises have struggled to prove the ROI on their AI use cases. Now we have runaway token costs arriving at the exact moment everyone is lining up to deploy agents.

IDC recently published a report on effective agent cost management. In the report, the team showed cost per action spikes early in almost every deployment, before value catches up. We call that phase High Anxiety. Value climbs slowly the whole time, crossing cost at what we call the Strategic Alignment phase. Past that point, cost keeps falling and value keeps climbing. That’s the payoff phase.

Most organizations in this industry are still on the wrong side of that curve. The token economy conversation isn’t about whether AI is worth the spend. It’s about how long it takes you to get through the High Anxiety phase. The organizations pulling ahead are the ones treating ROI as a discipline, not a one-time calculation. A cost model that only counts inference will undercount true total cost of ownership by 30 to 60%. The shift that matters is treating tokens like a raw material, the way a factory tracks cost per unit, instead of like a technology bill.

That framework is one example of the kind of intelligence Quanta is built to deliver. Not a report waiting to be opened weeks after it would have mattered. Something you can reach directly at idc.com, or through connectors built into the platforms your team already uses, so the intelligence shows up where the decisions and execution happens instead of sitting in a document.

Why I’m telling you this today

Quanta didn’t come from spotting a market opportunity from a distance. It came from our team solving the exact problem I just described, for our own organization, alongside the people who build and research this every day.

For decades, our model was simple: we publish research, and you come find it. That worked when the pace of decisions making was slower. It doesn’t work anymore, not with a billion agents coming and the decisions being made this year that companies will live with for years. We built Quanta to work two ways. Come to idc.com directly for grounded, evidence-based answers. Or reach that same intelligence through connectors already built into the platforms your team uses, so you’re not switching context.

I’m proud of what we’re launching today. But the thing I actually want you to take from this is the reminder that the gap between where your organization is and where it needs to be closes the same way ours did: someone has to own the whole board, and go get the intelligence instead of waiting for it to come to you.
Meredith Whalen - Chief Research Officer - IDC

As IDC's Chief Product, Research & Delivery Officer, Meredith Whalen leads the company's global product, research and data, and delivery organizations. Under her leadership, IDC delivers cutting-edge intelligence to the world's leading technology vendors, enterprises, and investors as they navigate the evolving AI economy. Meredith sets the strategic direction for IDC's global analyst community, shaping research methodologies and agendas that generate industry-leading data and actionable insights to drive high-impact business decisions. With more than 20 years at IDC, Meredith has been a catalyst for some of the company's most transformative initiatives. She founded IDC's Industry Insights and Tech Buyer business units and pioneered the industry's first comprehensive business use case taxonomy. She also led the creation of IDC's DecisionScape methodology-a strategic framework that empowers organizations to better plan, implement, and optimize their technology investments. A recognized thought leader and sought-after speaker, Meredith regularly delivers keynotes at major global technology events and advises senior executives on the trends shaping the future of business and technology. Meredith holds a B.A. with honors from Wellesley College and an MBA with honors from Babson College's F.W. Olin Graduate School of Business.

I spent much of my career helping organizations operationalize customer and employee intelligence. During that time, I watched an entire industry emerge around dashboards.

Companies invested billions collecting customer feedback, employee sentiment, operational metrics, and business intelligence. Entire software categories were built around helping organizations visualize that information and drive action.

The model worked extraordinarily well.

Companies like Qualtrics, Medallia, Tableau, Salesforce, and many others helped define a generation of enterprise software. But over time, a pattern emerged.

The problem was never collecting the data; the problem was getting people to use it.

Organizations spent years trying to encourage executives, managers, and frontline employees to regularly log into dashboards, review reports, identify issues, and take action.

Adoption became a business problem unto itself. The intelligence existed, but the behavior did not.

The hidden cost of dashboards

The challenge with dashboards is simple: they require users to interrupt their workflow.

Every dashboard assumes a user will:

  1. Stop what they are doing.
  2. Open a separate application.
  3. Find the relevant information.
  4. Interpret it.
  5. Decide what to do next.

That process creates friction, and friction is the enemy of adoption.

Today, most professionals spend the majority of their time in a handful of environments:

  • Email
  • Teams
  • Slack
  • CRM platforms
  • ChatGPT
  • Claude
  • Productivity applications

These have become the operating systems for modern work. Every additional application competes for attention against those environments, and most lose.

AI changes the equation

Large language models have created a new interface for work, allowing users to interact with intelligence through natural language rather than reports, dashboards, and portals. For the first time, intelligence no longer needs to live in a separate destination. Instead, it can travel directly to the user.

An executive can ask a question inside ChatGPT.

A seller preparing for a customer meeting can instantly surface market trends, competitive threats, and analyst insights directly within Salesforce.

A product leader can receive market insights through Teams.

A strategist can query complex research through an AI assistant.

The user never leaves their workflow, because the intelligence comes to them. This represents more than a user experience improvement: It’s about introducing a fundamentally different operating model.

The goal isn’t simply better intelligence. It’s reducing the friction between intelligence and action.

Why proprietary data matters more than ever

Many organizations believe AI itself is the competitive advantage. I believe the opposite.

As models become increasingly accessible, the differentiator will be intelligence.

Organizations that possess unique, proprietary, trusted data will have a significant advantage because they can combine AI with insights that cannot be found on the open internet. That’s exactly what makes this moment so rich with potential.

At IDC, we have decades of proprietary market intelligence: market sizing data, competitive positioning, technology adoption trends, vendor performance data, industry forecasts, and strategic research.

These are the datasets organizations use to make billion-dollar decisions. Historically, customers accessed that intelligence through reports, portals, and analyst interactions.

Today, AI allows us to reimagine how that intelligence is consumed.

From intelligence systems to decision systems

The next evolution is bigger than dashboards, and it’s bigger than reports. It’s even bigger than AI assistants.

The real opportunity is creating a technology intelligence layer that connects:

  • Market intelligence
  • Customer intelligence
  • Operational intelligence
  • Financial intelligence
  • First-party enterprise data

When those signals come together, organizations gain a more complete view of their markets, customers, competitors, and business performance. At that point, we are no longer talking about a research platform, but a new decision system.

IDC Quanta was built around this idea: bringing trusted technology intelligence directly into the workflows where decisions are made.

The organizations that win in the next decade will not necessarily have the most data, but they will have the least friction between intelligence and action.

Dashboards are dead because intelligence no longer needs a destination. It can travel directly to the moment of decision.

Nick Mercurio - Chief Revenue Officer - IDC

Chief Revenue Officer As Chief Revenue Officer of IDC, Nick Mercurio leads the company’s global commercial organization, including Sales, Customer Success, and Revenue Operations. He is responsible for accelerating growth, expanding customer value, and advancing IDC’s position as the technology intelligence layer of the AI economy.

Right now, the world is generating more than seven petabytes of data every second. That’s roughly the equivalent of producing 17 billion books every second. By 2029, that number will more than double. And that’s before more than a billion AI agents come online, each one generating, consuming, and amplifying information at machine speed. [IDC Global DataSphere Forecast, 2025–2029]

We’re drowning in information.

But more data doesn’t mean more clarity. In fact, it’s quite the opposite. Most of what’s flooding in isn’t even original; it’s copies, reprints, and regurgitations. And AI can make even bad data look very convincing.

In a world where noise is growing and clarity is fading; the biggest challenge enterprises face is discerning what’s real from what’s just an echo.  The winners won’t be the organizations with the most data. They’ll be the ones with frictionless access to the truth — and the confidence to act on it.

Today, IDC is delivering that with IDC Quanta, the technology intelligence fabric of the AI-enabled enterprise. For more than 60 years, organizations around the world have trusted IDC to help them navigate technology decisions and deliver data-backed intelligence to sharpen business strategies.

IDC Quanta takes the same structured, sourced, defensible insights, pairs them with your data and context, and puts them inside the tools your teams already use. A process that previously required disjointed systems, manual synthesis, and endless hours is now relevant, citable, and frictionless.

Intelligence embedded where you work

IDC Quanta lives inside email, inside Anthropic’s Claude AI, and inside the custom AI tools and workflows enterprises are building right now. No portal or separate login required. No need to leave the tools or workflows you’re already in. Instead, IDC Quanta gives you the ability to call on its intelligence the moment you need it — whether that’s a competitive client deal on the line, a board presentation, a roadmap under review, or vetting a new software platform.

Intelligence built on your context

Upload your own data and documents, and IDC Quanta synthesizes and visualizes them alongside IDC’s research in a single session. Adding to that is an extensive memory layer that ensures every conversation deepens what IDC Quanta knows about your role and your priorities, making each answer it returns sharper than the last. Your business context, combined with IDC’s, gives you a fuller picture than either could produce on its own.

But there’s something else important to note when it comes to context, and that’s security. With more than 175 beta customers helping us shape IDC Quanta’s development, the questions we heard most were simple: is loading data and documents secure, and are those documents used to train the model? The answers are “yes” and “no, respectively. Every upload lives in a private workspace with AES-256 encryption, enterprise-grade compliance and privacy controls, is automatically deleted after 90 days, and is never used to train IDC’s models. That means the confidence IDC Quanta gives you never comes at the cost of what you shared to get it.

Intelligence you can defend

Every response IDC Quanta gives runs through a multi-agent system that validates it against IDC’s 15B proprietary data points and expert-led research before it ever reaches you. An expandable reasoning panel shows exactly how the answer was built and includes detailed citations for answers you can stand in the boardroom and defend.

Intelligence on your schedule

IDC Quanta doesn’t wait to be asked. Automated scheduling capabilities enable IDC Quanta to proactively deliver the intelligence you need to monitor with regularity and then goes a step further, surfacing anonymized peer signals and related follow-up questions you didn’t know to ask.

An exciting future

IDC Quanta is live today and available to all current and new IDC customers. It was Amarok CIO Ashley Spicer who said it best:

“We are getting ridiculous, previously unimaginable value from IDC Quanta.  If you had told me 20 years ago that I would have access to something like this in my lifetime, I would have said no way. Our team is creating massive value by fielding questions and guiding understanding for critical decisions and strategic programs.”

With more integrations, more use cases, and packages tailored specifically for CIOs and IT leaders arriving this August, we’re just getting started. Intelligence will never be the same.

Visit www.idc.com/quanta to see it for yourself.


Lorenzo Larini - Chief Executive Officer - IDC

Chief Executive Officer of IDC, responsible for leading the company’s global strategy, operations, and growth. Lorenzo brings more than two decades of experience across the Research, Advisory Services, Enterprise Software, and AI sectors, most recently serving as CEO of Mint.ai, where he led the development of AI-driven workflow solutions. Previously, he served as CEO of Ipsos North America, where he led transformative growth for one of the world’s top market research and data analytics firms. He has also held global senior executive roles in Gartner’s technology division, including SVP of Executive Programs, advising global CIOs and enterprise leaders on digital transformation and operational excellence.

随着AI和智能体在企业业务、生产和办公场景中的广泛应用,零信任网络访问(ZTNA)解决方案不仅要防护传统用户和设备,还需针对AI模型、自动化智能体、API调用等新型主体进行身份认证、访问控制和行为审计。AI和智能体已成为新的访问与攻击面,ZTNA架构必须扩展至“人+设备+AI Agent”统一治理,防范AI身份伪造、越权访问、提示注入等新型风险。

与此同时,AI技术正深度赋能ZTNA解决方案。通过行为分析、风险建模、自动化策略生成和智能响应,AI显著提升了ZTNA的动态风险感知、异常检测、自动化运营和复杂场景下的安全决策能力。AI不仅是防护对象,更是能力跃迁的驱动力,使ZTNA成为智能体时代企业安全治理的核心平台。

零信任理念已成市场普遍认知

在全球数字化转型、云化和远程办公常态化的推动下,企业IT架构正快速从传统集中式数据中心模式,演进为覆盖云、多云、SaaS、边缘计算与第三方生态的分布式体系。业务边界、访问边界和数据边界不断模糊,传统“内外网边界”安全模型逐渐失效。攻击面扩展至终端、API、云工作负载、供应链及AI应用生态,网络安全风险高度动态化和复杂化。身份滥用、会话劫持、权限滥用成为主流攻击路径,“身份即边界”成为行业共识。

零信任理念(ZTNA)以“永不信任、持续验证”为核心,通过身份、设备状态、行为上下文和风险态势的动态访问控制,替代静态信任模型,成为企业安全架构升级的主流方案。中国企业对零信任的认知度和接受度已广泛提升,ZTNA逐步成为企业现代安全访问控制的主流方案。

中国ZTNA市场规模与竞争格局

近日,国际数据公司(IDC)发布了针对中国零信任网络访问(ZTNA)解决方案市场的一系列报告:

  • IDC MarketScape:中国GenAI赋能的零信任网络访问解决方案2026年厂商评估
  • 中国零信任网络访问解决方案市场份额,2025
  • 中国零信任网络访问场景之软件定义边界市场份额,2025
  • 中国零信任网络访问场景之终端安全市场份额,2025

通过这些研究对中国ZTNA整体市场和主要细分市场的规模、产品发展现状和技术发展趋势,以及市场主要代表厂商的能力和特点进行了全面介绍。有如下洞察:

1. 中国ZTNA技术能力发展现状

  • 厂商ZTNA解决方案相关的各项基础能力建设已经趋于成熟。国内主流安全厂商已基本具备身份认证、终端可信接入、应用级访问控制、动态权限管理、细粒度审计以及持续风险评估等核心能力,并逐渐形成覆盖身份、终端、网络与应用的一体化零信任架构。
  • 中国ZTNA市场正加速向安全访问服务边缘(SASE)方向演进。随着企业业务环境向多云、SaaS与分布式办公架构发展,单一ZTNA能力已难以满足企业对统一安全接入与持续安全运营的需求。越来越多厂商开始将ZTNA与SWG、CASB、SD-WAN、数据安全、终端安全以及安全运营能力进行深度融合,构建统一SASE平台,实现跨网络、跨云、跨终端环境的一体化安全访问控制。
  • 中国ZTNA市场正在进入“AI赋能ZTNA”的新阶段。当前,基于机器学习、行为分析与GenAI能力的智能检测、动态风险评估、自动化策略生成以及安全事件分析,已经在众多安全场景中取得显著效果,推动安全体系从“人工驱动”向“智能驱动”加速演进。与此同时,AI正在显著提升安全产品的实时分析能力、自动化运营能力和复杂环境下的风险感知能力,逐渐成为安全产品竞争力的重要核心。
  • AI自身安全问题成为国内技术提供商重点关注的新方向。当前,行业已经开始围绕AI身份管理、提示注入防护、模型调用安全、敏感数据保护等领域持续加大研发投入,希望构建面向“人+设备+智能体”的新一代安全体系。从目前中国市场发展阶段来看,AI自身安全能力与ZTNA体系之间仍未实现充分融合,大部分厂商对于AI智能体身份治理、AI行为持续监测、模型调用链审计以及AI最小权限控制等能力支持仍相对有限。

2. 中国ZTNA市场规模发展现状

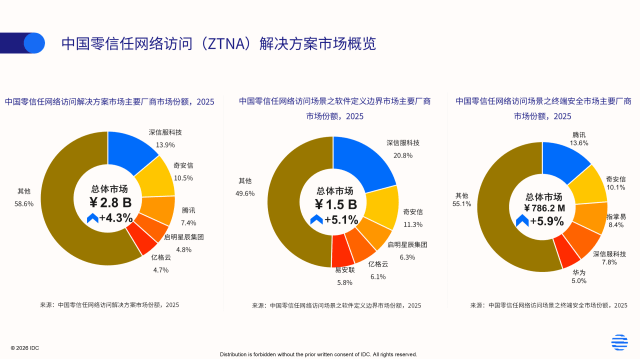
虽然近几年受到宏观环境的影响,中国整体网络安全市场承压明显,但ZTNA市场仍然凭借厂商不断完备的技术演进以及企业级客户的真实需求增长保持稳定增长态势。从市场规模来看,2025年中国零信任网络解决方案市场的整体规模达到27.6亿元,其中软件定义边界(SDP)依旧是最主要的ZTNA实现方式,市场规模为15.4亿元,零信任终端安全继续保持快速增长,市场规模为7.9亿元。深信服科技、奇安信、腾讯、启明星辰集团、亿格云、易安联、指掌易、华为等厂商在ZTNA市场占据重要的市场影响力。

IDC的调研发现,中国企业对零信任理念和ZTNA的认知度与接受度已广泛提升,ZTNA逐步成为新一代统一访问控制与身份安全体系的重要基础能力。主要技术提供商的ZTNA基础能力建设已经已覆盖远程办公、互联网暴露面治理、第三方接入、云原生、工业互联网及AI应用访问等复杂场景。同时,中国ZTNA市场正加速向SASE平台化演进,满足多云、分布式办公和AI应用生态下的统一安全接入与持续运营需求。IDC《中国智能安全访问服务边缘市场预测,2026—2030》报告数据显示,中国SASE市场在未来5年将保持快速增长,年均复合增长率为25.9%,市场规模在2030年将达到48.7亿元。

在另外一本《IDC MarketScape:中国GenAI赋能的零信任网络访问解决方案2026年厂商评估》报告中,IDC从能力、战略和营收等多个维度对国内市场主要的ZTNA解决方案技术提供商进行了全面评估,充分展现厂商各自的能力、优势和挑战,并最终选择阿里巴巴、持安科技、从云科技、缔盟云、华为、吉大正元、南凌科技、奇安信、启明星辰集团、山石网科、深信服科技、腾讯、网宿科技、易安联、亿格云、中国电信、竹云、指掌易入选本次报告(按拼音首字母顺序排列)。

ZTNA技术发展趋势:AI场景的双向驱动

结合今年的市场研究,IDC对ZTNA解决方案的技术发展趋势有如下判断:

  • AI赋能ZTNA能力升级:国际与中国技术提供商普遍将AI/GenAI技术深度嵌入ZTNA体系。AI驱动行为基线建模、动态风险评估、自动化策略生成、智能事件分析与响应,显著提升安全事件分析、预测和处置的智能化水平,降低人工运维负担。
  • 智能体安全防护:随着大模型、智能体、MCP、API等新型主体广泛应用,ZTNA需扩展至“人+设备+智能体”统一治理。技术提供商需要加大AI身份管理、访问控制、提示注入防护、模型调用安全、敏感数据保护和行为审计等研发投入,防范AI身份伪造、越权访问、提示注入、敏感数据泄露等新型风险。
  • 平台化与生态化融合:ZTNA正加速与SASE、IAM、安全运营、数据安全等体系深度融合,向一体化安全访问与运营平台演进。技术提供商将强调开放集成能力,支持多云、SaaS、分布式办公、AI应用等复杂场景下的统一安全管控。
  • 行业场景化与持续运营:针对政府、金融、能源、制造等重点行业,技术提供商需要提供定制化ZTNA/SASE方案,强化与云服务、终端安全、身份安全、SaaS等生态伙伴协同。ZTNA/SASE产品从单点部署转向长期治理与持续运营,提供全生命周期服务。
  • 数据安全与合规:技术提供商普遍将数据安全能力原生嵌入ZTNA架构,支持敏感数据识别、分级管理、全流程追踪、动态脱敏、泄密溯源水印及多渠道外发管控。AI助力数据行为监测、异常识别和自动化响应,推动数据安全防护从被动防御向主动治理转型。

因此,AI既是防护对象,也是能力跃迁的驱动力。未来,ZTNA将逐步演进为AI时代统一安全控制平面的关键组成部分。技术提供商需积极拥抱AI赋能,强化平台能力和生态协同,持续提升产品智能化和运营服务能力,以应对高度动态化的业务与攻击环境。

IDC建议

IDC中国网络安全市场高级研究经理赵卫京认为,在企业数字化、云化与AI化持续深入的背景下,ZTNA正在与SASE、IAM、安全运营及数据安全等体系深度融合,向平台化、智能化方向发展。GenAI与智能体的快速普及,也在从‘AI赋能安全’和‘保护AI自身安全’两方面重塑ZTNA解决方案。当前,中国ZTNA市场整体已进入规模化落地阶段,厂商基础能力逐渐成熟,但在AI与安全的融合、统一运营以及复杂场景适配等方面仍面临挑战。未来,ZTNA将逐步演进为AI时代统一安全控制平面的关键组成部分。”

进一步交流

AI攻防规则已变。IDC深耕大模型安全与智能体治理研究,助您量化风险、重构防线。欢迎联系IDC,获取最新洞察与定制化咨询,共探破局之道。

Austin Zhao

Austin Zhao - Senior Research Manager

Austin Zhao, senior research manager of IDC China, focuses on research and analysis of the China network security market. He provides intelligence and consulting services to both local and multinational cybersecurity vendors. Austin has deep insights into the China network…

办公和协同软件市场正在经历从“AI助手”向“AI Agent”和“AI原生工作流”的剧烈转型。各组织正快速从孤立的AI试点项目,转向企业级规模化部署,从根本上重塑人力与智能系统之间的工作分配模式。这一转型凸显了人类独有的核心能力——判断力、创造力与关系管理能力,而AI智能体则负责处理常规性、重复性及知识密集型任务。进入2026年,这个市场的硝烟已经从简单的对话框延伸到了企业的核心业务链条中。OpenClaw这样的AI Agent开源项目的流行标志着AI原生的智能化工作平台在企业数字化转型中的加速落地:其以多Agent驱动、自动化流程和深度生态集成为核心,极大提升了团队协作效率和创新能力。AI Agent不仅重塑了智能化工作平台的用户体验,还推动了市场对AI驱动工作流、安全合规和开放集成生态的高度关注。

国际数据公司(IDC)于2026年6月发布的《中国智能化工作平台In-App AI Agent评估, 2026》对于智能化工作平台领域中的AI助手/Agent能力进行评估,希望通过对中国市场中主要产品技术提供商的产品评测以及对最终用户的客观访谈来帮助市场更加全面地了解中国智能化工作平台AI能力的发展现状,能力特点和应用情况以及未来的技术发展趋势。IDC定义的智能化工作平台是指通过整合企业通讯、协同办公应用、生产力工作套件以及AI助手/AI Agent等数字化工具,帮助个人和组织高效、有效地完成任务或工作,实现目标的综合性平台。评估的内容包括智能办公能力、AI Agent流程自动化能力、集成和跨平台能力、基安全合规/Agent执行安全能力、行业解决方案和客户、AI生态建设等维度。

IDC通过这次评估观察到,智能化工作平台头部厂商的AI能力已经迈向逐渐成熟的发展阶段。领先厂商已经能够支持智能写作、会议纪要生成、文档总结、知识库问答、数据收集和分析、日程与任务建议、跨应用信息检索,以及基于用户指令调用部分办公工具完成稍有难度的任务。这说明AI能力正在从辅助内容生产,逐步走向办公流程中的任务协同。但是从一些评估维度来看,AI Agent流程自动化能力、Agent执行安全和AI生态建设整体得分偏低,说明该领域仍在快速探索阶段。模型稳定性、任务理解能力、流程编排能力、权限控制机制、执行边界管理以及生态伙伴协同机制尚未完全成熟,不同厂商之间的能力差异也比较明显。总体来看,当前市场的竞争核心正在从传统协同工具转向AI驱动的平台能力。未来市场竞争的关键,将不再只是AI功能的数量,而是厂商能否让AI Agent真正进入企业业务流程,并在可控、安全、可审计的前提下实现规模化应用。

基于本次评估情况和对未来趋势的判断,IDC认为,未来中国智能化工作平台市场将有以下发展趋势:

1. AI原生与多Agent驱动的智能化工作平台将成为主流

未来的智能化工作平台将以AI为核心驱动力,原生集成多模态协作、智能代理(Agent)、自动化、知识管理等能力。AI不仅承担任务自动化、智能推荐、内容生成,还将通过多Agent协作实现流程编排、知识流转和业务决策支持。IDC预测,企业将逐步从“AI插件”过渡到“AI原生”平台,AI与人、AI与AI之间的协作将成为提升创新力和敏捷性的关键。Agentic协作将推动企业从单一任务自动化迈向端到端的智能业务流程重塑。

2. 多模态与可视化协作体验持续深化

随着智能化办公场景的复杂化,智能化工作平台正快速融合文本、语音、视频、视觉画布、手势等多种交互方式。可视化协作(如数字白板、流程画布、可视化工作流)和“多人游戏化”体验成为主流。根据IDC全球调研数据,82%的企业认为视觉协作显著提升了创新与决策效率。未来,平台将进一步支持XR、智能硬件(如AI眼镜)、多语言和无障碍访问,实现全员、全场景的沉浸式协作体验。

3. 数据治理、信任与合规成为平台落地前提

随着AI和多方协作的深入,数据安全、隐私保护、合规和AI治理成为平台采购和部署的核心考量。平台需支持细粒度权限,权限继承自动化,数据驻留,合规认证(如GDPR、ISO等),合规审计可追溯,并通过透明的数据政策和治理机制建立员工与组织间的信任。IDC强调,信任是数字协作的基石,缺乏信任的协作空间难以实现持续创新和高效运营。

4. AI治理与FinOps兴起

随着数字员工增多,企业开始担心“AI乱花钱”或“AI越权”。因此,海外出现了专门审计AI Token消耗和AI安全合规的工具。Token成为财务成本,企业开始像审计水电费一样审计AI的Token消耗量。厂商需要推出更精准的ROI分析工具,用来证明AI助理到底帮员工省了多少时间。

5. 平台化与低代码深度融合

智能化工作平台正在从沟通和流程工具,升级为企业统一的工作入口。它可以通过连接ERP、CRM、HRM、财务和供应链等系统,把组织协作、业务流程和数据处理整合到同一界面中。与此同时,低代码能力将与AI和AI Agent深度结合。业务人员可以用自然语言描述需求,由AI辅助生成表单、流程、报表和轻量级应用;AI Agent则可以根据业务规则自动触发流程、分派任务、同步数据和提醒异常。

分析师观点

IDC
中国助理研究总监李昭表示,AI在办公场景中的演进,正在从“提升个体效率”加速走向“重构办公执行体系”。以OpenClaw为代表的新一代Agent框架,已不再局限于知识问答、内容生成、沟通协作、会议助手、数据和表格处理、日程规划等传统助手能力,而是进一步具备跨应用调用、连续任务执行和自主编排流程的特征,这标志着企业办公AI正从“会说”走向“会做”。软件不再只是工具,而是数字员工。AI Agent不再是被动响应,而是具备了规划能力,能自主跨应用完成复杂任务。与此同时,近期市场变化也表明,Agent的价值正在快速释放,但其规模化落地已不再只是技术问题,而是进入“技术能力、治理能力与成本模型”三重约束并行的新阶段。

进一步交流

如果您希望进一步了解Agent在企业软件中的落地路径、市场演进趋势或对自身业务的具体影响,欢迎与IDC分析师团队联系(点击此处)。IDC将基于持续的市场跟踪与研究,提供更具针对性的洞察与建议,支持企业与厂商在这一轮变革中做出更有前瞻性的决策。

Lizzie Li

Lizzie Li - Associate Research Director

Lizzie Li is Associate Research Director of IDC China's Enterprise System and Software Research that focuses on research and analysis of the China Datacenter, Cloud Computing, and IT infrastructure markets. She also provides intelligence and consulting services in customized projects for…

Key questions answered in this article: What is the AI supercycle and what does it mean for Japan? What are the biggest gaps between AI vendors and enterprise buyers in Japan? How is AI changing B2B technology buying decisions?

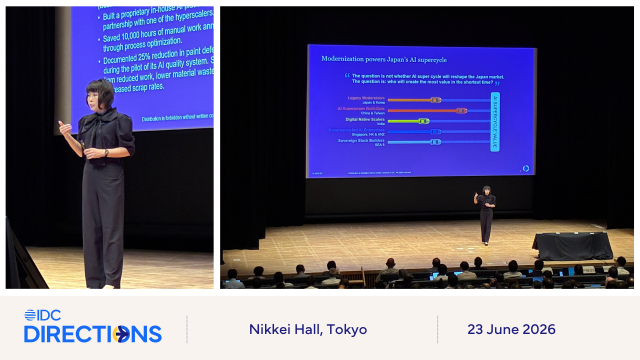
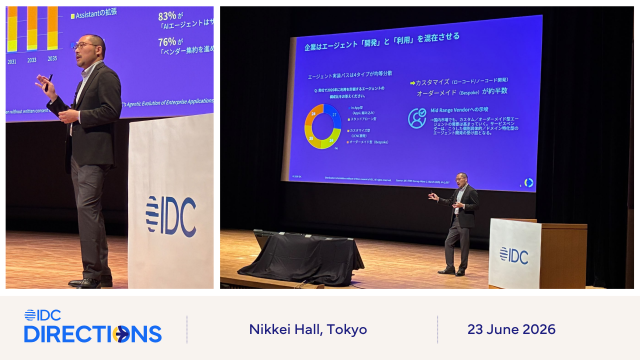
The energy in the room at IDC Directions Tokyo 2026 on June 23 said it all: Japan’s AI moment is no longer approaching — it has arrived. And the central message from IDC’s Senior Vice President Sandra Ng was both a wake-up call and a roadmap. The question, as she put it bluntly, is not whether AI will reshape the Japan market. It is: who will create the most value in the shortest time?

IDC Directions Tokyo 2026 brought together close to 400 attendees, with 65% at Director level or above, a room full of decision-makers, not just observers. Analyst 1-on-1 sessions were fully booked, and the volume of questions from the floor made one thing clear: the conversation was hitting a nerve.

The Supercycle Is Real and Japan Is Playing Catch-Up

To understand the scale of what is happening, consider this: global IT spending in 2025 is growing at 14% on a $4.2 trillion market base, the strongest IT spending growth since 1996. Back then, that same 14% growth rate applied to a $700 billion market. The numbers are in a different league entirely. (Source: IDC Worldwide Black Book, 31 March 2026)

This is the AI supercycle. While regions like China, Taiwan, and India are racing ahead as “AI Superpower Built-Outs” or “Digital Native Scalers,” IDC positions Japan alongside Korea as a Legacy Modernizer, a market where the path to AI value runs directly through modernization. That is not a disadvantage. It is a specific strategic imperative.

Japan’s AI market reflects this momentum. Domestic AI infrastructure spend is expected to reach $9 billion by end of 2026, growing at a 24% CAGR through 2029. AI services are projected to hit $8 billion by 2030 or 3.2x the 2025 figure. Moreover, 61% of CEOs in Asia Pacific named agentic and generative AI at scale as their number-one new investment priority. (Source: IDC Worldwide AI and Generative AI Spending Guide, Forecast V1 2026; IDC CEO Survey, March 2026)

The Vendor-Buyer Disconnect Is Costing Everyone

Here is where the conversation got uncomfortable and important.

Sandra Ng identified four persistent gaps between what enterprise buyers in Japan need and what technology vendors are actually delivering:

Gap #1 — Business case clarity. Buyers want outcomes grounded in their industry, not generic global benchmarks. “Show me what this looks like for a Japanese manufacturer” is a very different ask from a global case study slide.

Gap #2 — Total cost of AI ownership. This one deserves more attention than it typically gets. Hidden AI implementation costs in Japan — covering data preparation, system integration, ongoing model maintenance, compliance monitoring with METI guidelines, and change management, routinely add 50–70% beyond the headline technology price. Vendors who do not address this upfront are losing trust at the CFO conversation.

Gap #3 — AI governance readiness. Japan’s regulatory environment is real and specific. The FSA AI guidance, METI’s AI governance framework, and the Act on Protection of Personal Information (APPI) set high standards. Buyers are moving faster than many vendors’ governance answers can keep up.

Gap #4 — The “show me” moment. Japanese enterprise buyers want a local reference customer, a deployment timeline, and measurable outcomes, not a global success story. Vendors who cannot produce this are losing shortlist positions.

What Japan’s Leading Enterprises Are Actually Doing

These gaps are not theoretical. IDC’s CxO conversations in 2025–2026 point to concrete examples of how Japan’s most forward-thinking companies are navigating them:

  • Toyota built a proprietary in-house AI platform with a hyperscaler partner, saving 10,000 hours of manual work annually and documenting a 25% reduction in paint defects through AI-assisted quality systems.
  • Tokio Marine responded to METI and FSA guidance by publishing a 5-pillar AI governance policy first, covering transparency, human oversight, bias elimination, data protection, and operational reliability, before deploying AI for document and image analysis. Governance policy first, deployment second—this is the sequence Japan’s regulators now expect.
  • Yamato Transport used AI-driven supply chain optimization across 1.6 million corporate customers and 4,000+ logistics partners, targeting a 65% reduction in labor costs and a 42% cut in GHG emissions by optimizing relay points across 80 routes.

These are not pilots. These are production deployments with documented outcomes—exactly the reference stories buyers are demanding.

Your Buyers Are Already Using AI to Research You

One of the most striking data points from Sandra Ng’s presentation is that 84% of global technology buyers agree that AI will change how their companies buy technology in the next 12 months. (Source: IDC B2B Technology Buyer Survey 2025, WW n=406)

The buying journey has already shifted and it looks like this: AI discovery → vendor website check → peer and colleague validation → channel partner consultation → shortlist. If your brand and solutions do not surface clearly when a CIO or CFO uses ChatGPT or Google Gemini to research a purchase decision, you are being eliminated before you even know you are in the running.

This makes Answer Engine Optimization (AEO) and Generative Engine Optimization (GEO) business-critical capabilities, not just marketing experiments. By 2027, 35% of Japanese organizations are projected to have unified, coordinated AI governance in place. The vendors who are visible, credible, and well-structured in AI-generated answers will have a compounding advantage. (Source: IDC FutureScape 2026 – AI-Fueled Business Strategies, Japan)

Agentic AI: The Next Competitive Frontier

The broader industry shift reinforces why speed matters. As highlighted in the presentation by IDC Japan’s Takuya Uemura, the AI supercycle is now entering its second investment wave — moving from infrastructure build-out to enterprise application and services adoption. Enterprise AI platform, app, and services spend globally is projected to grow from $400 billion in 2026 to $1 trillion by 2029. (Source: IDC Worldwide AI and Generative AI Spending Guide V1 2026)

Critically, 83% of buyers surveyed agreed that AI agents are lowering switching barriers between suppliers. The vendors who lock in outcome-based relationships now, before the market commoditizes, will be the ones defining the next competitive moat.

Three Moves That Matter Right Now

Sandra Ng’s closing framework was direct and actionable:

Do now: Replace generic benchmarks with a single Japan reference customer, one metric, one timeline. Map your go-to-market pitch to the full buying committee, not just the CIO. Fix your AI discoverability gap immediately.

Do this year: Make ROI transparency your competitive weapon. Build deployable agentic workflow stories. Invest in AI-optimized third-party content that earns citations in AI-generated answers.

Bet on this: Position into AI governance, trust, and compliance as a revenue line, or become the vendor that makes compliance an outcome rather than a conversation. Start measuring your share of answer by category, persona, and geography. Execute a layered discovery strategy: SEO + AEO + GEO. (Source: IDC C-suite Survey, September 2025, APJ, n= 300)

Japan’s AI Supercycle Will Not Wait

The window to establish leadership positioning in Japan’s AI market is open—but it will not stay open indefinitely. The enterprises that move from experimentation to outcome-based deployment, the vendors who close the four gaps, and the organizations that make themselves discoverable in AI-powered buying journeys are the ones who will define the next era of Japan’s technology market.

The conversation that started in Tokyo continues in Osaka.

Join us at IDC Directions Osaka on July 28, 2026 to go deeper on how Japan’s AI supercycle is reshaping your industry, what the data says about where the next wave of value will be created, and how your organization can get ahead of it. Register for IDC Directions Osaka today. Seats are limited.

Mike de la Cruz - Corporate Communications Director - IDC Asia/Pacific

Mike de la Cruz is Corporate Communications Director for Asia Pacific at IDC, bringing over 25 years of career experience in marketing and communications for the information technology industry. He shapes and amplifies IDC's research-driven narratives, positions executives and analysts as authoritative industry voices, builds relationships with top-tier technology and business media across the region, ensures consistent brand voice and positioning, develops content that drives audience engagement, and leverages social media and digital communications to extend IDC's reach.

国际数据公司(IDC)最新研究显示,AI超级周期带来的不仅是技术代际的更迭,更是一场深层次的组织范式变革。以智能体为核心驱动力的新型生产力形态——OPX(One-Person X),正在悄悄影响传统的企业组织逻辑,并对PC等终端硬件市场产生结构性的拉动效应。

AI超级周期下的组织重构

以智能体为代表的AI超级周期带来的不仅是技术迭代,更是一场生产力供给的结构性变革。当智能体从“辅助工具”进化为能够独立执行与产出的“生产力单元”,组织形态的底层逻辑必然随之重构。国际数据公司(IDC)最新研究将这一变化命名为OPX(One-Person X)——AI时代以单人为核心决策单元的新型组织范式,其核心共识可概括为:少数人负责决策与价值判断,AI智能体集群承担执行与产出。

基于这一框架,OPX下辖两种落地形态:OPC(One-Person Company),即以个人为核心决策者、AI智能体为生产力引擎的企业级组织形态;OPE(One-Person Expert),面向个人专业服务领域。其中,OPC是AI重构商业组织最具颠覆性的形态。IDC对其的定义是:以个人为核心决策者,AI智能体/工具为核心生产力,至少可在单一任务环节独立完成业务,人工负责审核、判断与异常处理,最终实现传统需多人团队才能完成的商业闭环。从组织规模看,OPC可以是1个人,也可以是10人以内的轻量化团队

OPX的运作模式催生了一套独特的硬件需求:7×24小时不间断运行(无专职运维,中断即停业)、全生命周期高性价比(设备与算力成本均需可控)、端到端自动化闭环(任务接收、拆解、执行无需人工干预)、多设备无缝协同(跨终端业务连续性刚需)、无人值守下的远程管理与自进化,以及数据隐私与端侧主权保护。在这一需求图谱中,手机承担移动交互,云端提供弹性算力,而本地AI推理、多任务编排与端侧数据保护均依赖本地算力,这使得PC设备,尤其是AI PC、AI主机设备,正成为OPX工作流的本地中枢。

OPX驱动的PC出货量近160万台

根据 IDC 最新预测,2026 年中国 PC 市场总出货量约为 4,038万台,同比微降 6.1%,整体大盘小幅收缩。但在结构层面,以 OPX(一人公司/超级个体)范式驱动的 PC 需求正在形成一个独立的增长极。IDC预测,2026年由OPX驱动的PC市场出货量近160万台。

IDC 认为,OPX 对 PC 市场的拉动效应正在经历从 “边缘增量”到”结构性力量” 的转变。尽管 160万的出货量仍属早期,但考虑到 OPX 的增速逻辑,即存量企业业务扩张、设备换机周期叠加、AI Native 工具链持续成熟。这一力量的上升值得重点关注。我们判断,OPX 有望在未来 3-5 年内成为 PC 市场增长叙事中不可绕过的结构性变量。

OPX对PC市场的影响集中体现在两个核心维度:采购逻辑的多元化和换机节奏的两极分化。首先,采购逻辑正在走向多元化。传统企业PC采购长期由人员规模驱动,OPX则打破了这种一一对应关系,设备需求开始更多地由任务负载而非人头数定义,一个创业者同时运行多台设备处理不同任务流的情况在特定场景下已成为现实。其次,OPX的换机节奏呈现两极分化态势。驱动快速换机一侧的力量来自OPX业务机会的不可预见性,当核心设备直接承载产出,AI技术的代际迭代持续抬高硬件准入门槛,不具备新能力的旧设备将在特定场景中丧失竞争力,都可能迫使OPX为抓住机会而在短期内高频地更新设备。另一方面,OPX极致追求效率与性价比敏感又构成了强大的延缓效应。

IDC建议

在采购触达方面,OPX群体的决策路径迥异于传统企业客户——信息获取以与AI结合的评测内容、技术社区和同行口碑为核心,购买决策由个人独立完成,无需IT部门审批,购买渠道偏向个人消费路径。这意味着,针对OPX组织形态,厂商需要结合AI相关的内容做精准触达,可能包括评测合作、社区运营、KOL口碑建设,将成为撬动OPX客群的杠杆。

在产品策略方面,OPX在消费级价格、企业级可靠性与AI原生能力之间提出了三元要求。面向OPX群体的产品设计,不宜简单地在现有企业或消费产品线上做加减法,而应从OPX的实际业务场景和工作流出发,重新定义产品配置与服务组合。

在服务创新方面,OPX用户缺乏IT部门的缓冲,设备故障直接等同于业务中断。这种脆弱性定义了一个高付费意愿的服务市场,快速响应维修、备用机备援、数据恢复保障等“个人级紧急兜底”服务,有望成为PC后服务市场增长最快的板块之一。

AI超级周期带来的不仅是技术迭代,更是生产力供给的结构性变革。OPX之所以值得PC产业持续关注,根本在于生产力的最小单元正从“企业”转变为“个人+AI智能体”。产业的价值链条正从以硬件为中心的线性供给,转向围绕“个人生产力闭环”的软硬服一体化。

进一步交流

IDC中国终端系统研究团队将持续追踪OPX范式下的硬件需求演变与市场机会。如需获取更详尽的PC市场季度追踪数据、OPX用户画像深度分析,或定制化的市场策略咨询,欢迎随时与IDC中国团队取得联系。让我们共同探讨,如何在“一人即公司”的时代,重新定义计算终端的价值边界。如对其他研究内容感兴趣,也可与我们保持沟通。

引言:算力变局下的真实回响,拨开智算云迷雾

在日新月异的AI时代,中国智算云市场正经历着前所未有的狂飙突进。从大模型百模大战的喧嚣,到智能体应用的全面爆发,算力需求的重心正在发生深刻转移。然而,在千亿级市场规模的宏大叙事下,企业真实的使用现状却往往被层层迷雾所掩盖。当行业逐渐褪去‘唯算力规模论’的狂热,转向对效能与价值的理性审视时,真实的AI业务落地究竟面临着怎样的需求和挑战?

为了探寻这一命题,国际数据公司(IDC)与中国信通院分别从企业使用智算云服务与专属智算云建设两大视角,面向涵盖互联网、政府、金融、制造、通信、交通、能源等多个行业的250家企业用户,开展了一场深入调研,旨在还原当前中国企业智算云使用的十大真相。

核心数据总览:中国企业智算云整体产业格局

中国智算云市场正迎来从百亿级迈向千亿级的历史性跨越,整体格局呈现出规模扩张与结构优化并进的态势。

IDC数据显示:2025年中国智算云基础设施市场(AI IaaS)规模达到486.7亿元,同比迅猛增长128%,预计未来2年超千亿。互联网、大模型服务、汽车等行业是当前该市场的采购主力,部分制造、医疗、政务数智化项目从试点采购转向常态化租赁,成为拉动该市场的新增力量。

与此同时,企业的大模型推理服务需求呈指数级爆发,推动专属智算云建设市场进入高速增长通道。联合调研测算数据显示:截至2026年2月,中国企业自建智算云推理算力规模已超过350EFlops,能够支撑日均Token产能超70万亿,成为中国大模型推理服务的核心承载形态。

真相一:混合部署成产业标配,单一形态已不再是企业算力战略的最优解

在数据安全、成本效益、业务弹性的多重考量下,企业智算云部署已告别单一模式,“智算云服务+专属智算云建设”组合成为当前多数企业的默认形态和最优解。

IDC所调研的智算云服务用户中,85.8%的企业选择了 “外部AI算力服务+自建数据中心” 的混合架构,表明企业既希望解决突发峰值算力、短期项目研发、临时模型微调等弹性需求,又希望保持对核心数据、高频稳定业务的控制权。

中国信通院调研数据也显示:超过80%的省市级政务单位通过政务专有云平台部署大模型服务;头部银行机构中96%的算力规模采用自建模式,而中小金融机构则更多采用“专属云+公有云服务”的混合架构。此外,能源、制造等行业普遍遵循分级部署,按需采购原则。

真相二:通算与智算各司其职,共同构成企业算力供给底座

此前在智算中心大热的背景下,“通用算力中心是否会被取代”成为行业热议话题,本次调研数据给出了明确的答案。

从实际应用来看,通算凭借低成本、高兼容优势持续占据企业算力底盘,支撑 日常办公、ERP 、数据库、大数据离线统计等 IT 业务;智算作为增量支撑模型训练、多模态推理、Agent 智能应用等AI 业务,二者形成互补分工格局。

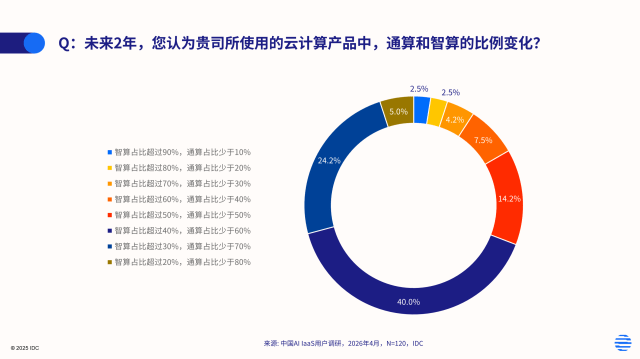
在问到企业当前智算和通算的使用比例时,最高比例(40.0%)的企业选择了“智算超过40%,通算少于60%”,但69.2% 的企业认为未来2年智算占比仍在50%以内。

2026年,随着AI迈入智能体时代,CPU迎来了新的发展机遇。过去大模型训练高度依赖GPU强大的并行计算能力,但随着智能体应用的规模化落地,智能体工作负载不仅需要GPU提供的大规模并行推理能力,也需要CPU所擅长的复杂任务编排、多步逻辑控制、系统级调度与状态管理能力。这一变化正推动 “CPU-GPU协同均衡”发展。

真相三:智算云规模增势迅猛,整体利用率均衡,但行业资源利用率分化明显

从供给侧看,智能算力利用率呈现节点与区域分化特征。枢纽节点的智能算力利用率高于非枢纽节点;东部地区整体利用率与西部地区相近,西部地区承接大量东部外溢的低时延、高计算密度、弱交互性的智算需求,显示出跨区域调度对提升整体算力效率的积极作用。从需求侧看,不同行业的智算资源利用率呈现分化格局。IDC调研数据显示:近半数企业的智算资源利用率维持在 51%-70% 的中等区间,且仍有 6.7% 的企业利用率仅为 31%-50%,处于较低水平。

头部云厂商、互联网企业、AI 自研大厂、新能源汽车等凭借多年技术积累,通过算力调度平台、精细化资源管控系统与全栈协同优化体系,实现了算力资源的高效复用,部分头部企业核心集群利用率突破80%。

制造、政务等行业的利用率低于平均水平,实现 70% 及以上高利用率的企业占比不足 35%。不少自建智算项目存在 “重硬轻软” ,仅完成了服务器、GPU 等硬件设备的上架部署,但缺乏配套的统一算力调度平台、资源池化管理系统与动态资源分配机制,造成了算力资源的浪费。

真相四:推理场景消耗AI算力过半,线下推理算力贡献1/3以上

百模大战时期,资本市场聚焦千亿参数大模型自研训练,训练算力需求一度占主导,但随着 Agent 应用规模化落地,轻量化小模型 + 端云协同推理进一步拉动推理算力需求,推理场景成为智算云市场的基本盘。

IDC调研数据显示,当前八成以上的企业用于训练工作负载的AI算力占比低于50%,如果按样本数加权平均计算来看,企业用于训练和推理工作负载的AI算力四六开。泛互(60%)、金融(46.7%)用于训练的AI算力占比高于平均值,而政府和制造行业2/3的AI算力都用于推理。

中国大模型 Token 调用量的爆发式增长,进一步推动了线下推理的崛起态势。根据发改委数据:截至2026年3月,中国智能算力规模超过1882EFLOPS。调研显示:推理算力占据六成,而其中企业自建智算云贡献的线下推理算力占比超过34%。政务、金融、能源等强监管行业的核心业务推理需求正不断通过物理隔离或逻辑强隔离实现线下部署,既能保障数据安全合规,又能实现毫秒级低时延响应,适配核心业务的严苛要求。

真相五:硬件与公有云IaaS仍是中国企业IT最大支出项

2025年企业总体IT支出中, IT软件与第三方服务花费占比不足三成,七成用于采购IT硬件和公有云IaaS。具体到AI相关支出,中国企业也高度集中在AI硬件与AI IaaS上,在 AI 应用和服务层的投入仍处于早期阶段。

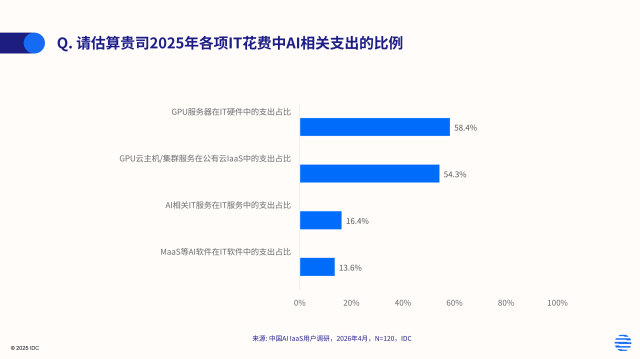
IDC调研数据显示:当前智算云企业用户IT硬件支出中用于GPU服务器的占比为58.4%,公有云IaaS支出中用于AI IaaS的占比为54.3%。泛互行业作为AI投入力度最大的行业,AI支出占比超过上述平均水平。

真相六:100P算力是企业智算云部署模式偏好的关键分水岭

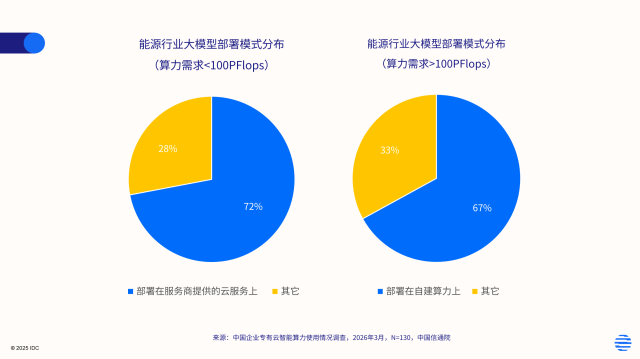
IDC调研数据显示:当前超过85%的企业使用了26-100 PFLOPS规模的AI算力。这一区间足以支撑中小参数大模型后训练、企业级场景推理及数据密集型AI应用,是兼顾成本与实用性的主流选择。对于该算力区间的企业而言,AI业务往往存在阶段性、波动性特征,全年算力使用起伏较大,自建投入的回报率偏低,因此更倾向于采购公有智算云服务。

中国信通院调研显示,100P FP16等效算力是企业选择规模化自建和上云的核心分界指标。当算力需求超过100P时,企业倾向于自建以掌握核心资产并实现长期成本摊薄。这类主体主要为大型央企、头部银行机构、头部互联网企业。调研发现,当前国有六大行自建智算云规模均超过100P,实现了完全物理隔离的私有云环境。而当需求在几十P级别时,企业更倾向使用服务商提供的共享或独享的云服务,这一分化布局现象在能源行业尤为突出。

真相七:制约智算云产业规模化落地的并非算力短缺,而是全链路配套能力不足

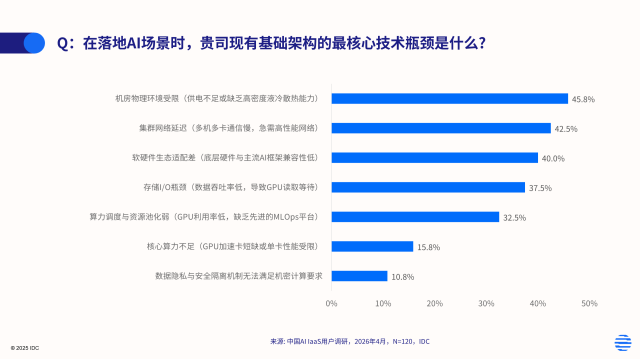
AI 基础设施落地是系统性工程,单一环节短板会形成 “木桶效应” ,拉低整体算力效率。IDC调研数据显示:企业 AI 基础设施落地的瓶颈已从 “算力短缺” 转向 “全链路配套能力不足” ,机房环境、网络互联、软件适配、存储吞吐等共同构成了制约 AI 业务规模化落地的系统性障碍。

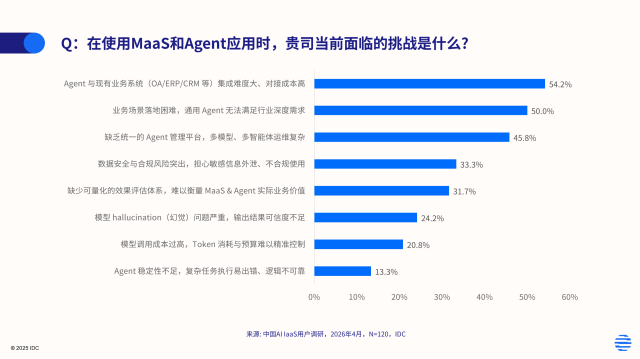
真相八:使用 MaaS 和 Agent 的挑战是“将 AI 真正用进业务里”

模型即服务(MaaS)与Agent的持续落地,让AI的获取变得像水电一样简单,但“用好”依然是巨大挑战。调研显示:企业核心瓶颈并非算力供给不足,真正的挑战在于:如何与现有业务集成打通业务孤岛?如何让Agent理解复杂的业务逻辑?如何管理数量庞大功能各异的智能体?只有跨越了从 “技术工具” 到“业务引擎” 的鸿沟,AI才能真正创造商业价值。

真相九:全栈智算云在线下推理场景凸显效能优势

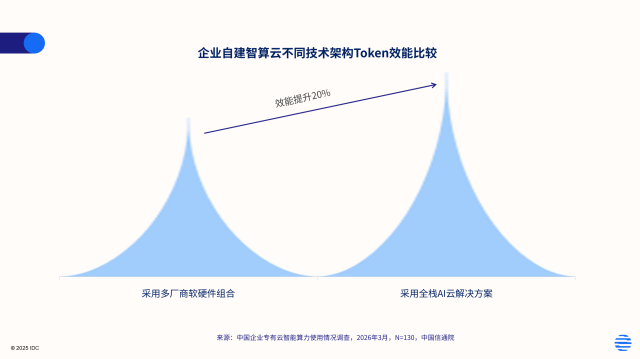
对于采用智算云服务的企业而言,推理效能取决于云服务商;而对于自建智算云的企业而言,AI落地涉及从底层芯片、算力调度、云平台,到大模型部署、场景微调、应用开发的每个环节,任一环节的短板都会拉低整体效能。

本次联合调研及实测数据显示,相较于零散拼凑多厂商软硬件的项目,采用全栈AI云服务厂商产品组合的项目词元产出效能提升超过20%(词元产出效能:相同场景下单位算力日均Token调用量),全栈厂商在芯片、云平台与模型层面可实现端到端协同优化,降低跨产品兼容损耗。

真相十:国芯国模适配逐步完善,全栈国产化进入规模化部署窗口

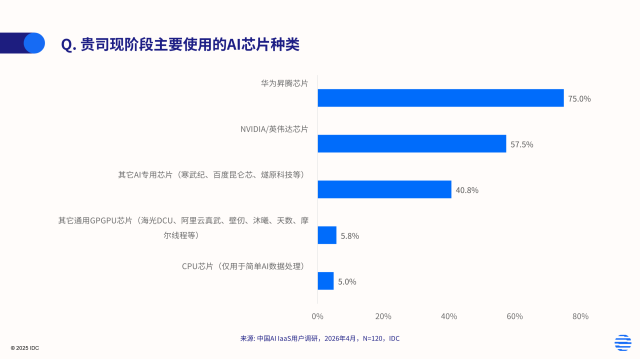
IDC调研数据显示:总体而言,当前国产AI芯片的使用率已高于国外品牌,但不同行业差异较大,互联网、模型和IT服务行业国外品牌的使用率明显高于国产品牌;汽车和金融服务行业两者的使用率相当;政府、能源和传统制造行业中国产品牌的使用比例更高,政务行业新建智算项目已100%采用全栈国产化方案,大型银行机构的核心业务系统逐步完成了国产化适配,能源、制造等行业的国产化替代进程也在不断加速。

随着国产芯片市场占有率逐步提升,国产AI芯片与国产大模型的协同适配正从“单点突破”走向“联合体推进”,基于“国芯+国模”的全栈国产化解决方案已迈入实质性规模化部署周期,这点在政府、银行、能源等关键行业表现得尤为明显。

结语:中国智算云告别粗放,迈入精细化运营时代

2026年的企业智算云市场,正在经历一场深刻的 “成人礼” 。随着市场认知回归理性,粗放式堆算力的发展逻辑彻底落幕,逐渐进入精细化运营时代。在这个时代,赢家不再属于单纯囤积算力的人,而是属于那些能够精准调度异构资源、深刻理解行业场景、并将AI无缝融入业务血脉的长期主义者。

IDC相关研究

围绕智算云相关研究内容、技术能力与市场格局,IDC 将持续开展系统性研究,包括但不限于:

  • 《中国智算云基础设施服务(AI IaaS)市场跟踪,2025下半年》(2026年4月发布)
  • 《IDC Market Forecast:中国整体云计算市场预测,2025-2029》(2026年5月发布)  
  • 《IDC Survey:中国智算云服务市场企业用户调研,2026》(即将发布)
  • 《IDC Tech Assessment:面向智能体的混合云智算基础设施技术能力评估,2026》(即将发布)
  • 《IDC Market Share:中国AI云存储市场份额,2025》(即将发布)
  • 《IDC PeerScape:中国市场异构算力调度和管理实践洞察,2026》

如需进一步了解智算云相关研究内容,或咨询 IDC 在云计算、AI 基础设施及数字化转型领域的其他研究成果,欢迎与我们保持联系。

Rachel Liu

Rachel Liu - Research Director

Rachel Liu is a research director for China’s Cloud and Services group. Her research covers public cloud, private cloud, edge cloud, industrial cloud, intelligent computing, and IT services. She is responsible for research plans, research execution and management, data tracking…

2025年,中国金融行业站上了从”数字化”迈向”智能化”的关键转折点。银行、保险、证券这类一向以稳健著称的机构,在合规与风控的硬约束之下,对新技术的引入历来审慎;但生成式AI带来的效率跃升与体验重塑,又是任何一家金融机构都不愿错过的红利。行业演进的核心驱动力,已经从最初”要不要用大模型”的试探和观望,转向场景的快速扩张、应用的规模化落地,以及对底层算力、解决方案与合规能力的系统性需求。金融AI云的竞争逻辑由此发生了一次根本性跃迁——从比拼算力”资源供给”维度,转向以”算力底座、平台调度、行业模型与合规可控”为核心的全栈能力竞争。

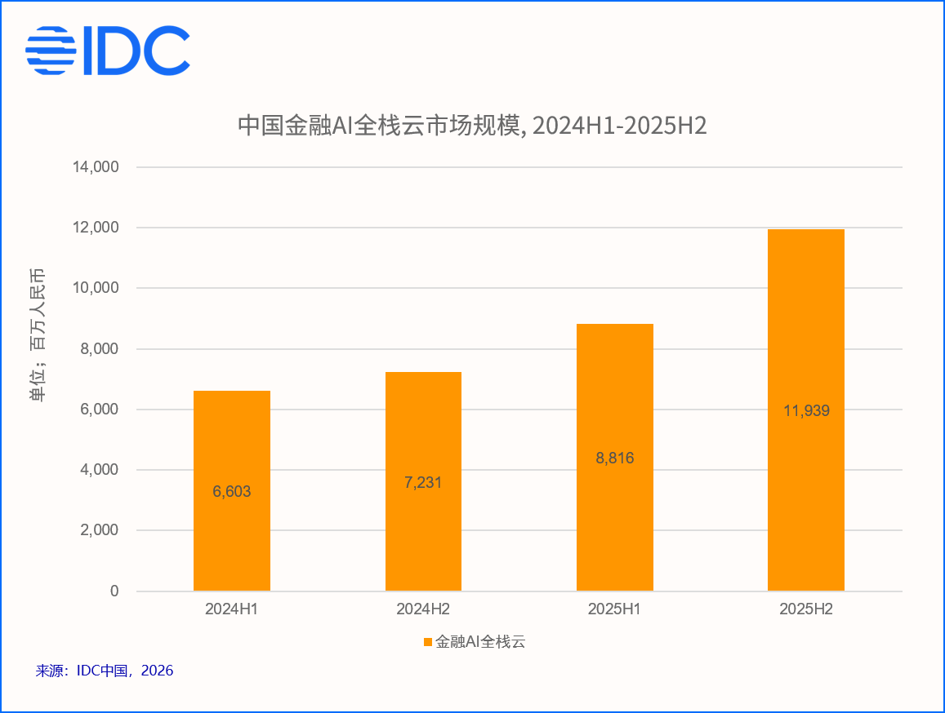
国际数据公司(IDC)最新发布的《中国金融云市场跟踪研究Add-on_AI全栈云》报告首次对中国金融云市场中公有云AI算力服务、私有云软硬件AI基础设施和GenAI解决方案子市场做出全栈式市场营收评估,中国金融AI全栈云市场2025全年市场规模207.6亿人民币,较2024年同比增长50.0%,远超金融云总盘23.9%的同比增速。这个数据对比显示出金融机构对AI相关领域的重视程度不断升级,预算投入持续加码,市场潜力快速兑现。

金融全栈布局下,头部云厂商的五种路径

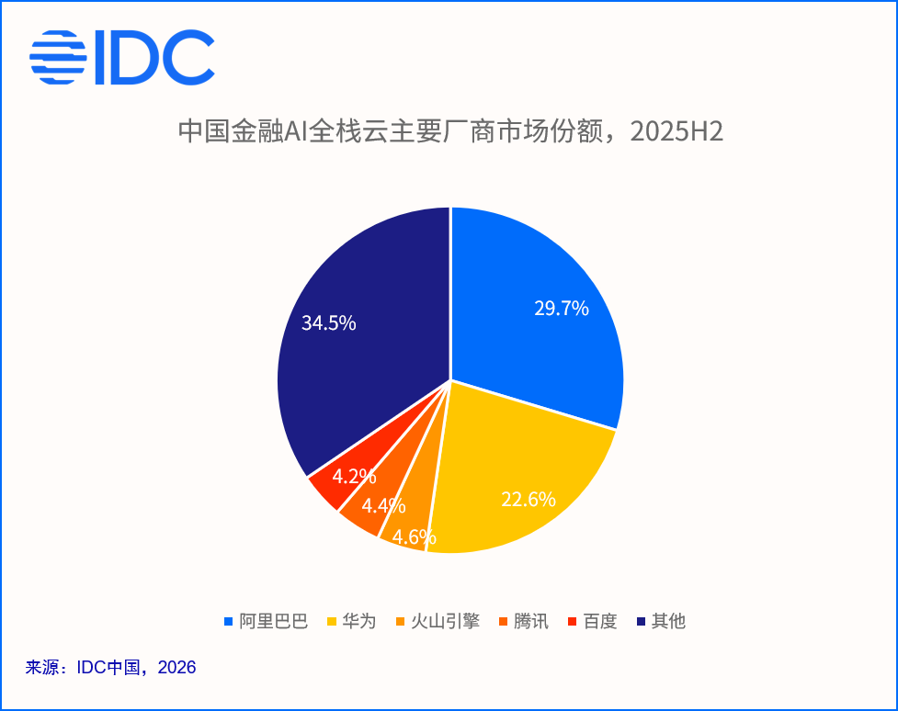
经过几轮市场调整,金融AI全栈云的第一梯队逐渐清晰。五家代表性厂商在算力、平台、模型与应用上的侧重各有不同,拼出一张完整的能力地图。

“公有云算力+私有化交付“双轨并进:代表厂商 阿里云

阿里金融云,在公有云一侧依托灵骏智能计算集群,在大规模算力调度与推理优化上持续投入;金融自主私有云一侧,平头哥自研的真武AI芯片已进入规模化部署阶段,并从2025年下半年开始逐步起量。叠加面向金融场景打磨的通义点金行业大模型,以及可落入客户机房的一体机交付形态,阿里云事实上把”芯片—模型—应用”的链路在金融场景里走通了一遍,并将在2026年持续深耕,加速复制。

软硬协同稳扎稳打:代表厂商 华为云

华为昇腾系列智算服务器,多年来在国产算力替代的进程中扮演压舱石角色。对金融机构而言,华为的吸引力恰恰在于”软硬一体、自主可控”带来的确定性——在数据不出域、供应链安全成为硬约束的当下,一套经过大规模验证的昇腾底座,往往比单纯的性能参数更有说服力。

AI应用和智能体先行:代表厂商 火山引擎

背靠字节跳动内部高并发推理场景的长期锤炼,火山引擎在推理成本控制与资源利用率方面建立了差异化优势,豆包C端的成功也给火山解决方案带来足够的曝光度和品牌效应,豆包大模型与火山方舟平台构成其对外的主要解决方案抓手。在智能营销、智能客服等高频交互场景中,这种”应用先行、智能体多点开花”的策略,更容易让金融客户在数据非敏感领域优先尝到AI红利甜头。

让金融AI“融汇贯通”起来:代表厂商 腾讯云

依托在平台层数据库和大数据产品的行业优势,腾讯云从AI通用大模型到上层AI应用,从平台产品到底层异构算力管理,试图把这条链路做成一个连续整体,而非彼此割裂的模块。对于拥有庞大存量系统、又要稳步引入AI能力的金融客户来说,这种平滑过渡、整体交付的能力,本身就是一种稀缺竞争力。

“芯片+平台”组合拳:代表厂商 百度智能云

昆仑芯P800已完成规模化验证,2025年以来已交付多个万卡集群,并支撑了文心大模型新版本的训练。配合百舸AI计算平台在异构调度上的能力和千帆平台对金融应用场景的支撑,百度为金融客户从模型基础训练到推理开发上线,铺设了一条相对完整的国产化通道。

五家厂商路径不同,指向的判断却高度一致:在金融这样对”稳健”近乎苛求的行业里,单点能力很难构成壁垒,唯有把算力、平台、模型、应用与合规能力打通,才能真正站稳脚跟。

金融ISV服务商的“喜“与“痛“:增量市场背后的挑战

在AI云厂商与金融机构之间,往往活跃着各个子赛道金融ISV服务商的身影。他们既是AI方案的集成者,也是AI应用落地的”最后一公里”。2025年,金融ISV服务商感受到了明显的市场变化,AI市场带来新增营收机会的同时,也带来了全新的机遇和挑战。

一方面,金融AI场景在2025年正式跨过了“项目落地“的门槛,并呈现出明显的量价齐升势头。在传统金融预算大环境整体承压的当下,这样一块实打实的市场增量殊为不易,它意味着新的项目机会、新的合作入口,以及与客户重建深度连接的契机。不过,这份增量需要冷静看待,AI相关收入对整体金融云解决方案营收的直接贡献占比仍然偏小,更多扮演的是”敲门砖”与”引流器”的角色——通过AI项目切入客户、增强黏性,再向定制化开发、平台软件乃至底层基础设施资源的销售导流,而这些方向的受益者往往是云厂商占优。真正的商业价值,可能兑现在AI之外。

另一方面,金融机构对AI方案的选型普遍呈现迷茫状态。用哪家大模型,走开源还是闭源,部署在公有云还是落到本地机房,是否涉及业务系统解耦和微服务改造,数据安全合规如何满足监管要求,未来方案兼容性与可持续性又如何保证——这些问题几乎没有现成经验可以照搬。金融ISV服务商需要陪伴客户共同摸索试错,在反复的POC与调优中消耗大量人力成本。这种”陪跑”固然能加深信任,却也推高了交付成本,挤压了本就不宽裕的利润空间。

IDC市场调研发现,金融ISV AI服务商正从”项目制交付”向”持续运营”转型,从单纯的技术提供者,转变为深度参与客户流程重构的”业务转型伙伴”。金融AI可能对未来ISV服务商竞争格局带来颠覆性变化,金融服务商不仅要懂业务,还要懂AI、养AI、用AI,扛的住长期AI运营的玩家才能在未来竞争中立于不败之地。

IDC洞察:金融AI要以全栈能力和生态协同赢得长期战斗的胜利

对于金融云服务商和云厂商而言,是否全栈式布局已不再是选答题,而是必答题。金融客户要的不是某一颗更快的芯片或某一个更准的模型,而是一套“数据—模型—平台—应用—服务“端到端打通、并能自我迭代和强化的能力体系。在这一点上,自主算力与行业大模型的协同尤为关键,它既回应了自主可控的政策诉求,也构筑起别人难以复制的护城河。与此同时,”合规”应当被前置为产品能力而非事后补丁——数据不出域、决策可追溯、幻觉可约束,在通用市场或许是加分项,在金融市场却是入场券。

随着智能体应用从单点走向全流程,推理调用量将呈指数级放大,按需租赁、弹性扩容与混合部署在未来三到五年内,有望逐步替代传统的重资产采购模式,成为金融AI基础设施建设的新常态。能在保障性能的同时把综合成本压下来的厂商,将在长期竞争中占得先机。

此外,建议金融云厂商加大对金融ISV服务商的支持力度。ISV是云厂商触达金融客户的重要渠道,也是行业Know-How的历史沉淀者,并在AI拓展方面成本承压。云厂商在算力补贴、平台开放、收益合作与人才培养上给予生态伙伴更深层的支持,可加快金融AI整体升级节奏。

金融行业要的,从来不是非此即彼的”创新”或”稳健”,而是两者之间的平衡。能否帮客户既迈得开步子、又站得稳脚跟,正是这场金融AI全栈云竞速中,最终拉开差距的地方。

如需进一步了解IDC相关研究,或就中国金融云AI市场发展趋势进行深入交流,欢迎与IDC联系,获取更多洞察与数据支持。