北京,2026年6月5日——国际数据公司(IDC)最新发布的《2026年第一季度全球手持智能相机市场跟踪报告》显示,2026Q1全球手持智能相机市场出货量达到414万台,同比增长33%。销售额超过105亿元人民币,同比增长20%。IDC预计,至2030年,全球手持智能相机市场规模将会超过4000万台,五年复合增长率接近18%。

2026Q1全球手持智能相机发展状况

  • 运动相机市场:26Q1全球运动相机出货量接近201万台,同比增长39%。平均单价2149人民币,同比下降11%。推动市场高速增长的主升浪来自于大疆和影石爆款明星产品热销,同时上一代产品的强势调价促销也为厂家贡献了良好业绩。大疆和影石出货量市场份额同比攀升13个百分点,老牌厂商GoPro生存空间继续被挤压。从运动相机市场细分品类来看,可拆卸运动相机即“拇指相机”出货量同比增长惊人超过350%,不可拆卸运动相机同比增长16%。
  • 云台相机市场:26Q1全球云台相机出货量同比增长超过18%,平均单价2840人民币,同比下调12.5%。此市场大疆继续保持独占领先优势。手持云台相机市场在产业上下游供给侧和最终用户需求端都保持了高热度,26年将迎来产品突破升级和新竞争厂商出现。
  • 全景相机市场:26Q1全球出货量超过50万台,同比增长高于50%。影石在全景相机领域排名第一且大幅领先,出货量份额接近七成,大疆Osmo360火爆单品保持热度拿下超过两成市场。

2026Q1全球手持智能相机市场主要厂商概况:

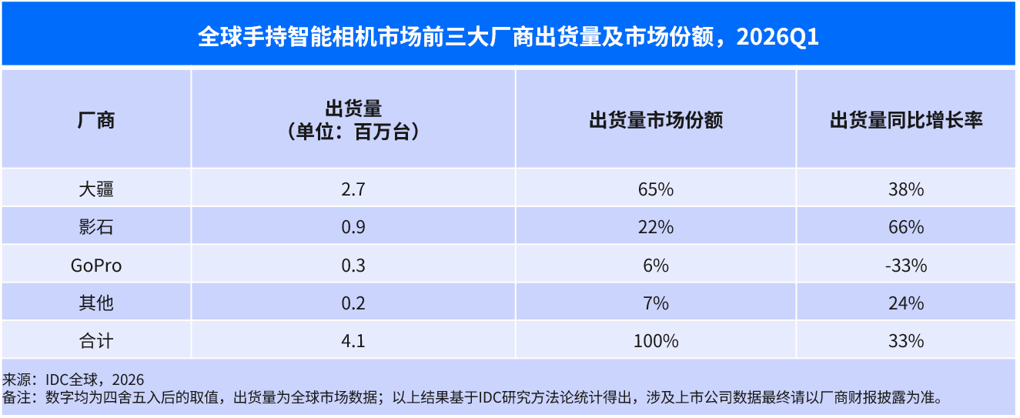
26Q1全球手持智能相机市场,大疆以65%出货量市场份额保持第一,同比增长38%。影石出货量市场份额达到22%,同比增长66%排名第二。GoPro受到大疆和影石的全球激烈竞争出货量同比持续萎缩。
大疆

大疆凭借无人机领域全产业链成功多年积累的硬件核心技术(多轴云台稳定系统,影像及多传感器融合技术,飞行及运动控制系统)向手持智能影像设备迁移,打造高可靠性和易用性的影像产品全系列矩阵。品牌拥有完善供应链体系,成本抗压弹性,议价能力,上游核心部件定制化能力均较强。26Q1云台相机自身出货量占比超过一半,Pocket4新品预售火爆断货,3代产品调价后继续受到市场追捧。不可拆卸运动相机出货量市场份额同比上升3和百分点增长至54%,可拆卸运动相机即“拇指相机”单品Osmo Nano在25年发售后保持热销,26Q1出货量拿下过半市场份额。在全景相机领域,26Q1大疆凭借Osmo360单品赢得22%出货量市场份额占稳这一市场。

影石

26Q1全球出货量接近90万台(结果基于IDC研究方法论统计得出,涉及上市公司数据最终请以厂商财报披露为准)。影石持续加大投入研发资源,凭借在全景相机领域作为全球领军厂商的多年技术积累,已经在差异化应用场景和应用软件方面形成独特优势和壁垒。其系统应用软件在拼接算法,多场景防抖,深度主体追踪以及在AI助手一键剪辑方面获得庞大用户群的广泛认可。影石在全景相机领域虽然遭遇挑战,但26Q1仍旧保持了接近七成出货量市场份额。在不可拆卸运动相机领域,AcePro2街拍套装促销取得成功,出货量市场份额创新高超过17%,同比吃掉7个百分点。在可拆卸运动相机市场,尽管面临强势竞争,产品出货量同比增长翻倍且Go Ultra表现亮眼。此外云台相机高热度新品将在第二季度全球出货也为厂商锚定新的增长点。

GoPro

遭遇中国厂商全球激烈竞争,面临供应链成本上涨,削减库存等多方面压力同比大幅收缩。26Q1全景相机出货量同比跌幅大于运动相机,运动相机内部Lit Hero以及Hero低价老品自身比重增加,整体均价同比下调17%。虽然发布M1系列新一代运动相机以及继续推广全景Max2新品但市场表现有待观察。

IDC分析师洞察与市场未来发展预测:

  1. 手持智能相机从硬件堆叠到全产品矩阵,进一步深度挖掘场景覆盖。回顾手持智能相机发展历程,关键硬件研发诸如大底传感器,可变光圈系统,8K超高分辨率等技术仍旧是推动市场发展的核心因素。从产品端侧看已经由全景相机,不可拆卸运动相机,手持云台相机到可拆卸运动相机形成手持智能影像全产品矩阵。与此同时覆盖用户人群由小众极限运动极大拓展到广大运动爱好者到Vlog创作者和大众记录日常。厂商仍旧致力于深挖用户场景需求乐此不疲。
  2. AI融入手持智能影像终端最终能为用户带来什么价值。目前AI功能主要集中于AI场景深度感知,AI智能降噪,多帧合成算法,暗光画质增强,AI后期智能剪辑成片等功能型应用。AI融入手持智能影像终端的未来愿景是成为智能影像机器人终端的底座和大脑,由被动的影像记录终端成长为基于海量数据采集可以按照用户各种需求主动生成创作内容的超级智能体。
  3. 中国是手持智能相机的第一大市场。从2025年度出货量来看,中国贡献了超过一半的市场份额,26Q1延续了这种趋势且贡献进一步有所加大。除中国外,美国,西欧,亚太区和日本是全球前四大市场。海外市场产品渠道营销是国内厂商投入资源的核心议题之一。
  4. 手持智能相机市场的渗透率仍旧较低,未来增长空间可期。手持智能相机市场无论从产业资本和上下游供给侧还是最终用户消费者层面仍旧保持高热度。无论哪一条细分产品线市场的未来五年复合增长率均高于15%。IDC预计,至2030年,全球手持智能相机市场规模将会超过4000万台,总体复合增长率接近18%。

IDC手持智能相机定义

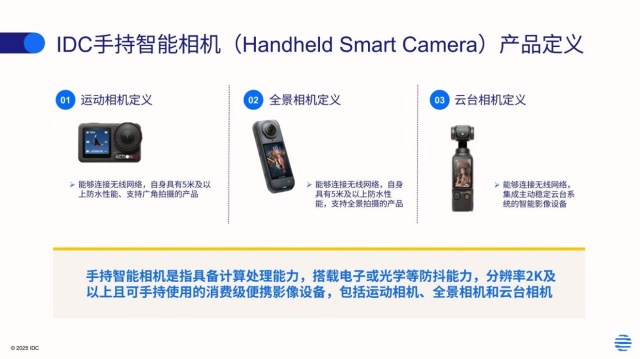
IDC对手持智能相机的定义是指具备计算处理能力,搭载电子或光学等防抖能力,分辨率2K及以上且可手持使用的消费级便携影像设备,包括运动相机(包含可拆卸和不可拆卸运动相机两种形态),全景相机和云台相机。
IDC更多相关详细内容,敬请关注:IDC WW Quarterly Handheld Smart Camera Tracker

请点击此处与我们联系。
Jacky Xue

Jacky Xue - Research Manager

Jacky Xue is a research manager with the Client Systems Research team at IDC China, responsible for projector, IWB and enterprise client devices research and analysis. His responsibilities include tracking the industry data, monitoring the market development, analyzing the future…

Key Takeaways:

  • NXP introduced the Neural Axis architecture and is leveraging its acquisition of Kinara to expand its edge-AI NPU capabilities.
  • NVIDIA launched a platform for humanoid robotics, including world simulation and reference hardware.
  • Qualcomm introduced the Dragonwing IQ10, a fully integrated robotics SoC (system-on-chip) targeting production deployment by September 2026.
  • Intel formally launched Intel Robotics as a dedicated business unit with 130+ commercial design partnerships.

Computex Taipei 2026 demonstrated that robotics is no longer a side story at the world’s largest computing show. For the first time in its 45-year history, Computex dedicated an entire exhibition zone to Robotics and Physical AI. Major semiconductor vendors arrived not just with products but with a strategic position on who should own the market for the processors used in robotics.

Nvidia Leans on CUDA to Train and Run Physical AI

NVIDIA came to Computex with the boldest claim: that it intends to own the software layer that every robot in the world is developed on and runs on. Jensen Huang unveiled a complete platform spanning AI models for humanoid robots, a world simulation environment that lets developers train robots faster and at far lower cost, and a reference robot design that any manufacturer can build upon. Partners such as Stanford and ETH Zurich are already committed to the platform.

NVIDIA is releasing models and development tools openly to entice the robotics ecosystem onto its platform. It is taking the same playbook that built its dominance in datacenter AI and applying it to robotics. NVIDIA’s solutions are higher cost and have higher power consumption than its competitors.

NVIDIA’s benchmark claims are strong, but the real test is unstructured real-world performance over sustained operating periods, not controlled evaluations. The reference design approach smartly avoids NVIDIA competing with potential hardware partners. Watch whether robot manufacturers outside the Unitree partnership accept a platform built on a competitor’s silicon roadmap. That tension is where the ecosystem story either succeeds or stalls.

Qualcomm’s Dragonwing IQ10 Aims for Ease of Development

Qualcomm made a sharper, more immediate argument. Building a robot today means stitching together components from dozens of vendors, and every seam in that system is a source of cost, delay, and failure. Qualcomm’s answer is a single fully integrated platform, the Dragonwing IQ10, that collapses that complexity into one deployment-ready system. Cristiano Amon drove the point home by bringing a full-sized humanoid robot on stage and demonstrating it live. The commercial target is clear: the growing tier of robot makers and industrial operators who want to move from prototype to production without building their own technology stack. Early partners include NEURA Robotics, Advantech, and NEXCOM, with broader availability by September 2026.

Qualcomm’s position is built on a decade of designing chips for cars, where real-time reliability is non-negotiable. That heritage is a genuine differentiator in industrial Robotics. Pricing and actual partner shipments will be the proof points to watch.

Intel Robotics Goes the Open Source Path

Intel took the longest-term angle of the three. The company formally launched ‘Intel Robotics’ as a dedicated business and introduced an open-source framework designed to close the gap between robots that work in the lab and robots that work reliably on the factory floor. With more than 130 commercial design partnerships already in place, Intel has a broader installed base than its keynote visibility might suggest.

The clearest demonstration came from Sensory AI’s Ella, a robot barista operating in live retail environments, running multiple AI tasks simultaneously on a single Intel Panther Lake SoC. The one SoC has replaced what would have required multiple processors and a more complex system.

Intel’s open-platform strategy is a smart way to compete without going head-to-head with NVIDIA’s brand authority or Qualcomm’s automotive credibility. The risk is that open ecosystems take time to build, and Intel needs its developer community to grow faster than the incumbent platforms consolidate

Intel is also building on a long history of providing processors for edge infrastructure used for industrial automation and robotics, including the coordination of robots in a factory. Intel also has a history with its RealSense camera sensors, demonstrating drones that could fly through a forest, for example, dodging trees, and providing drone show coordination solutions. Intel is not new to robotics or to working with robotics companies, and it will be able to leverage decades of experience.

NXP’s Neural Axis Architecture Likened to a Nervous System for Robots

NXP used the closing keynote of Computex to make the most pointed argument of the show. CEO Rafael Sotomayor’s talk, ‘Bringing AI into the Real World,’ unveiled the Neural Axis architecture — a three-layer, biologically inspired framework spanning reasoning, coordination, and reflexive intelligence. His thesis: the defining challenge of physical AI is not how smart a machine is, but whether it can react in milliseconds without round-tripping to the cloud. Intelligence, he argued, cannot be centrally scaled; it has to be distributed so that no single point of failure can stop the machine.

NXP demonstrated the architecture across drones, software-defined vehicles, and humanoid robots, wrapped it in a trust framework built on containment, protection, verification, and adaptation, and tied it to its eIQ developer toolkit and its $307 million acquisition of edge-AI NPU maker Kinara. The framing casts NXP as the owner of the robotic nervous system—the reflexes and safety layer beneath whichever “brain” handles high-level reasoning.

NXP’s wide portfolio of processors, microcontroller units (MCUs), neural processing units (NPUs), connectivity technologies and analog components is highly complementary to the main processor.  NXP can own the deterministic, safety-critical layer where decisions happen in real time. Its decades of heritage in automotive and industrial silicon are hard to replicate. It can apply its experience in reliable solutions and functional safety to the robotics space. NXP is also partnering with Nvidia and supporting its software stack.

The Robotics Semiconductor Landscape Became More Competitive After Computex 2026

Computex’s new AI Robotics Zone drew Taiwan’s full supply chain of components, motors, and system builders. AI-related industries are forecast to account for around 70% of Taiwan’s exports over the next six months.

Beyond the headline platforms, Computex surfaced a sharper debate about what robotics requires to succeed at scale. NXP, as covered above, pressed the case that responsiveness — not raw intelligence — is the real constraint on physical AI. ABB, the industrial automation giant, showed that its NVIDIA partnership is enabling simulation accuracy close enough to real-world conditions that training times and deployment risks are falling significantly. ASUS entered the consumer market with service robots for healthcare and senior care, backed by an orchestration platform designed to work across brands and devices.

Robotics companies will have choices across processor vendors, processor architectures, closed versus open development platforms and software solutions, and various performance, power consumption, and cost specifications for CPUs and accelerators. The robotics market is not new, but the training and inference on new AI models – physical AI – is new, and the semiconductor vendors that can best support these new models with low power consumption and low cost will be best positioned to hit the sweet spot of unit volume and ASPs. There is also a lot of opportunity for adjacent companies such as NXP, IP vendors such as MIPS, and all the other semiconductors that provide other processors, connectivity, sensors, and power-related components.

Stay ahead of the physical AI semiconductor market. Access IDC’s latest forecasts, vendor analysis, and industry data at IDC Semiconductor Research. Speak with our analysts, contact us today!

Phil Solis - Research Director, Semiconductors and Enabling Technologies - IDC

Phil Solis is Research Director within IDC’s enterprise infrastructure global research domain. He focuses on client computing and connectivity as part of the Semiconductors and Enabling Technologies subdomain. Phil’s coverage spans semiconductors in PCs, media tablets, smartphones, and wireless and mobile connectivity technologies.

Navkendar Singh - Associate Vice President - IDC

Navkendar Singh is a Associate Vice President with IDC India, based in Gurgaon. His research domains encompass deep-dive research and insights in and around mobile devices, smart homes, PCs, tablets, wearables, and the printing market in India, Bangladesh, and Sri Lanka. He is also involved in building IDC's successful channel research programs for these domains at city and state levels. Navkendar also leads research related to analyzing the role of devices, emerging business engagement models, the impact of emerging technologies on devices, and emerging personas related to Future of Work.

At the start of 2026, many in the semiconductor ecosystem were expecting some breathing room. New fab capacity was coming online. Consumer demand had softened. The AI infrastructure build-out, the thinking went, would eventually plateau. That reset hasn’t arrived. If anything, the pressure points have multiplied.

Why will the memory market be tight through 2027?

The memory market entered 2026 riding strong pricing momentum, and it has not let up. Server demand continues to grow faster than supply can respond. Consumer segments like smartphones and PCs are contending with bill-of-materials costs that are rewriting device economics. And the AI infrastructure build-out, far from normalizing, is generating a demand profile that behaves differently from anything the memory industry has navigated before.

The anticipated relief will not arrive because the forces driving tightness will be compounding.

Is the memory shortage structural or cyclical?

This is the critical question, and the answer matters for every decision the industry makes, from procurement to capex to product roadmap.

Memory is no longer a cyclical commodity. It has become a strategic infrastructure input.

For decades, the semiconductor industry ran on a recognizable rhythm: demand surges, prices spike, supply catches up, prices correct. Painful, but predictable. What the data is showing now is different— a fundamental shift in demand architecture, away from consumer electronics, where seasonality and upgrade cycles govern behavior, and toward AI training and inference infrastructure, where demand doesn’t normalize between quarters. It compounds. Every inference workload deployed creates a baseline the next workload builds on.

High-bandwidth memory (HBM), high-density DRAM, and enterprise-grade NAND are no longer priced or allocated the way standard components were. Supply agreements are longer, allocation is tighter, and the gap between players who have locked supply and those who haven’t is widening. Major memory producers have been explicit in their public guidance: tight conditions are not a short-term anomaly. That’s not analyst projection. It’s the market telling you what to plan for.

What is driving continued memory tightness through 2027?

On the demand side, AI infrastructure is doing most of the work. GPU servers are expanding at a pace that absorbs memory capacity before supply can rebalance. Inference workloads, once considered lighter than training, are proving just as memory-intensive at scale, particularly as enterprises move from pilots to production. On-device AI in premium smartphones and AI PCs is adding a distributed demand layer on top of the data center story.

On the supply side, the picture is more controlled than constrained. Major memory manufacturers have internalized the lessons of previous cycles. They are exercising deliberate capacity discipline, prioritizing advanced nodes and HBM over legacy products, managing bit output carefully, and letting pricing reflect scarcity rather than racing to fill every wafer. New fabs are coming online, but lead times are long, and geopolitical factors, including technology restrictions affecting key Chinese producers, add meaningful uncertainty to the global supply calculus.

The result is a market where supply is not absent. It is being managed. And the beneficiaries of that management are not evenly distributed.

Five questions the semiconductor industry should be tracking

These are the signals I’m watching most closely, relevant to memory makers, OEMs, system integrators, distributors, and the financial community worldwide.

1. How will HBM allocation evolve as competition intensifies? HBM is the most constrained and highest-value DRAM segment. As more producers enter HBM manufacturing and AI chip architects compete for allocation, pricing and availability could shift quickly, in either direction. Watching who wins design wins and on what timeline matters.

2. When does the consumer segment recover, and on what terms? Smartphones and PCs are both under severe BOM pressure in 2026. The question isn’t just when volumes recover. The real question is whether the product economics of affordable devices can be rebuilt around structurally higher memory costs, or whether product mix and ASPs shift permanently upward.

3. What is China’s effective memory supply capacity? YMTC and CXMT are reaching significant production milestones in 2026, but technology restrictions will continue to limit node access. How this plays out in global NAND and DRAM supply, and where it creates openings or risks for players across the value chain, remains fluid and worth monitoring closely.

4. How are OEMs and procurement teams adapting sourcing strategies? The spot-buying, short-contract model is increasingly unworkable. Across industries, buyers are rethinking long-term agreements, dual-sourcing, and design choices to reduce memory dependency risk. Who has adapted, and who hasn’t, will determine competitive positioning as conditions evolve.

5. Where does the DRAM and NAND pricing trajectory go from here? Pricing has trended in one direction for much of the past 18 months. The conditions that produced that momentum are largely still in place, but they won’t hold indefinitely. Understanding what triggers a reversal, how quickly it moves, and which segments are most exposed is essential for anyone making capital allocation or inventory decisions today.

Frequently asked questions about the current memory market

What is causing the memory chip shortage? The primary driver is AI infrastructure demand, particularly for HBM and high-density DRAM in GPU server configurations, growing faster than manufacturers are expanding capacity. This is compounded by deliberate supply discipline among major producers, who are prioritizing advanced nodes and profitability over volume growth.

Will memory prices come down in 2027? Based on current analysis, the supply-demand imbalance expected to persist beyond 2027 in key segments. The conditions that produced sustained pricing pressure remain largely in place. I’ll be presenting the full forecast and scenario analysis, including pricing trajectories through 2030 at IDC’s Memory Market Outlook webinar on July 8.

What is HBM and why does it matter for the memory market? High-bandwidth memory (HBM) is a high-performance DRAM interface used primarily in AI accelerators and GPU systems. It is among the tightest and highest-value segments of the memory market today, with demand driven by AI training and inference infrastructure. HBM capacity constraints directly affect the availability and pricing of AI compute systems globally, making it a bellweather for the broader memory market outlook.

Join me on July 8 for the full picture

Learn about IDC’s detailed, data-driven view on all of the questions above at the IDC Memory Market Outlook webinar on July 8, 2:00 PM SGT.

Drawing on IDC’s trusted tech intelligence and worldwide memory demand and supply forecasts through 2030, I’ll cover where DRAM, NAND, and HBM pricing is headed, how the supply-demand imbalance is expected to evolve, and what the scenarios look like for every segment of the value chain, from the rest of 2026 through the end of the decade.

If memory is a constraint in your business today, or if you need to navigate your next move with confidence in a market where the old playbook no longer applies, I hope to see you there. Register today!

Soo Kyoum Kim - Associate Program Vice President, Semiconductors and Enabling Technologies - IDC

Soo Kyoum Kim is Associate Vice President within IDC’s Enterprise Infrastructure global research domain. He focuses on DRAM and NAND Memory as part of the Semiconductors and Enabling Technologies subdomain. Soo Kyoum’s research covers demand and supply analysis for DRAM and NAND, memory consumption for server workloads, next generation memory, and emerging memory markets. He provides insights on the demand and supply dynamics in industry, chip pricing, competitor, and fab capacity. He also covers the dedicated foundry market.

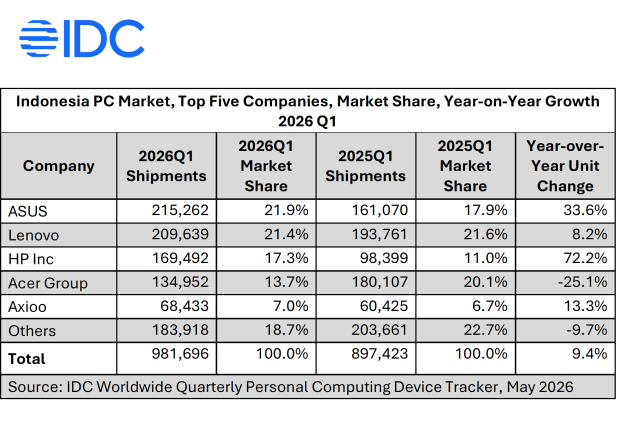
Indonesia’s PC market (encompassing desktops, notebooks, and workstations) shipped 982,000 units in Q1 2026, up 9.4% year over year, exceeding expectations despite rising component costs and tightening supply, according to IDC’s Worldwide Quarterly Personal Computing Device Tracker.[MD1]  The growth was driven by frontloading across both consumer and commercial channels, as distributors rushed to secure inventory ahead of anticipated price increases.

What’s Driving Indonesia PC Market Growth?

Rising device prices prompted end-users and channels to accelerate purchases in Q1, ahead of expected further increases. Channels moved quickly to build inventory buffers as macroeconomic uncertainty made near-term pricing unpredictable.

This frontloading is a double-edged result. It inflated Q1 figures while simultaneously pulling demand forward, leaving less runway for the remainder of 2026.

The acceleration in Q1 comes at a cost to 2H 2026. While budget-flexible organizations moved purchases forward, others have begun reducing expenditure, a trend IDC expects to intensify, contributing to sharp shipment declines in Q3 and Q4.

Analyst Insight

“Indonesia remains a strategic market for PC vendors. The allocation of shipments, particularly for lower-priced products, makes that clear. Moving forward, however, macroeconomic headwinds and ongoing component shortages are forecast to continue to push the prices higher, likely triggering a decline in demand in the near term.” 

— Leonard Adiarto Sudjono, Senior Market Analyst, Devices Research, IDC 

Vendor Outlook: Who Won the Quarter?

IDC Outlook: What’s Next?

Frontloading, that began in Q4 2025 and carried into Q1 2026 reflects a sustained effort by global and local players to secure supply. Q2 2026 will see less stocking activity due to increasing economic uncertainty and anticipated further price hikes, with shipments expected to decline 12.5%. The second half of 2026 is expected to see considerably more negative trends, as inventory piles up and demand weakens. IDC forecasts Q3 to contract 35.4% and Q4 to fall 40.6%, bringing the full-year 2026 decline to 22.9%

What may improve the market outlook? 

  • Continued new product releases may sustain short-term purchasing. Apple’s MacBook Neo, positioned at an attractive price point and launched in Indonesia in May, could drive incremental demand in Q2, though this will depend on the supply availability and allocation to Indonesia market.
  • Indonesia’s government recently revised its policy outlook, including halting expansion of the “free meals” program that had absorbed a significant part of the fiscal budget. These moves have marginally improved investor sentiment, reflected in a slight recovery of the Rupiah. Sustained movement in this direction through 2H 2026 could provide a modest improvement in market sentiment.

What could slow it down?

  • Inventory correction is coming. High channel inventory levels combined with slowing sell-through will lead to reduction in shipments as early as Q3.
  • Macroeconomic pressures are mounting. Currency fluctuations, rising SMB taxation rates, and increased fuel prices from June have intensified market uncertainty and will dampen end-user purchasing power.
  • Supply-side pressures are compounding. Supply constraints, rising component costs, and increasing price sensitivity among end-users will also lead to further negative sentiment in the market.

Key Indicators to Watch: Currency, Taxes, and Inventory Turnover

Currency movements, the widespread impact from new tax policies, and inventory turnover rates will determine the rest of this year’s outlook. With stock levels already high, macroeconomic headwinds are likely to add to the negative impact that will shape the market going forward. 

Frequently Asked Questions

How large is Indonesia’s PC market?

IDC tracked 982,000 units shipped in Q1 2026, up 9.4% year over year.

Which PC vendor leads in Indonesia?

ASUS led the Indonesia PC market in Q1 2026 with a 21.9% market share, followed closely by Lenovo at 21.4%.

What is IDC’s forecast for Indonesia’s PC market in 2026?

IDC forecasts a full-year 2026 decline of 22.9%, with Q3 contracting 35.4% and Q4 falling 40.6%, as inventory correction and macroeconomic pressures weigh on demand.

Go deeper with IDC. Whether you want access to the full tracker dataset or a direct conversation with our analysts, we’re ready to help you navigate your next move.

Leonard Adiarto Sudjono - Senior Market Analyst - IDC Indonesia

Based in Jakarta, Indonesia, Leonard joined IDC as a Senior Market Analyst in May 2023 and has since been responsible for managing IDC’s Trackers for several products, starting with Hardcopy Peripherals, Scanners, Consumables and, since 2024, Industrial Printers, before moving to the Devices team in 2026 where he now covers Personal Computers and Monitors.

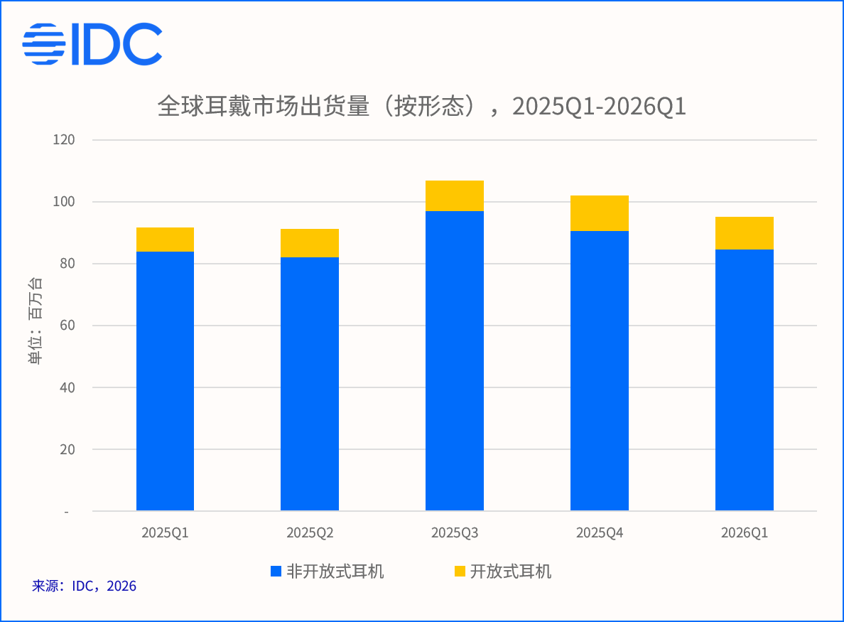
国际数据公司(IDC)最新发布的2026年第一季度全球耳戴市场数据显示,开放式耳机出货量同比增长39.9%,在整体耳戴市场仅增长3.9%的背景下表现突出。但IDC认为,比增速更值得关注的是品类结构,竞争格局与市场需求的多重转变。品类结构上,耳夹式占比首次过半,稳固其主流产品形态的地位。当前全球开放式耳机市场由中国厂商主导,海外品牌加速入局,行业竞争持续升温。与此同时,AI技术为市场注入全新动能,智能化将成为下一阶段竞争核心。

根据IDC最新发布的《全球可穿戴设备市场季度跟踪报告,2026年第一季度》显示,2026年一季度全球耳戴市场出货9,520万台,其中开放式出货1,067万台,同比增长39.9%,占比达到11.2%。凭借差异化的佩戴体验,开放式耳机在蓝牙耳机品类中的出货占比正持续攀升。

IDC三大核心洞察

结合开放式整体市场走势与市场竞争态势,2026年一季度全球开放式市场耳机三大核心洞察如下:

洞察一:细分品类格局重塑,耳夹式领跑市场增长

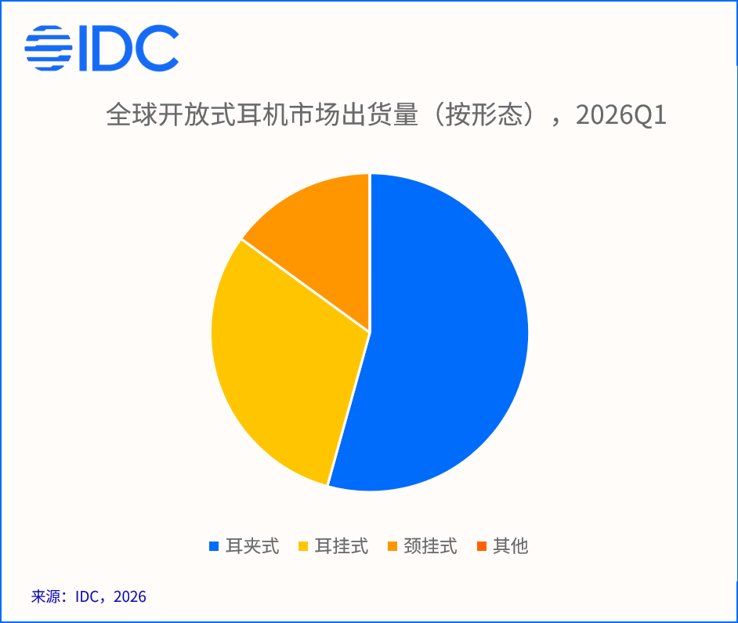
开放式耳机细分形态迎来明显更迭,品类内部竞争格局持续重构。2026年一季度,耳夹式在开放式产品中占比54.3%,同比份额增幅超10个百分点,已成为全球开放式耳机的主流形态。该品类凭借精巧的外观与多场景适配的能力受到市场认可,叠加时尚属性带来的溢价能力,部分采取机海战术的厂商逐步调整布局重心,从耳挂式赛道转向加码耳夹式产品。耳挂式同比增长11.8%,市场份额有所回落,凭借佩戴稳定性,现阶段头部品牌主要聚焦于运动细分场景。作为开放式领域成熟度最高的品类,颈挂式产品凭借骨传导技术深耕运动赛道,并依托游泳等专属场景稳固市场定位,同比增长11.9%,增速保持稳健。

洞察二:中国厂商主导市场,差异化竞争格局深化

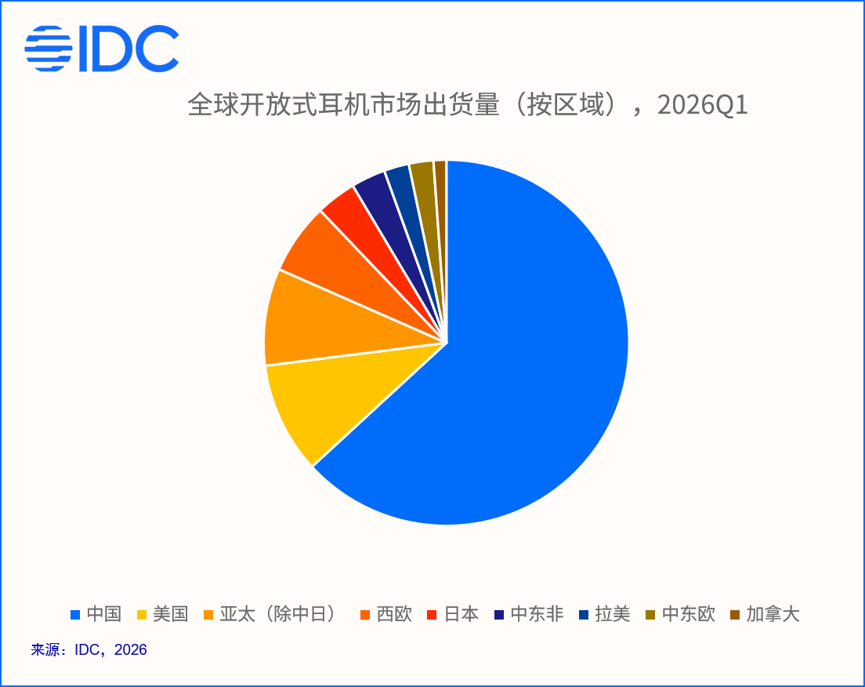
中国是开放式耳机起步最早,规模最大的核心市场,2026年一季度中国市场出货量占比超过六成。美国,亚太(不含中国和日本)及西欧市场紧随其后,增长态势亮眼。中国厂商利用先发优势全球布局,凭借完善的供应链与多元化产品矩阵持续抢占全球市场份额。市场主流集中在50美元以下及100美元以上两大价格区间,分层竞争特征显著。100美元以上高端市场中,核心技术,音质表现,品牌力与智能化成为竞争关键。韶音,华为凭借综合实力稳居领先位置。Bose,JBL等海外传统音频厂商也加码布局,依靠声学技术优势夯实产品实力,丰富自身产品线。50美元以下入门市场主打性价比,厂商凭借多样外观,新颖形态及丰富机型吸引消费者,中国与印度厂商为该市场主力。

洞察三:AI赋能硬件升级,智能化渗透空间广阔

随着蓝牙耳机硬件日趋同质化,AI技术已成为行业破局的重要方向。智能服务的迭代优化,离不开长期佩戴所沉淀的用户数据,而开放式耳机适配长时间佩戴的特性,为AI功能落地提供了天然优势。部分中国厂商已将产品搭载AI功能作为营销亮点,入门级产品主要对接第三方云端大模型,落地场景以实时翻译,会议纪要等办公需求为主,相关功能主要依托手机APP运行,并不具备端侧实时运算能力。优质的智能化体验目前仍集中于中高端产品线。定位商务场景的厂商,搭配自研大模型与端侧处理芯片,将AI打造为核心竞争壁垒,而非常规附加功能。手机品牌则凭借自有操作系统优势,整合自研大模型与终端硬件,构建“系统+模型+硬件”一体化生态闭环。该模式深度绑定用户使用习惯,有效强化用户粘性与品牌忠诚度。目前全球市场中的AI功能整体渗透率有待提升,品类智能化升级仍拥有广阔发展空间。

IDC建议

面对开放式耳机品类格局重构,中国厂商领跑全球,AI技术驱动产品升级的行业新态势,IDC为行业参与者提出以下三点切实可行的战略建议:

建议一:找准市场定位,优化产品结构与资源布局

开放式耳机品类加速分化,市场格局不断演变。厂商需明确自身赛道定位,避免盲目跟风内卷。耳夹式增长势头强劲,而耳挂式凭借更大的机身空间,更利于搭载元器件,落地 AI相关功能。厂商需结合自身核心优势搭建产品矩阵,平衡流量型与技术型产品布局,合理分配研发与产能资源,打造符合行业长期发展趋势的产品体系。

建议二:依托产业优势,深耕差异化竞争与品牌力建设

依托成熟的供应链与规模化制造能力,中国厂商可充分发挥产业优势。作为市场的先发参与者,应把握发展窗口期,聚焦品牌建设,规避同质化低价竞争。同步推进本土化运营,结合各地消费特征,文化偏好制定市场策略,以差异化产品与本地化服务提升用户认同,持续夯实全球品牌价值与综合竞争力。

建议三:着眼长远发展,强化AI核心能力建设

随着蓝牙耳机产品同质化问题日益凸显,厂商应将AI智能化升级确立为长期核心战略。依托开放式耳机可长时间佩戴、持续沉淀用户数据的特性,在现有的语音助手,AI降噪等应用基础上,拓展个性化服务,智能自适应调节等高阶体验。推动AI从单纯的营销亮点转变为核心产品实力,把握行业智能化转型机遇,充分释放市场增长潜力。

IDC中国研究经理戴翘楚认为,当前全球开放式耳机品类结构加速调整,中国厂商依托产业积淀与先发优势领跑市场,AI智能化则将成为行业下一阶段竞争焦点。厂商需明确发展方向,打造差异化产品,推进全球化布局,同时坚持长期投入,深耕AI核心技术,夯实可持续发展根基。

综合来看,IDC认为2026年第一季度全球开放式耳机市场的核心变化在于:耳夹式正在重塑品类格局,中国厂商持续主导全球市场,而AI技术的实际落地仍处于早期阶段。对于行业参与者而言,单纯依靠形态创新或价格策略的增长空间正在收窄,下一阶段的竞争将更多取决于厂商在技术深耕和智能化能力上的长期投入。市场仍在高速增长,但赛道逻辑正在变化,唯有做出清晰战略选择的厂商才能在竞争中占据主动。

如对本次报告内容感兴趣,或咨询其他相关内容,欢迎与IDC联系,以获取更多信息或探讨合作机会。

请点击此处与我们联系。

腕戴设备市场正在发生静默而深刻的结构性转折。智能手表与手环的走势分化、各价位段需求的冷热不均、区域市场之间的增长落差——这些表象背后,同一个问题是所有参与者必须回答的:当普及红利消退,增量从何而来?本文基于IDC最新发布的《全球可穿戴设备市场季度跟踪报告》,梳理2026年第一季度全球腕戴市场的三大结构性特征、头部厂商的应对策略,以及中国市场的独特发展路径。


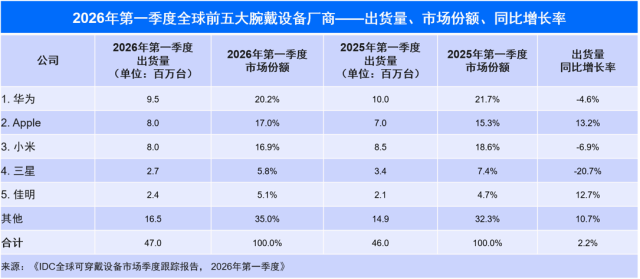
根据国际数据公司(IDC)最新发布的《全球可穿戴设备市场季度跟踪报告》,2026年第一季度全球腕戴设备市场出货量为4,705万台,同比增长2.2%。腕戴设备市场包含智能手表和手环产品。其中,全球智能手表市场出货量3,703万台,同比增长4.8%。手环市场出货量1,002万台,同比下滑6.1%。腕戴产品发展背后,全球市场呈现出哪些特点?头部厂商表现如何?中国市场又将呈现哪些异同?本文将为您一一解读。

2026年一季度全球腕戴市场发展的三大特点

根据IDC跟踪报告,2026年一季度全球腕戴市场发展呈现以下三个显著特点:

特点一:手表走强,手环疲软

智能手表凭借功能升级稳步增长,部分分流手环用户。手环受去年需求提前透支、存储成本抬升影响,再加入门手表价格下探抢占市场,需求持续承压,整体走势偏弱。

特点二:价位结构升级,入门稳、高端旺

大环境承压下,百元美金以内入门产品依靠刚需稳住出货量;300 美元以上高端机型依托软硬件迭代、健康医疗及AI功能升级,消费升级需求逐渐释放,高端价位段增速突出。

特点三:区域发展分化

中国凭借新品发布与电商促销,成为全球增长主力;美国、拉美受益换新与渗透率提升小幅增长,其他地区受经济影响需求表现平淡。

2026年一季度全球腕戴市场Top 5厂商表现

华为

2026 年一季度华为腕戴产品全球出货量登顶。华为时隔5年推出 WATCH GT Runner 2,深耕专业跑步赛道;Ultimate 2 高尔夫版满足进阶人群的专业需求;手环 11 系列补齐入门价位空档。全品类阶梯矩阵落地,完善价格与功能布局,稳固华为穿戴出货领先优势。

Apple

2026年一季度中国市场成为苹果智能手表全球增长核心驱动力。品牌提前落地多轮促销活动有效拉动终端销量;产品高端定价优势明显,可更大程度消化上游元器件涨价带来的成本压力,对冲供应链紧缺负面影响,支撑中国市场业绩稳步上行。

小米

2026年一季度小米智能手表表现优于手环品类。品牌落地 S5 系列新品,持续加大中高端 Watch 5 铺货力度,稳步向上优化产品结构。中高端机型逐渐放量,小米加速优化产品结构,逐步向中高端市场纵深布局。

三星

三星全球主推 Galaxy Watch8 及 8 Classic,但整体出货受内部战略调整小幅收缩。欧美成熟市场需求承压,中东、非洲等新兴市场依托品牌口碑与渗透率提升实现小幅增长,成为品牌现阶段为数不多的增量市场。

佳明

佳明坚守专业户外、运动细分赛道,深耕垂直用户巩固专业产品壁垒;同时加速产品迭代、拓宽大众消费产品线。配合各地阶段性营销与促销落地,品牌兼顾专业与大众市场,在多个区域实现出货同比增长。

2026年一季度中国市场发展的三大特点

IDC报告指出,2026年第一季度中国腕戴市场出货量1814万台,同比增长3.5%;其中成人智能手表出货量888万台,同比增长15.3%,儿童手表出货量442万台,同比增长22.4%,手环市场出货量483万台,同比下滑22.2%。

特点一:入门价位补位扩容,五百元档市场回暖

500 元以下成人智能手表一季度出货量回暖。头部品牌产品迭代逐步撤出该价格带,中小品牌顺势优化产品配置填补空白。上游存储成本抬升环境下,该档位机型性价比凸显,精准承接入门刚需,拉动该价位稳步回暖。

特点二:渠道分化凸显,线上增速领跑线下

产品成熟带动消费者选购趋于理性,用户习惯线上比价筛选机型。叠加直播、多平台大促等多元电商业态持续扩容,线上渠道出货增速显著跑赢线下。线下侧重体验成交,增长相对稳健,线上已成为拉动大盘增量的核心载体。

特点三:产品精细化发展,功能人群多元细分

市场开始逐渐尝试跳出同质化堆砌,逐步走向场景与用户分层。更具有针对性的女性向和青少年设计的产品更多出现,在全智能、专业健康、专业运动、日常健康和轻运动等维度打造差异化卖点,围绕细分需求定制产品,精细化细分成为行业明确发展趋势。

针对技术供应商和采购方的建议

建议一:产品分层精细化布局,打造差异化竞争壁垒

厂商应搭建阶梯化、差异化产品矩阵,规避同质化与低价内卷。面对存储成本上涨压力,各价位段需优化配置与定价策略。中小厂商依托优质体验稳固入门市场,头部品牌深耕高端健康、AI、运动功能迭代。通过场景、功能、外观多元差异化设计,覆盖多人群需求,筑牢产品竞争壁垒。

建议二:双线渠道协同布局,高效盘活存量增量市场

厂商需优化线上线下双线渠道协同布局,加大电商、直播等线上资源投入,依托平台优势快速走量、盘活存量。线下门店重点聚焦高端机型体验、售后服务与高价值用户转化,打造线上引流、线下提质增收的良性渠道体系。

建议三:区域市场差异化深耕,分散经营风险挖掘增量

厂商应实施差异化区域运营策略,平衡市场规模与盈利水平。欧美成熟市场避开低价内卷,深耕专业运动、健康垂直圈层守住利润;积极开拓拉美、中东非等新兴市场,凭借性价比快速提升渗透率。同时深耕中国本土市场,依托新品迭代与电商促销持续激活换新增量。

分析师观点与行业建议

IDC认为,全球腕戴行业已告别普及放量期,正式迈入存量精细化竞争阶段。增量不再依靠全民新机普及,转而由产品升级、细分人群、区域下沉三大逻辑驱动。成本波动加速行业洗牌,倒逼品牌放弃低价同质化内卷,依托价位分层与场景细分挖掘新增量,未来品牌综合产品架构、渠道与区域布局的能力将成为拉开份额差距的关键。

延伸阅读与沟通:

如需了解更多IDC相关研究或进一步与我们沟通,欢迎与 IDC 联系,我们将安排专人与您对接,为您提供定制化的市场洞察与咨询服务。

请点击此处与我们联系。

Sophie Pan

Sophie Pan - Research Director, Client System Research

Sophie Pan is a research director for the Client Systems Research team at IDC China. She is responsible for emerging technology device research, including wearable devices and smart home devices. Sophie has a deep understanding of the landscape and ecosystem…

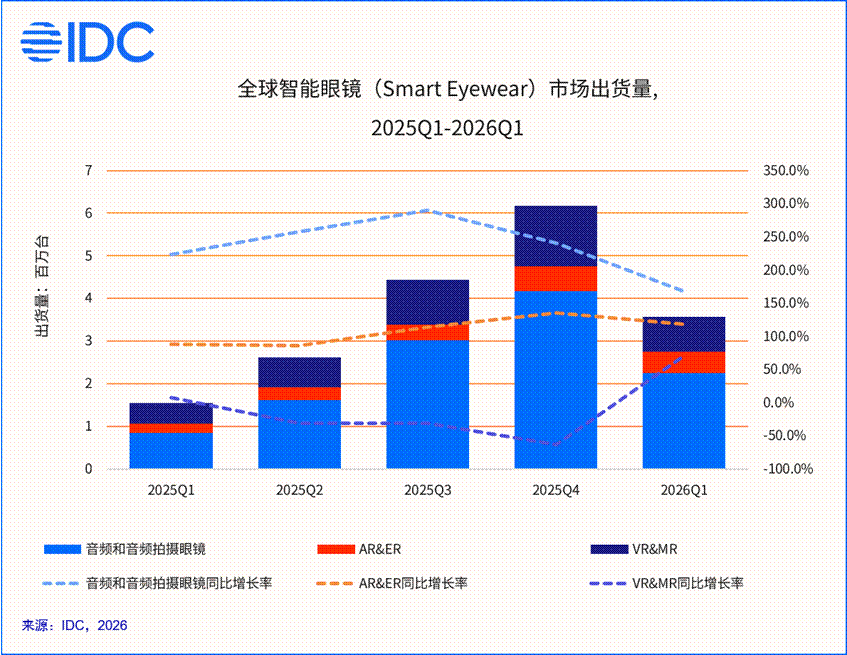
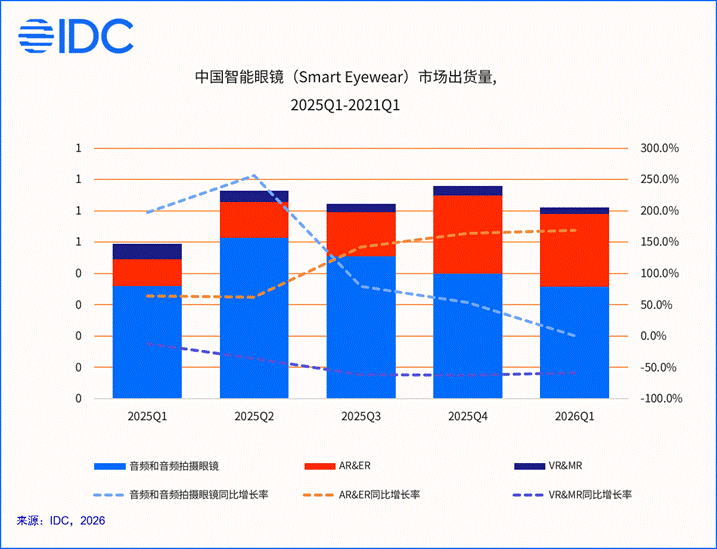
2026年第一季度,全球智能眼镜市场以130.1%的同比增速交出亮眼答卷,中国市场以23.5%的增长位列全球第三。然而,增速背后的结构性剧变更值得关注。国际数据公司(IDC)最新数据显示,中国音频和音频拍摄眼镜市场整体出货量同比下滑0.1%,其中不具备拍摄功能的纯音频眼镜产品需求开始疲软;,而轻量级显示眼镜逐步进入消费视野,带动AR&ER市场同比增长168.6%,成为一季度市场结构变化的重要变量。与此同时,国家补贴首次纳入智能眼镜,叠加AI大模型落地和密集新品发布,正在加速行业从“功能叠加”向“场景增值”演进。

全球市场

IDC最新数据显示,2026年第一季度全球智能眼镜(Smart Eyewear)市场出货量356.6万台,同比增长130.1%。其中全球音频和音频拍摄眼镜市场出货量224.8万台,同比增长167.4%;AR/VR市场出货131.8万台,同比增长85.9%。

全球市场产品动态

1. 国际巨头动向持续定义赛道方向

巨头在智能眼镜领域的布局预期持续发酵,赛道本身的战略价值已获得产业链和资本端的双重验证。

苹果:智能眼镜项目或于2026–2027年进入量产窗口。首代可能采用无屏轻量化设计,分阶段落地规划可为供应链预留爬坡周期,同时通过持续释放预期信号占据市场声量,为后续产品迭代积累用户认知基础。苹果的入局会倒逼供应链成熟、拉升用户认知,但也会在高端市场形成新的竞争压力。

谷歌:谷歌以Android XR平台授权加合作方硬件为主,与XREAL合作的Project Aura、与三星及Gentle Monster等联合开发的音频及显示眼镜均为确认项目。平台方身份规避了自有硬件的库存与品控风险,同时为国产硬件出海提供适配入口。

2. 跨界新玩家入局拓宽行业边界

非传统XR厂商的进入,说明智能眼镜的竞争已从专业赛道扩展至更广泛的消费电子领域。不同背景厂商带来的差异化场景定义有助于激活多元用户群体。

科大讯飞:语音技术切入办公场景,避开定位和手机生态的正面竞争。以垂直场景建立差异化认知,为中小厂商提供单点突破路径参考,其场景深度与商业闭环的验证值得期待。

极米:将自身技术优势进行迁移,探索新形态,品牌认知为产品溢价提供支撑,也为行业注入创新变量,将拓展智能眼镜在影音娱乐场景的价值边界。

3. AI厂商加速布局,推动竞争逻辑升级

未来的竞争将更多依赖软件生态和用户数据积累,而非单纯的产品迭代速度。对行业而言,头部AI厂商的介入将提升终端用户的认知水位,加速市场教育进程。

阿里:千问眼镜上市后份额提升迅速,核心在于打通了千问大模型与电商、支付生态,将硬件作为生态入口。有屏S1与无屏G1双线并行,覆盖不同用户需求,生态闭环的完整性是其区别于竞品的核心优势。

字节:字节产品发布时间尚未明确,但其在内容生态和算法推荐上的积累,使其具备从内容分发端切入市场的潜力。有望激活更多年轻用户群体,为市场带来新的增长变量。

中国市场:

2026年一季度中国智能眼镜市场在全球市场中份额排名第三,一季度出货量61万台,同比增长23.5%。本季度,智能眼镜首次被纳入国家补贴目录,带动渠道备货和终端需求释放,成为市场增量的核心动力。拍摄眼镜、具备AI大模型的眼镜、显示眼镜等细分品类均实现三位数同比增长,行业竞争加速分化,创新节奏明显加快。主流产品在轻量化、AI能力和佩戴体验等方面持续优化,叠加新品密集发布和渠道深度拓展。

中国细分市场概况及市场格局

音频和音频拍摄眼镜市场

2026年一季度,中国音频和音频拍摄眼镜市场结构出现明显升级,总出货量35.8万台,同比下滑0.1%,但其中音频拍摄眼镜占比达到43.4%,同比增长513.1%。

支持AI大模型语音助手的新品上市节奏加快,推动产品创新活跃。市场份额进一步向具备差异化功能和创新能力的品牌集中,TOP5品牌合计市场份额超过50%。小米、阿里、华为、雷鸟等头部厂商持续储备新品,带动行业竞争格局加速分化。从应用角度来看,厂商需要在高频场景中验证产品能否真正降低用户操作成本,这将直接影响用户留存和品牌口碑。

AR/VR市场

2026年一季度,中国AR/VR市场出货量25.2万台,同比增长86.2%。

AR&ER品类保持高速增长,季度市场份额已超过90%,同比增长168.6%。从市场表现来看,显示型眼镜新品的关注度相对高于音频眼镜,尽管轻量级显示眼镜的价格普遍集中在2000-3500元区间,仍处于较高水平,但其核心优势在于用户价值感知的提升。音频眼镜的功能与手机高度重叠,用户较难形成刚性使用习惯,而显示型眼镜能够覆盖手机难以触达的应用场景,带来更直观的体验,因此用户的尝鲜意愿和溢价接受度更高。从产品结构来看,轻量级显示眼镜已成为用户入门显示类产品的首选,为后续向更高端产品的转化奠定基础。

VR&MR市场一季度出货量同比下滑58.8%。整体表现依然低迷,缺乏新的增长动力。苹果Vision Pro M5版本虽然在产品层面有所更新,但产品定价仍处高位,内容生态和佩戴舒适度尚未达到用户预期,导致市场热度与实际转化之间存在明显落差。此外,VR&MR市场企业级采购有一定机会,但体量有限,尚不足以对冲消费端的疲软表现。

未来展望与新机会

IDC中国市场分析师叶青清认为,当前智能眼镜产品普遍面临的问题在于,虽然用户愿意为新鲜感买单,但不会为体验短板持续付费,若无法在体验上形成持续价值,用户留存就会成为瓶颈。因此厂商在产品定义和资源投入上需要做出更务实和偏向性的取舍。

在此基础上,未来还有以下几个方向值得追踪:

第一,新型方案已开始受到行业关注。独立通信、固态电池、体征监测集成等方向已经处于技术验证或小规模试产阶段,为产品定义和场景创新提供了新的可能性,值得持续跟踪。但现阶段真正影响用户留存的仍是连接稳定性、佩戴舒适度等基础体验,厂商在跟进新技术的同时,需要优先把现有成熟方案做到位。

第二,外观设计正成为用户决策的关键变量。轻量化已从加分项变为必选项,时尚性和个性化设计将在下半年成为头部厂商建立品牌辨识度的重要手段。在技术参数趋同的背景下,佩戴体验直接影响购买转化和日常使用频率,设计的差异化正在从产品层面升级为品牌资产。

第三,国内隐私安全标准正在加速落地。随着可穿戴设备采集敏感数据的场景增多,国内相关标准化工作已在推进。厂商需将隐私保护前置到概念设计阶段,合规能力将加速行业洗牌,提前建立技术储备和认证体系的厂商,有望在下一阶段竞争中占据主动。

IDC持续关注全球智能眼镜及可穿戴设备市场的发展动态。我们诚邀行业同仁、投资机构及媒体朋友与IDC中国分析师团队保持沟通,共同探讨市场趋势、技术创新与商业机遇。无论您是希望深入了解数据细节,还是寻求定制化市场洞察,欢迎随时与我们联系。

请点击此处与我们联系。