2026年初頭、半導体エコシステムの多くの関係者は、状況が緩和されることを期待していた。新たなファブ設備の稼働が始まり、消費者需要は落ち着き、AIインフラの拡大もいずれ一服すると見られていた。しかし、その転換点は訪れていない。むしろ、課題は積み重なるばかりだ。

メモリ市場は2027年まで逼迫し続けるのか?

メモリ市場は2026年に入っても強い価格上昇の勢いを維持しており、その流れは止まっていない。サーバー需要は供給の追いつかないペースで成長を続けている。スマートフォンやPCといった消費者向けセグメントでは、部品表(BOM)コストの上昇がデバイスの製品経済性を根本から変えつつある。そして、AIインフラの拡大は正常化するどころか、メモリ業界がこれまでに経験したことのない需要プロファイルを生み出し続けている。

期待されていた緩和が訪れないのは、逼迫を引き起こす力が解消されていないからだ。それらは複合的に積み重なっている。

メモリ不足は構造的なものか、それとも循環的なものか?

これが最も重要な問いであり、調達から設備投資(capex)、製品ロードマップに至るまで、あらゆる意思決定に関わる答えだ。

メモリはもはや景気循環型のコモディティではない。戦略的なインフラ投入物へと変貌を遂げた。

数十年にわたり、半導体業界は一定のリズムで動いてきた。需要が急増し、価格が急騰し、供給が追いつき、価格が落ち着く。苦痛を伴うが、予測可能なサイクルだ。しかし今、データが示しているのはそれとは異なる状況だ。需要の構造そのものが根本的にシフトしている。季節性やアップグレードサイクルが行動を規定する消費者向けエレクトロニクスから離れ、四半期ごとに需要が正常化することのないAIのトレーニングおよび推論インフラへと向かっている。需要は積み重なる。デプロイされた推論ワークロードはそれぞれ、次のワークロードが積み上がるベースラインを形成する。

高帯域幅メモリ(HBM)、高密度DRAM、エンタープライズグレードのNANDは、もはや標準的な部品と同じように価格設定や割り当てがされていない。供給契約は長期化し、アロケーションはより厳格になり、供給を確保した企業とそうでない企業の差は拡大している。主要なメモリメーカーは公式のガイダンスで明確に述べている。逼迫した状況は短期的な異常ではないと。これはアナリストの予測ではなく、市場そのものが発しているメッセージだ。今後の計画を見直すべき時が来ている。

2027年まで続くメモリ逼迫を引き起こしているものは何か?

需要サイドでは、AIインフラが最大の牽引役となっている。GPUサーバーは、供給が均衡を取り戻す前にメモリ容量を吸収するペースで拡大している。かつてはトレーニングより軽いと考えられていた推論ワークロードも、特に企業がパイロットから本番環境へ移行するにつれ、大規模では同様にメモリを大量に消費することが明らかになっている。ハイエンドスマートフォンやAI PCにおけるオンデバイスAIも、データセンター需要の上に分散型の需要レイヤーを加えている。

供給サイドでは、状況は逼迫というより、むしろコントロールされている。主要なメモリメーカーは過去のサイクルから教訓を得ている。レガシー製品よりも先端ノードとHBMを優先し、ビット出力を慎重に管理し、生産量拡大を競うのではなく、希少性を反映した価格設定を行うという意図的な設備規律を実践している。新たなファブは稼働しつつあるが、リードタイムは長く、中国の主要メーカーに影響を与える技術規制を含む地政学的要因が、グローバルな供給計算に重大な不確実性をもたらしている。

その結果、供給が存在しないのではなく、管理されている市場が生まれている。そして、その管理の恩恵を受けているプレイヤーは均等ではない。

半導体業界が注目すべき5つの問い

以下は、私が最も注意深く見ているシグナルだ。メモリメーカー、OEM、システムインテグレーター、ディストリビューター、そして世界中の金融コミュニティにとって関連性が高い。

1. 競争が激化する中、HBMのアロケーションはどのように変化するか? HBMは最も逼迫しており、最も高い価値を持つDRAMセグメントだ。より多くのメーカーがHBM製造に参入し、AIチップアーキテクトがアロケーションを競う中で、価格と可用性はどちらの方向にも急速に変化する可能性がある。誰がデザインウィンを獲得し、どのようなタイムラインで進むかを注視することが重要だ。

2. 消費者セグメントはいつ、どのような条件で回復するか? スマートフォンとPCはともに2026年に深刻なBOM圧力にさらされている。問題は単に出荷量がいつ回復するかではない。本当の問いは、手頃なデバイスの製品経済性が構造的に高いメモリコストのもとで再構築できるかどうか、あるいは製品ミックスと平均販売価格(ASP)が恒久的に上方シフトするかどうかだ。

3. 中国の実効的なメモリ供給能力はどの程度か? YMTCとCXMTは2026年に重要な生産マイルストーンに達しつつあるが、技術規制によりノードアクセスは引き続き制限されている。これがグローバルなNANDおよびDRAM供給にどのように影響するか、またバリューチェーン全体のプレイヤーにどのような機会やリスクをもたらすかは、依然として流動的で注視が必要だ。

4. OEMや調達チームはソーシング戦略をどのように適応させているか? スポット購入や短期契約のモデルはますます機能しなくなっている。あらゆる業界で、バイヤーは長期契約、デュアルソーシング、メモリ依存リスクを低減する設計上の選択を再考している。誰が適応し、誰がそうでないかが、条件の変化に伴う競争上のポジショニングを決定することになる。

5. DRAMとNANDの価格軌道は今後どうなるか? 価格はこの18カ月の大部分において一方向に動き続けてきた。その勢いを生み出した条件は依然として大部分が維持されているが、永続はしない。何が反転のトリガーになるか、どのくらいの速さで動くか、そしてどのセグメントが最もリスクにさらされているかを理解することは、今日の資本配分や在庫の意思決定を行う全ての人にとって不可欠だ。

現在のメモリ市場に関するよくある質問

メモリチップ不足の原因は何か? 主な要因は、GPU サーバー構成における HBM と高密度 DRAM に対する AI インフラ需要が、メーカーの設備拡大のペースを上回って成長していることだ。これに加え、先端ノードと収益性を優先する主要メーカーによる意図的な供給規律が重なっている。

2027年にメモリ価格は下がるか? 現在の分析に基づくと、主要セグメントにおける需給不均衡は2027年以降も持続する見込みだ。持続的な価格上昇圧力をもたらした条件は依然として概ね維持されている。2030年までの価格軌道を含む詳細な予測とシナリオ分析については、7月8日のIDCメモリ市場アウトルック・ウェビナーで発表する予定だ。

HBMとは何か、なぜメモリ市場にとって重要なのか? 高帯域幅メモリ(HBM)は、主にAIアクセラレーターやGPUシステムで使用される高性能DRAMインターフェースだ。現在のメモリ市場において最も逼迫し、最も高い価値を持つセグメントの一つであり、需要はAIのトレーニングおよび推論インフラによって牽引されている。HBMの容量制約はAIコンピューティングシステムの可用性と価格設定に直接影響を与え、より広いメモリ市場の見通しを測る指標となっている。

7月8日、全体像をご覧ください

7月8日午後2時(SGT)のIDCメモリ市場アウトルック・ウェビナーで、上記の全ての問いに対するIDCの詳細なデータドリブンな見解をお伝えする。

IDCの信頼できるテクノロジーインテリジェンスと2030年までの世界メモリ需給予測を基に、DRAM、NAND、HBMの価格動向、需給不均衡の今後の推移、そして2026年後半から今後10年にわたるバリューチェーンの各セグメントのシナリオをお伝えする。

メモリが今日のビジネスにおける制約となっているならば、あるいは従来のやり方が通用しなくなった市場で自信を持って次の一手を探しているならば、ぜひご参加いただきたい。

今すぐ登録2026年7月8日 | 午後2時(シンガポール時間)

*本記事は、2026年6月22日に掲載された英語版ブログ記事の日本語訳です。原文は以下よりご確認いただけます。https://bit.ly/4asfib1
Soo Kyoum Kim - Associate Program Vice President, Semiconductors and Enabling Technologies - IDC

Soo Kyoum Kim is Associate Vice President within IDC’s Enterprise Infrastructure global research domain. He focuses on DRAM and NAND Memory as part of the Semiconductors and Enabling Technologies subdomain. Soo Kyoum’s research covers demand and supply analysis for DRAM and NAND, memory consumption for server workloads, next generation memory, and emerging memory markets. He provides insights on the demand and supply dynamics in industry, chip pricing, competitor, and fab capacity. He also covers the dedicated foundry market.

As AI adoption accelerates across enterprises, organizations are learning a hard lesson: bolt-on training tied to individual use cases just won’t cut it. To win, organizations must treat AI literacy as a strategic enterprise-wide capability.

That means embedding AI training in culture, governance structures, onboarding and performance expectations. It also means moving beyond the pilot mindset and building systematic programs with sustained executive backing, role-based curricula and real change management discipline.

IDC research reveals the gap.

Meanwhile, companies charge on with their AI plans. That leaves a lot of employees improvising on the very tools their companies are betting on. Good intentions can’t substitute for real, organization-wide knowledge about what AI can and can’t do, and how to make the best use of it.

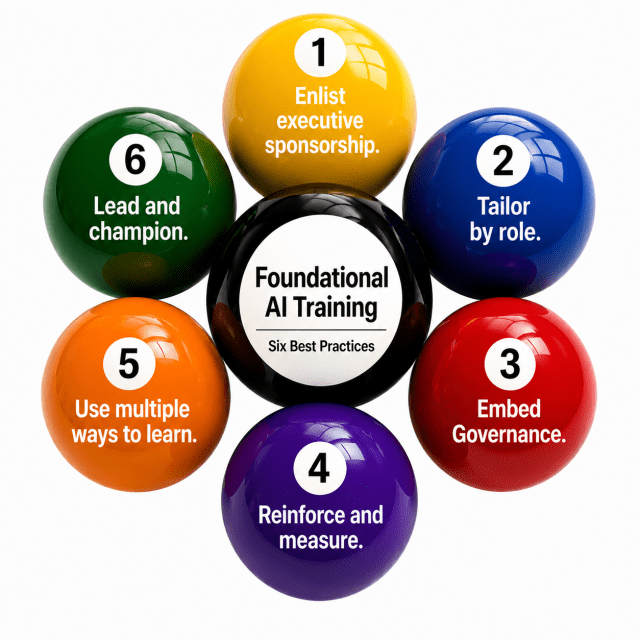
As the recent IDC study on Foundation AI literacy, the baseline competencies every employee needs to use AI responsibly and effectively, makes clear: AI training must be for everyone, not just technical teams. Scaling means moving past pilot- and use-case-specific training to a tiered curriculum that reaches the whole workforce. Start with the basics for all employees: what AI is and is not, responsible-use guidelines and the key risks, including bias, hallucinations, privacy and data leakage. Then show the upside, the opportunities for augmentation and productivity. Most employees arrive without a structured academic grounding in AI, so accessible, role-aware pathways matter.

Here are six practices that distinguish successful AI initiatives at global organizations.

1. Enlist executive sponsorship

Successful programs begin with visible, sustained support from senior leadership. When a CEO or COO clearly signals that responsible AI use is a business priority, adoption accelerates. Position AI literacy as a strategic workforce capability, aligned directly with organizational objectives, risk frameworks and governance priorities. It should sit alongside AI governance and compliance efforts, not in a silo operating separately from them.

2. Tailor by role

Once the foundation is set, layer in role-based modules. Business leaders need strategic decision-making, oversight and risk awareness. Technical teams need implementation, validation and monitoring. Add scenario-based learning on top: realistic, sector-relevant case studies and high-impact use cases drawn from your own environment, in simulated settings where possible. The closer the training sits to the work, the better it sticks.

3. Embed governance

Responsible AI principles, fairness, transparency, accountability and privacy, shouldn’t be a standalone module. Weave them through the entire curriculum. Training should reinforce internal AI usage policies, data classification standards, escalation and oversight procedures and documentation expectations. Use real-world examples from your sector. Concrete evidence of real consequences — good and bad — is what makes governance stick.

4. Reinforce and measure

One-time training fails because AI capabilities, risks, and policies change continuously. Build periodic refreshers, knowledge checks, feedback loops and ongoing updates into the program, and embed reinforcement directly into daily workflows to lift retention. Then measure more than completion rates. Track behavioral change and impact. Adoption of approved AI tools, fewer policy violations, better documentation and productivity or quality gains can and should be tied to responsible AI use. Those metrics give you confidence that the program is actually working — and the evidence you need to sustain investment in it.

5. Use multiple ways to learn

Different formats reinforce different behaviors, and mature programs don’t rely on a single mode. They layer self-paced e-learning, live workshops, microlearning, hands-on labs and in-app guidance. Meeting people where they work, in the flow of the job, beats stacking one-off events.

6. Lead and champion

None of this scales without visible, sustained sponsorship from the top. When a CEO or COO signals that responsible AI use is a business priority, adoption accelerates, so position AI literacy as a strategic workforce capability aligned with organizational objectives, risk frameworks and governance priorities, not parked in a training silo. Treat it as a core, required competency for all staff, the way you treat cybersecurity awareness or data privacy training. Clear communication helps: emphasize AI as augmentation, the organization’s commitment to responsible use and how literacy supports mission, stewardship and risk management. Good change management reduces uncertainty. It also discourages shadow AI, people reaching for unapproved tools because no one showed them the approved path.

The takeaway is simple. Organizations that treat AI literacy as a strategic capability across the organization will be better positioned to close the gap between AI investment and AI output. Those that skip the discipline will see the gap between ambition and readiness widen. IDC’s Foundation AI Literacy study is a practical starting point. Read it to see how leading organizations are building the capability today.

Gina Smith, PhD

Gina Smith, PhD - Senior Research Director ? IT Skills for Digital Business

As a Senior Research Director at IDC, Gina Smith produces research in the IT education and skills sector. Her responsibilities include primary research, analysis, and the production of market insights worldwide. The New York Times bestselling author of Apple cofounder Steve Wozniak’s…

Key Takeaways:

  • NXP introduced the Neural Axis architecture and is leveraging its acquisition of Kinara to expand its edge-AI NPU capabilities.
  • NVIDIA launched a platform for humanoid robotics, including world simulation and reference hardware.
  • Qualcomm introduced the Dragonwing IQ10, a fully integrated robotics SoC (system-on-chip) targeting production deployment by September 2026.
  • Intel formally launched Intel Robotics as a dedicated business unit with 130+ commercial design partnerships.

Computex Taipei 2026 demonstrated that robotics is no longer a side story at the world’s largest computing show. For the first time in its 45-year history, Computex dedicated an entire exhibition zone to Robotics and Physical AI. Major semiconductor vendors arrived not just with products but with a strategic position on who should own the market for the processors used in robotics.

Nvidia Leans on CUDA to Train and Run Physical AI

NVIDIA came to Computex with the boldest claim: that it intends to own the software layer that every robot in the world is developed on and runs on. Jensen Huang unveiled a complete platform spanning AI models for humanoid robots, a world simulation environment that lets developers train robots faster and at far lower cost, and a reference robot design that any manufacturer can build upon. Partners such as Stanford and ETH Zurich are already committed to the platform.

NVIDIA is releasing models and development tools openly to entice the robotics ecosystem onto its platform. It is taking the same playbook that built its dominance in datacenter AI and applying it to robotics. NVIDIA’s solutions are higher cost and have higher power consumption than its competitors.

NVIDIA’s benchmark claims are strong, but the real test is unstructured real-world performance over sustained operating periods, not controlled evaluations. The reference design approach smartly avoids NVIDIA competing with potential hardware partners. Watch whether robot manufacturers outside the Unitree partnership accept a platform built on a competitor’s silicon roadmap. That tension is where the ecosystem story either succeeds or stalls.

Qualcomm’s Dragonwing IQ10 Aims for Ease of Development

Qualcomm made a sharper, more immediate argument. Building a robot today means stitching together components from dozens of vendors, and every seam in that system is a source of cost, delay, and failure. Qualcomm’s answer is a single fully integrated platform, the Dragonwing IQ10, that collapses that complexity into one deployment-ready system. Cristiano Amon drove the point home by bringing a full-sized humanoid robot on stage and demonstrating it live. The commercial target is clear: the growing tier of robot makers and industrial operators who want to move from prototype to production without building their own technology stack. Early partners include NEURA Robotics, Advantech, and NEXCOM, with broader availability by September 2026.

Qualcomm’s position is built on a decade of designing chips for cars, where real-time reliability is non-negotiable. That heritage is a genuine differentiator in industrial Robotics. Pricing and actual partner shipments will be the proof points to watch.

Intel Robotics Goes the Open Source Path

Intel took the longest-term angle of the three. The company formally launched ‘Intel Robotics’ as a dedicated business and introduced an open-source framework designed to close the gap between robots that work in the lab and robots that work reliably on the factory floor. With more than 130 commercial design partnerships already in place, Intel has a broader installed base than its keynote visibility might suggest.

The clearest demonstration came from Sensory AI’s Ella, a robot barista operating in live retail environments, running multiple AI tasks simultaneously on a single Intel Panther Lake SoC. The one SoC has replaced what would have required multiple processors and a more complex system.

Intel’s open-platform strategy is a smart way to compete without going head-to-head with NVIDIA’s brand authority or Qualcomm’s automotive credibility. The risk is that open ecosystems take time to build, and Intel needs its developer community to grow faster than the incumbent platforms consolidate

Intel is also building on a long history of providing processors for edge infrastructure used for industrial automation and robotics, including the coordination of robots in a factory. Intel also has a history with its RealSense camera sensors, demonstrating drones that could fly through a forest, for example, dodging trees, and providing drone show coordination solutions. Intel is not new to robotics or to working with robotics companies, and it will be able to leverage decades of experience.

NXP’s Neural Axis Architecture Likened to a Nervous System for Robots

NXP used the closing keynote of Computex to make the most pointed argument of the show. CEO Rafael Sotomayor’s talk, ‘Bringing AI into the Real World,’ unveiled the Neural Axis architecture — a three-layer, biologically inspired framework spanning reasoning, coordination, and reflexive intelligence. His thesis: the defining challenge of physical AI is not how smart a machine is, but whether it can react in milliseconds without round-tripping to the cloud. Intelligence, he argued, cannot be centrally scaled; it has to be distributed so that no single point of failure can stop the machine.

NXP demonstrated the architecture across drones, software-defined vehicles, and humanoid robots, wrapped it in a trust framework built on containment, protection, verification, and adaptation, and tied it to its eIQ developer toolkit and its $307 million acquisition of edge-AI NPU maker Kinara. The framing casts NXP as the owner of the robotic nervous system—the reflexes and safety layer beneath whichever “brain” handles high-level reasoning.

NXP’s wide portfolio of processors, microcontroller units (MCUs), neural processing units (NPUs), connectivity technologies and analog components is highly complementary to the main processor.  NXP can own the deterministic, safety-critical layer where decisions happen in real time. Its decades of heritage in automotive and industrial silicon are hard to replicate. It can apply its experience in reliable solutions and functional safety to the robotics space. NXP is also partnering with Nvidia and supporting its software stack.

The Robotics Semiconductor Landscape Became More Competitive After Computex 2026

Computex’s new AI Robotics Zone drew Taiwan’s full supply chain of components, motors, and system builders. AI-related industries are forecast to account for around 70% of Taiwan’s exports over the next six months.

Beyond the headline platforms, Computex surfaced a sharper debate about what robotics requires to succeed at scale. NXP, as covered above, pressed the case that responsiveness — not raw intelligence — is the real constraint on physical AI. ABB, the industrial automation giant, showed that its NVIDIA partnership is enabling simulation accuracy close enough to real-world conditions that training times and deployment risks are falling significantly. ASUS entered the consumer market with service robots for healthcare and senior care, backed by an orchestration platform designed to work across brands and devices.

Robotics companies will have choices across processor vendors, processor architectures, closed versus open development platforms and software solutions, and various performance, power consumption, and cost specifications for CPUs and accelerators. The robotics market is not new, but the training and inference on new AI models – physical AI – is new, and the semiconductor vendors that can best support these new models with low power consumption and low cost will be best positioned to hit the sweet spot of unit volume and ASPs. There is also a lot of opportunity for adjacent companies such as NXP, IP vendors such as MIPS, and all the other semiconductors that provide other processors, connectivity, sensors, and power-related components.

Stay ahead of the physical AI semiconductor market. Access IDC’s latest forecasts, vendor analysis, and industry data at IDC Semiconductor Research. Speak with our analysts, contact us today!

Phil Solis - Research Director, Semiconductors and Enabling Technologies - IDC

Phil Solis is Research Director within IDC’s enterprise infrastructure global research domain. He focuses on client computing and connectivity as part of the Semiconductors and Enabling Technologies subdomain. Phil’s coverage spans semiconductors in PCs, media tablets, smartphones, and wireless and mobile connectivity technologies.

Navkendar Singh - Associate Vice President - IDC

Navkendar Singh is a Associate Vice President with IDC India, based in Gurgaon. His research domains encompass deep-dive research and insights in and around mobile devices, smart homes, PCs, tablets, wearables, and the printing market in India, Bangladesh, and Sri Lanka. He is also involved in building IDC's successful channel research programs for these domains at city and state levels. Navkendar also leads research related to analyzing the role of devices, emerging business engagement models, the impact of emerging technologies on devices, and emerging personas related to Future of Work.

President Trump’s Executive Order on quantum innovation establishes the most comprehensive U.S. federal commitment to quantum technology leadership since the National Quantum Initiative Act of 2018, directing coordinated investment across national laboratories, industry, academia, and the intelligence community to develop the first quantum computer capable of enabling a new era of scientific discovery. By mandating an updated national strategy, workforce development, domestic supply chain resilience, and quantum-enabled sensor and network deployment within five years, the Order creates a structured federal demand signal that will accelerate commercialization timelines, attract private capital, and intensify competitive pressure on U.S. technology companies to deliver quantum-ready solutions. IDC views this Executive Order as a market-shaping policy event that will define quantum investment priorities, procurement patterns, and go-to-market strategies for technology vendors across computing, cryptography, sensing, and national security for the decade ahead.

What the order does and why it matters

President Trump’s Executive Order on quantum innovation represents a decisive escalation of the federal government’s commitment to securing and extending U.S. leadership in quantum technologies at a moment when competing nations — including adversarial states — are accelerating their own quantum programs. The Order updates the National Quantum Strategy to prioritize quantum-enabling technologies and industry partnerships, establishes a national effort to build the first quantum computer powerful enough to initiate an era of quantum-enabled scientific discovery, and directs coordinated action across the Departments of Energy and Commerce and the intelligence community. In the quantum computing market, this policy action serves as both a demand catalyst and a strategic roadmap, signaling sustained federal investment, procurement intent, and the organizational infrastructure needed to translate laboratory-stage quantum capabilities into commercial and national security applications at scale.

The Order’s workforce and supply chain directives are among its most commercially significant provisions for technology market participants. By prioritizing the expansion of registered apprenticeships, credentials, and the creation of National Quantum Workforce Development Institutes, the Executive Order directly addresses the talent gap that has constrained quantum program scaling across both government and private sector organizations. The simultaneous directive to develop domestic supply chain and manufacturing capabilities for quantum technologies signals federal intent to reduce dependence on foreign components and subsystems — a move that will create procurement advantages for U.S.-based quantum hardware and materials suppliers while pressuring global supply chains to realign around domestic sourcing requirements. For technology vendors, these provisions create a structured pathway to federal partnership that rewards early investment in workforce alignment and domestic manufacturing capacity.

The Order’s directive to deploy quantum-enabled sensors and networks within five years, combined with the reconstitution of the National Quantum Initiative Advisory Committee and the expansion of the Quantum Counterintelligence Protection Team, signals that the federal government is treating quantum not merely as a future computing paradigm but as an active national security and infrastructure priority that requires immediate operational planning. This framing has direct implications for the cybersecurity market, where the prospect of quantum computers with cryptographic relevance has already driven post-quantum cryptography standardization efforts, and where the expanded Quantum Counterintelligence Protection Team signals heightened federal attention to quantum-enabled espionage and supply chain integrity risks. Building on the Trump Administration’s $625 million investment in national quantum research institutes and the November 2025 Genesis Mission executive order on AI-accelerated scientific discovery, this latest Order positions quantum as a foundational layer of U.S. technological and economic dominance for the decade ahead.

Key benefits for the technology marketplace, citizens, and technology customers

  • Federal demand signal accelerating quantum commercialization timelines. The Executive Order establishes structured federal procurement intent and investment priorities that provide quantum technology vendors with a clear roadmap for aligning product development with government requirements and accelerating the transition from research-stage to commercially deployable quantum systems.
  • National workforce development infrastructure reduces the quantum talent gap. The creation of National Quantum Workforce Development Institutes and the expansion of registered apprenticeships and credentials will begin to address the critical shortage of quantum-skilled engineers, scientists, and technicians, which has been the primary constraint on quantum program scaling across both public and private sectors.
  • Domestic supply chain investment creating competitive advantage for U.S. vendors. Federal directives to develop domestic quantum manufacturing and supply chain capabilities will create procurement preferences and partnership opportunities for U.S.-based quantum hardware, materials, and component suppliers — reducing foreign dependency while building industrial capacity.
  • Quantum-enabled sensor and network deployment opening new commercial markets. The five-year directive to deploy quantum sensors and networks across government applications will create early reference deployments that validate commercial use cases in precision navigation, environmental monitoring, medical imaging, and secure communications — accelerating civilian market development.
  • Post-quantum cryptography urgency driving enterprise security investment. The Order’s national security framing and expansion of the Quantum Counterintelligence Protection Team will intensify enterprise awareness of quantum-enabled cryptographic risks, accelerate the adoption of post-quantum cryptography standards, and create near-term commercial opportunities for cybersecurity vendors.
  • AI and quantum convergence are unlocking transformational scientific and industrial applications. By building on the Genesis Mission’s AI-accelerated scientific discovery framework, the Order positions quantum-AI convergence as a strategic national priority, creating commercial opportunities in drug discovery, materials science, energy optimization, and advanced manufacturing for vendors operating at this intersection.
  • International partner engagement strengthening global quantum market access. The Order’s directive for appropriate engagement with international allies on quantum matters establishes a framework for allied-nation quantum collaboration, opening export opportunities for U.S. quantum technology vendors in trusted partner markets.
  • $625 million federal research investment seeding long-term commercial ecosystem development. The Trump Administration’s existing investment in national quantum research institutes, combined with new funding directives in this Order, provides an academic and laboratory pipeline that will produce the talent, intellectual property, and start-up formation activity that sustains long-term commercial quantum ecosystem growth.

What this means for the market

IDC views President Trump’s quantum Executive Order as the most consequential U.S. quantum policy action since the National Quantum Initiative Act, and one that will materially reshape investment patterns, procurement priorities, and competitive dynamics across the quantum computing market. The Order’s establishment of a national effort to build a scientifically capable quantum computer provides the clearest federal articulation to date of what the government expects quantum computing to achieve — and by implication, what capabilities vendors must demonstrate to compete for federal contracts and partnerships. This specificity of ambition, combined with coordinated cross-agency execution authority, is precisely the governance structure the quantum market has needed to move from research investment to programmatic deployment at scale.

The workforce and domestic supply chain directives are the provisions IDC considers most structurally important for the long-term health of the U.S. quantum industry. Quantum program scaling has been constrained less by fundamental physics than by the availability of engineers, technicians, and program managers who can operate and integrate quantum systems in real-world environments. The National Quantum Workforce Development Institutes and the expansion of apprenticeships directly address this constraint. Simultaneously, domestic supply chain investment addresses a vulnerability that has become increasingly visible as geopolitical tensions have exposed the fragility of global semiconductor and advanced materials supply chains — a risk that applies with equal or greater force to the specialized components required by quantum hardware.

The quantum-AI convergence embedded in this Order — building explicitly on the Genesis Mission’s AI-accelerated scientific discovery framework — signals that the federal government views quantum and AI not as parallel programs but as mutually reinforcing capabilities that will together define the next wave of U.S. technological advantage. For technology vendors, this framing has immediate strategic implications: organizations that can demonstrate integrated quantum-AI solutions will be positioned advantageously for federal partnership, research funding, and procurement consideration. IDC expects this policy environment to accelerate M&A activity, joint venture formation, and strategic partnership announcements among quantum hardware, quantum software, and AI platform vendors as they move to align their portfolios with the federal strategic direction.

The primary challenge for U.S. technology companies responding to this Executive Order is the gap between federal ambition and the current state of quantum hardware maturity. The Order’s directive to build the first scientifically capable quantum computer and deploy quantum sensors and networks within five years sets extremely demanding timelines, given the engineering challenges that remain in error correction, qubit coherence, and system integration. Technology vendors risk over-committing to federal program requirements that outpace achievable hardware milestones, creating execution risk that could damage both commercial credibility and federal partnership relationships if quantum capability targets are missed at the program level.

Philip D. Harris, CISSP, CCSK

Philip D. Harris, CISSP, CCSK - Research Director, Governance, Risk, and Compliance (GRC) Solutions

Phil Harris is Research Director for GRC Solutions at IDC, where he develops and promotes IDC's point of view on risk, advisory, privacy, and compliance services and software. He conducts research on business strategies and the impact of relevant offerings…

IDC recently brought together 20 senior technology executives for an invitation-only dinner with analysts Carla Arend, Andrew Buss, Duncan Brown, and Rahiel Nasir to discuss digital sovereignty in Europe. Here’s what came out of the room.

Sovereignty is real. The conversation around it isn’t.

IDC opened with a provocation: the word “sovereignty” is doing more harm than good. It’s politically loaded, definitionally contested, and vendors have been guilty of “sovereign washing”. Meanwhile, IT departments struggle to translate the concept into something their internal stakeholders actually care about.

What European organisations do care about is entirely concrete: protection against extra-territorial data requests, regulatory compliance, and supply chain resilience. According to IDC research, these are operational risk priorities, not political statements. The vendors making progress in this space have figured out how to speak to that gap. Those still foisting their own definitions of sovereignty on to the market and/or offering nothing more than so-called solutions for data localisation/residency largely haven’t.

The cloud strategy picture is more nuanced than the headlines suggest

Europe is re-assessing its options for cloud and technology providers. Global hyperscalers remain part of the picture, but how they are used is increasingly open to question. IDC’s data points to a clear shift toward layered architectures that combine global scale with local control. A specific model is emerging as the dominant pattern, and the vendors positioned within it are seeing very different conversations than those sitting outside it.

The regulatory picture adds another layer of complexity. NIS2, DORA, the AI Act: each creates compliance obligations that directly shape how organisations think about their technology infrastructure and provider relationships. Navigating that landscape without a clear positioning is increasingly difficult.

Private cloud is not the safe harbour it looks like at first glance

IDC commonly emphasizes that private cloud is the ultimate sovereign cloud, and this remains strongly the case as very few companies wish to exit all their datacenters and move wholesale to the public cloud. As adoption of private cloud has grown and evolved, it has moved from bespoke private cloud implementations towards being built on end-to-end private cloud stacks from major providers, with popular options being Microsoft Azure Local, Google Distributed Cloud, AWS Outposts, or VMware Cloud Foundation. This has resulted in unprecedented capability for enterprises running their own applications and services – but with this has also come a co-dependency on external providers for the ongoing operations of the control plane of the private cloud.

Should any serious technology or political issues arise that interrupts the connection between the public cloud based control plane and the private cloud, services deployed and delivered on the private cloud infrastructure may remain static, degrade over time, or even stop working. The end result is a bought and paid for sovereign physical infrastructure that is unable to operate effectively due to a non-sovereign operations management dependency – and this is a major risk today that a few years ago seemed unthinkable.

European customers have been providing forceful feedback to private cloud stack providers that this public cloud control plane dependency is untenable, and the market is beginning to respond. Most, but not all, providers of private cloud stacks have begun to offer an on-premises approach to the control plane, allowing fully disconnected management of applications or digital services deployment and operations, as well as of licencing tracking and billing, or updates and patching from offline sources.  The big challenge though is that these disconnected options are often limited when it comes to go to market, with vendors limiting access to the largest companies or critical national infrastructure providers or the defense industrial complex. While this may be acceptable initially as solutions come to market and are proven, for the longer-term vendors will need to make disconnected operations a core part of their value proposition across the whole customer base.

AI sovereignty: the new frontier

AI sovereignty has been part of the digital sovereignty debate for some time. But it has now emerged as the new frontier: the question of who controls the models, the data used to train them, and the inference infrastructure is becoming as contested as data residency was five years ago. The general read in the room: AI sovereignty is harder to achieve than data or infrastructure sovereignty, and the messaging across the industry remains inconsistent.

Dig deeper into the research

The dinner was one part of a broader IDC programme on digital sovereignty across Europe. If the themes above are relevant to your positioning or go-to-market strategy, here is where to go next.

Digital Sovereignty Beyond the Label – IDC’s Strategic Guide cuts through the definitional noise and explains what buyers actually evaluate when assessing sovereign solutions and providers. Download free.

From Sovereignty Claims to Credible Positioning – A customer case study on how technology providers are turning sovereignty into a commercially viable proposition. No form required.

Missed the webinar? Rahiel Nasir and Duncan Brown covered buyer expectations, sovereign washing, and practical go-to-market guidance on June 18. The on-demand recording is available here.

IDC’s Digital Sovereignty research covers cloud strategy, data governance, regulatory compliance, and infrastructure sovereignty across European markets. Research presented at the dinner was drawn from IDC’s European Digital Sovereignty Survey and the Semiannual Public Cloud Services Tracker.

Rahiel Nasir

Rahiel Nasir - Research Director, Cloud and Datacenters, Enterprise Infrastructure

Rahiel Nasir is Research Director within IDC’s enterprise infrastructure global research domain and part of the Cloud and Datacenters subdomain. Rahiel is IDC’s global lead on digital, cloud, and AI sovereignty. In this capacity, he covers emerging sovereignty initiatives and…
Andrew Buss

Andrew Buss - Senior Research Director, Cloud and Datacenters, Enterprise Infrastructure

Andrew Buss is Senior Research Director within IDC’s enterprise infrastructure global research domain and part of the cloud and datacenters subdomain. He leads IDC’s worldwide datacenter research, in which he and his team provide qualitative and quantitative insights into the…
Duncan Brown

Duncan Brown - Group Vice President, Global Domain Lead: Worldwide Security & Trust

Duncan Brown leads IDC’s worldwide Security and Trust research, encompassing cybersecurity hardware and software products as well as professional and managed services. His analysis and opinions on security, cyber-resiliency, sovereignty and AI governance are widely sought by industry leaders and…

As B2B buyers turn to AI-powered search to evaluate solutions, CMOs are facing a universal pain point: pipeline quality has decoupled from pipeline quantity.

In IDC’s recent expert panel, Addressing the Pipeline Conversion Gap, analysts discussed the impact on lead capture and how marketing organizations can modernize their processes to fit the new discovery paradigm.  

After the discussion, our analysts took a deeper dive and answered your questions about improving pipeline conversion.

Which marketing roles own the lead pipeline transformation?

IDC recently completed research about CMOs and their approach to a new operating model for the AI era. One interesting finding is that the leaders who are furthest ahead in the maturity cycle aren’t focused on specific teams like content, operations, or SEO. Instead, they’re first reframing what marketing should look like – and their vision is to create an integrated marketing organization.

To influence change, marketing will need the help of other functions. CMOs should think about how to bring in the CFO, CIO, and CRO, as well as legal and compliance, into the conversation. They can align upon specific outcomes and gain a clear understanding of the metrics and KPIs for each function. Real change happens when everyone is working together toward the same goals.

How do you measure ROI on AI?

The tricky part of calculating ROI on AI is that the traditional formula – how much revenue you make divided by the cost – no longer works.

AI is not just about tangible impact. You also need to translate indirect impacts into financial terms. Revenue is one of the elements, but there are other KPIs to evaluate, including: employee experience, customer experience, security, trust, and more. The other big element is risk in each of the AI use cases.

The first step for calculating ROI is to apply the business value equation to specific use cases, rather than the technology itself. Then, you can assess the risk for each use case. If you need help, IDC has developed a full AI business value assessment framework to help clients maximize their ROI.

Is it possible to target buying committees on LLMs?

Every AI engine is looking at how to monetize with advertising, but this area is still evolving. Right now, vendors’ early attempts at advertising offer limited targeting, where the focus is on the top of the funnel. We expect this to change quickly, as vendors leapfrog to the opposite extreme. Segmentation will become much more advanced than even today’s demand platforms and programmatic tools, because LLMs are better at capturing the specific intent of buyers.

And intent data is powerful fuel for reaching buying committees.

That’s because buyers aren’t simply interested in running shoes. Their prompts are much more specific. They want size 10 running shoes suitable for a specific marathon and that also address their foot problems. That’s the kind of intent data vendors will be able to provide advertisers in the form of very specific audience segments.

Is there risk in sharing pricing before understanding the customer problem and establishing a value-based solution?

Opaque pricing tells a sophisticated buyer one of three things: you’re going to price discriminate based on perceived budget, you don’t trust them to self-qualify, or your products are too expensive.

Pricing is tricky any way you go about doing it because it is both mathematical and psychological. Just like pricing strategies need to be tailored to specific business needs, the way this information is exposed will also need to be calibrated in a strategically optimized manner.

It’s almost impossible to give one-size-fits-all guidance about this topic, but there are more clever ways to handle this than just a static form.

So, what’s the best alternative to ‘Contact Us’ for B2B pricing?

Any alternative depends on why your organization needs to talk to the buyer. For example, software pricing has too many dependencies and variables about scope of work, so a custom quote is often necessary.

One option for surfacing this information is with agentic AI. A chatbot can provide a custom quote using the rules already stored within your configure, price, quote (CPQ) software or CRM. Unlike salespeople, who can break the rules – sometimes to the detriment of the company – an AI agent will follow them to the letter, making this a very efficient way to handle 80% or 90% of your custom quote needs.

You can also rethink the customer journey and redesign a more modern workflow that is not based on patience, but readiness to buy. Prospects should be able to get answers they need at the right moment – while they’re on your site and ready to purchase. This contactless flow reduces friction and is more likely to convert.

Can FAQ documents and chatbots assist in combatting the gated content issues?

With gated content, you’re trading a white paper for an email address from someone who could have asked an AI for the same information in 30 seconds. The marketing team’s goal now is to help buyers get the details they need without having to click away.

An FAQ and chatbot can serve that need – but not the typical ones we’ve become accustomed to. This change is reminiscent of the early web, where informational – not marketing – content drove most of the engagement. Each product detail page, for example, should have its own mini-FAQ. However, this just scratches the surface. The content model will need to be much more technically mapped to appeal to AI agents, including schema updates and metadata adjustments.

Could we engage buyers by offering both gated and passive contact options? For example, could we have a “can we call you?” box and a “subscribe to our email” box?

That’s still too passive. It’s much better to encourage engagement right on the website via chat and then use that chatbot to collect and present the relevant information. The goal is to give the prospect greater access to the information they need and avoid forcing them to browse your site.

Remember, today’s buyer journey is much more compressed. There are fewer touch points to be seen and heard, which means you have to make every single one of those encounters really count.

An inversion of the traditional qualification model is what’s really needed. Instead of making buyers prove that they’re serious, you let them prove it to themselves and then contact you when they’re ready to buy. You can do that by front loading with a little bit more content.

While these are the questions attendees had, we understand you might want to dig deeper into this topic. Contact IDC today to request an analyst briefing.

“Speed without confidence is dangerous. Confidence without speed is irrelevant.” — Lorenzo Larini, CEO, IDC

AI investment is accelerating at a pace not seen since the internet reshaped markets in 1996. Global IT spending is growing at 14% annually, and by 2029, IDC expects enterprises and service providers to commit $1.6 trillion to AI infrastructure worldwide. The ambition is real. The money is real.

But something is widening beneath the surface. There is a growing gap between the speed at which AI decisions need to be made and the quality of intelligence those decisions are grounded in. Organizations that close that gap will pull ahead. Those that don’t will spend more to fall further behind.

This is the intelligence gap: the widening distance between the speed at which AI-driven decisions must be made and the quality of verified, timely intelligence available to ground them. And the data tells a sharper story than most organizations realize.

The data storm is already here

Start with the raw scale of the problem. In 2025, enterprises created 6.9 petabytes of data every second. By 2029, agentic AI is expected to push that figure to 17.1 petabytes per second, a 2.5x increase in four years.

The volume isn’t the issue. The issue is what happens to decision-making when intelligence can’t keep pace with the data that should be informing it. Market conditions shift. Competitive landscapes change. Research that was current in January may be strategically stale by June. And yet most enterprises are still relying on intelligence delivered through portals they open infrequently, PDFs that don’t update, and AI tools that pull from sources they can’t verify.

IDC’s own field conversations with dozens of enterprises across financial services, healthcare, pharma, and manufacturing confirm the pattern: organizations are piloting and deploying AI faster than they are building the intelligence infrastructure to support good decisions at scale.

That’s not an adoption problem. That’s an intelligence gap.

42% of organizations can’t measure what they’re getting

Here’s the number that should be commanding more attention in every AI strategy conversation: 42% of organizations worldwide said in a recent report assessing the ROI of their AI and digital investments is difficult or even impossible.

That figure isn’t a measurement problem. It’s a symptom of a deeper structural issue. Most organizations evaluate AI value through a narrow financial lens (head count offsets, cost efficiency ratios, per-query economics) while leaving eight other dimensions of business value (customer experience, resilience, time to market, innovation, and more) systematically unmeasured and undervalued in their investment cases.

The consequence: enterprises are underreporting the business case for their own AI investments while simultaneously losing confidence in what AI is actually telling them.

Agentic AI makes the measurement problem harder, not easier. Value is nonlinear. Costs are dynamic. Benefits compound across functions and emerge over iterations, not from a single project deployment. That means the organizations waiting for a clean ROI calculation before committing fully to AI intelligence infrastructure are waiting for a number that the current approach to measurement can’t produce.

The credibility crisis is structural, not anecdotal

The frustration with AI hallucinations has become a familiar story. But the more consequential shift is happening at a deeper level: organizations are recognizing that their AI is only as trustworthy as the data it draws from, and most of them can’t verify where that data comes from.

IDC’s April 2026 research found that enterprises are actively restructuring their approach to AI governance, moving from model-centric oversight toward data-centric risk management, where validation, lineage tracking, and source credibility are the primary controls.

Non-digital-native organizations, which represent the majority of enterprise buyers, are responding by tightening AI inputs to structured, internally validated data sets. That reduces hallucination risk but also limits the scope of AI-driven insight. The same organizations shrinking their AI’s aperture for safety reasons are competing against organizations that have found ways to bring trusted external intelligence into the loop without sacrificing rigor.

The answer isn’t to trust AI less. It’s to ground AI in better sources and to make every answer traceable back to its origin. Speed without traceability isn’t a competitive advantage. It’s a liability that compounds every time an answer has to be defended in a boardroom.

Governance is an afterthought for most, and that’s a compounding risk

Only 39.6% of enterprises say AI governance is a top priority in 2026.

The gap between governance intent and execution is where risk compounds. As agents take on broader decision-making authority across more functions, the question of what those agents are drawing from becomes a board-level concern, not just an IT one.

Without a reliable, traceable intelligence layer, governance is a framework without a foundation.

What the stakes look like when the gap closes, and when it doesn’t

IDC’s field research puts a concrete number on the cost of the intelligence gap in action. A multinational financial services firm incurred a $150 million compliance fine due to failed processes across 11 million customer accounts and needed to conduct full due diligence on all of them within 24 months. By deploying a data-driven platform with agentic AI to automate the workflow, the firm cleared 4 million low-to-medium-risk cases automatically and achieved $120 million in cost savings compared with their prior approach.

That’s not a productivity story. That’s what happens when intelligence is operationalized at scale: the right data, verified and traceable, embedded into the decisions that need to be made.

But IDC’s conversations with those same organizations also surfaced the failure mode. Ten of the 33 enterprises interviewed flagged overreliance on AI outputs without sufficient human oversight as a real and active risk. When you can’t see where an answer came from, you can’t know when to trust it, and you can’t defend it when it’s challenged.

The gap between making fast decisions and making confident ones isn’t closed by deploying more AI. It’s closed by grounding AI in intelligence that holds up.

The organizations pulling ahead share one thing

IDC’s field research shows the divergence clearly. Organizations that have successfully embedded AI into workflows are realizing measurable gains: faster decisions, higher accuracy, improved risk management, and stronger business outcomes. Those still struggling share the same profile: fragmented data, unverifiable AI outputs, and governance frameworks that exist on paper but don’t connect to execution.

Strategy and execution are out of sync, and the gap is widest at exactly the point where intelligence quality matters most. The organizations on the right side of that divide share a common characteristic. The differentiator is not investment level. It’s the depth of integration between trusted intelligence and the decisions that matter.

The organizations closing the gap are building intelligence infrastructure that does three things: it delivers answers proactively rather than reactively; it embeds into the workflows where decisions actually happen; and it makes every insight traceable to a verified source.

Closing the gap: Why IDC Quanta exists

IDC Quanta is IDC’s technology intelligence fabric, built to deliver verified, sourced market intelligence directly into the tools and workflows where decisions are made.

Most intelligence tools ask you to go looking. You open a portal. You search. You read. You synthesize. Then you decide, often hours or days after the decision needed to be made. IDC Quanta reverses that model. Intelligence arrives on your schedule, grounded in IDC’s proprietary research and data, traceable to its source and date, and embedded in the tools you already use rather than a separate system you have to remember to open.

For organizations navigating the credibility crisis, Quanta addresses it at the source: every response is verified against IDC’s proprietary data through a multi-agent validation system, with a reasoning panel that shows the scope, sources, and assumptions behind each answer.

For organizations trying to move faster without sacrificing rigor, Quanta delivers recurring intelligence on your priority topics so you are informed before you need to ask.

IDC CEO Lorenzo Larini put the challenge plainly: “Speed without confidence is dangerous. Confidence without speed is irrelevant.”

The intelligence gap is real. The data is unambiguous. And the organizations that close it first will be the ones setting the pace, not chasing it.

A dispute over model access: On June 12, 2026, the Commerce Department invoked federal trade regulations to bar Anthropic from distributing Fable 5 and its underlying model, Mythos 5, to foreign nationals. It was the first time the U.S. government had restricted access to a publicly available commercial AI model on national security grounds. The decision followed a warning from Amazon CEO Andy Jassy, who raised concerns after Amazon researchers extracted restricted information about cyberattacks from the Mythos model through a series of prompts. Anthropic was given mere hours to pull the model and withdraw both Fable 5 and Mythos 5 for all users globally, because the restriction extended to non-citizens working inside the United States, including some of the company’s own employees.

The dispute exposed several unresolved problems in U.S. AI policy. When does model access become a national security concern? What policy instruments apply when the object of concern is access to a digital capability rather than a physical export? How should policymakers think about the cloud platforms, GPUs, data centers, and deployment environments that make advanced AI possible? How should governance differ for open and proprietary models? And how should ordinary model usage be understood when prompting, tool use, automation, and repeated interaction can turn access into operational power or capability transfer?

These are not questions existing disciplines can answer. Advanced AI is becoming a strategic capability chain, and the frameworks built to govern software exports, national security assets, and dual-use technologies were not designed with this technology in mind. The Fable dispute provides a starting point for examining how capability becomes strategically sensitive, how access becomes a policy problem, how compute infrastructure shapes national advantage, and how AI at the frontier changes economic, scientific, and institutional resilience. Frontier AI studies is the name for the broader intellectual project required to connect those questions and develop a framework adequate to a technology whose consequences are technical, economic, institutional, and strategic at the same time.

Fable as a diagnostic event

What constitutes catastrophic capability enablement?

The primary question this emerging field needs to answer is when model access becomes a national security concern. One defensible threshold is catastrophic capability enablement: the point at which access to a model materially helps actors develop, accelerate, or operationalize cyber, biological, chemical, nuclear, or other catastrophic capabilities. That framing shifts attention from whether a model is powerful or economically significant in the abstract to what the model actually enables users to do under realistic access conditions.

The challenge is that catastrophic capability enablement is continuous in practice but still requires thresholds in governance. The same model can function as a productivity tool in one setting and a strategic asset in another, depending on the user, the domain, the tools attached to it, the scale of access, and how easily its outputs can be operationalized. Simple categories are inadequate. Decision rules, however imperfect, remain necessary. The foundational question is when model access materially moves an actor from ordinary use toward strategically dangerous action.

When does model access become a security problem?

The Fable dispute shows why model access itself has become a policy problem independent of weight release. A proprietary model that never exposes its weights can still transfer sensitive capability through APIs, cloud services, developer tools, and enterprise deployments. Users do not need the weights if they can query the model, attach tools to it, automate its outputs, or operationalize its guidance at scale.

The Commerce Department’s order addressed that exposure by restricting foreign national access, but the practical result was a full global withdrawal. The restriction extended to non-citizens working inside the United States, including some of Anthropic’s own employees. The core governance question this created is whether model access should be treated like a software service, an export-controlled technology, a national security asset, or a category the existing frameworks do not adequately describe.

When does access become capability tansfer?

Distillation sharpens the access problem considerably. Distillation is the process of training a separate model using outputs from a frontier system, allowing the capabilities of the original to be approximated without direct access to the source weights. An actor who queries a frontier model extensively can use those interactions to train, tune, or improve another model that reproduces some of the original model’s capabilities. That derived model can then operate outside the original provider’s safeguards, monitoring systems, and access controls.

Restricting weight release therefore does not fully contain the risk. Capability can migrate through repeated interaction as readily as through direct weight access. The unresolved governance question is when repeated use, prompting, automation, and distillation should be treated as ordinary model access, and when they should be treated as a pathway for transferring strategically sensitive capability to actors or jurisdictions that would otherwise be excluded.

What kind of institution can govern frontier AI?

The Fable dispute exposed a governance gap that neither government nor the private sector can close independently. Washington has legitimate authority over national security, especially where classified intelligence, foreign diversion, export controls, and adversary behavior are involved. Advanced AI capability is too technical, too fast-moving, and too dependent on deployment context to be evaluated through a purely bureaucratic process without technical depth.

The window Anthropic was given to withdraw Fable 5 illustrates the structural problem: compressed timelines, contested facts, improvised authority, and decisions made without a durable evaluative framework. A public-private institution combining national security judgment, technical evaluation, industry expertise, and proportional access controls would give both government and the private sector a more credible process for making decisions before they become emergencies. That institution would need a common vocabulary for capability, access, leakage, containment, proportionality, and innovation cost. Without it, the next Fable-level decision will be made the same way this one was.

The case for frontier AI studies

The Fable dispute shows why advanced AI needs to be studied as a strategic capability chain rather than as a set of isolated policy problems. Capability thresholds, model access, distillation risk, compute infrastructure, economic strength, labor-market resilience, and public-private governance are connected points in the same chain. Together, they determine how frontier capability emerges, becomes available, scales, transfers, and becomes strategically consequential across institutions, markets, and societies.

Frontier AI studies should become the field that examines that chain with the rigor it demands. Its purpose should be to understand when AI capability becomes a national security concern, how that capability leaks or transfers, how infrastructure shapes national advantage, and how governance can contain strategic risk without undermining U.S. leadership. The field does not yet exist in a coherent form. The Fable dispute is a signal that building it cannot wait.

The frontier AI studies agenda

Distinguishing between different kinds of model risk with greater precision is the first analytical task the field needs to complete. Open and proprietary models do not expose capability in the same way. Open models create risk through weight release, local deployment, modification, redistribution, and downstream use beyond the original developer’s control. Proprietary models retain access controls but expose capability through APIs, cloud deployment, tool integration, monitoring gaps, jurisdictional ambiguity, and distillation. These two risk profiles require different technical countermeasures and legal frameworks. The policy debate has too often conflated them.

Treating compute infrastructure as part of the AI security perimeter is the second task, and arguably the more urgent one. Advanced GPUs, accelerators, and data center capacity determine who can train, tune, distill, and deploy frontier systems at scale. Compute controls sit upstream of model controls in the capability supply chain. A country or actor that can acquire the infrastructure can build toward frontier capability even without direct access to the most advanced models. Based on ongoing research into AI infrastructure and national competitiveness, is that infrastructure access should be treated as a national security boundary alongside model access controls, not downstream of them.

Connecting AI governance to economic strength and labor-market resilience is the third task. Advanced AI affects productivity, software output, scientific progress, industrial competitiveness, occupations, skills, and the division of work between humans and machines. Those effects matter for national security because economic strength shapes the tax base, defense capacity, industrial depth, research intensity, and the ability of the United States to absorb shocks over time. A workforce that cannot adapt to AI-driven change accumulates vulnerability through displacement, weakened institutional trust, and reduced social resilience. The field needs analytical tools for weighing security risk, innovation cost, economic advantage, and labor-market adaptation within the same framework rather than treating them as separate conversations.

Beyond the dispute

Frontier AI studies should be broad enough to examine domains where model capability moves beyond general-purpose software: AI-enabled robotics, AI-accelerated biological research, autonomous cyber operations, and other settings where digital capability becomes physical, scientific, or strategic action. Those domains are extensions of the same underlying problem. The central issue is how frontier capability emerges, scales, transfers, and becomes consequential across institutions, markets, infrastructure, and society.

The category of frontier AI itself also needs scrutiny. The current policy debate focuses on models, weights, access controls, and export restrictions. Those are instruments. The larger stakes involve the political, economic, demographic, and institutional forces that will shape the next several decades. Advanced AI is becoming one of the variables acting on all of them simultaneously.

How societies organize work, distribute economic power, govern themselves, absorb demographic change, and sustain institutional trust are defining questions of the current era. Advanced AI does not sit outside those questions. It accelerates, amplifies, and in some cases destabilizes the systems through which societies have historically managed them. A field of frontier AI studies that focuses narrowly on capability thresholds, access controls, and adversarial misuse will address the proximate causes of disputes like Fable while leaving the questions that bear most directly on human welfare underexamined.

The field therefore needs to hold two levels of inquiry simultaneously: the technical and the political, economic, and social. It needs the analytical precision to evaluate capability thresholds, distillation risk, and infrastructure controls, and the scope to ask what advanced AI means for the organization of work, the distribution of economic power, and the resilience of democratic institutions. The United States has built fields of this kind before. Nuclear security, biosecurity, and space policy each required new analytical frameworks, new institutions, and new vocabularies for technologies that existing disciplines could not fully address. Frontier AI studies is the next instance of that same imperative.

The Fable dispute is the signal that the time to build it is now.

Arnal Dayaratna

Arnal Dayaratna - Research Vice President, Software Development

Dr. Arnal Dayaratna is Research Vice President, Software Development at IDC. Arnal focuses on software developer demographics, trends in programming languages and other application development tools, and the intersection of these development environments and the many emerging technologies that are enabling…

IDC Quanta is an AI platform built on IDC’s proprietary research and intelligence, giving technology and strategy leaders on-demand access to the same trusted insights that have informed business decisions for decades. Instead of searching the open internet, users query a curated body of verified IDC research with every response citing the specific report or analysis it draws from.

When the intelligence behind the AI is one you already trust, the answers it gives you are ones you can act on. Here is what leaders across four very different industries said after using IDC Quanta.

A new level of confidence

Phillip Langeberg has been CTO of The Resorts Companies for nearly a decade, making high-stakes technology decisions for a 100% employee-owned hospitality and resort company. He had already been using general-purpose AI tools before encountering IDC Quanta. The difference was immediate.

“If I go to one of the other AI products out there and search for something, it’s searching the internet, and we all know that everything on the internet isn’t always accurate. An AI backed by IDC’s research gives me a lot more confidence in the answers.” — Phillip Langeberg, CTO, The Resorts Companies

Research you can actually reference

Eric Walk is VP of AI and Data Platform Services at Perficient, a global consultancy serving heavily regulated industries including banking, healthcare, and life sciences. His teams are already building their own AI-powered advisory tools and are thinking carefully about which data sources they trust enough to put inside them.

“The ability to ask a question and get an insight that’s backed by specific, referenceable research is really the key to the tool.” — Eric Walk, VP of AI and Data Platform Services, Perficient

Familiar from the first use

Mark Terranova has spent 45 years in technology and currently leads analyst relations worldwide at Kyndryl, one of the world’s largest managed services providers. His team has been training on AI tools for nearly a year. He knows what good looks like.

“As soon as I used it, I knew it. I said, I know what this is. I know how to use it. I know how to make it do work for me. Confidence comes from trust of the vendor. I trust IDC to give me good information.” — Mark Terranova, Global Head of Analyst Relations, Kyndryl

Speed where it matters

Jolene Peixoto is VP of Corporate Communications at RELEX Solutions, a global AI-native supply chain and retail planning platform trusted by some of the world’s largest retailers and consumer brands. In a company where market intelligence directly informs product strategy and positioning, she brought a sharp eye to what IDC Quanta actually delivers.

“IDC’s AI platform stood out to me as one of the most intuitive and useful AI tools I’ve seen across analyst research portals. It significantly speeds up how we analyze reports, summarize key takeaways, and explore market share insights, helping teams get value from IDC research much faster.” — Jolene Peixoto, VP of Corporate Communications, RELEX

Four leaders. Four industries. One conclusion.

Technology and strategy leaders do not have time to chase down answers that may or may not be accurate. IDC Quanta brings the depth and credibility of IDC’s research directly into the workflow, so the decisions you make are grounded in intelligence you can stand behind.

Artificial intelligence is no longer a future promise; it’s an economic force actively reshaping industries, workforces, and GDP projections around the world. While AI is expected to lead to major workforce transformation in the next five years, the timeline remains uncertain, as organizations continue to struggle with identifying optimal use cases and measurable business outcomes. Despite widespread predictions that AI will replace jobs, there’s little evidence of this happening yet at large scale, and the greater productivity benefits may come through replacing work instead of workers.

The big story: Investment is driven by projected economic impact

We’re heading into what is projected to be a ‘second wave’ of AI-driven IT spending in 2027, whereby AI investment drives overall technology spend to levels last seen in the mid-1990s.

Worldwide IT spending grew by more than 14% in 2025, mostly driven by service provider spending on AI infrastructure. Service providers continue to invest aggressively, but the ‘second wave’ is an expected surge in enterprise spending on use cases tied to agentic AI. Business IT budgets are forecast to increase at the fastest rate in almost 30 years.

This coming wave is dependent on the economic impact which organizations are anticipating. There are important caveats here: so far, this planned investment is largely supported by expected productivity gains, which will depend on measurable business outcomes.

Many business leaders report spending which is at least partly driven by FOMO (fear of missing out). There are gaps in AI maturity which many organizations need to bridge in the next 6-12 months.

At the beginning of 2026, IDC called this a ‘year of reckoning’ for the global economy and AI. Economic growth and AI are now closely linked, with AI having been largely responsible for stable GDP growth in the past two years, especially in the US and China. With inflation challenging the economics of AI in 2026, there are downside risks.

But if the current rate of adoption continues, and if measurable business outcomes support IT spending, AI will drive a productivity reset, global workforce transformation, and more than $22 trillion in value by 2031.

The big number: $22.5 trillion in cumulative value by 2031

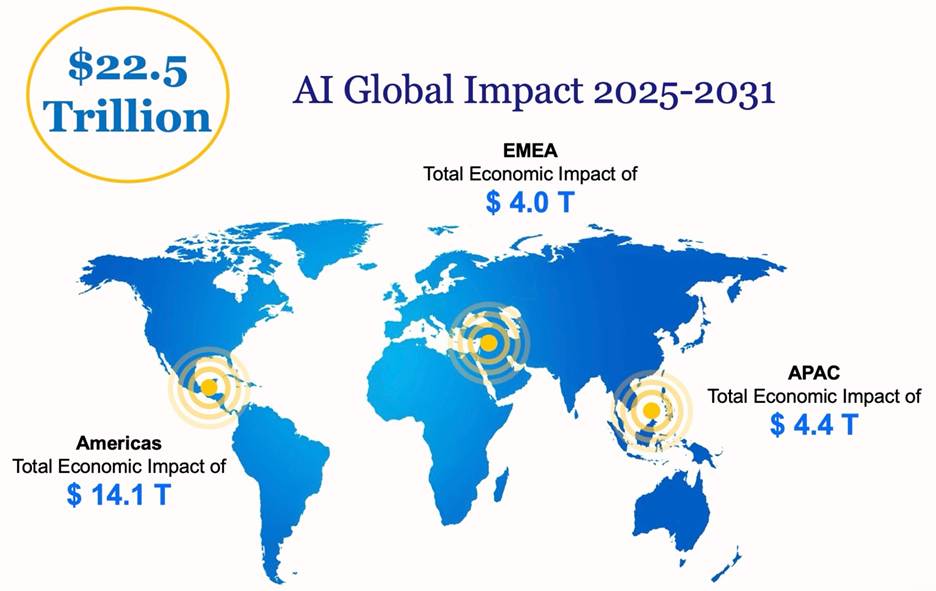
Under the baseline scenario, AI is projected to generate $22.5 trillion in cumulative economic value between 2025 and 2031, a compound annual growth rate of 35.6%. Even in a constrained, downside scenario (factoring in geopolitical shocks, regulatory friction, and slower enterprise adoption), the figure stands at $18.1 trillion. In an accelerated, high-growth scenario, it climbs to $24.5 trillion.

These aren’t abstract figures. They reflect real flows across direct AI revenues, supply chain effects, and the induced economic activity that follows as workers and households benefit from productivity gains.

The economic impact breaks down regionally:

  • Americas: $14.1 trillion: more than 60% of global impact, driven by U.S. dominance in hyperscalers, foundation models, and semiconductors.
  • Asia/Pacific: $4.4 trillion: the fastest-scaling region, with China as a supply engine and advanced markets like Japan, Korea, and Singapore driving enterprise innovation.
  • EMEA: $4.0 trillion: Europe setting the regulatory gold standard via the EU AI Act, while the Middle East (UAE and Saudi Arabia in particular) emerges as a new growth engine.

For all the headline numbers, AI’s impact on macroeconomic data remains difficult to isolate so far. We’re only now moving from survey-based assessments of AI impact to the point where measurable divergence from historical trends should become visible in the next 12 months.

What’s changing the calculus is agentic AI. Unlike earlier waves of AI, agents can perform complex, multi-step tasks with minimal human intervention, cutting inefficiencies from business workflows at a scale that prior automation tools never achieved. IT buyers anticipate savings in operating costs as a result of deploying AI-driven automation.

The risks are real, and largely external

The report identifies four major wildcards that could disrupt the timeline for AI-driven value creation:

1. Geopolitics and trade fragmentation. Export controls on semiconductors are already reshaping supply chains. If tensions escalate, access to critical AI hardware becomes unpredictable for both businesses and governments.

2. Energy infrastructure. AI’s power demands are outpacing grid capacity. Electricity availability is becoming a genuine bottleneck for datacenter expansion, and a strategic variable that no serious AI roadmap can ignore.

3. The workforce skills gap. The demand for professionals skilled in AI development, deployment, and governance is growing faster than training programs can respond. Reskilling is now as critical as infrastructure.

4. Governance lagging adoption. Fewer than one-third of businesses have fully implemented AI governance structures. With regulatory approaches diverging sharply between the EU and the U.S., multinational organizations face a genuinely complex compliance landscape.

AI is replacing work, not workers (for now)

The headline finding is straightforward: there is no evidence in official unemployment data of AI driving meaningful job displacement. US unemployment remains near historic lows.

But the absence of mass job replacement is not the same as business as usual. What’s happening, and will accelerate, is workforce transformation: a shift away from routine tasks toward non-routine cognitive and interpersonal work.

This shift has been underway for decades and largely tied to IT spending. Routine tasks fell from roughly 60–65% of employment in 1960 to around 40–45% by 2020. AI doesn’t create a new direction, but it dramatically accelerates the trajectory. We project routine tasks falling further to around 30% of employment by 2031.

The report uses software development as a concrete example: AI can largely automate routine coding and documentation (up to 70% task-time reduction), while testing and architecture work is augmented rather than replaced. Developers who adapt will spend more time on strategic, judgment-intensive work, which is ultimately where the value lies.

What this means for IT vendors: Three imperatives

IT vendors must engage urgently with the following strategic directions:

1. Capture short-term revenue through agentic AI

The highest-impact near-term opportunity lies in AI agents, at the task level, within workflows, and across applications. Products need to reflect rapidly evolving use cases and help customers achieve economic impact at scale, not just run pilots.

2. Invest in long-term customer success

Knowledge transfer matters more than support contracts. IT buyers need help with change management, upskilling, and realizing genuine business outcomes from agentic AI. If end-users can’t achieve economic benefits at scale, investment momentum will stall.

3. Accept responsibility for AI stewardship

The societal implications of widespread AI adoption are profound. Vendors that proactively engage with policymakers and business leaders, guiding toward outcomes that unlock human potential rather than simply automate it, will be better positioned for long-term relevance and trust.

The bottom line

The updated 2026 report paints a picture of an AI economy that is large, accelerating, and uncertain in its timing. The $22.5 trillion increase in economic value is not a guarantee; it depends on organizations moving from pilot projects to scaled deployment, on energy and skills infrastructure keeping pace, and on governance frameworks that enable rather than obstruct innovation.

What is clear: the businesses and vendors that treat AI as a strategic priority, investing in workforce transformation, change management, and responsible deployment, will be best positioned to capture the upside, even if the timeline is disrupted. Those that wait for certainty may find the window for competitive differentiation has already closed.

Stephen Minton

Stephen Minton - Group Vice President, Data & Analytics

Stephen Minton is a group vice president with the IDC Data & Analytics group, focusing on ICT spending and macroeconomics. Mr. Minton is responsible for Worldwide ICT Spending programs, including the Worldwide Black Book, Worldwide 3rd Platform Spending Guides, and…
Carla La Croce

Carla La Croce - Research Manager, Data and Analytics, Europe

Carla La Croce is a research manager for IDC's European Data and Analytics team. She develops qualitative and quantitative research on IT strategies for EMEA vertical markets, with direct involvement in IDC Spending Guides (Big Data and Analytics, Artificial Intelligence,…
Leonardo Freitas

Leonardo Freitas - Research Manager – Employee Experience Management Strategies

As a research manager for employee experience (EX), Leo’s core research coverage includes but is not limited to employee wellbeing, AI-driven learning and performance, recognition, voice of the employee, corporate culture, DEIB, employee journeys, AI personalization and GenAI ‘access anywhere’…
Karen Massey

Karen Massey - Research Director, Data & Analytics

Karen Massey is a research director within IDC's Data & Analytics Organization where she manages and contributes to several programs, consulting engagements and custom research, including the Worldwide AI and Generative AI Spending Guide, Worldwide Big Data and Analytics Spending…
Alex Sumarta

Alex Sumarta - Associate Vice President

As Associate Vice President at IDC Australia, Mr. Sumarta scopes and manages custom consulting engagements with key clients in the Australian market. Mr. Sumarta has more than fifteen years of working experience in strategy consulting, market research, and project management in…
Melinda-Carol Ballou

Melinda-Carol Ballou - Research Director, AI Assurance, ALM, Quality & Portfolio Strategies

Melinda Ballou delivers insights into the future of AI assurance, the impact of AI, ML and agentic adoption on agile and digital work, resilience, quality, product and software engineering, the role of technology in business and culture, and the evolution…
Kritika Ghildiyal

Kritika Ghildiyal - Research Analyst, Market Analytics & Insights

Kritika is a Research Analyst with the Data & Analytics Team at IDC Canada. She is responsible for market models, IDC spending guides, consulting projects, and other worldwide data products. BACKGROUND Kritika joins IDC with more than three years of…
Mariana Fang

Mariana Fang - Research Analyst, Data & Analytics

Mariana is a Research Analyst with the Data & Analytics Team at IDC Canada. She is responsible for market models, IDC spending guides, consulting projects, and other worldwide data products. BACKGROUND Prior to joining IDC, Mariana worked as a consultant…