At the start of 2026, many in the semiconductor ecosystem were expecting some breathing room. New fab capacity was coming online. Consumer demand had softened. The AI infrastructure build-out, the thinking went, would eventually plateau. That reset hasn’t arrived. If anything, the pressure points have multiplied.

Why will the memory market be tight through 2027?

The memory market entered 2026 riding strong pricing momentum, and it has not let up. Server demand continues to grow faster than supply can respond. Consumer segments like smartphones and PCs are contending with bill-of-materials costs that are rewriting device economics. And the AI infrastructure build-out, far from normalizing, is generating a demand profile that behaves differently from anything the memory industry has navigated before.

The anticipated relief will not arrive because the forces driving tightness will be compounding.

Is the memory shortage structural or cyclical?

This is the critical question, and the answer matters for every decision the industry makes, from procurement to capex to product roadmap.

Memory is no longer a cyclical commodity. It has become a strategic infrastructure input.

For decades, the semiconductor industry ran on a recognizable rhythm: demand surges, prices spike, supply catches up, prices correct. Painful, but predictable. What the data is showing now is different— a fundamental shift in demand architecture, away from consumer electronics, where seasonality and upgrade cycles govern behavior, and toward AI training and inference infrastructure, where demand doesn’t normalize between quarters. It compounds. Every inference workload deployed creates a baseline the next workload builds on.

High-bandwidth memory (HBM), high-density DRAM, and enterprise-grade NAND are no longer priced or allocated the way standard components were. Supply agreements are longer, allocation is tighter, and the gap between players who have locked supply and those who haven’t is widening. Major memory producers have been explicit in their public guidance: tight conditions are not a short-term anomaly. That’s not analyst projection. It’s the market telling you what to plan for.

What is driving continued memory tightness through 2027?

On the demand side, AI infrastructure is doing most of the work. GPU servers are expanding at a pace that absorbs memory capacity before supply can rebalance. Inference workloads, once considered lighter than training, are proving just as memory-intensive at scale, particularly as enterprises move from pilots to production. On-device AI in premium smartphones and AI PCs is adding a distributed demand layer on top of the data center story.

On the supply side, the picture is more controlled than constrained. Major memory manufacturers have internalized the lessons of previous cycles. They are exercising deliberate capacity discipline, prioritizing advanced nodes and HBM over legacy products, managing bit output carefully, and letting pricing reflect scarcity rather than racing to fill every wafer. New fabs are coming online, but lead times are long, and geopolitical factors, including technology restrictions affecting key Chinese producers, add meaningful uncertainty to the global supply calculus.

The result is a market where supply is not absent. It is being managed. And the beneficiaries of that management are not evenly distributed.

Five questions the semiconductor industry should be tracking

These are the signals I’m watching most closely, relevant to memory makers, OEMs, system integrators, distributors, and the financial community worldwide.

1. How will HBM allocation evolve as competition intensifies? HBM is the most constrained and highest-value DRAM segment. As more producers enter HBM manufacturing and AI chip architects compete for allocation, pricing and availability could shift quickly, in either direction. Watching who wins design wins and on what timeline matters.

2. When does the consumer segment recover, and on what terms? Smartphones and PCs are both under severe BOM pressure in 2026. The question isn’t just when volumes recover. The real question is whether the product economics of affordable devices can be rebuilt around structurally higher memory costs, or whether product mix and ASPs shift permanently upward.

3. What is China’s effective memory supply capacity? YMTC and CXMT are reaching significant production milestones in 2026, but technology restrictions will continue to limit node access. How this plays out in global NAND and DRAM supply, and where it creates openings or risks for players across the value chain, remains fluid and worth monitoring closely.

4. How are OEMs and procurement teams adapting sourcing strategies? The spot-buying, short-contract model is increasingly unworkable. Across industries, buyers are rethinking long-term agreements, dual-sourcing, and design choices to reduce memory dependency risk. Who has adapted, and who hasn’t, will determine competitive positioning as conditions evolve.

5. Where does the DRAM and NAND pricing trajectory go from here? Pricing has trended in one direction for much of the past 18 months. The conditions that produced that momentum are largely still in place, but they won’t hold indefinitely. Understanding what triggers a reversal, how quickly it moves, and which segments are most exposed is essential for anyone making capital allocation or inventory decisions today.

Frequently asked questions about the current memory market

What is causing the memory chip shortage? The primary driver is AI infrastructure demand, particularly for HBM and high-density DRAM in GPU server configurations, growing faster than manufacturers are expanding capacity. This is compounded by deliberate supply discipline among major producers, who are prioritizing advanced nodes and profitability over volume growth.

Will memory prices come down in 2027? Based on current analysis, the supply-demand imbalance expected to persist beyond 2027 in key segments. The conditions that produced sustained pricing pressure remain largely in place. I’ll be presenting the full forecast and scenario analysis, including pricing trajectories through 2030 at IDC’s Memory Market Outlook webinar on July 8.

What is HBM and why does it matter for the memory market? High-bandwidth memory (HBM) is a high-performance DRAM interface used primarily in AI accelerators and GPU systems. It is among the tightest and highest-value segments of the memory market today, with demand driven by AI training and inference infrastructure. HBM capacity constraints directly affect the availability and pricing of AI compute systems globally, making it a bellweather for the broader memory market outlook.

Join me on July 8 for the full picture

Learn about IDC’s detailed, data-driven view on all of the questions above at the IDC Memory Market Outlook webinar on July 8, 2:00 PM SGT.

Drawing on IDC’s trusted tech intelligence and worldwide memory demand and supply forecasts through 2030, I’ll cover where DRAM, NAND, and HBM pricing is headed, how the supply-demand imbalance is expected to evolve, and what the scenarios look like for every segment of the value chain, from the rest of 2026 through the end of the decade.

If memory is a constraint in your business today, or if you need to navigate your next move with confidence in a market where the old playbook no longer applies, I hope to see you there. Register today!
Soo Kyoum Kim - Associate Program Vice President, Semiconductors and Enabling Technologies - IDC

Soo Kyoum Kim is Associate Vice President within IDC’s Enterprise Infrastructure global research domain. He focuses on DRAM and NAND Memory as part of the Semiconductors and Enabling Technologies subdomain. Soo Kyoum’s research covers demand and supply analysis for DRAM and NAND, memory consumption for server workloads, next generation memory, and emerging memory markets. He provides insights on the demand and supply dynamics in industry, chip pricing, competitor, and fab capacity. He also covers the dedicated foundry market.

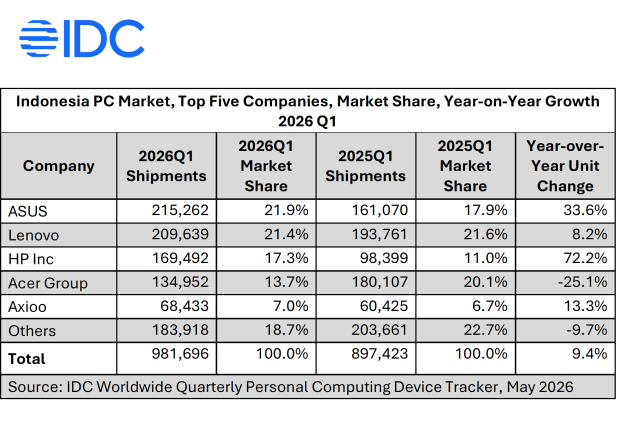
Indonesia’s PC market (encompassing desktops, notebooks, and workstations) shipped 982,000 units in Q1 2026, up 9.4% year over year, exceeding expectations despite rising component costs and tightening supply, according to IDC’s Worldwide Quarterly Personal Computing Device Tracker.[MD1]  The growth was driven by frontloading across both consumer and commercial channels, as distributors rushed to secure inventory ahead of anticipated price increases.

What’s Driving Indonesia PC Market Growth?

Rising device prices prompted end-users and channels to accelerate purchases in Q1, ahead of expected further increases. Channels moved quickly to build inventory buffers as macroeconomic uncertainty made near-term pricing unpredictable.

This frontloading is a double-edged result. It inflated Q1 figures while simultaneously pulling demand forward, leaving less runway for the remainder of 2026.

The acceleration in Q1 comes at a cost to 2H 2026. While budget-flexible organizations moved purchases forward, others have begun reducing expenditure, a trend IDC expects to intensify, contributing to sharp shipment declines in Q3 and Q4.

Analyst Insight

“Indonesia remains a strategic market for PC vendors. The allocation of shipments, particularly for lower-priced products, makes that clear. Moving forward, however, macroeconomic headwinds and ongoing component shortages are forecast to continue to push the prices higher, likely triggering a decline in demand in the near term.” 

— Leonard Adiarto Sudjono, Senior Market Analyst, Devices Research, IDC 

Vendor Outlook: Who Won the Quarter?

IDC Outlook: What’s Next?

Frontloading, that began in Q4 2025 and carried into Q1 2026 reflects a sustained effort by global and local players to secure supply. Q2 2026 will see less stocking activity due to increasing economic uncertainty and anticipated further price hikes, with shipments expected to decline 12.5%. The second half of 2026 is expected to see considerably more negative trends, as inventory piles up and demand weakens. IDC forecasts Q3 to contract 35.4% and Q4 to fall 40.6%, bringing the full-year 2026 decline to 22.9%

What may improve the market outlook? 

  • Continued new product releases may sustain short-term purchasing. Apple’s MacBook Neo, positioned at an attractive price point and launched in Indonesia in May, could drive incremental demand in Q2, though this will depend on the supply availability and allocation to Indonesia market.
  • Indonesia’s government recently revised its policy outlook, including halting expansion of the “free meals” program that had absorbed a significant part of the fiscal budget. These moves have marginally improved investor sentiment, reflected in a slight recovery of the Rupiah. Sustained movement in this direction through 2H 2026 could provide a modest improvement in market sentiment.

What could slow it down?

  • Inventory correction is coming. High channel inventory levels combined with slowing sell-through will lead to reduction in shipments as early as Q3.
  • Macroeconomic pressures are mounting. Currency fluctuations, rising SMB taxation rates, and increased fuel prices from June have intensified market uncertainty and will dampen end-user purchasing power.
  • Supply-side pressures are compounding. Supply constraints, rising component costs, and increasing price sensitivity among end-users will also lead to further negative sentiment in the market.

Key Indicators to Watch: Currency, Taxes, and Inventory Turnover

Currency movements, the widespread impact from new tax policies, and inventory turnover rates will determine the rest of this year’s outlook. With stock levels already high, macroeconomic headwinds are likely to add to the negative impact that will shape the market going forward. 

Frequently Asked Questions

How large is Indonesia’s PC market?

IDC tracked 982,000 units shipped in Q1 2026, up 9.4% year over year.

Which PC vendor leads in Indonesia?

ASUS led the Indonesia PC market in Q1 2026 with a 21.9% market share, followed closely by Lenovo at 21.4%.

What is IDC’s forecast for Indonesia’s PC market in 2026?

IDC forecasts a full-year 2026 decline of 22.9%, with Q3 contracting 35.4% and Q4 falling 40.6%, as inventory correction and macroeconomic pressures weigh on demand.

Go deeper with IDC. Whether you want access to the full tracker dataset or a direct conversation with our analysts, we’re ready to help you navigate your next move.

Leonard Adiarto Sudjono - Senior Market Analyst - IDC Indonesia

Based in Jakarta, Indonesia, Leonard joined IDC as a Senior Market Analyst in May 2023 and has since been responsible for managing IDC’s Trackers for several products, starting with Hardcopy Peripherals, Scanners, Consumables and, since 2024, Industrial Printers, before moving to the Devices team in 2026 where he now covers Personal Computers and Monitors.

For decades, manufacturing was transformed by a single insight: Build only what you need, exactly when you need it. Toyota’s just-in-time model introduced the precision delivery of exactly the right parts, at exactly the right moment, for exactly the right task—eliminating warehouses full of idle inventory and accelerating production. It was one of the most consequential operational shifts of the 20th century.

Enterprise software is about to experience its own JIT moment. And the implications are just as large.

The old model is breaking

Traditional enterprise applications were built on a simple premise. Define a function (finance, HR, procurement, etc.), build a system around it, and get users to come to that system. For decades, that model has held. ERP, CRM, HCM, SCM. Each application owned its functional domain, and humans navigated between them.

That premise is now collapsing.

IDC’s Agentic Evolution of Enterprise Applications Framework, first published in early 2025, laid out the stages through which software was expected to evolve.  Moving through progressive phases, from AI assistant-enhanced applications, to agent-supplemented, to agent-led, and ultimately to agents-as-apps. Now, the next phase is emerging, which IDC refers to as Cross-Application Agents. The concept is simple. AI agents will no longer work inside a single application. They will work across all of them, executing on real-time composability, pulling capabilities, workflows, and data from wherever they live and assembling exactly what the user needs in real time, for that specific outcome.

That is just-in-time software.

What JIT software actually means

In manufacturing, JIT eliminated the cost of excess inventory. In software, JIT eliminates the cost of excess interface. Users no longer navigate to a system. The system comes to them, assembled on demand, hyper-personalized to their role, context, and intent.

Oracle’s recent announcement of 22 Fusion Agentic Applications is a concrete, production example of this model. These are not pre-built applications that users log into. They are cross-application agents created autonomously in real time when needed, combining functionality, workflows, and data from ERP, financials, HCM, CRM, and wherever else the work requires. The application is built in the moment the outcome is requested.  And depending on the likelihood that the request will be repeated in the future, the application may also be dissolved when the work is done.

SAP is making the same bet but framing it differently.  With Joule as the anchoring AI layer sitting between the user and enterprise execution, users state their business intent, and SAP’s autonomous systems handle the rest. It pulls from the underlying application estate to deliver the outcome without requiring the user to understand which systems provide which pieces of the solution.

The Toyota parallel is not subtle

Toyota’s JIT model worked because it required a complete rethinking of the supply chain, including clean supplier relationships, reliable APIs between partners, and shared standards that made on-demand assembly possible. The enterprise software equivalent is identical. Cross-application agents require clean APIs, event-driven architectures, semantic data models, and open connectivity standards like MCP that allow agents to discover and orchestrate capabilities across vendors.

Vendors that haven’t invested in that infrastructure will find themselves on the wrong side of a distribution shift that is already underway. Distribution, in the agent era, no longer runs through a UI. It runs through agent marketplaces, connectors, and open protocols. If an agent can’t find your capability, your capability doesn’t exist.

The stakes are real

This is not a five-year horizon thought experiment. Our Agentic Evolution of Enterprise Applications Framework places cross-application agents as an emerging reality, with leading vendors already building their initial JIT software solutions. IDC’s updated 2026 framework is scheduled for publication in early August. It will not only show the projected transition timing of the enterprise application market toward JIT software (both in aggregate and within 15+ individual application markets), but it will also break down the pricing model progression that is set to accompany this transformation. 

The window for vendors to make their products agent-operable has already begun. APIs must be clean, connectors must be built, and packaging needs to be redesigned around outcomes and consumption, not seats.

For buyers, the shift is equally urgent. The traditional bounds of application markets are becoming transient. The question will no longer be just about which ERP or HCM vendor has the best capabilities. It will be about whether your enterprise architecture can support agents that move freely across it, and whether your software vendor can deliver you the same types of JIT efficiencies that manufacturers started benefiting from nearly 80 years ago.  Just-in-time manufacturing didn’t make the parts less important. It made the system that assembled them the competitive advantage. The same logic applies here.

Software that arrives exactly when needed, assembled precisely for the outcome at hand, and drawing from the full capability estate of the enterprise… that is the model that wins.

Eric Newmark

Eric Newmark - Group Vice President & General Manager of IDC's SaaS, Enterprise Software, CX and Workplace Solutions Division

Eric Newmark is Group Vice President & General Manager of IDC’s SaaS, Enterprise Software, CX, and Workplace Solutions Division, which includes several teams of analysts covering SaaS, 18 enterprise application markets, software monetization, business platforms, marketplaces, and services firms focused…

In two earlier posts I argued that SaaS is being disrupted rather than killed, and that the per-seat revenue model is on its way out. The dramatic decline in market capitalization of SaaS vendors over the past 9 months, sometimes referred to as the SaaS-pocalypse, is partly about investors pricing in the fear that SaaS applications will recede behind an AI agent layer. This would make the SaaS applications become invisible “featureware,” with the agent capturing the user relationship, the workflow, and, eventually, the budget. 

This post will show that enterprise buyers now expect their software vendors to supply the agents, and to serve as the trusted source of data and context for custom-built and third-party agents. This is the natural next progression for SaaS vendors and represents an attractive market opportunity. 

To avoid confusion, here are IDC’s AI-related definitions. An AI assistant is conversational and works as a tool for a human. An AI agent is autonomous, uses other tools, and carries memory and context across tasks. An agentic workflow is a business process that an agent executes end-to-end with limited human intervention. 

SaaS vendors are faced with a dual threat, hence SaaS-pocalypse 

The first threat is that organizations will simply write their own applications instead of buying standard SaaS applications. This threat triggered the dramatic devaluation of SaaS stock in February as Anthropic released its Code capabilities. Conversations with CIOs in enterprises partly validate this fear. While they are not contemplating creating core accounting, HRIS or workforce management applications, they might build rather than buy auxiliary applications in areas such as planning, performance management, compensation management, logistics planning, etc. Application areas where customer requirements vary widely and where legal complexity is low are moving gradually from buy to build. 

The second threat is that agentic overlays will increasingly handle the user interaction while AI agents access SaaS applications via API interfaces to carry out transactions on behalf of the human user. The implication is key price justifiers of SaaS applications, such as the interface, the feature breadth, and the brand gradually disappears from the users. This also implies that the per-seat user pricing stop making sense, when humans are no longer the primary users of SaaS applications. 

AI agent adoption is already past the tipping point 

In IDC’s April 2026 Future Enterprise Resiliency and Spending survey of organizations with 500 or more employees, 74% had already deployed at least one agent, 15% were piloting, and only 1% reported no use and no plans. The same respondents expect the number of agent types in production to roughly triple, from 24 in March 2026 to 62 by 2027. Buyers are not evaluating whether to enter the agentic era. They are deciding which parts of their operation to hand over first, and operational and core business data are their top target. 

The big question is who will deliver these AI agents. Most organizations have deployed standard AI tools and run pilots, but few have redesigned core processes to use AI at scale. The survey results shows that most organizations deploy ready-made agents wherever they can, rather than build their own. 

Where vendor-supplied agents win 

IDC distinguishes four kinds of agent by who builds them and how the buyer obtains them. In-application agents come packaged inside the application and the buyer simply adopts them. Low-code / no-code agents are configured by the buyer in a visual builder the vendor provides. Standalone agents are third-party products the buyer implements alongside existing applications. Custom-built agents are assembled by internal teams using full-stack orchestration frameworks. 

The survey data, which focuses on AI agent quantities as opposed to spend, points in one direction. The two types that vendors supply directly, in-application agents and low-code or no-code builders, are growing fastest in numbers and from the largest installed base. Custom-built agents show the slowest growth, because the orchestration they require is more difficult and require more inhouse skills to build. Buyers prefer to adopt or configure an agent that already understands their data and respects their permissions over building one from scratch. 

SaaS applications as trusted data and context for custom-built agents 

IDC also sees massive demand for custom-built AI agents, especially for core business processes unique to an industry or organization. Standalone products and custom-built agents will operate inside the same enterprise, and they will need data and context that lives inside your application. 

A custom-built or third-party agent that accesses data “from anywhere” still needs a place where the data is correct, the process is compliant, the permissions are enforced, and the transaction is guaranteed to execute. A SaaS vendor can offer vetted business processes, governed data, and audit trails for custom AI agent consumption. This is, in IDC’s view, a key future role for today’s SaaS applications. 

What the AI-pivoted SaaS application looks like 

The interface stops being a single screen and becomes several modes serving the same processes: the traditional UI, a conversational UI, a flow-of-work UI embedded where the user already operates, and machine interfaces so external agents can call the application directly and safely. 

The AI-pivot requires SaaS vendors to rethink the workflow from the ground up, which touches the full stack: foundation models, an embedding layer, a vector database, retrieval-augmented generation, an orchestration layer, guardrails, monitoring, and version management. The vendor also has to give buyers an agent toolkit of their own, so that the low-code and no-code configuration buyers increasingly demand happens inside the vendor’s governed environment rather than outside it. 

European vendors carry an additional set of requirements that, handled well, become a selling advantage. Compliance with GDPR, NIS2, and the EU AI Act (still there despite the recent delay), data residency and sovereign cloud guarantees, genuine multi-language model performance, and transparency in how the AI reaches a decision are all conditions of sale to compliance-sensitive European buyers. 

SaaS is not dead, and the incumbents are not doomed. But the asset that justifies a vendor’s existence is shifting from the screen the user looks at to the agents the vendor supplies and the governed data those and other agents rely on. Your customers already expect you to be their agent supplier. The only question is whether you are ahead of that shift or reacting to it. 

So, what do you actually do with this? There are three concrete moves software vendors need to make in the near term. They are specific, they are sequenced, and the window to move first is closing. I will walk through all three in a focused 25-minute webcast, grounded in IDC survey data from more than 1,000 enterprise organisations: where your customers sit on the AI maturity curve, why vendor-supplied agents will dominate enterprise deployments through 2030, and which ERP and SaaS processes are attracting the most AI investment right now. Secure your spot here. 

Bo Lykkegaard

Bo Lykkegaard - Associate VP for Software Research Europe

Bo Lykkegaard is associate vice president for the enterprise-software-related expertise centers in Europe. His team focuses on the $172 billion European software market, specifically on business applications, customer experience, business analytics, and artificial intelligence. Specific research areas include market analysis,…

これまで、国内のビジネスコンサルティング市場の成長は、個別テーマへの需要と、それを担うコンサルタントの人員拡大によって説明されてきました。「需要が増えれば人を増やし、売上が伸びる」これが長く前提とされてきた成長の方程式です。

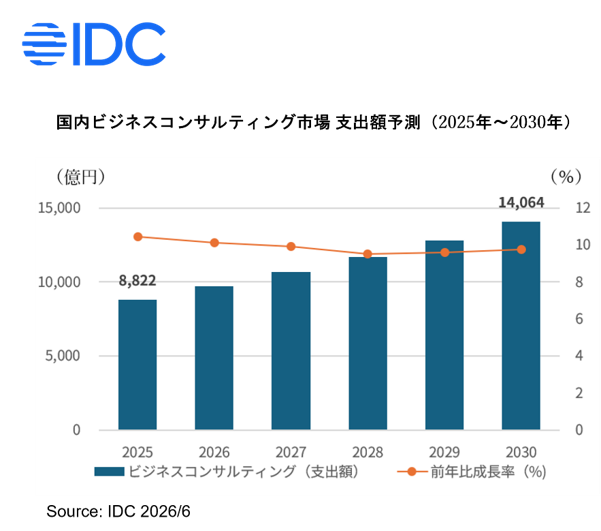
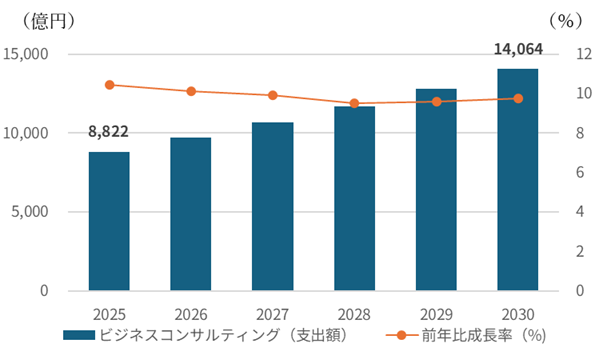
しかし、その前提は変わりつつあります。IDCは、国内ビジネスコンサルティング市場の支出額が、2025年の約8,822億円から2030年には約14,064億円へと、年間平均成長率(CAGRCompound Annual Growth Rate9.8%で拡大を続けると予測しています。

注目すべきは規模だけではありません。AIを核とした企業変革が市場を牽引する中で、案件の規模や収益化、そして成長と人員数の関係そのものが構造的に変化し始めています。本稿では、IDCの最新予測から読み解ける3つの構造変化を解説します。

構造変化(1)AIを核とした「全社変革」が市場を牽引し、案件が大型化する

成長の最大のドライバーは、企業のAI活用と変革需要です。生成AIやエージェンティックAIが「試す」段階から「変革する」段階へ移行し、局所的なAI導入ではなく、業務プロセス・データ基盤・組織体制を一体的に変革する全社変革型の案件が増え、ディールサイズの大型化と複数年にわたる長期プログラム化が進んでいます。

この動きはセグメント別の成長率にも表れています。業務改善コンサルティングは、AIエージェントの業務実装支援やERPのサポート終了(EOS)対応、レガシーモダナイゼーションに伴う上流支援を背景に、全セグメントで最も高い成長を示す見通しです。組織/変革コンサルティングも、後述する「人と組織」の変革需要を背景に堅調な成長が見込まれます。

構造変化(2):「人員増を上回る成長」への転換

より本質的な変化は、売上成長と人員数の関係が切り離され始めていることです。従来の労働集約的な人月モデルに対し、人員数の伸びを上回るペースで売上を拡大するファームが増えています。背景には、複数の要因が同時に作用しています。

  • フィー単価の上昇:人材の供給不足を背景に、案件単価が人員数の伸びを上回って上昇し、1人当たり売上を押し上げています。
  • ソリューション化・アセット化:再利用可能なフレームワークやAIツール、業界別テンプレートを提供物に組み込み、人員を比例的に増やさずに価値を拡大しています。
  • グローバルデリバリーの活用:海外デリバリーセンターやニアショア/オフショアを活用し、国内人員コストを抑えながら供給能力を拡張しています。
  • AIによるデリバリー生産性の向上:現時点で「劇的」ではないものの、1人当たり売上額の着実な向上として表れ始めており、2030年に向けて効果は累積していきます。

さらに中長期では、提供モデルそのものの変容も萌芽的に進んでいます。

  • 成果報酬型(アウトカムベース)契約:顧客の成果指標に連動した報酬設計。
  • プラットフォーム/マネージドサービス型:継続的な収益(リカーリング)を生む提供形態。
  • BOT型・内製化支援:顧客の自走を支えるBOT(Build-Operate-Transfer)型の関与モデル。
  • GCCの活用支援:GCC(グローバルケイパビリティセンター)の構築・活用支援。

これらはまだ一部にとどまりますが、顧客の価値可視化ニーズの高まりとともに採用事例は増えており、人月依存型モデルからの構造転換がファーム各社の戦略課題として明確になりつつあります。

構造変化(3):「人と組織」の変革支援が成長の中核テーマに

企業変革の主軸は、戦略と業務、人と組織、テクノロジー(AI)を横断する形へと拡張しており、中でも「人と組織」の変革支援の重要性が高まっています。全社的なAI変革においてチェンジマネジメントとタレント支援は不可分であり、その需要は単独の案件としてだけでなく、大型変革案件の不可欠な構成要素として組み込まれる傾向を強めています。具体的には、以下のような領域で需要が拡大しています。

  • リスキリング/アップスキリング:AIを前提とした働き方に向けた人材育成。
  • 人的資本経営(HCM):戦略立案から実践までの支援。
  • ワークフォース変革:AIケイパビリティを軸とした役割・組織・チームの再設計。
  • チェンジマネジメント:大型変革プログラムに組み込まれる変革推進支援。

これらは経営戦略や財務・経理など他機能と統合され、複合的な「経営課題」として扱われるようになっています。組織変革の実績を持たないファームは、最も価値の高い変革案件を獲得・維持することが難しくなりつつあります。

ビジネスコンサルティングはITコンサルティングを上回る成長を続ける

国内コンサルティング市場全体(ビジネス+IT)は、2025年の約1兆4,554億円から2030年には約2兆2,897億円へと拡大します。このうちビジネスコンサルティングはCAGR 9.8%でITコンサルティング(同9.0%)をわずかに上回り、全体に占める構成比は2025年の60.6%から2030年には61.4%へと緩やかに上昇する見通しです。背景には、AIを核とした変革の入り口が「経営アジェンダ」からトップダウンで設定されるようになり、戦略立案や業務変革設計といったビジネスコンサルティング領域から案件が起動するケースが増えています。主要事業者の多くが上流のビジネス領域とIT実装を一体化したデリバリーへ移行しており、ビジネスコンサルティング比率の高い案件が収益成長を牽引しています。

コンサルティング事業者のリーダーへの示唆:2030年に向けた5つの戦略的優先事項

以上の構造変化を踏まえると、市場の拡大に乗るだけのファームは、構造転換を進めた競合に成長率で劣後するおそれがあります。次の成長フェーズを取り込むために、各社が優先すべき打ち手は明確になりつつあります。

  • AIを核とした全社変革案件の獲得:個別ソリューションではなく、複数年にわたる大型プログラムにポジショニングする。
  • AIによるデリバリー生産性への投資:競争要件になる前に、今から体制と仕組みを構築する。
  • スケーラブルなソリューション・アセットの整備:人員数に比例しない収益構造へ転換する。
  • 「人と組織」の変革ケイパビリティの確立:最大級の案件を勝ち取る鍵として、組織変革の実績を積む。
  • 成果報酬型・プラットフォーム型モデルの探索:価値の可視化を求める顧客の増加に備える。

国内ビジネスコンサルティング市場は、これからも堅調に拡大します。しかし、その成長の「中身」は、AIを前提とした提供モデルへの転換と、「人と組織」を中核に据えた全社変革支援へと確実にシフトしていきます。この構造変化を早期に捉え、自社のオファリング・人材・デリバリー体制を適応させたファームこそが、2030年に向けた次の成長フェーズを取り込むことができるでしょう。

関連する調査やご相談について 本稿は『国内ビジネスコンサルティング市場予測、2026年~2030年』(IDC #JPJ53501026、2026年5月発行)[MD1][TU2]に基づいています。市場規模・予測の詳細、セグメント別・産業分野別のデータ、主要事業者の動向については、当社アナリストへお気軽にご相談ください[MD3][TU4] 。

植村 卓弥 (Takuya Uemura) - Senior Research Manager, AI and Automation, IDC Japan - IDC Japan

IDC Japanにおいて、年間情報提供プログラムであるJapan AI and Data Platformsのリードアナリストとして、国内AI市場について、サービス/ソフトウェア/インフラストラクチャといったテクノロジースタック全般の予測やシェアの調査/分析を担当する。 IDCでは、15年以上に渡り、ビジネスコンサルティングやITサービス市場などサービス市場全般の予測や競合分析、企業ユーザーニーズなどの調査を担当し、国内市場におけるデジタルトランスフォーメーション/デジタルビジネスの動向と、これらを実現するサービス市場(デジタルビジネスプロフェッショナルサービス市場)についての専門性を持つ。 IDC Japan入社前は、主に国内大手IT ベンダー/通信事業者/電機メーカーなどに向けて、上位レイヤーサービスや各種製品の事業性評価などの調査・コンサルティングに従事。IT関連市場においてSMBを含む法人、消費者の各市場分野についての定量、定性両面の調査経験を有する。 【専門の分野/テーマ】 国内AI市場 国内企業のAI駆動型(AI Fueled)ビジネス動向

これまで、国内のビジネスコンサルティング市場の成長は、個別テーマへの需要と、それを担うコンサルタントの人員拡大によって説明されてきました。「需要が増えれば人を増やし、売上が伸びる」これが長く前提とされてきた成長の方程式です。

しかし、その前提は変わりつつあります。IDCは、国内ビジネスコンサルティング市場の支出額が、2025年の約8,822億円から2030年には約1兆4,064億円へと、年間平均成長率(CAGR:Compound Annual Growth Rate)9.8%で拡大を続けると予測しています。

2025の市場規模(支出額)

8,822億円

2030年までのCAGR

9.8%

注目すべきは規模だけではありません。AIを核とした企業変革が市場を牽引する中で、案件の規模や収益化、そして成長と人員数の関係そのものが構造的に変化し始めています。本稿では、IDCの最新予測から読み解ける3つの構造変化を解説します。

図表1:国内ビジネスコンサルティング市場 支出額予測(2025年~2030年)

Source: IDC 2026/6

構造変化(1)AIを核とした「全社変革」が市場を牽引し、案件が大型化する

成長の最大のドライバーは、企業のAI活用と変革需要です。生成AIやエージェンティックAIが「試す」段階から「変革する」段階へ移行し、局所的なAI導入ではなく、業務プロセス・データ基盤・組織体制を一体的に変革する全社変革型の案件が増え、ディールサイズの大型化と複数年にわたる長期プログラム化が進んでいます。

この動きはセグメント別の成長率にも表れています。業務改善コンサルティングは、AIエージェントの業務実装支援やERPのサポート終了(EOS)対応、レガシーモダナイゼーションに伴う上流支援を背景に、全セグメントで最も高い成長を示す見通しです。組織/変革コンサルティングも、後述する「人と組織」の変革需要を背景に堅調な成長が見込まれます。

構造変化(2):「人員増を上回る成長」への転換

より本質的な変化は、売上成長と人員数の関係が切り離され始めていることです。従来の労働集約的な人月モデルに対し、人員数の伸びを上回るペースで売上を拡大するファームが増えています。背景には、複数の要因が同時に作用しています。

  • フィー単価の上昇:人材の供給不足を背景に、案件単価が人員数の伸びを上回って上昇し、1人当たり売上を押し上げています。
  • ソリューション化・アセット化:再利用可能なフレームワークやAIツール、業界別テンプレートを提供物に組み込み、人員を比例的に増やさずに価値を拡大しています。
  • グローバルデリバリーの活用:海外デリバリーセンターやニアショア/オフショアを活用し、国内人員コストを抑えながら供給能力を拡張しています。
  • AIによるデリバリー生産性の向上:現時点で「劇的」ではないものの、1人当たり売上額の着実な向上として表れ始めており、2030年に向けて効果は累積していきます。

さらに中長期では、提供モデルそのものの変容も萌芽的に進んでいます。

  • 成果報酬型(アウトカムベース)契約:顧客の成果指標に連動した報酬設計。
  • プラットフォーム/マネージドサービス型:継続的な収益(リカーリング)を生む提供形態。
  • BOT型・内製化支援:顧客の自走を支えるBOT(Build-Operate-Transfer)型の関与モデル。
  • GCCの活用支援:GCC(グローバルケイパビリティセンター)の構築・活用支援。

これらはまだ一部にとどまりますが、顧客の価値可視化ニーズの高まりとともに採用事例は増えており、人月依存型モデルからの構造転換がファーム各社の戦略課題として明確になりつつあります。

構造変化(3):「人と組織」の変革支援が成長の中核テーマに

企業変革の主軸は、戦略と業務、人と組織、テクノロジー(AI)を横断する形へと拡張しており、中でも「人と組織」の変革支援の重要性が高まっています。全社的なAI変革においてチェンジマネジメントとタレント支援は不可分であり、その需要は単独の案件としてだけでなく、大型変革案件の不可欠な構成要素として組み込まれる傾向を強めています。具体的には、以下のような領域で需要が拡大しています。

  • リスキリング/アップスキリング:AIを前提とした働き方に向けた人材育成。
  • 人的資本経営(HCM):戦略立案から実践までの支援。
  • ワークフォース変革:AIケイパビリティを軸とした役割・組織・チームの再設計。
  • チェンジマネジメント:大型変革プログラムに組み込まれる変革推進支援。

これらは経営戦略や財務・経理など他機能と統合され、複合的な「経営課題」として扱われるようになっています。組織変革の実績を持たないファームは、最も価値の高い変革案件を獲得・維持することが難しくなりつつあります。

ビジネスコンサルティングはITコンサルティングを上回る成長を続ける

国内コンサルティング市場全体(ビジネス+IT)は、2025年の約1兆4,554億円から2030年には約2兆2,897億円へと拡大します。このうちビジネスコンサルティングはCAGR 9.8%でITコンサルティング(同9.0%)をわずかに上回り、全体に占める構成比は2025年の60.6%から2030年には61.4%へと緩やかに上昇する見通しです。背景には、AIを核とした変革の入り口が「経営アジェンダ」からトップダウンで設定されるようになり、戦略立案や業務変革設計といったビジネスコンサルティング領域から案件が起動するケースが増えています。主要事業者の多くが上流のビジネス領域とIT実装を一体化したデリバリーへ移行しており、ビジネスコンサルティング比率の高い案件が収益成長を牽引しています。

コンサルティング事業者のリーダーへの示唆:2030年に向けた5つの戦略的優先事項

以上の構造変化を踏まえると、市場の拡大に乗るだけのファームは、構造転換を進めた競合に成長率で劣後するおそれがあります。次の成長フェーズを取り込むために、各社が優先すべき打ち手は明確になりつつあります。

  • AIを核とした全社変革案件の獲得:個別ソリューションではなく、複数年にわたる大型プログラムにポジショニングする。
  • AIによるデリバリー生産性への投資:競争要件になる前に、今から体制と仕組みを構築する。
  • スケーラブルなソリューション・アセットの整備:人員数に比例しない収益構造へ転換する。
  • 「人と組織」の変革ケイパビリティの確立:最大級の案件を勝ち取る鍵として、組織変革の実績を積む。
  • 成果報酬型・プラットフォーム型モデルの探索:価値の可視化を求める顧客の増加に備える。

国内ビジネスコンサルティング市場は、これからも堅調に拡大します。しかし、その成長の「中身」は、AIを前提とした提供モデルへの転換と、「人と組織」を中核に据えた全社変革支援へと確実にシフトしていきます。この構造変化を早期に捉え、自社のオファリング・人材・デリバリー体制を適応させたファームこそが、2030年に向けた次の成長フェーズを取り込むことができるでしょう。

関連する調査やご相談について

本稿は『国内ビジネスコンサルティング市場予測、2026年~2030年』(IDC #JPJ53501026、2026年5月発行)に基づいています。市場規模・予測の詳細、セグメント別・産業分野別のデータ、主要事業者の動向については、当社アナリストへお気軽にご相談ください。

植村 卓弥 (Takuya Uemura) - Senior Research Manager, AI and Automation, IDC Japan - IDC Japan

IDC Japanにおいて、年間情報提供プログラムであるJapan AI and Data Platformsのリードアナリストとして、国内AI市場について、サービス/ソフトウェア/インフラストラクチャといったテクノロジースタック全般の予測やシェアの調査/分析を担当する。 IDCでは、15年以上に渡り、ビジネスコンサルティングやITサービス市場などサービス市場全般の予測や競合分析、企業ユーザーニーズなどの調査を担当し、国内市場におけるデジタルトランスフォーメーション/デジタルビジネスの動向と、これらを実現するサービス市場(デジタルビジネスプロフェッショナルサービス市場)についての専門性を持つ。 IDC Japan入社前は、主に国内大手IT ベンダー/通信事業者/電機メーカーなどに向けて、上位レイヤーサービスや各種製品の事業性評価などの調査・コンサルティングに従事。IT関連市場においてSMBを含む法人、消費者の各市場分野についての定量、定性両面の調査経験を有する。 【専門の分野/テーマ】 国内AI市場 国内企業のAI駆動型(AI Fueled)ビジネス動向

SpaceX’s $60 billion acquisition of Cursor is the largest deal in the history of AI software and one that reshapes the competitive landscape for agentic coding. The all-stock transaction, filed with the SEC and expected to close in Q3 2026, follows an option SpaceX secured in April and exercised just two trading days after its Nasdaq debut, the largest IPO in history. Cursor enters the deal with reported annualized revenue near $2.6 billion, a growing enterprise customer base, and a proprietary coding model in Composer that the two companies have already been jointly training on Colossus, xAI’s purpose-built supercomputing cluster.

The acquisition gives Cursor the GPU capacity, power, cooling, and land to build a best-in-class coding LLM on its own terms, while giving SpaceX a commercially proven path into enterprise software engineering that its AI division has been unable to build on its own. The question now is whether Cursor can translate that infrastructure position into a proprietary model layer that rivals what Anthropic and OpenAI offer, and whether SpaceX can provide the operational conditions for that to happen.

The SpaceX acquisition empowers Cursor to produce a best-in-class coding LLM

Cursor’s most important strategic move in this acquisition is gaining the infrastructure to build a proprietary coding model that can compete directly with the best models from Anthropic and OpenAI. In agentic coding, innovation now occurs at two layers. The harness shapes how the system plans, uses tools, navigates repositories, and interacts with developers across a workflow. The model determines the quality of reasoning, coding intelligence, and long-horizon execution. Cursor has established credibility at the harness layer through its product, but the model layer is where the economics and competitive dynamics of the business are decided.

Today, Anthropic and OpenAI occupy a dual role in Cursor’s stack. They supply the models that power much of the product while competing directly against it through Claude Code and Codex. That overlap gives outside providers influence over Cursor’s cost structure, release timing, and the pace at which underlying model quality improves. Under those conditions, revenue can scale faster than gross margin improvement, because incremental usage continues to flow through the same high-cost third-party model APIs. Cursor can grow more successful commercially without becoming proportionally more efficient.

Cursor has already demonstrated the ability to develop promising coding models of its own. The progression from Composer 2 to Composer 2.5 has combined coding-specific pretraining, large-scale reinforcement learning, and synthetic data generation to improve end-to-end software engineering performance. With access to Colossus, Cursor can now run pretraining, post-training refinement, synthetic data generation, and evaluation across successive model generations on its own timeline, at the cadence and scale required to produce a best-in-class coding LLM. A proprietary model layer at that level would reduce Cursor’s exposure to supplier concentration, give the company greater control over gross margins, and allow it to set its own cadence for performance improvement and product releases rather than tracking the road maps of its direct competitors.

Cursor’s domain focus is an advantage in model development that broader frontier labs cannot easily match

Cursor’s exclusive focus on coding and software engineering gives it an advantage over Anthropic and OpenAI that the SpaceX acquisition now allows it to exploit at frontier scale. Its model-development effort, from pretraining data to post-training refinement to evaluation benchmarks, is organized around the developer personas and workflows that define the agentic coding market. Anthropic and OpenAI, by contrast, build general-purpose frontier models where coding is one priority among many, competing for post-training resources against writing, content generation, multimodal reasoning, and other capabilities their customers depend on. Post-training involves trade-offs across a model’s capability surface, and improving performance in one dimension can diminish it in others. Cursor faces no such constraint. Because Composer serves one use case, Cursor can push post-training as far as coding performance allows without managing the downstream effects on capabilities it does not need to preserve.

That advantage compounds over time because feedback loops are tighter, improvement cycles are more targeted, and the benchmarks that matter are directly tied to what determines whether a developer trusts a coding tool enough to make it part of their daily workflow. With Colossus behind it, Cursor can run that focused, domain-specific development loop at frontier scale and at a pace that broader frontier labs, managing far wider capability obligations, will find difficult to match.

Secured GPU capacity determines who can compete at the frontier

The SpaceX acquisition gives Cursor access to GPUs at a scale previously secured only by the hyperscalers and a small number of frontier AI companies and infrastructure providers such as OpenAI, Anthropic, Oracle, and NVIDIA. GPU capacity remains the primary gating factor in the development of frontier foundation models. The companies that can train and refine the best coding models are, in large part, the companies that can secure sustained access to large concentrations of GPUs. Without that access, a company may have strong model-development methods but no way to apply them at the scale that frontier competition demands.

Securing that level of dedicated GPU capacity is difficult through conventional channels. Neocloud providers such as CoreWeave and Lambda can supply GPU capacity, and hyperscaler marketplaces offer on-demand and reserved instances, but none of these can guarantee the sustained, concentrated access that frontier model development requires. Training runs for successive model generations span weeks at high utilization across thousands of chips simultaneously. That demand profile is incompatible with shared infrastructure and variable availability.

Power, cooling, and land are the infrastructure constraints that sit upstream of GPU access

GPU scarcity is only the most visible bottleneck. Sustained model training at frontier intensity also depends on physical infrastructure that most organizations cannot assemble on demand. Power is the first constraint, because training runs at this scale require continuous, uninterrupted supply measured in hundreds of megawatts, backed by utility agreements that take years to negotiate. Cooling is the second, because dense GPU clusters running at sustained utilization generate thermal loads that require purpose-built systems designed and installed before a facility becomes operational. Land is the third, because suitable sites must offer grid access sufficient to support these loads, zoning and permitting conditions that allow large-scale datacenter construction, and proximity to transmission infrastructure. These inputs are increasingly contested as AI infrastructure buildouts compete with other industrial and residential demands for the same sites and the same grid capacity.

Anthropic, OpenAI, and Google have secured their compute positions through years of capital commitment, hyperscaler relationships, and direct NVIDIA agreements. Colossus, xAI’s purpose-built supercomputing cluster, reflects a comparable effort to control the full set of inputs required for frontier-scale compute. The SpaceX acquisition transfers that secured position to Cursor, bypassing the procurement bottleneck that would otherwise define the company’s model development ceiling. Cursor gains immediate access to infrastructure that would have taken years to assemble independently.

SpaceX acquires enterprise distribution it could not build through model development alone

The acquisition gives SpaceX something its AI division has been unable to build on its own, a commercially proven path into enterprise software engineering. Strong foundation models often struggle to translate into meaningful adoption inside engineering teams because this market is shaped by workflow fit, developer trust, product integration, and the degree to which a tool becomes part of daily software development rather than an occasional assistant. xAI has faced exactly that challenge. Despite investing heavily in Grok, it has not built the product surface, the developer relationships, or the commercial traction needed to compete for enterprise software engineering workflows against Anthropic and OpenAI. Cursor closes that gap in a way that model development alone cannot.

Cursor has already built one of the most commercially significant agentic coding products in the market, with reported annualized revenue near $2.6 billion and a growing enterprise customer base. That position took years of product execution to build and cannot be replicated by releasing a better model. At 3.4% dilution against its IPO valuation, SpaceX is making a concentrated bet that enterprise software distribution is worth acquiring rather than building from scratch. That bet becomes more credible as Composer improves on Colossus, because the infrastructure investment and the distribution asset reinforce each other. A better model running inside a trusted developer product is the combination that drives sustained enterprise adoption.

Conclusion

The central risk to Cursor’s enterprise position is whether SpaceX under Elon Musk can sustain the organizational conditions that enterprise software adoption requires. Musk’s stewardship of X raised legitimate questions about product stability, developer relations, and sustained institutional engagement. His outspoken political positions and willingness to use his platforms to advance them have also made brand association a factor in enterprise procurement decisions in ways that most technology vendors do not face. Those concerns affect procurement conversations and vendor risk assessments, and they are not unreasonable. SpaceX has strong financial incentives to grant the Cursor team a high degree of operational independence, because the alternative would erode the asset it just paid $60 billion to acquire. Whether those incentives prove sufficient is not yet clear.

The more important question, however, is what Cursor can become with the resources now behind it. With dedicated access to one of the largest GPU clusters outside the hyperscalers, a focused model-development effort unconstrained by the multi-domain trade-offs that Anthropic and OpenAI must manage, and a product that has already reached meaningful commercial scale, Cursor is positioned to build one of the strongest proprietary coding model layers in the industry. If SpaceX provides the operational autonomy and infrastructure access the deal implies, the ceiling on what Cursor can achieve in agentic coding is substantially higher than it was as an independent company.

Arnal Dayaratna

Arnal Dayaratna - Research Vice President, Software Development

Dr. Arnal Dayaratna is Research Vice President, Software Development at IDC. Arnal focuses on software developer demographics, trends in programming languages and other application development tools, and the intersection of these development environments and the many emerging technologies that are enabling…

In the first quarter of 2026, the worldwide Ethernet switch market reached $15.4 billion, growing 39.8% year over year, according to IDC’s Quarterly Ethernet Switch Tracker. The datacenter segment, which covers high-speed switching infrastructure inside hyperscale and enterprise data centers, surged 61.0% YoY to $10.0 billion, fueled by AI infrastructure investments for AI inferencing and training workloads at scale. In a landmark shift, NVIDIA became the #1 vendor by revenue in datacenter Ethernet switching for the first time. Campus and branch switching grew 12.3% YoY, supported by a hardware refresh cycle and rising component prices.

Ethernet switch market highlights

Datacenter segment

The datacenter portion of the Ethernet switch market grew 61.0% YoY in 1Q26 to reach $10.0 billion, according to IDC. This growth reflects the continued build-out of AI infrastructure by hyperscalers, cloud providers, and large enterprises. High-speed ports dominate spending: 800G switches accounted for 35.8% of datacenter segment revenues, while 200Gb/400Gb speeds represented 34.1% combined, together making up nearly 70% of datacenter Ethernet switch spending.

Campus/branch (non-datacenter) segment

Enterprise campus and branch Ethernet switch revenue grew 12.3% YoY in 1Q26 to $5.4 billion, per IDC. Two forces are at work: a broad hardware refresh cycle as organizations upgrade aging infrastructure to support newer Wi-Fi standards, AI-powered applications, and modern digital workloads; and average selling price increases driven by component shortages, particularly memory, which amplified revenue growth above underlying unit shipment trends.

Regional performance

Total Ethernet switch revenues grew across all regions in 1Q26, according to IDC. The Americas led with 49.7% YoY growth, reflecting strong hyperscaler and enterprise AI investment in North America. EMEA posted 32.2% growth, while Asia Pacific grew 25.9% YoY.

Router market highlights

The total router market reached $3.8 billion in 1Q26, growing 11.3% year over year, driven by continued investment in both service provider and enterprise network infrastructure, according to IDC’s Quarterly Router Tracker.

Service provider segment

The service provider segment, including communications service providers and cloud SPs, made up 77.2% of total router market revenues in 1Q26, reaching $2.9 billion with 12.9% YoY growth. Cloud and telecom infrastructure upgrades remain the primary driver.

Enterprise segment

The enterprise router market contributed $867 million, growing 6.1% YoY in 1Q26, reflecting ongoing investment in enterprise WAN connectivity and SD-WAN-enabled infrastructure modernization.

Regional performance

In 1Q26, the Americas router market rose 19.6% YoY, leading all regions. EMEA grew 9.8% YoY, while Asia Pacific posted 2.8% growth.

Vendor highlights

Cisco

$4.5B revenue, 29.3% market share, +24.0% YoY.  Cisco’s total Ethernet switch revenues increased 24.0% YoY in 1Q26, capturing 29.3% market share, per IDC. Non-datacenter revenues, representing 60.5% of Cisco’s total, grew 14.1% YoY, reflecting the campus refresh tailwind, while datacenter revenues rose 43.0% YoY on strong AI infrastructure demand. Cisco’s total router revenue grew 24.4% YoY, giving the company a 35.1% market share in 1Q26.

NVIDIA

$2.1B revenue, 21.5% datacenter segment share, +192.7% YoY.  NVIDIA’s Ethernet switch revenues, entirely from the datacenter segment, surged 192.7% YoY to $2.1 billion in 1Q26, giving it a 21.5% share of the datacenter segment, according to IDC. This result marks a significant milestone: NVIDIA is now the #1 vendor by revenue in datacenter Ethernet switching. NVIDIA’s Spectrum-X platform, an end-to-end AI networking solution that integrates Spectrum Ethernet switches with BlueField DPUs and NVIDIA LinkX cables, purpose-built for large-scale GPU clusters, has emerged as the preferred network interconnect for large-scale AI training, winning significant traction with hyperscalers and AI-native cloud providers building AI factories.

Arista Networks

$2.2B revenue, 14.6% market share, +37.3% YoY.  With 92% of its Ethernet switch revenues in the datacenter segment, Arista’s revenues grew 37.3% YoY in 1Q26 to $2.2 billion, per IDC. Arista holds a 14.6% share of the total Ethernet switch market and 20.7% in the datacenter segment, maintaining strong positioning in 400G and 800G deployments with hyperscale customers.

Huawei

$895M revenue, 5.8% market share, +27.2% YoY.  Huawei’s total Ethernet switch revenue increased 27.2% YoY in 1Q26 to $895 million, giving the company a 5.8% market share, per IDC. Huawei’s router revenue grew 0.8% YoY in 1Q26, with a 25.4% market share, underscoring continued strength in the service provider networking segment, particularly in China and select emerging markets.

HPE

$985M revenue, 6.4% market share, +15.4% YoY.  HPE’s total Ethernet switch revenue (70.5% from the non-datacenter segment) grew 15.4% YoY in 1Q26, reaching a 6.4% market share, per IDC. HPE revenues now include Juniper Networks, following the July 2025 acquisition. The company’s deepened campus and branch portfolio is converting the current refresh wave into revenue.

Market dynamics

NVIDIA becomes #1 in datacenter Ethernet switching

The main takeaway for 1Q26 is NVIDIA’s position at the top of the datacenter Ethernet switch market. IDC data shows that with 192.7% YoY growth and $2.1 billion in quarterly revenue, NVIDIA’s Spectrum-X platform has captured hyperscaler and enterprise demand for AI factory network infrastructure through integrated co-design across GPUs and networking. This structural shift is redrawing vendor standing across the datacenter networking industry.

AI as the primary demand driver

AI deployments are accelerating across both hyperscalers and large organizations, applied to enhance customer experience, reduce operational risk, and empower key business areas, including IT infrastructure and operations, software development, and sales. According to IDC, this broad adoption of AI workloads, from large-scale training clusters to inferencing at the enterprise edge, is driving sustained demand for high-speed, low-latency datacenter networking.

Campus refresh cycle and component-price inflation

Non-datacenter switching is benefiting from a convergence of a broad enterprise hardware refresh cycle and rising average selling prices driven by memory component shortages, according to IDC. Organizations are replacing switching infrastructure to support modern wireless standards and digital workloads, while supply constraints are inflating revenue growth above underlying unit volumes, a dynamic IDC expects to persist in the near term.

“NVIDIA’s rise to #1 in datacenter Ethernet switching in a single year is one of the most significant vendor landscape shifts IDC has tracked in enterprise networking. Spectrum-X’s integrated GPU-plus-networking design is winning AI factory deals that incumbent networking vendors cannot match with standalone hardware alone. The campus side tells a different but equally important story: the refresh wave is real, but IT teams should plan for ASP normalization once memory supply constraints ease. Budget for the transition now, not after prices move.” — Paul Nicholson, Research Vice President, Cloud and Datacenter Networks, IDC

“Enterprise campus and branch ethernet switching growth is driven by a variety of factors: First, organizations are upgrading both their wired and wireless networks as part of a multi-year refresh cycle to support Wi-Fi 7, and enhanced speeds across the access, distribution, and core layers of the network. AI, security and IoT are other key drivers. Meanwhile, memory-driven supply chain concerns are a headwind worth watching in the coming quarters.” — Brandon Butler, Senior Research Manager, Network Infrastructure and Services, IDC

Why it matters

Who should care?

CIOs, network architects, IT procurement teams, and technology vendors should pay close attention. According to IDC, NVIDIA’s position as the #1 datacenter Ethernet switching vendor in 1Q26 signals a shift in datacenter networking, reflecting the growing influence of AI infrastructure on purchasing decisions. Campus-focused buyers should factor in the impact of sustained ASP increases when planning budget refreshes.

Business impact

Organizations building AI infrastructure now face a more complex vendor landscape for datacenter networking, with compute and network decisions increasingly intertwined. On the campus side, the convergence of a refresh wave and price inflation is creating both urgency and budget pressure for IT teams.

Ecosystem signal

The composition of the datacenter Ethernet switching market is being redrawn. Vendors that meet AI factory requirements with highly integrated functionality, including high-bandwidth, low-latency, lossless fabrics, are gaining share at scale. This is reshaping the competitive outlook for all incumbent networking vendors.

What’s next for the Ethernet switch and router market

IDC expects the Ethernet switch market to sustain strong momentum through 2026, underpinned by continued AI infrastructure investment from hyperscalers and enterprises. As inferencing deployments scale alongside training workloads, demand for high-speed datacenter switching, particularly at 800G and beyond, should remain robust. NVIDIA’s position will face increasing competitive responses from Cisco, Arista, and Broadcom ecosystem vendors, making the datacenter segment one of the most actively contested in networking.

In campus and branch, the refresh cycle is expected to continue, though revenue growth could moderate if memory supply constraints ease and reduce the ASP tailwind. Macro uncertainty, including tariff risks and regional economic volatility, remains a watch item that could temper investment decisions in some geographies.

Learn more

For deeper analysis and IDC research on enterprise network infrastructure trends, visit the IDC Quarterly Ethernet Switch Tracker and IDC Quarterly Router Tracker at idc.com, or contact IDC for the latest market insights and custom research.

Paul Nicholson

Paul Nicholson - Research Vice President, Networking and Infrastructure Services, Enterprise Infrastructure

Paul Nicholson is Research Vice President within IDC’s enterprise infrastructure global research domain and part of the networking infrastructure and services subdomain. He focuses on AI, cloud, and datacenter network infrastructure. His research spans Ethernet and InfiniBand switching, application delivery…
Brandon Butler

Brandon Butler - Senior Research Manager, Networking and Infrastructure Services, Enterprise Infrastructure

Brandon Butler is a Senior Research Manager within IDC’s enterprise infrastructure global research domain and part of the networking infrastructure and services subdomain. His research covers market and technology trends, forecasts, and competitive analysis in enterprise campus, branch, and edge…
Petr Jirovsky

Petr Jirovsky - Senior Research Director, Networking and Infrastructure Services, Enterprise Infrastructure

Petr Jirovsky is a Senior Research Director within IDC’s enterprise infrastructure global research domain and part of the Networking and Infrastructure Services subdomain. He provides quantitative insights on network infrastructure for the datacenter, cloud, and campus/branch environments. He serves as…
Diego Anesini

Diego Anesini - VP Data and Analytics, Networking

Diego Anesini serves as Vice-President, Data & Analytics, Networking. Prior to this position, Diego held various roles in the company. The most recent was VP, Data & Analytics for Latin America. He has extensive experience in the Networking, Telecom and…

AIエージェントの台頭を背景に、ソフトウェア市場では「SaaS is Dead?」をはじめとするアプリケーション市場の終焉論が各所で語られるようになっています。しかし、日本のソフトウェア市場は今、一世代に一度の成長サイクルへと踏み出そうとしています。

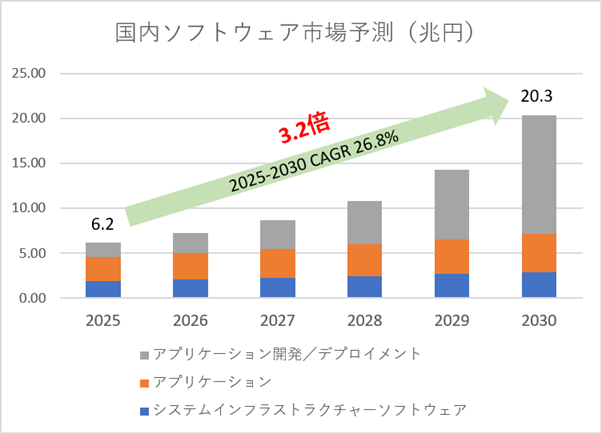
IDCの最新調査「Worldwide Semiannual Software Tracker, 2025H2(2026年5月発行)」は、2030年までに国内ソフトウェア市場が20兆円規模に達すると示しています。この成長は漸進的な量的拡大ではなく、あらゆるソフトウェアセグメントにわたるAIネイティブソフトウェアへの構造的転換が原動力です。

「市場は縮小しない、変革する—そして変革こそが成長の源泉となる」

数年おきに、特定のソフトウェアカテゴリが終焉を迎えるという言説が繰り返されてきました。かつてはオンプレミス、次いで企業向けIT、そして今やSaaSが「時代遅れ」の槍玉に挙がっています。その根拠は単純です——AIエージェントがあらゆる業務を自動化できるなら、多層的なアプリケーションにコストをかけ続ける意義はどこにあるのか、というものです。

IDCの最新データは、この問いに明確な答えを示しています。ソフトウェアはAIによって陳腐化するのではなく、AIによって根本から作り直されているのです。そしてこの転換は、多くの関係者が想定していたよりもはるかに速いペースで進行しています。

実際、2025年末時点で日本企業の50%以上がすでに生成AIを本格導入しており、PoC段階を含めると90%以上が何らかの形で活用しています。AIエージェントについても、40%超の企業でパイロットまたは本番環境での運用が始まっています。IDCはこの現状こそが、今後5年間の成長を測る出発点になると見ています。

「3つのセグメント、1つの共通エンジン」

IDCは国内ソフトウェア市場を3つの主要セグメントに分類して予測しています。いずれのセグメントでもAIによる再編が進行中ですが、成長の速度や性質にはセグメントごとに明確な差異が見られます。

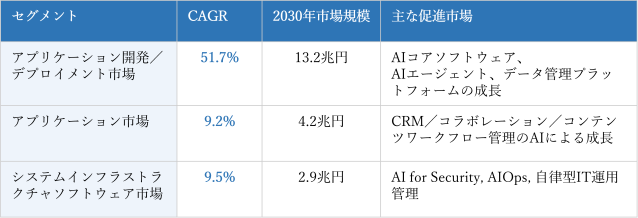
出典:Worldwide Semiannual Software Tracker 2025H2, IDC Japan, June 2026

「際立つ存在:AIコアソフトウェア市場」

アプリケーション開発/デプロイメント市場の中に、特筆すべき市場があります。生成AIファウンデーションモデルやAIエージェントを含む「AIコアソフトウェア市場」は、予測型AI、生成AI、エージェンティックAIの導入進行によって大きく成長すると予測しています。

これが、アプリケーション開発/デプロイメント市場全体のCAGRを51.7%へと押し上げている主要因です。AIは既存のソフトウェアカテゴリを単に強化しているのではなく、5年前には存在しなかったまったく新たなカテゴリそのものを創出しています。

「着実な拡大:アプリケーション市場とシステムインフラストラクチャ市場」

アプリケーション市場はCAGR 9.2%という堅実なペースで成長を続け、2030年までに4兆2,223億円に達すると予測されています。これは成長の鈍化ではなく、既存レイヤーが「置き換え」ではなく「AIへのアップグレード」として進化していることを示しています。アプリケーションベンダー各社はAI/エージェント機能を製品に組み込み差別化を図っていますが、ソフトウェアをゼロから再構築しているわけではありません。

システムインフラストラクチャソフトウェア市場も同様の傾向を示しています。CAGR 9.5%での拡大は、切実なオペレーション上の課題が牽引しています。セキュリティ領域でのAI活用、AIOps、そして自律型エージェントによるITシステム管理は、セキュリティ、ITオペレーション分野での人材不足が深刻化する中、もはや選択肢ではなく必要不可欠な手段となりつつあります。

「IDC最新データが示す示唆」

ベンダーにとって、問いの中心はすでに「AIを取り入れるべきか」から「どこまで深く組み込むか」へと移っています。表層的なAI統合はすでに標準化されつつあり、先行するプレイヤーはAIを段階的な機能追加としてではなく、製品そのものの抜本的な再設計として捉えています。

ITバイヤーにとっては、明確な近道を示しています。AI対応アプリケーションの採用は、カスタムビルドソフトウェアの完成を待つよりもはるかに早く価値創出を実現します。すでにAIを本番環境で稼働させている企業と、まだ計画段階にとどまる企業との差は、着実に開き続けています。

「SaaSは終わった」という言説は、現実を見誤っています。終焉の圧力にさらされているのは、静的でAIへの対応を怠ったソフトウェアです。一方、AIネイティブソフトウェアは成長を続けており、エージェント中心の世界に向けて設計され、前世代のツールには不可能だった形で市場を切り拓いています。日本のソフトウェア市場が2030年に20兆円規模に達するという予測は、過去の成長サイクルの単純な繰り返しではありません。IDCはこれを、業界そのものが根底から姿を変えていることを告げる構造的なシグナルと捉えています。

出典:IDC Japan、Worldwide Semiannual Software Tracker 2025H2、2026年5月発行

関連する調査やご相談について

より詳細なインサイトや市場動向については、当社アナリストへお気軽にご相談ください。

Takashi Manabe - Senior Research Director, AI and Automation, IDC Japan - IDC Japan

Takashi Manabe is the Senior Research Director of AI and Automation groups in IDC Japan. Mr. Manabe's primary responsibility includes the analysis of the dynamics and trends, vendor strategies, and market sizing/modeling of Japan’s enterprise AI related market including Software, Services and Infrastructure. He also covers Security, Data Management/ Bigdata Analytics, Customer Experience and Digital Transformation market related to AI. Before joining IDC, Mr. Manabe worked at Toshiba Corporation, Toshiba America Information Systems, Inc., and Toshiba TEC Corporation. 20 over years his experience in the communications and software market, Mr. Manabe started his business as a system engineer for PBX/enterprise data communications equipment in Toshiba Corporation. He was also act as product planning and marketing manager for communication equipment/ software. He also acted as business planning, business management in Toshiba America's age for cable TV Internet business in the enterprise, security software and consumer communication market. Just prior to join IDC, Mr. Manabe worked at Toshiba TEC Corporation, for document solution such like MFP remote management system, scan OCR solution as product planning manager. Mr. Manabe graduate of Muroran Institute of Technology, Japan, holds a Master Degree of Computer Science and Engineering. He also holds a Bachelor degree in Computer Managed Machinery Systems from Muroran Institute of Technology.

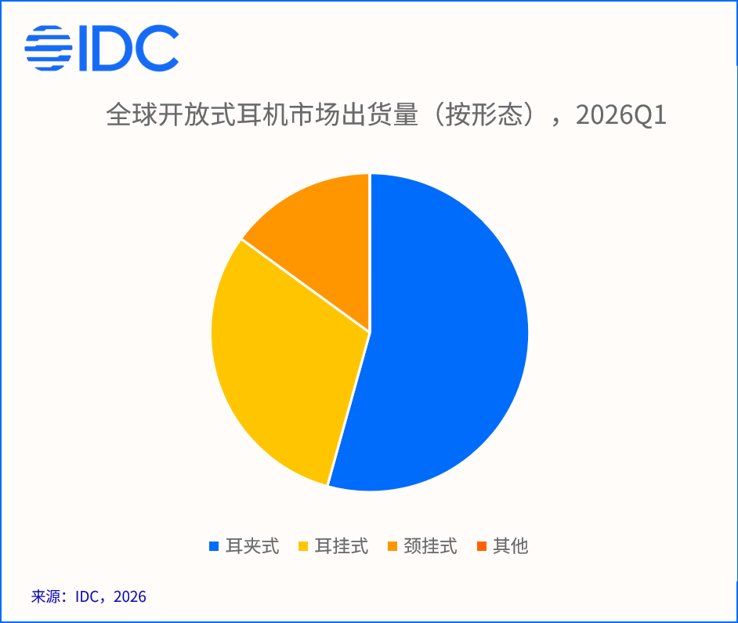
国际数据公司(IDC)最新发布的2026年第一季度全球耳戴市场数据显示,开放式耳机出货量同比增长39.9%,在整体耳戴市场仅增长3.9%的背景下表现突出。但IDC认为,比增速更值得关注的是品类结构,竞争格局与市场需求的多重转变。品类结构上,耳夹式占比首次过半,稳固其主流产品形态的地位。当前全球开放式耳机市场由中国厂商主导,海外品牌加速入局,行业竞争持续升温。与此同时,AI技术为市场注入全新动能,智能化将成为下一阶段竞争核心。

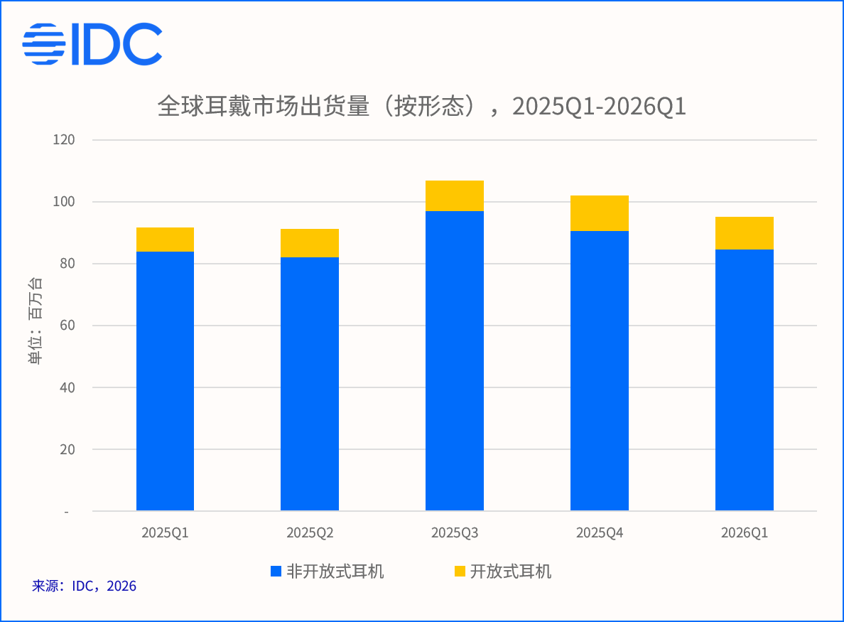
根据IDC最新发布的《全球可穿戴设备市场季度跟踪报告,2026年第一季度》显示,2026年一季度全球耳戴市场出货9,520万台,其中开放式出货1,067万台,同比增长39.9%,占比达到11.2%。凭借差异化的佩戴体验,开放式耳机在蓝牙耳机品类中的出货占比正持续攀升。

IDC三大核心洞察

结合开放式整体市场走势与市场竞争态势,2026年一季度全球开放式市场耳机三大核心洞察如下:

洞察一:细分品类格局重塑,耳夹式领跑市场增长

开放式耳机细分形态迎来明显更迭,品类内部竞争格局持续重构。2026年一季度,耳夹式在开放式产品中占比54.3%,同比份额增幅超10个百分点,已成为全球开放式耳机的主流形态。该品类凭借精巧的外观与多场景适配的能力受到市场认可,叠加时尚属性带来的溢价能力,部分采取机海战术的厂商逐步调整布局重心,从耳挂式赛道转向加码耳夹式产品。耳挂式同比增长11.8%,市场份额有所回落,凭借佩戴稳定性,现阶段头部品牌主要聚焦于运动细分场景。作为开放式领域成熟度最高的品类,颈挂式产品凭借骨传导技术深耕运动赛道,并依托游泳等专属场景稳固市场定位,同比增长11.9%,增速保持稳健。

洞察二:中国厂商主导市场,差异化竞争格局深化

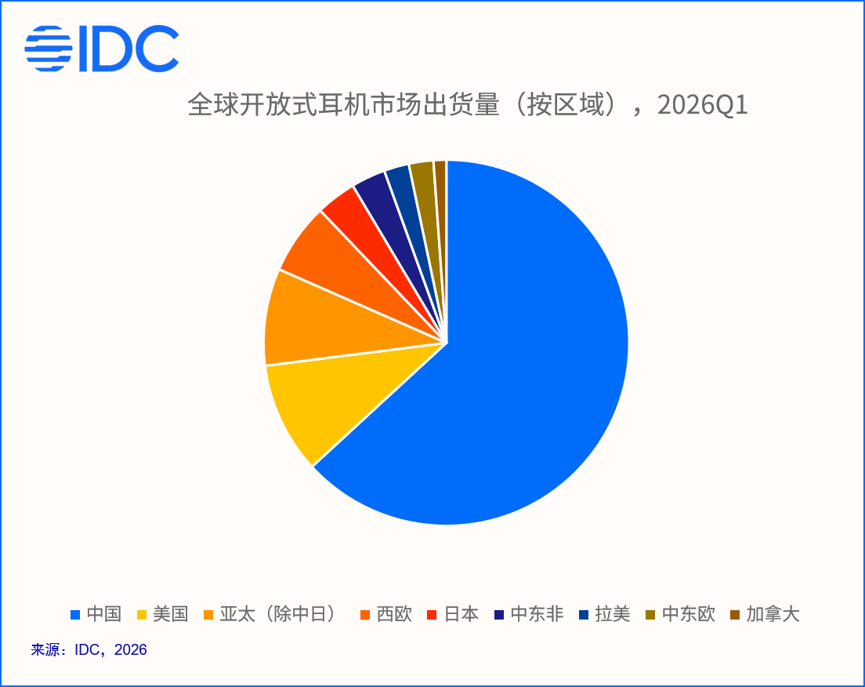
中国是开放式耳机起步最早,规模最大的核心市场,2026年一季度中国市场出货量占比超过六成。美国,亚太(不含中国和日本)及西欧市场紧随其后,增长态势亮眼。中国厂商利用先发优势全球布局,凭借完善的供应链与多元化产品矩阵持续抢占全球市场份额。市场主流集中在50美元以下及100美元以上两大价格区间,分层竞争特征显著。100美元以上高端市场中,核心技术,音质表现,品牌力与智能化成为竞争关键。韶音,华为凭借综合实力稳居领先位置。Bose,JBL等海外传统音频厂商也加码布局,依靠声学技术优势夯实产品实力,丰富自身产品线。50美元以下入门市场主打性价比,厂商凭借多样外观,新颖形态及丰富机型吸引消费者,中国与印度厂商为该市场主力。

洞察三:AI赋能硬件升级,智能化渗透空间广阔

随着蓝牙耳机硬件日趋同质化,AI技术已成为行业破局的重要方向。智能服务的迭代优化,离不开长期佩戴所沉淀的用户数据,而开放式耳机适配长时间佩戴的特性,为AI功能落地提供了天然优势。部分中国厂商已将产品搭载AI功能作为营销亮点,入门级产品主要对接第三方云端大模型,落地场景以实时翻译,会议纪要等办公需求为主,相关功能主要依托手机APP运行,并不具备端侧实时运算能力。优质的智能化体验目前仍集中于中高端产品线。定位商务场景的厂商,搭配自研大模型与端侧处理芯片,将AI打造为核心竞争壁垒,而非常规附加功能。手机品牌则凭借自有操作系统优势,整合自研大模型与终端硬件,构建“系统+模型+硬件”一体化生态闭环。该模式深度绑定用户使用习惯,有效强化用户粘性与品牌忠诚度。目前全球市场中的AI功能整体渗透率有待提升,品类智能化升级仍拥有广阔发展空间。

IDC建议

面对开放式耳机品类格局重构,中国厂商领跑全球,AI技术驱动产品升级的行业新态势,IDC为行业参与者提出以下三点切实可行的战略建议:

建议一:找准市场定位,优化产品结构与资源布局

开放式耳机品类加速分化,市场格局不断演变。厂商需明确自身赛道定位,避免盲目跟风内卷。耳夹式增长势头强劲,而耳挂式凭借更大的机身空间,更利于搭载元器件,落地 AI相关功能。厂商需结合自身核心优势搭建产品矩阵,平衡流量型与技术型产品布局,合理分配研发与产能资源,打造符合行业长期发展趋势的产品体系。

建议二:依托产业优势,深耕差异化竞争与品牌力建设

依托成熟的供应链与规模化制造能力,中国厂商可充分发挥产业优势。作为市场的先发参与者,应把握发展窗口期,聚焦品牌建设,规避同质化低价竞争。同步推进本土化运营,结合各地消费特征,文化偏好制定市场策略,以差异化产品与本地化服务提升用户认同,持续夯实全球品牌价值与综合竞争力。

建议三:着眼长远发展,强化AI核心能力建设

随着蓝牙耳机产品同质化问题日益凸显,厂商应将AI智能化升级确立为长期核心战略。依托开放式耳机可长时间佩戴、持续沉淀用户数据的特性,在现有的语音助手,AI降噪等应用基础上,拓展个性化服务,智能自适应调节等高阶体验。推动AI从单纯的营销亮点转变为核心产品实力,把握行业智能化转型机遇,充分释放市场增长潜力。

IDC中国研究经理戴翘楚认为,当前全球开放式耳机品类结构加速调整,中国厂商依托产业积淀与先发优势领跑市场,AI智能化则将成为行业下一阶段竞争焦点。厂商需明确发展方向,打造差异化产品,推进全球化布局,同时坚持长期投入,深耕AI核心技术,夯实可持续发展根基。

综合来看,IDC认为2026年第一季度全球开放式耳机市场的核心变化在于:耳夹式正在重塑品类格局,中国厂商持续主导全球市场,而AI技术的实际落地仍处于早期阶段。对于行业参与者而言,单纯依靠形态创新或价格策略的增长空间正在收窄,下一阶段的竞争将更多取决于厂商在技术深耕和智能化能力上的长期投入。市场仍在高速增长,但赛道逻辑正在变化,唯有做出清晰战略选择的厂商才能在竞争中占据主动。

如对本次报告内容感兴趣,或咨询其他相关内容,欢迎与IDC联系,以获取更多信息或探讨合作机会。

请点击此处与我们联系