腕戴设备市场正在发生静默而深刻的结构性转折。智能手表与手环的走势分化、各价位段需求的冷热不均、区域市场之间的增长落差——这些表象背后,同一个问题是所有参与者必须回答的:当普及红利消退,增量从何而来?本文基于IDC最新发布的《全球可穿戴设备市场季度跟踪报告》,梳理2026年第一季度全球腕戴市场的三大结构性特征、头部厂商的应对策略,以及中国市场的独特发展路径。


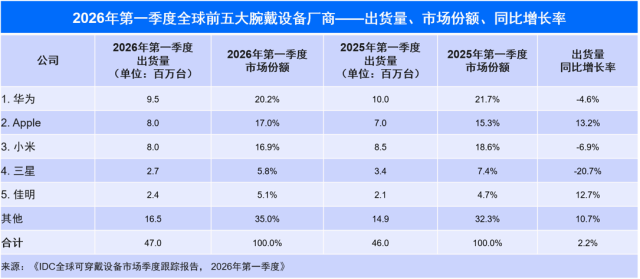
根据国际数据公司(IDC)最新发布的《全球可穿戴设备市场季度跟踪报告》,2026年第一季度全球腕戴设备市场出货量为4,705万台,同比增长2.2%。腕戴设备市场包含智能手表和手环产品。其中,全球智能手表市场出货量3,703万台,同比增长4.8%。手环市场出货量1,002万台,同比下滑6.1%。腕戴产品发展背后,全球市场呈现出哪些特点?头部厂商表现如何?中国市场又将呈现哪些异同?本文将为您一一解读。

2026一季度全球腕戴市场发展的三大特点

根据IDC跟踪报告,2026年一季度全球腕戴市场发展呈现以下三个显著特点:

特点一:手表走强,手环疲软

智能手表凭借功能升级稳步增长,部分分流手环用户。手环受去年需求提前透支、存储成本抬升影响,再加入门手表价格下探抢占市场,需求持续承压,整体走势偏弱。

特点二:价位结构升级,入门稳、高端旺

大环境承压下,百元美金以内入门产品依靠刚需稳住出货量;300 美元以上高端机型依托软硬件迭代、健康医疗及AI功能升级,消费升级需求逐渐释放,高端价位段增速突出。

特点三:区域发展分化

中国凭借新品发布与电商促销,成为全球增长主力;美国、拉美受益换新与渗透率提升小幅增长,其他地区受经济影响需求表现平淡。

2026一季度全球腕戴市场Top 5厂商表现

华为

2026 年一季度华为腕戴产品全球出货量登顶。华为时隔5年推出 WATCH GT Runner 2,深耕专业跑步赛道;Ultimate 2 高尔夫版满足进阶人群的专业需求;手环 11 系列补齐入门价位空档。全品类阶梯矩阵落地,完善价格与功能布局,稳固华为穿戴出货领先优势。

Apple

2026年一季度中国市场成为苹果智能手表全球增长核心驱动力。品牌提前落地多轮促销活动有效拉动终端销量;产品高端定价优势明显,可更大程度消化上游元器件涨价带来的成本压力,对冲供应链紧缺负面影响,支撑中国市场业绩稳步上行。

小米

2026年一季度小米智能手表表现优于手环品类。品牌落地 S5 系列新品,持续加大中高端 Watch 5 铺货力度,稳步向上优化产品结构。中高端机型逐渐放量,小米加速优化产品结构,逐步向中高端市场纵深布局。

三星

三星全球主推 Galaxy Watch8 及 8 Classic,但整体出货受内部战略调整小幅收缩。欧美成熟市场需求承压,中东、非洲等新兴市场依托品牌口碑与渗透率提升实现小幅增长,成为品牌现阶段为数不多的增量市场。

佳明

佳明坚守专业户外、运动细分赛道,深耕垂直用户巩固专业产品壁垒;同时加速产品迭代、拓宽大众消费产品线。配合各地阶段性营销与促销落地,品牌兼顾专业与大众市场,在多个区域实现出货同比增长。

2026一季度中国市场发展的三大特点

IDC报告指出,2026年第一季度中国腕戴市场出货量1814万台,同比增长3.5%;其中成人智能手表出货量888万台,同比增长15.3%,儿童手表出货量442万台,同比增长22.4%,手环市场出货量483万台,同比下滑22.2%。

特点一:入门价位补位扩容,五百元档市场回暖

500 元以下成人智能手表一季度出货量回暖。头部品牌产品迭代逐步撤出该价格带,中小品牌顺势优化产品配置填补空白。上游存储成本抬升环境下,该档位机型性价比凸显,精准承接入门刚需,拉动该价位稳步回暖。

特点二:渠道分化凸显,线上增速领跑线下

产品成熟带动消费者选购趋于理性,用户习惯线上比价筛选机型。叠加直播、多平台大促等多元电商业态持续扩容,线上渠道出货增速显著跑赢线下。线下侧重体验成交,增长相对稳健,线上已成为拉动大盘增量的核心载体。

特点三:产品精细化发展,功能人群多元细分

市场开始逐渐尝试跳出同质化堆砌,逐步走向场景与用户分层。更具有针对性的女性向和青少年设计的产品更多出现,在全智能、专业健康、专业运动、日常健康和轻运动等维度打造差异化卖点,围绕细分需求定制产品,精细化细分成为行业明确发展趋势。

针对技术供应商和采购方的建议

建议一:产品分层精细化布局,打造差异化竞争壁垒

厂商应搭建阶梯化、差异化产品矩阵,规避同质化与低价内卷。面对存储成本上涨压力,各价位段需优化配置与定价策略。中小厂商依托优质体验稳固入门市场,头部品牌深耕高端健康、AI、运动功能迭代。通过场景、功能、外观多元差异化设计,覆盖多人群需求,筑牢产品竞争壁垒。

建议二:双线渠道协同布局,高效盘活存量增量市场

厂商需优化线上线下双线渠道协同布局,加大电商、直播等线上资源投入,依托平台优势快速走量、盘活存量。线下门店重点聚焦高端机型体验、售后服务与高价值用户转化,打造线上引流、线下提质增收的良性渠道体系。

建议三:区域市场差异化深耕,分散经营风险挖掘增量

厂商应实施差异化区域运营策略,平衡市场规模与盈利水平。欧美成熟市场避开低价内卷,深耕专业运动、健康垂直圈层守住利润;积极开拓拉美、中东非等新兴市场,凭借性价比快速提升渗透率。同时深耕中国本土市场,依托新品迭代与电商促销持续激活换新增量。

分析师观点与行业建议

IDC认为,全球腕戴行业已告别普及放量期,正式迈入存量精细化竞争阶段。增量不再依靠全民新机普及,转而由产品升级、细分人群、区域下沉三大逻辑驱动。成本波动加速行业洗牌,倒逼品牌放弃低价同质化内卷,依托价位分层与场景细分挖掘新增量,未来品牌综合产品架构、渠道与区域布局的能力将成为拉开份额差距的关键。

延伸阅读与沟通:

如需了解更多IDC相关研究或进一步与我们沟通,欢迎与 IDC 联系,我们将安排专人与您对接,为您提供定制化的市场洞察与咨询服务。

请点击此处与我们联系

Sophie Pan

Sophie Pan - Research Director, Client System Research

Sophie Pan is a research director for the Client Systems Research team at IDC China. She is responsible for emerging technology device research, including wearable devices and smart home devices. Sophie has a deep understanding of the landscape and ecosystem…

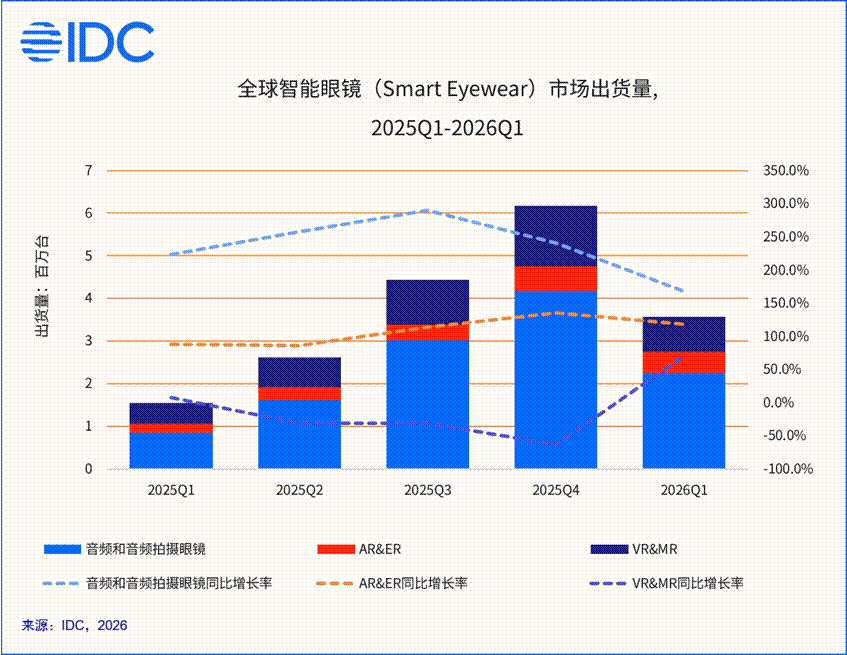
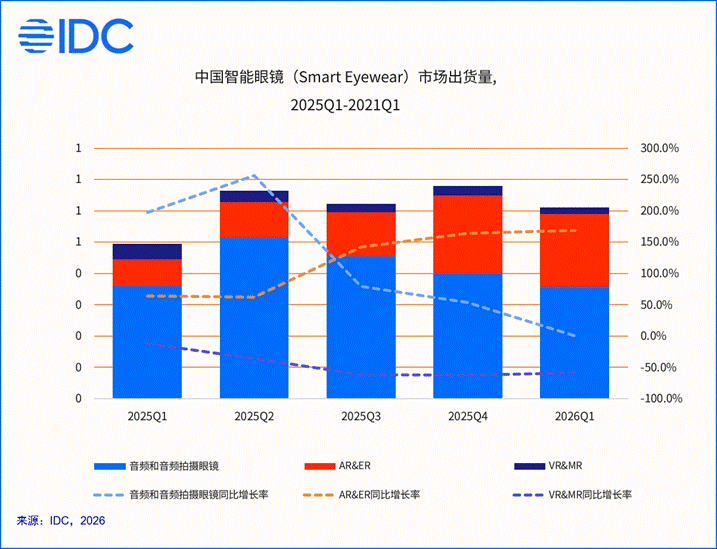
2026年第一季度,全球智能眼镜市场以130.1%的同比增速交出亮眼答卷,中国市场以23.5%的增长位列全球第三。然而,增速背后的结构性剧变更值得关注。国际数据公司(IDC)最新数据显示,中国音频和音频拍摄眼镜市场整体出货量同比下滑0.1%,其中不具备拍摄功能的纯音频眼镜产品需求开始疲软;,而轻量级显示眼镜逐步进入消费视野,带动AR&ER市场同比增长168.6%,成为一季度市场结构变化的重要变量。与此同时,国家补贴首次纳入智能眼镜,叠加AI大模型落地和密集新品发布,正在加速行业从“功能叠加”向“场景增值”演进。

全球市场

IDC最新数据显示,2026年第一季度全球智能眼镜(Smart Eyewear)市场出货量356.6万台,同比增长130.1%。其中全球音频和音频拍摄眼镜市场出货量224.8万台,同比增长167.4%;AR/VR市场出货131.8万台,同比增长85.9%。

全球市场产品动态

1. 国际巨头动向持续定义赛道方向

巨头在智能眼镜领域的布局预期持续发酵,赛道本身的战略价值已获得产业链和资本端的双重验证。

苹果:智能眼镜项目或于2026–2027年进入量产窗口。首代可能采用无屏轻量化设计,分阶段落地规划可为供应链预留爬坡周期,同时通过持续释放预期信号占据市场声量,为后续产品迭代积累用户认知基础。苹果的入局会倒逼供应链成熟、拉升用户认知,但也会在高端市场形成新的竞争压力。

谷歌:谷歌以Android XR平台授权加合作方硬件为主,与XREAL合作的Project Aura、与三星及Gentle Monster等联合开发的音频及显示眼镜均为确认项目。平台方身份规避了自有硬件的库存与品控风险,同时为国产硬件出海提供适配入口。

2. 跨界新玩家入局拓宽行业边界

非传统XR厂商的进入,说明智能眼镜的竞争已从专业赛道扩展至更广泛的消费电子领域。不同背景厂商带来的差异化场景定义有助于激活多元用户群体。

科大讯飞:语音技术切入办公场景,避开定位和手机生态的正面竞争。以垂直场景建立差异化认知,为中小厂商提供单点突破路径参考,其场景深度与商业闭环的验证值得期待。

极米:将自身技术优势进行迁移,探索新形态,品牌认知为产品溢价提供支撑,也为行业注入创新变量,将拓展智能眼镜在影音娱乐场景的价值边界。

3. AI厂商加速布局,推动竞争逻辑升级

未来的竞争将更多依赖软件生态和用户数据积累,而非单纯的产品迭代速度。对行业而言,头部AI厂商的介入将提升终端用户的认知水位,加速市场教育进程。

阿里:千问眼镜上市后份额提升迅速,核心在于打通了千问大模型与电商、支付生态,将硬件作为生态入口。有屏S1与无屏G1双线并行,覆盖不同用户需求,生态闭环的完整性是其区别于竞品的核心优势。

字节:字节产品发布时间尚未明确,但其在内容生态和算法推荐上的积累,使其具备从内容分发端切入市场的潜力。有望激活更多年轻用户群体,为市场带来新的增长变量。

中国市场:

2026年一季度中国智能眼镜市场在全球市场中份额排名第三,一季度出货量61万台,同比增长23.5%。本季度,智能眼镜首次被纳入国家补贴目录,带动渠道备货和终端需求释放,成为市场增量的核心动力。拍摄眼镜、具备AI大模型的眼镜、显示眼镜等细分品类均实现三位数同比增长,行业竞争加速分化,创新节奏明显加快。主流产品在轻量化、AI能力和佩戴体验等方面持续优化,叠加新品密集发布和渠道深度拓展。

中国细分市场概况及市场格局

音频和音频拍摄眼镜市场

2026年一季度,中国音频和音频拍摄眼镜市场结构出现明显升级,总出货量35.8万台,同比下滑0.1%,但其中音频拍摄眼镜占比达到43.4%,同比增长513.1%。

支持AI大模型语音助手的新品上市节奏加快,推动产品创新活跃。市场份额进一步向具备差异化功能和创新能力的品牌集中,TOP5品牌合计市场份额超过50%。小米、阿里、华为、雷鸟等头部厂商持续储备新品,带动行业竞争格局加速分化。从应用角度来看,厂商需要在高频场景中验证产品能否真正降低用户操作成本,这将直接影响用户留存和品牌口碑。

AR/VR市场

2026年一季度,中国AR/VR市场出货量25.2万台,同比增长86.2%。

AR&ER品类保持高速增长,季度市场份额已超过90%,同比增长168.6%。从市场表现来看,显示型眼镜新品的关注度相对高于音频眼镜,尽管轻量级显示眼镜的价格普遍集中在2000-3500元区间,仍处于较高水平,但其核心优势在于用户价值感知的提升。音频眼镜的功能与手机高度重叠,用户较难形成刚性使用习惯,而显示型眼镜能够覆盖手机难以触达的应用场景,带来更直观的体验,因此用户的尝鲜意愿和溢价接受度更高。从产品结构来看,轻量级显示眼镜已成为用户入门显示类产品的首选,为后续向更高端产品的转化奠定基础。

VR&MR市场一季度出货量同比下滑58.8%。整体表现依然低迷,缺乏新的增长动力。苹果Vision Pro M5版本虽然在产品层面有所更新,但产品定价仍处高位,内容生态和佩戴舒适度尚未达到用户预期,导致市场热度与实际转化之间存在明显落差。此外,VR&MR市场企业级采购有一定机会,但体量有限,尚不足以对冲消费端的疲软表现。

未来展望与新机会

IDC中国市场分析师叶青清认为,当前智能眼镜产品普遍面临的问题在于,虽然用户愿意为新鲜感买单,但不会为体验短板持续付费,若无法在体验上形成持续价值,用户留存就会成为瓶颈。因此厂商在产品定义和资源投入上需要做出更务实和偏向性的取舍。

在此基础上,未来还有以下几个方向值得追踪:

第一,新型方案已开始受到行业关注。独立通信、固态电池、体征监测集成等方向已经处于技术验证或小规模试产阶段,为产品定义和场景创新提供了新的可能性,值得持续跟踪。但现阶段真正影响用户留存的仍是连接稳定性、佩戴舒适度等基础体验,厂商在跟进新技术的同时,需要优先把现有成熟方案做到位。

第二,外观设计正成为用户决策的关键变量。轻量化已从加分项变为必选项,时尚性和个性化设计将在下半年成为头部厂商建立品牌辨识度的重要手段。在技术参数趋同的背景下,佩戴体验直接影响购买转化和日常使用频率,设计的差异化正在从产品层面升级为品牌资产。

第三,国内隐私安全标准正在加速落地。随着可穿戴设备采集敏感数据的场景增多,国内相关标准化工作已在推进。厂商需将隐私保护前置到概念设计阶段,合规能力将加速行业洗牌,提前建立技术储备和认证体系的厂商,有望在下一阶段竞争中占据主动。

IDC持续关注全球智能眼镜及可穿戴设备市场的发展动态。我们诚邀行业同仁、投资机构及媒体朋友与IDC中国分析师团队保持沟通,共同探讨市场趋势、技术创新与商业机遇。无论您是希望深入了解数据细节,还是寻求定制化市场洞察,欢迎随时与我们联系。

请点击此处与我们联系

The worldwide WLAN market reached $2.7 billion in 1Q26, growing 15.9% year over year. Wi-Fi 7 (802.11be) now accounts for 44.5% of enterprise dependent access point revenues (up from 11.8% in 1Q25). Within four quarters, Wi-Fi 7 went from a nascent segment to the dominant enterprise Wi-Fi generation being deployed globally. The shift is driven by enterprise demand for higher throughput, lower latency, and Multi-Link Operation (MLO) capabilities, all essential for AI-powered applications, high-density wireless environments, and modern IoT-intensive workloads. Source: IDC Quarterly Wireless LAN Tracker, 1Q26.

WLAN market highlights

Total market

The worldwide WLAN market grew 15.9% year over year in 1Q26, reaching $2.7 billion. The dependent AP segment (the majority of the market) grew 18.5% YoY to $2.1 billion, outpacing overall market growth. According to IDC’s Quarterly Wireless LAN Tracker, this reflects sustained corporate investment in wireless infrastructure modernization.

Wi-Fi 7 inflection

Wi-Fi 7 dependent AP revenues reached $958.4 million in 1Q26, representing 44.5% of dependent AP revenues and growing 348% year over year from $214.1 million in 1Q25. IDC’s tracker shows the pace of adoption has been rapid: from under 1% of enterprise revenues in 1Q24 to nearly half the market by 1Q26.

Wi-Fi 6/6E migration

As Wi-Fi 7 accelerates, earlier-generation standards are declining in share. Wi-Fi 6 (802.11ax) accounted for 34.8% of enterprise dependent AP revenues in 1Q26 (down from 54.4% a year ago), while Wi-Fi 6E held 20.0%. Both are now primarily driven by refresh, mid-market, and value-based deployments rather than strategic enterprise wireless initiatives.

Regional performance

The Americas led WLAN growth in 1Q26 at 17.0% YoY, reaching $1.29 billion and accounting for 48.5% of total revenues. EMEA grew 15.7% YoY to $799.7 million; APJ expanded 13.7% YoY to $565.5 million.

Vendor highlights

Cisco

$1.0B revenue, 38.9% market share, +14.1% YoY.  Cisco remains the market share leader, supported by strong enterprise demand for its Wi-Fi 7 portfolio and continued momentum in large-scale campus and branch deployments.

HPE

$527.9M revenue, 19.9% market share, +8.9% YoY.  The combined HPE Networking business (comprising HPE Aruba Networking and HPE Juniper Networking) brings complementary strengths to enterprise WLAN, spanning cloud-managed deployments to AI-powered operations.

Ubiquiti

$345.1M revenue, 13.0% market share, +29.1% YoY.  The strongest revenue growth among the top five vendors. Ubiquiti’s platform continues to gain traction with mid-market enterprises and managed service providers attracted by competitive pricing, rapid Wi-Fi 7 product refresh, and cloud-based management.

Huawei

$158.5M revenue, 6.0% market share, +27.7% YoY.  Growth is driven primarily by Wi-Fi 7 campus solutions and an integrated campus-LAN portfolio, mainly in markets outside the USA, Canada, and Western Europe.

Vistance Networks

$91.6M revenue, 3.5% market share, +12.9% YoY.  Formerly CommScope/Ruckus. In April 2026, Belden announced its intent to acquire Ruckus Networks from Vistance.

Market dynamics

Wi-Fi 7: from emerging to dominant in eight quarters

Wi-Fi 7 is one of the fastest-ramping enterprise wireless standards in IDC’s tracking. In 1Q24, Wi-Fi 7 represented less than 1% of enterprise dependent AP revenues. By 1Q26, it accounts for 44.5%.

The drivers are structural. The combination of Multi-Link Operation (MLO), 320 MHz channel bandwidth, and 4096-QAM delivers throughput that prior generations cannot match at scale. For enterprise buyers deploying AI-assisted collaboration, high-density video, and real-time location services, Wi-Fi 7 addresses requirements that Wi-Fi 6 and 6E cannot efficiently serve at scale.

AI workloads as a catalyst for wireless refresh

AI-powered enterprise applications are showing up in WLAN refresh conversations in a way that wasn’t true two years ago. As organizations deploy AI tools across workforce productivity, customer engagement, and operations, the demands on network infrastructure intensify. Applications requiring real-time inference, constant cloud connectivity, and low-latency responses to mobile users all stress WLAN capacity. This is pulling forward Wi-Fi 7 decisions on otherwise conservative refresh timelines.

Enterprise refresh cycle and multi-standard coexistence

Not all enterprise buyers are moving to Wi-Fi 7 at the same pace. Large, distributed organizations are managing multi-standard environments where Wi-Fi 6, Wi-Fi 6E, and Wi-Fi 7 coexist across campuses and branch sites. Vendors with strong cloud management platforms that can orchestrate heterogeneous deployments are better positioned to capture refresh spend. The rising average selling price (ASP) of Wi-Fi 7 access points is also contributing to the revenue mix shift above and beyond unit volume.

“Wi-Fi 7’s move to 44.5% of enterprise dependent AP revenues in a single year is one of the faster standard transitions we’ve tracked in enterprise WLAN. The drivers are real and reinforcing: AI workloads demanding lower latency, denser IoT environments, and MLO capabilities that earlier standards simply can’t deliver at scale. The growth outlook for 2026 remains strong, but macroeconomic pressure, memory supply constraints, and competing IT budget priorities are headwinds worth monitoring as the year progresses.” – Brandon Butler, Senior Research Manager, Network Infrastructure & Services, IDC

Why it matters

Who should care?

CIOs, network architects, IT procurement teams, and CFOs planning capital budgets should take note. The Wi-Fi 7 inflection is not a distant trend: it is happening now and the transition carries real implications for refresh planning, vendor selection, and total cost of ownership. Organizations that delay Wi-Fi 7 adoption risk falling behind on the network capabilities required to support enterprise AI and next-generation mobile workloads.

Business impact

The rapid mix shift to Wi-Fi 7 is reshaping enterprise wireless economics. Access points that support Wi-Fi 7 carry higher average selling prices than previous generations, raising per-site deployment costs and requiring renewed budget conversations with finance teams. At the same time, organizations that invest in Wi-Fi 7 are positioning themselves to support AI-driven applications and high-density connectivity scenarios that Wi-Fi 6/6E cannot efficiently serve at scale.

What’s next for the WLAN market

IDC expects the WLAN market to sustain strong growth through 2026, with Wi-Fi 7 continuing to capture a larger share of enterprise revenues as the installed base of Wi-Fi 6 and 6E access points comes up for refresh. IDC’s trajectory analysis suggests Wi-Fi 7 will exceed 50% of enterprise WLAN revenues in the near term, accelerated by enterprise AI adoption, the ongoing campus modernization wave, and competitive pricing pressure as the vendor ecosystem scales up Wi-Fi 7 supply chains.

Competition among the top vendors will stay intense. Cisco’s scale holds in large enterprise. HPE Networking’s AIOps differentiation with HPE Juniper Networking is a credible differentiator in intelligence-forward environments. Ubiquiti is applying cost pressure in the mid-market that the larger players can’t ignore. Macro risks (memory supply chain challenges and tariff exposure) are real headwinds, particularly outside the Americas, but the structural demand driving Wi-Fi 7 adoption isn’t discretionary. The applications requiring it exist today.

Learn more

For deeper analysis and IDC research on enterprise wireless LAN trends, visit the IDC Quarterly Wireless LAN Tracker at idc.com, or contact IDC for the latest market insights and custom research.

Brandon Butler

Brandon Butler - Senior Research Manager, Networking and Infrastructure Services, Enterprise Infrastructure

Brandon Butler is a Senior Research Manager within IDC’s enterprise infrastructure global research domain and part of the networking infrastructure and services subdomain. His research covers market and technology trends, forecasts, and competitive analysis in enterprise campus, branch, and edge…
Petr Jirovsky

Petr Jirovsky - Senior Research Director, Networking and Infrastructure Services, Enterprise Infrastructure

Petr Jirovsky is a Senior Research Director within IDC’s enterprise infrastructure global research domain and part of the Networking and Infrastructure Services subdomain. He provides quantitative insights on network infrastructure for the datacenter, cloud, and campus/branch environments. He serves as…
Diego Anesini

Diego Anesini - VP Data and Analytics, Networking

Diego Anesini serves as Vice-President, Data & Analytics, Networking. Prior to this position, Diego held various roles in the company. The most recent was VP, Data & Analytics for Latin America. He has extensive experience in the Networking, Telecom and…

We are projecting global IT spending on AI to reach $409 billion in 2026, roughly 53% year-over-year growth, and on track to reach $700 billion by 2029. That is not a trend. That is a structural transformation of the global technology economy, playing out in real time.

And yet, for all that investment, the enterprise is not keeping up. AI is now mainstream in production use, with roughly two-thirds of organizations already using AI in live production environments as of the beginning of 2026. But most have not scaled meaningfully beyond targeted, isolated deployments. Broad, full-scale operationalization remains the exception, not the rule. IDC’s FutureScape 2026 research puts a finer point on this, projecting that nearly 50% of AI-driven digital use cases will miss their ROI targets in 2026 due to unclear business gains, weak human-machine collaboration, and poor data foundations.

This is not a technology problem. Technology is advancing faster than at any point in modern enterprise computing history. This is an adoption enablement problem. If you want to dive deeper into the reasoning behind why this is happening, check out our previously published report, The Speed of AI Value Creation in Applications: What’s Causing the Delay?. But the bottom line is that the gap is widening. AI innovation is outpacing enterprise adoption, and vendors building and selling AI software are the only ones positioned to solve it.

The pilot-to-production gap is where value goes to die

We have been here before. In the early cloud era, organizations ran dozens of successful pilots while struggling to migrate core workloads. In the early SaaS era, adoption stalled on integration complexity and change management, not product capability. The pattern is familiar. Technology races ahead, and the enterprise ecosystem (integrations, governance, skills, data infrastructure) takes years to catch up.

AI is repeating this cycle at a faster and more consequential pace. The vendors who recognize that and act on it will define the next era of enterprise software leadership. The vendors who do not will find that great technology alone does not close a revenue gap.

Lead with outcomes, not capabilities

The first imperative is a reframing of what vendors are actually selling. Enterprises do not struggle to understand what AI can do in a demo. They struggle to connect AI capabilities to measurable business outcomes within their specific operating environments, data, workflows, and compliance requirements.

Vendors that lead with model benchmarks and feature roadmaps are speaking a language their buyers have stopped prioritizing. Vendors that lead with quantified outcomes (reduced invoice processing cycle times, lower error rates in demand forecasting, faster financial close) will earn the trust and the internal sponsorship needed to move from pilot to production. This is not a marketing adjustment. It is a fundamental repositioning of the value proposition with direct revenue implications. For any AI provider, growth is no longer tied to license counts. It is tied to how deeply customers embed AI into daily workflows. Outcome-led selling accelerates that depth.

Time-to-value is now a competitive differentiator

One of the most important metrics vendors need to track is time-to-value: how quickly a new customer achieves a materially improved workflow through AI. Right now, that timeline is too long for too many enterprises. Integration complexity, data readiness gaps, and internal skills shortages create friction that stalls momentum and gives procurement committees reasons to pause.

Vendors can close this gap directly. Pre-built integrations for common enterprise architectures, workflow templates calibrated to specific industry use cases, and structured onboarding programs that guide customers from pilot to production are no longer nice-to-have services. They are now the product. Enterprises successfully scaling AI are doing so with vendor partners who meet them where they are, not where the vendor’s road map assumes they should be.

Stop handing the data problem back to the customer

Poor data foundations are consistently among the top barriers to AI ROI. Our research has explicitly shown this, and it’s a core reason why roughly half of AI pilots fail to deliver ROI. Yet many vendors still mistakenly treat data readiness as a customer prerequisite rather than a shared problem.

That assumption needs to end. Vendors who win the next phase of this market will be those who help enterprises assess, clean, and structure their data as part of the implementation process, not as a precondition that customers must solve before the real engagement begins. That means investing in data readiness tooling, offering pre-implementation assessments, and building data quality explicitly into success criteria from day one. At best, handing the data problem back to the customer delays deployment. At worst, it kills the project entirely and takes the renewal with it.

Governance is not a feature. It’s a foundation.

Governance concerns (security, auditability, regulatory compliance, responsible AI use) are significantly slowing enterprise decision cycles. Vendors that treat governance as a layer to add later are creating their own headwinds. Enterprises that stall after a successful pilot often do so not because the AI stopped working, but because legal, compliance, or IT security raised issues that the product was not designed to address.

Building explainability, access controls, audit trails, and compliance frameworks into the core product, rather than bolting them on top, is what separates vendors well-positioned for enterprise deployments from those perpetually stuck at the proof-of-concept stage. And the window to get this right is narrowing, as governance requirements are quickly moving toward regulatory mandates.

Align commercial models to customer success

The vendors best positioned to close the adoption gap will be those who structure their commercial relationships around customer outcomes rather than seat counts or token consumption. Oracle’s recently announced 22 Fusion Agentic Applications are a great example of this refocusing, as they shift their enterprise software solutions from being passive “systems of record” to autonomous “systems of outcomes”. SAP and ServiceNow both recently announced similar positioning. SAP is moving beyond traditional SaaS toward an outcome-oriented model where agentic AI, anchored by Joule, sits between the user and enterprise execution. Users state their business intent, and SAP’s autonomous systems handle the rest, more closely aligning execution with outcome. ServiceNow also made a deliberate pivot toward outcome-driven execution, repositioning itself from a platform of record into what it now calls an “AI control tower.” The shift extends to its partner ecosystem as well, where updated programs now reward vendors based on actual customer outcomes and successful deployments rather than traditional membership tiers.

Vendors need to continually focus more on outcome-based pricing, adoption milestone incentives, and dedicated customer success resources to ensure they’re clearly demonstrating to clients that their financial interests are aligned with customers’ results, and not just with the initial transaction. That alignment builds the trust required for long-term expansion that benefits both parties.

The widening gap between AI innovation and enterprise adoption is real, but it’s closeable. Technology is not the constraint. The path to closing it runs directly through how software vendors show up for their customers, not just at the point of sale, but across the full journey from pilot to production to scale. Vendors who embrace that responsibility will win twice: earning enterprise trust and capturing the market share that comes with it.

Eric Newmark

Eric Newmark - Group Vice President & General Manager of IDC's SaaS, Enterprise Software, CX and Workplace Solutions Division

Eric Newmark is Group Vice President & General Manager of IDC’s SaaS, Enterprise Software, CX, and Workplace Solutions Division, which includes several teams of analysts covering SaaS, 18 enterprise application markets, software monetization, business platforms, marketplaces, and services firms focused…

The extended reality (XR) market is not the same industry it was two years ago. What was once defined by bulky headsets and gaming-first use cases has transformed, rapidly and decisively, into a market shaped by smart glasses you’d actually want to wear to the grocery store.

A market on the move

Smart glasses without displays, surged 167% year-over-year in Q1 2026, reaching approximately 2.25 million units in a single quarter. To put that in perspective: the entire category shipped roughly the same number (2.7M) units in all of 2024 than it did in the first three months of this year. That is the kind of growth that reorganizes industries.

Meanwhile, eyewear with displays tracked under IDC’s ARVR segment, encompassing Augmented Reality, Extended Reality, Mixed Reality, and Virtual Reality, grew 86% year-over-year in Q1 2026.

The message is clear: eyewear-form-factor devices are no longer the niche. They are the market.

Who’s winning right now: Q1 2026 market share

Meta continues to dominate with 69.2% market share in Q1 2026, a commanding lead built on the strength of its Ray-Ban partnership with EssilorLuxottica, the world’s largest eyewear maker, and a marketing machine that few hardware companies can replicate. The Ray-Ban Meta lineup has done something rare in consumer tech: it created a device people are genuinely unafraid to be seen wearing in public.

The rest of the competitive field remains fragmented. RayNeo captured 3.4% share thanks to its lower cost display glasses. Xiaomi held 3.1% share, fueled primarily by China shipments across its audio-first and camera-equipped models. Viture’s expansion into US retail and the launch of its Beast glasses helped the company rank fourth with 2.5% share while XREAL rounded out the top five with 2% as the company preps for its big push on the Android XR platform.

The Others category, comprising a long tail of Chinese and global brands, accounts for 19.8% collectively, a number that will only grow as more vendors enter.

CompanyQ1 2026 Market Share
Meta69.2%
RayNeo3.4%
Xiaomi3.1%
Viture2.5%
XREAL2.0%
Others19.8%

The competitive pressure building on Meta

Meta’s lead is real, but it is not impenetrable, and the challengers assembling against it are formidable.

Google enters the smart glasses race with an advantage no rival can manufacture overnight: an ecosystem already embedded in billions of lives. Gemini is already in people’s email, photos, search history, and calendars. When someone puts on a pair of Android XR glasses, the AI assistant doesn’t need an introduction. It already knows you. That depth of integration is structurally different from what Meta offers. Meta’s glasses are compelling, but they require a smartphone connection and depend heavily on Meta’s own social and advertising platform for discovery and relevance. Google, by contrast, is creating stickiness through the very services consumers already use daily.

Snap has spent a decade building something no hardware startup can buy overnight: a generation of users who think in visual, ephemeral, camera-first terms. Its Lens Studio ecosystem already has tens of thousands of developers who have spent years building AR experiences, meaning the content and creative layer for Specs arrives largely pre-built. Five generations of Spectacles hardware, sold initially at a loss and iterated quietly, gave Snap real-world learnings on optics, thermal management, and social comfort that simply cannot be shortcut. Unlike every other company entering this space, Snap has demonstrated that it can change how a generation communicates through software alone. That is a harder trick than shipping hardware, and Snap has already pulled it off once.

The Chinese vendor ecosystem, including Xiaomi, Huawei, Alibaba, and RayNeo among a growing cast of others, will apply sustained pressure on pricing and volume, particularly in Asia-Pacific markets. These vendors are not just competing on cost; they are iterating quickly, and several are developing AI capabilities in-house that could rival Western models within the forecast horizon.

What unites Google, Samsung, and Snap is a critical shared requirement: a smartphone. Meta’s Ray-Ban glasses also depend on a phone for full functionality, but Google and Samsung’s glasses will be deeply integrated with the Android XR ecosystem, leaning heavily into existing device relationships. The question is not whether you need a phone. It is whose phone, and what experience that phone unlocks.

That said, dethroning the giant that is Meta won’t come easy. Meta’s core advantage isn’t just market share; it’s distribution. The partnership with EssilorLuxottica gives Meta access to the largest eyewear retail network in the world, putting Ray-Ban Meta frames in optician shops alongside prescription lenses, not just in electronics stores. That kind of shelf presence is extraordinarily difficult to replicate. Layer on top of that a social graph of more than three billion people, an advertising business that funds aggressive hardware subsidies, and two-plus years of real-world usage data from millions of Ray-Ban Meta wearers, and Meta enters this next competitive cycle with structural advantages that go well beyond the device itself. The question is whether a head start in hardware translates into a platform moat, and that is precisely what Google, Snap, and others are betting it won’t.

The smart glasses race is no longer just about who ships the most units. It’s about who builds the most indispensable experience. Meta has the head start and the hardware momentum, but Google is entering with an AI assistant that already lives in your pocket, your photos, and your daily routine. New products from Google’s Android XR ecosystem, Snap, and a growing number of Chinese vendors will accelerate adoption by expanding smart glasses availability and familiarizing consumers with AI-first experiences, and that puts real pressure on Meta to evolve beyond hardware into a full platform play.

The road ahead: Forecast 2026–2030

The scale of what is coming is difficult to overstate.

Display-less Glasses: Volume soars, ASPs compress

IDC forecasts shipments for glasses without will reach approximately 13.6 million units in full-year 2026, growing to 27.3 million units by 2030, a compound annual growth rate (CAGR) of 18.9%. In revenue terms, the category is expected to reach $5.1 billion in 2026 and $6.4 billion in 2027, before moderating as pricing pressure intensifies.

This is where the ASP story becomes important. The average selling price (ASP) for smart glasses is approximately $376 in 2026, already reflecting the mid-market positioning of the Ray-Ban Meta and its emerging rivals. By 2030, ASPs are forecast to compress to approximately $229, a decline of nearly 40% over four years. This is not bad news; it is the hallmark of a maturing market. Falling ASPs mean more consumers can access the category, which in turn drives volume. But it also means vendors who compete purely on hardware will face margin pressure, and software, services, and AI differentiation will become the real moat.

Mixed reality: The platform bet paying off

Mixed reality, the category anchored by devices like Meta’s Quest series and ByteDance’s headsets, is forecast to grow from 3.2 million units in 2026 to 10.4 million by 2030, a CAGR of 34.4% in units and 31.6% in value. Revenue is expected to reach $7.1 billion by 2030, up from $2.4 billion in 2026. ASPs hold relatively steady, ranging from $742 in 2026 to $682 in 2030, reflecting the premium nature of these devices and the enterprise and prosumer audiences they serve.

Optical See Through (OST) glasses (augmented and extended reality): The display glasses inflection

The combined OST opportunity across augmented and extended reality represents the most dynamic segment of the XR forecast. Display glasses from companies like XREAL, Viture, and RayNeo are forecast to grow from 3 million units in 2026 to 12.2 million by 2030, a CAGR of 41.9% in units. ASPs are expected to hold in the $516 to $547 range, reflecting steady demand for quality display hardware without the extreme price compression seen in screenless smart glasses. However, the most sophisticated hardware will sell well above $1000 bringing with it the benefits of spatial computing such as 3D imagery and the ability to anchor visuals within the world.

This bifurcation of pricing is also expected to reflect real world demand as enterprise users will lean into the sophistication to offset other costs while increasing productivity. Meanwhile, consumers are likely to latch onto mid-priced products that offer simpler use cases.

What this means for the industry

The XR market is at a genuine inflection point. The technology has crossed the fashion threshold: people will wear these devices, and that changes everything. But the real competition ahead is not hardware. It is platform, ecosystem, and AI. Companies that can deliver seamless, always-on assistance through a pair of glasses that people actually want on their face will define this decade’s computing transition.

Jitesh Ubrani

Jitesh Ubrani - Director, Consumer Devices Research

Jitesh Ubrani is a Director at IDC leading a team of analysts within the Worldwide Consumer Device Trackers group, covering wearables, augmented reality (AR), virtual reality (VR), tablets, phones, PCs, gaming, and smart home devices, with a focus on market…

企业AI落地正在从“试点优先”走向“价值优先”,服务商的竞争焦点也从交付项目转向交付持续业务结果。中国AI专业服务市场正在进入由应用落地和运营能力驱动的新阶段。

中国企业级AI服务市场正在经历一次重要转向。过去,企业更关注模型能力、算力资源和试点项目;现在,越来越多客户开始关注AI能否真正嵌入业务流程,能否连接企业数据与核心系统,能否在安全合规的前提下持续产生业务价值。

国际数据公司(IDC)最新发布的《2025H2中国AI专业服务市场跟踪报告》显示,2025年下半年,中国AI专业服务市场继续提速,市场规模近 20亿美元;2025全年市场规模超过 30亿美元。但比规模增长更值得关注的是,市场驱动力正在发生变化:基础设施集成仍是重要基本盘,平台与应用服务、管理与支持服务正在成为新的增长引擎。这意味着,AI专业服务市场的竞争逻辑正在从“谁能建项目”,转向“谁能帮助客户把AI长期用好”

一、市场增长的核心信号:从“建设”走向“建设+应用+运营”

报告显示,2025H2中国AI专业服务市场规模达到近两年来的高点。其中,基础设施集成服务仍是最大板块,云、算力、网络、安全、数据中心、国产化和混合架构建设仍是企业AI服务投入的重要基本盘。

但更值得关注的是结构变化。平台与应用服务在2025H2快速增长,反映企业正在从底层环境建设转向应用现代化、数据平台建设、AI应用开发、RAG/Agent落地和业务系统改造。与此同时,管理与支持服务也呈现高增长态势,说明客户对AI应用上线后的持续运营、应用支持、安全保障和效果监控需求正在提升。

中国AI专业服务市场正在从过去以“项目建设”为中心,逐步进入“建设、应用、运营”并重的新阶段。AI正在推动专业服务从一次性项目交付,走向更长期、更持续的能力运营。

二、AI正在改变专业服务需求结构

过去,专业服务项目更多围绕基础设施部署、系统集成和应用上线展开。但AI应用进入企业场景后,客户需求变得更加复杂。企业不再只要求服务商完成系统交付,而是更关注AI能否接入真实业务数据,能否与现有业务系统和数据平台集成,能否满足权限控制、数据安全和合规要求,能否持续优化模型效果并产生业务价值。这也是平台与应用服务增长的重要原因。

同时,AI应用上线并不意味着项目结束。知识库需要持续更新,Prompt需要管理,模型调用成本需要优化,输出质量需要评估,安全风险需要监控,业务部门使用效果也需要持续跟踪。因此,AI正在推动专业服务从“一次性交付”走向“持续运营”。

三、竞争格局正在重塑:头部厂商稳固基本盘,AI与平台能力成为分化关键

从2025H2市场表现看,中国AI专业服务市场的头部厂商仍主要集中在具备云、算力、基础设施、AI平台和大型政企服务能力的企业之中。华为在基础设施集成服务中保持优势;百度在平台与应用服务中表现活跃,体现出AI平台和大模型应用落地带来的增长机会;联想、新华三、浪潮等企业依托基础设施和全栈服务能力参与市场竞争;软通动力等服务商则在系统集成、本地交付和行业客户服务中保持增长;运营商也依托云网资源、政企客户基础和本地服务能力参与相关项目。

总体来看,2025H2中国AI专业服务市场的竞争不再只是“谁能交付项目”,而是“谁能把基础设施、平台应用和持续运营连接起来”。未来市场分化的关键,将取决于服务商能否从单一项目交付,转向行业化方案、平台化工具和管理化运营。

IDC建议:服务商如何抓住转型窗口?

第一,把AI能力嵌入现有IT服务组合。

服务商不应把AI作为单独的创新实验,而应将AI能力嵌入基础设施集成、平台应用建设和管理支持服务中,形成从环境建设、应用开发到持续运营的完整服务链。

第二,从项目交付转向行业资产沉淀。

平台与应用服务的快速增长说明,客户需求正在行业化和场景化。服务商应沉淀行业知识库、RAG模板、Agent流程、数据连接器、测试集、评估指标和部署蓝图,将项目经验转化为可复制的解决方案,提高交付效率和利润率。

第三,提前布局AI管理运营服务。

管理与支持服务增长显示,客户正在为持续运营能力付费。服务商应强化AI应用监控、模型成本管理、Prompt管理、知识库更新、安全审计和业务效果评估等能力,从一次性项目收入转向持续性服务收入。

IDC认为,2025年下半年,中国AI专业服务市场规模已近20亿美元,全年市场规模超过30亿美元,按人民币口径测算已成为明确的百亿级市场赛道。这一增长不仅是短期项目回暖,更标志着企业AI建设进入新的扩张周期,市场正从传统基础设施建设,向AI驱动的平台应用建设和持续运营服务加速延伸。展望2026年,OpenClaw等智能体平台的规模化落地将进一步深刻重塑AI专业服务市场的发展路径,推动服务内容、交付模式和商业价值的全面升级,成为企业数智化转型的重要引擎。

IDC中国企业级服务研究经理张舒认为,中国AI专业服务市场正在进入从“技术验证”到“业务规模化”的关键转换期。过去企业采购AI服务,更多关注模型能力、应用演示和短期试点;未来企业将更关注服务商是否具备端到端落地能力,包括业务场景识别、数据治理、系统集成、安全合规、AI治理和持续运营。

为了更好地帮助用户了解企业与软件AI的发展动态和未来趋势,IDC正式发布《2025H2中国AI专业服务市场跟踪报告》,并即将启动《2026H1 中国AI专业服务市场跟踪》报告研究,欢迎大家与我们保持沟通交流,与IDC共同开展更多前瞻性与实践性研究。

请点击此处与我们联系

Emily Zhang

Emily Zhang - Research Manager

Emily Zhang is Research Manager for IDC’s Services technology data in China and leads IDC’s PRC IT Services research. Her coverage spans IT consulting, cloud managed services, and AI-related service offerings. Emily delivers data and insights from both tech provider…

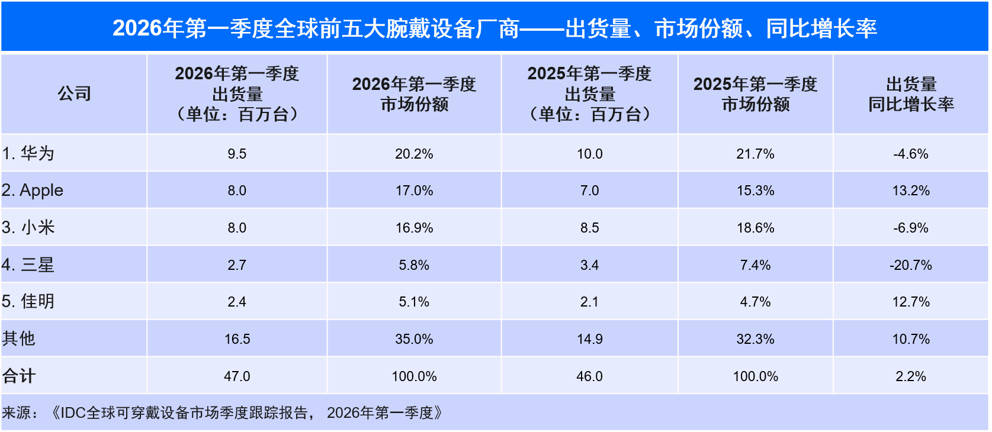
腕戴设备市场正在发生静默而深刻的结构性转折。智能手表与手环的走势分化、各价位段需求的冷热不均、区域市场之间的增长落差——这些表象背后,同一个问题是所有参与者必须回答的:当普及红利消退,增量从何而来?本文基于IDC最新发布的《全球可穿戴设备市场季度跟踪报告》,梳理2026年第一季度全球腕戴市场的三大结构性特征、头部厂商的应对策略,以及中国市场的独特发展路径。


根据国际数据公司(IDC)最新发布的《全球可穿戴设备市场季度跟踪报告》,2026年第一季度全球腕戴设备市场出货量为4,705万台,同比增长2.2%。腕戴设备市场包含智能手表和手环产品。其中,全球智能手表市场出货量3,703万台,同比增长4.8%。手环市场出货量1,002万台,同比下滑6.1%。腕戴产品发展背后,全球市场呈现出哪些特点?头部厂商表现如何?中国市场又将呈现哪些异同?本文将为您一一解读。

2026一季度全球腕戴市场发展的三大特点

根据IDC跟踪报告,2026年一季度全球腕戴市场发展呈现以下三个显著特点:

特点一:手表走强,手环疲软

智能手表凭借功能升级稳步增长,部分分流手环用户。手环受去年需求提前透支、存储成本抬升影响,再加入门手表价格下探抢占市场,需求持续承压,整体走势偏弱。

特点二:价位结构升级,入门稳、高端旺

大环境承压下,百元美金以内入门产品依靠刚需稳住出货量;300 美元以上高端机型依托软硬件迭代、健康医疗及AI功能升级,消费升级需求逐渐释放,高端价位段增速突出。

特点三:区域发展分化

中国凭借新品发布与电商促销,成为全球增长主力;美国、拉美受益换新与渗透率提升小幅增长,其他地区受经济影响需求表现平淡。

2026一季度全球腕戴市场Top 5厂商表现

华为

2026 年一季度华为腕戴产品全球出货量登顶。华为时隔5年推出 WATCH GT Runner 2,深耕专业跑步赛道;Ultimate 2 高尔夫版满足进阶人群的专业需求;手环 11 系列补齐入门价位空档。全品类阶梯矩阵落地,完善价格与功能布局,稳固华为穿戴出货领先优势。

Apple

2026年一季度中国市场成为苹果智能手表全球增长核心驱动力。品牌提前落地多轮促销活动有效拉动终端销量;产品高端定价优势明显,可更大程度消化上游元器件涨价带来的成本压力,对冲供应链紧缺负面影响,支撑中国市场业绩稳步上行。

小米

2026年一季度小米智能手表表现优于手环品类。品牌落地 S5 系列新品,持续加大中高端 Watch 5 铺货力度,稳步向上优化产品结构。中高端机型逐渐放量,小米加速优化产品结构,逐步向中高端市场纵深布局。

三星

三星全球主推 Galaxy Watch8 及 8 Classic,但整体出货受内部战略调整小幅收缩。欧美成熟市场需求承压,中东、非洲等新兴市场依托品牌口碑与渗透率提升实现小幅增长,成为品牌现阶段为数不多的增量市场。

佳明

佳明坚守专业户外、运动细分赛道,深耕垂直用户巩固专业产品壁垒;同时加速产品迭代、拓宽大众消费产品线。配合各地阶段性营销与促销落地,品牌兼顾专业与大众市场,在多个区域实现出货同比增长。

2026一季度中国市场发展的三大特点

IDC报告指出,2026年第一季度中国腕戴市场出货量1814万台,同比增长3.5%;其中成人智能手表出货量888万台,同比增长15.3%,儿童手表出货量442万台,同比增长22.4%,手环市场出货量483万台,同比下滑22.2%。

特点一:入门价位补位扩容,五百元档市场回暖

500 元以下成人智能手表一季度出货量回暖。头部品牌产品迭代逐步撤出该价格带,中小品牌顺势优化产品配置填补空白。上游存储成本抬升环境下,该档位机型性价比凸显,精准承接入门刚需,拉动该价位稳步回暖。

特点二:渠道分化凸显,线上增速领跑线下

产品成熟带动消费者选购趋于理性,用户习惯线上比价筛选机型。叠加直播、多平台大促等多元电商业态持续扩容,线上渠道出货增速显著跑赢线下。线下侧重体验成交,增长相对稳健,线上已成为拉动大盘增量的核心载体。

特点三:产品精细化发展,功能人群多元细分

市场开始逐渐尝试跳出同质化堆砌,逐步走向场景与用户分层。更具有针对性的女性向和青少年设计的产品更多出现,在全智能、专业健康、专业运动、日常健康和轻运动等维度打造差异化卖点,围绕细分需求定制产品,精细化细分成为行业明确发展趋势。

针对技术供应商和采购方的建议

建议一:产品分层精细化布局,打造差异化竞争壁垒

厂商应搭建阶梯化、差异化产品矩阵,规避同质化与低价内卷。面对存储成本上涨压力,各价位段需优化配置与定价策略。中小厂商依托优质体验稳固入门市场,头部品牌深耕高端健康、AI、运动功能迭代。通过场景、功能、外观多元差异化设计,覆盖多人群需求,筑牢产品竞争壁垒。

建议二:双线渠道协同布局,高效盘活存量增量市场

厂商需优化线上线下双线渠道协同布局,加大电商、直播等线上资源投入,依托平台优势快速走量、盘活存量。线下门店重点聚焦高端机型体验、售后服务与高价值用户转化,打造线上引流、线下提质增收的良性渠道体系。

建议三:区域市场差异化深耕,分散经营风险挖掘增量

厂商应实施差异化区域运营策略,平衡市场规模与盈利水平。欧美成熟市场避开低价内卷,深耕专业运动、健康垂直圈层守住利润;积极开拓拉美、中东非等新兴市场,凭借性价比快速提升渗透率。同时深耕中国本土市场,依托新品迭代与电商促销持续激活换新增量。

分析师观点与行业建议

IDC认为,全球腕戴行业已告别普及放量期,正式迈入存量精细化竞争阶段。增量不再依靠全民新机普及,转而由产品升级、细分人群、区域下沉三大逻辑驱动。成本波动加速行业洗牌,倒逼品牌放弃低价同质化内卷,依托价位分层与场景细分挖掘新增量,未来品牌综合产品架构、渠道与区域布局的能力将成为拉开份额差距的关键。

延伸阅读与沟通:

如需了解更多IDC相关研究或进一步与我们沟通,请点击此处与我们联系。我们将安排专人与您对接,为您提供定制化的市场洞察与咨询服务。

Sophie Pan

Sophie Pan - Research Director, Client System Research

Sophie Pan is a research director for the Client Systems Research team at IDC China. She is responsible for emerging technology device research, including wearable devices and smart home devices. Sophie has a deep understanding of the landscape and ecosystem…

Although WWDC is a developers’ conference, this year’s keynote was primarily a statement of intent about Apple’s future and demonstration of its AI credibility.

The most important announcement this year was the new Siri AI. Apple rebuilt it from the ground up, trying to make AI feel native, useful and invisible across devices people already own. The winning AI experience for consumers will not be the loudest or most technically complex. It will be the one that understands context, respects privacy, works reliably across apps, and reduces friction without forcing users to change behavior.

Apple has rarely been about being first to a trend. It has been about waiting for the ability to embed technology far enough into hardware and silicon to change how people actually behave. Much has been made about Apple being behind on AI, and the company certainly had failed to deliver on promises made back in 2024. But consumers are wary of AI, and what the company demonstrated at WWDC this year seems ready to meet them where they are today.

What is the new Siri AI?

The center piece is a rebuilt Siri, dubbed Siri AI, and the detail that matters most is what sits underneath it. Apple was emphatic on one point: this third generation of foundation models is its own work, trained on its own data. Yes, the company worked with Google to develop the model family, and Apple refined four of the five models using outputs from Gemini’s frontier models. But the models, the training data, and the privacy architecture all belong to Apple. And while some of the broader Apple Intelligence capabilities, such as image generation, will run on Google’s Cloud Platform on NVIDIA chips, none of the new Siri AI runs on Gemini’s chat infrastructure.

The new Siri AI also arrives as a standalone app across iPhone, iPad, Mac, and Vision Pro with an iMessage-style interface, persistent conversation bubbles and a full chat history synced through iCloud. Users can attach images and documents and switch between quick voice commands and a deeper chatbot mode. The visual signature has changed too. Instead of the edge glow that has signaled Siri for years, the assistant now lives inside the Dynamic Island, expanding the pill to show prompts and a glowing search state. The “All Systems Glow” tagline was a tease of exactly this. The effect is that Siri AI feels part of the hardware rather than something that hijacks the screen.

What can Siri AI do?

One of the stronger Siri AI demos is write with Siri AI. Startups like WisprFlow have built entire businesses around helping people dictate clean text on an iPhone instead of thumbing out long passages. Siri AI goes further, picking up on your writing style, proofreading on its own, and producing complete drafts. Assuming it performs the way Apple showed it, the company has pulled off a familiar trick: baking in for free the kind of capability users have been paying outside vendors to get.

Siri AI appears to finally do what Apple suggested it would be capable of doing back in 2024. It reads personal context across emails, photos, messages and files, understands what is on screen, and executes multi-step tasks across apps. That personal context is a unique advantage that Apple has over competing AI services. While services such as OpenAI’s ChatGPT and Anthropic’s Claude are collecting contextual data on their users now, Apple has that data going back many years. It’s a true advantage, but one that Apple must leverage carefully as it continues to hammer on its privacy and security promises.

Understandably, then, Apple is being cautious with this Siri AI rollout. It is shipping the new feature as a preview, gated behind a waitlist even among those receiving the live developer betas. We expect many of the advanced parts of the stack to arrive across later 27.x updates rather than at launch.

What other OS improvements did Apple announce?

Beneath Siri AI, the various OS updates are where most users will experience benefits. Across each device Apple has worked to enhance app launches, speed up performance, and smooth animations. It added a slider so users can change the opacity of the Liquid Glass interface. And on macOS 27, specifically, it addressed a wide range of complaints around last year’s additions, from fixing the corner radius of windows to removing extraneous menu icons.

Safari gains Organize Tabs, which sorts open tabs into topics such as shopping, travel and work. Shortcuts have been rebuilt so you can describe a multi-step automation in plain language, and have it assembled for you, which finally makes the feature accessible to people who were never going to script it.

The camera and photo upgrades in iOS 27 are where Apple Intelligence becomes very tangible and will likely get the fastest recognition from consumers outside of Siri. Photos adds two generative tools: Extend, which fills in scenery beyond the original frame, and Reframe, which shifts the perspective of spatial photos after capture. The Camera app gains a Siri AI-powered Visual Intelligence mode that reads a nutrition label and logs calories and macronutrients straight into Health or pulls a phone number and address off a business card into Contacts. Wallet can now scan a physical ticket or membership and generate a digital version, and a new bill-splitting feature tied to Apple Cash lets you photograph a receipt, assign items to people, and send payment requests with tax and tip handled automatically, approved from your wrist if you like. The bill-splitter launches in the United States first because of the Apple Cash dependency.

What is Apple’s AI Strategy?

Apple’s strength has never been to ship new technologies for the sake of shipping. It has been to package complex technology into experiences that feel polished and trusted. This year’s Apple Intelligence announcements follow that logic. The new Siri AI, with a richer understanding of the user, smarter Shortcuts, visual intelligence in the camera, improved writing and image tools, and more capable on-device intelligence all point to the same strategic direction: Apple wants AI to become part of the operating system, not a separate destination only available through an app.

Siri AI is central to that ambition. For years, voice assistants were useful but limited. They answered basic questions, controlled simple settings and handled routine commands. What Apple is now proposing is genuinely different: an assistant that can understand what is on screen, read what is actually happening across apps, and execute multi-step actions on behalf of the user. If Apple delivers this well, Siri AI stops being a feature and becomes a new interaction layer for all of Apple’s current devices and eventually future categories of hardware.

Will Siri AI improve Apple’s long term growth or upgrade cycle?

The iPhone remains the center of Apple’s ecosystem, but growth increasingly depends on making the installed base more valuable, more loyal and more difficult to leave. A better Siri AI and a more capable Apple Intelligence layer make Apple devices harder to leave by making them work together in more personal and contextual ways. A Siri AI experience that works the same way across every device is an advantage other vendors will find difficult to replicate and gives Apple the upper hand. 

It also gives Apple a stronger upgrade argument, especially as the best AI experiences will depend on newer hardware. The argument is even more pronounced for iPhone 15 and older users, who lack all access to Apple Intelligence.  Any users that may have resisted upgrading due to inflationary pressures and economic uncertainty have a compelling argument to upgrade.  For Apple this means continued upgrade momentum in 2026, despite a very strong upgrade cycle last year.

The announcements around Apple platforms reinforce this point. The operating systems are not being reinvented visually this year. They are being refined around performance, usability and embedded intelligence. That is the right move. After a major design transition, Apple needed to show maturity. The company is signalling that AI will improve everyday tasks: managing information, searching, automating workflows, editing photos, understanding documents, using the camera, and moving between apps with less effort.

Why is 2026 a pivotal year for Apple?

The bigger strategic question is execution. The AI features Apple showed this week weren’t groundbreaking. And the word “agentic” was rarely uttered. Apple isn’t chasing the hype around AI; it’s focused on delivering a polished AI experience rather than an experimental one. Consumers will not judge Apple Intelligence by model sizes, partnerships or technical architecture. They will judge it by whether Siri AI understands them, whether actions work, whether personal context feels useful rather than intrusive, and whether the experience is consistent across devices.

This is therefore a high-stakes year for Apple. If the new Siri AI works as shown, Apple Intelligence could become one of the most important ecosystem upgrades since the App Store matured into a services platform. It would deepen loyalty, increase the value of newer devices and reposition Apple’s operating systems around personal intelligence.

But the margin for disappointment is narrow. Apple has chosen a user-first AI narrative. Now it must deliver against it. The keynote created confidence; the real test will come when these features reach millions of users. Delivering on what was shown on stage is critical, because for Apple the risk is not that users misunderstand the strategy. The risk is that they understand it perfectly, try it, and feel the experience falls short. However, the announcements today make me feel that Apple is ready to excite its users with its intelligence capabilities.

How does WWDC position Apple for leadership transition to John Ternus?

This was also Tim Cook’s last WWDC keynote, and what he announced at every single WWDC keynote over the years reflected his leadership: disciplined, ecosystem-first, privacy-led, and making technology useful at scale. Apple has never been about being first to a trend. It has been about waiting until technology is embedded far enough into hardware and silicon to change how people actually behave. This is what Apple showed at WWDC26.

This is also a defining platform moment for John Ternus as he prepares to take over as CEO. He will inherit a company with one of the strongest hardware platforms in the world, but the next chapter will be defined by how intelligently that hardware works for users. For a leader with deep hardware DNA, the opportunity is to make Apple Intelligence feel inseparable from Apple devices.

WWDC 2026 gives Ternus a clear strategic runway: more personal devices, more contextual software, more intelligent services and a tighter link between silicon, hardware and AI. If Apple delivers the experience with the reliability, elegance and trust users expect, this could be remembered as the moment Siri AI and Apple Intelligence moved from the background of Apple’s product lineup to the center of its future.

Francisco Jeronimo

Francisco Jeronimo - VP, Data and Analytics, Devices, IDC EMEA

Francisco Jeronimo is VP for Data and Analytics at IDC EMEA. Based in London, he leads the research that covers mobile devices, personal computing devices, emerging technologies and the circular economy trends across EMEA. His team delivers data on personal…
Tom Mainelli

Tom Mainelli - Group Vice President, Device & Consumer Research

Tom Mainelli heads the Device & Consumer Research Group, overseeing a wide array of hardware and technology categories catering to both home and enterprise markets. His team's research spans PCs, tablets, smartphones, wearables, smart home devices, thin clients, displays, and…
Nabila Popal

Nabila Popal - Senior Director, Data & Analytics

Nabila Popal is Senor Director with IDC's Data & Analytics team, specializing in Mobile Phones, PC Monitors and other consumer devices.  Ms. Popal is responsible for the global research and quality and timely delivery for her respective technologies, coordinating with regional…

In my last blog, I explained that when your CMDB is a mess, AI makes that mess happen faster. The same principle applies when your Managed Service Provider (MSP) gets there first. MSPs are now moving fast. AI is now embedded across service delivery operations. IDC research shows how AI is shifting IT services away from labor-led delivery toward platform-led, outcome-based models. The smarter MSPs get to know your environment, the harder it becomes to challenge their pricing.

When MSPs deploy AI across service delivery, their per-unit costs fall. But contract rates rarely follow. Buyers who maintain an independent, cost-enriched CMDB can verify MSP-reported usage, identify idle resources, and negotiate from evidence rather than estimates. The good news is that the same data foundation that protects you in IT Service Management can also protect you commercially.

What MSPs are actually deploying

Every major MSP now has an AI platform. The table below shows what the leading providers are running and what it means for buyers.

ProviderPlatformWhat It Does
AccentureAI Refinery for IndustryBuilds and deploys industry-specific AI agent solutions using NVIDIA’s AI stack, now targeting over 50 solutions across telecommunications, financial services, and insurance.
AtosPolaris AIDelivers agentic AI capabilities for IT engineering and business functions.
CapgeminiGenAI OperationsAI-powered service desk and infrastructure intelligence. In 2026, Capgemini joined OpenAI’s Frontier Alliance to build and scale agentic AI workflows across enterprise operations.
DeloitteZora AIAgentic platform for business finance functions, leveraging NVIDIA AI.
DXC TechnologyOASISConnects the entire IT estate into a single trusted view, using AI agents and human expertise to anticipate issues and act before they affect the business.
EYEY.ai Agentic PlatformLeverages NVIDIA AI to enhance tax, risk, and finance operations.
FujitsuKozuchi AI AgentEnhances operational productivity across managed infrastructure contracts.
IBMConsulting Advantage / watsonx OrchestrateDeploys AI agents across HR, finance, and IT workflows, with a catalog of over 150 pre-built domain-specific agents and multi-agent interoperability across SAP, AWS, and other enterprise platforms.
InfosysAgentic AI Foundry (part of Infosys Topaz)Published case data shows 30–40% reductions in ticket volume for specific engagements.
KPMGKPMG VelocityAI-powered business transformation platform built for consultants.
KyndrylAgentic Service ManagementCombines a maturity model, structured assessments, and implementation blueprints to help enterprises move from traditional service operations to autonomous, intelligent workflows at scale.
McKinseyLegacyXAccelerates legacy infrastructure modernization using agentic AI.
PwCAgent OSA new operating system for orchestrating AI agents across enterprise functions.
TCSWisdomNextEnterprise AI platform delivering automation across managed services delivery with integrated AI orchestration capabilities.
WiproWeGA Studio / WEGAProvides pre-built accelerators, domain frameworks, and agentic AI toolkits across software engineering, cloud, data, and enterprise applications, with NVIDIA AI Enterprise integrated throughout.

This list is not intended to be exhaustive.

Agentic AI refers to AI systems that can autonomously plan and execute multi-step workflows. They do not just generate responses; they act on them. IDC research confirms that leading platforms now share a common architecture covering agent orchestration, model services, knowledge management, enterprise integration, and governance. This is no longer experimental. It is becoming the standard delivery model.

For buyers purchasing the same services under existing contracts, the commercial question at renegotiation is straightforward: if your MSP’s delivery costs are falling, are your contract rates falling with them? In most cases, the answer is no. MSPs are actively working to demonstrate additional value to justify maintaining or increasing their rates, and the ones doing it well have the data to back it up. Buyers who lack independent data do not.

What this means for managed services pricing

Factors pushing prices up

Agentic platforms are enabling always-on, outcome-based service models, which support premium pricing for higher-value outcomes, particularly in business process services. Demand is also growing for orchestration, governance, and multi-agent operations across IT and business functions. MSPs are also expanding into new customers and workloads, including mid-market segments that were previously too expensive to serve.

Importantly, not all customers will adopt premium agentic services. MSPs need to recoup their platform investment costs across a broader base, which adds further upward pressure on pricing across the board.

Factors pushing prices down

AI agents now handle monitoring, triage, root cause analysis, and remediation within defined boundaries, reducing reliance on people for routine tasks. Platform efficiencies compress the cost per unit of work, and performance in predictable scenarios is becoming more consistent.

Net impact for MSPs

AI platforms are compressing MSP delivery costs while enabling premium pricing for outcome-based services. The net result is stronger margin for MSPs, and a real commercial case for buyers who can prove what they’re actually using.

Important context for IT buyers

AI platforms are not free for MSPs to build and run. Infrastructure, integration, specialist skills, and ongoing maintenance all carry significant costs. Buyers should find out whether AI investment is listed as a separate line item or is absorbed into base rates at renewal.

The commercial model is also shifting.

Traditional time-and-materials and consumption-based pricing do not map well to how agentic services are actually delivered, which is one reason outcome-based models are gaining ground. Buyers who understand this shift and write contracts that reflect it will be better placed to share in the productivity gains, rather than fund them.

Where IT buyers are still losing ground

Three problems consistently arise at contract renewal.

1. Accepting the MSP’s usage data

Most organizations have no independent, current view of their own environment. IDC PeerScape research found that organizations regularly discover assets MSPs keep billing for even after they leave active use. Old virtual machines, unallocated storage, and devices that were never decommissioned are common examples. When the MSP’s AI platform generates usage reports, most buyers have no external check, so they accept the numbers.

2. Paying for unused infrastructure

In one financial services organization I worked with, a pre-renewal audit found 50 virtual machines switched off for more than three months, and 15 terabytes of storage with no active application attached. The MSP was billing for all of it. Removing those items from scope saved 48,000 euros a year.

3. No basis to challenge per-unit pricing

MSP contracts priced per virtual machine, per device, or per terabyte are only negotiable if the buyer can independently verify what is actually in use. Without that, the MSP’s numbers go unchallenged. This is also one of the reasons outcome-based pricing deserves serious consideration. When delivery is driven by AI agents rather than headcount, per-unit pricing often fails to reflect the true cost or value of the service.

The answer is still the same

IDC’s research on agentic AI in services concludes that the providers who win will be those who prove value transparently and build trust through governance, portability, and accountability. Buyers have a role to play in demanding exactly that.

Build an independent source of truth. A well-maintained, cost-enriched CMDB is your foundation.

Run a pre-renewal audit. Start 90 to 120 days before contract expiry, using independent discovery tools such as ServiceNow Discovery or Dynatrace. This lets you verify MSP-reported usage, identify idle resources, and challenge billing for unused infrastructure before you reach the negotiating table.

Get the contract language right. Include the right to conduct your own audits, tie billing to verified active use, and build in scope reduction mechanisms. Ask directly how AI deployment costs and efficiency gains will be shared. Providers who cannot answer that question clearly are worth watching.

Push for outcome-based models, and define outcomes broadly. Buyers who request transparent pricing, clear ownership terms, and outcome-based commercial structures will be better placed to capture value rather than pay for it. But make sure the outcomes you measure go beyond technical metrics. An MSP can meet every SLA target and still fail to deliver real business value. Build business outcomes, not just service desk targets, into the contract from the start.

The bottom line

IDC forecasts cumulative AI economic value of $22.5 trillion between 2025 and 2031. The MSPs listed here are investing heavily to capture their share of the market. The platforms they are building are not just delivery tools. They are becoming the primary way MSPs own the workflow and outcome layer in managed services.

IT buyers with accurate, independent data about their own environments are in a much stronger position to participate in that value rather than fund it. An accurate, cost-enriched CMDB is not an IT housekeeping exercise. In the age of AI-driven managed services, it is a commercial imperative.

Tom Collins - Senior Consultant, Global IT Sourcing & Benchmarking Practice - IDC

Tom Collins is a Senior Consultant in IDC's Global IT Sourcing and Benchmarking practice, advising organizations on IT cost management, sourcing strategy, and technology procurement.

The way business buyers find and evaluate solutions has changed more in the last two years than in the previous two decades. The arrival of AI-powered search hasn’t just added a new channel. It has reorganized where discovery happens, who shapes the shortlist, and whether a brand even gets a chance to be seen. 

During a recent IDC expert panel, Addressing the Pipeline Conversion Gap, analysts examined the shift from traditional ranked search to AI-facilitated discovery and beyond. 

You’ve spent years perfecting your Google rank. Your buyers just stopped using Google.” — Roger Beharry Lall, Research Director, Advertising Technologies and SMB Marketing Applications at IDC

To capitalize on this new mode of discovery and capture the market before competitors, CMOs, digital marketing leaders, demand gen managers, and B2B marketers must pivot from search engine optimization (SEO) to a new discipline: answer engine optimization (AEO). 

AEO is not SEO with a new name 

AEO and SEO operate on fundamentally different logics. The SEO pipeline was built on a clear sequence: optimize pages for keywords, earn backlinks to build domain authority, and win placement in a ranked list on Google or Bing. The buyer clicks your link. From that point forward, you control the experience. 

AEO, also called generative engine optimization (GEO), operates entirely differently. Large language model (LLM) chatbots like Gemini or ChatGPT synthesize an answer before the buyer even sees the options. Brands that get cited in AI-generated responses aren’t necessarily those with the best keyword density. They’re the ones with a deep, authoritative, and interconnected content infrastructure. 

In SEO, keywords signal relevance. In AEO, context and content depth establish authority. An LLM evaluating whether to cite your brand isn’t scanning meta titles. It’s assessing whether your information ecosystem is comprehensive enough to trust. 

Treating AEO as an extension of existing SEO practice is the most common and most costly mistake marketers are currently making. 

Most organizations aren’t ready for the shift 

According to IDC Research Director Roger Beharry Lall, only 35% of organizations have enterprise-wide content capabilities. That means nearly two-thirds of B2B brands are structurally unprepared to succeed in the AEO environment. 

Enterprise-wide content capability means more than a well-maintained website. It means product information management (PIM) systems that are integrated and externally surfaceable. Engines must be able to parse your digital asset management (DAM) libraries. Knowledge bases and technical documentation need to be connected to public-facing repositories. 

Most marketing teams have optimized their digital presence for ranked search engine performance. AEO requires something more: deep connection layers into your full data stack, exposed to the platforms buyers are now using to form their views. That demands cross-functional reach that most demand gen teams haven’t had to develop before. 

And that’s only the half you can control. 

Reputation is the new discoverability asset 

The “dark funnel” describes the portion of B2B buyer discovery that happens inside AI systems, beyond a brand’s direct control. In the traditional B2B discovery model, channels like communities, social, PR, ratings and reviews, and advertising reached buyers directly. In the emerging model, those same signals flow through AI first. The buyer receives a synthesized view of your brand, one that draws on everything the internet says, not just what lives on your domain. 

Buyers asking an LLM about your company aren’t just getting your FAQs and product specs. They’re getting a response built from analyst citations, peer review websites, press coverage, forum discussions, and social media. All of it beyond your control. 

For CMOs, the implication is significant. Reputation management, earned media, analyst relations, and community presence are no longer solely the domain of PR. They are the foundations for AEO. 

The window for early movers is real 

Most organizations haven’t begun to address AEO, which is precisely what makes this moment significant. The brands investing in it now are doing so before the field gets too crowded. That won’t be true for long. 

In IDC’s conversations with CMOs this year, the organizations moving on AEO now share one trait: they’re planning 12-month content infrastructure investments, not 90-day campaigns. AEO isn’t a campaign. It rewards consistent, long-term investment in how a brand shows up across the information environments buyers use, not just the ones you control. 

One area to watch closely: in-LLM advertising. The field is still in its early stages, but all the major platforms are working out how to monetize their models. When they do, the data a user prompt carries, who the buyer is, what problem they’re solving, how urgently they need it. That data will give advertisers a level of unprecedented targeting precision, at exactly the moment a purchasing decision is beginning to form. 

When advertising models mature, they have the potential to shift meaningful control back to the CMOs and marketing leaders who are positioned to capitalize on it. 

Fixing the funnel for the age of AEO 

The pipeline conversion problem doesn’t start at the qualification stage. It begins the moment a buyer asks an AI chatbot which vendors to consider and your brand doesn’t appear in the answer. Fixing the bottom of the funnel matters. But the organizations that will succeed in the AEO era are those shining a light on the dark funnel and investing in discoverability at the top. 

IDC’s latest expert panel explores how AI is reshaping buyer behavior across discovery, evaluation, and purchase, and what marketing and revenue leaders must change to remain competitive. 

Interested in exploring more of Roger Beharry Lall’s research on AI-era demand generation? Contact IDC today. 

IDC - -

International Data Corporation (IDC) is the premier global market intelligence, data, and events provider for the information technology, telecommunications, and consumer technology markets. With more than 1,300 analysts worldwide, IDC offers global, regional, and local expertise on technology and industry opportunities and trends in over 110 countries. IDC’s analysis and insight help IT professionals, business executives, and the investment community make fact-based technology decisions and achieve their key business objectives.