Work in 2026 is being rewired around human-AI teams, where people who learn to collaborate with intelligent systems are gaining a clear edge in productivity, creativity, and career growth. IDC’s latest FutureScape and Future of Work insights show that this is no longer a distant trend but the operating reality for leading organisations worldwide.

The new shape of work

According our 2026 Futurescape for the AI-enabled Future of Work around 40% of roles in the G2000 will involve direct engagement with AI agents by 2026, fundamentally reshaping how entry, mid-level, and senior jobs are designed. In Europe specifically, we expect around 70% of new positions to be directly influenced by AI, blending technical fluency with human-centred capabilities like problem solving, empathy, and domain expertise.

AI is simultaneously and subtly absorbing much of the background work. Our analysis suggests AI tools can save workers over 40% of their typical workday, with IT workers gaining up to 45% of their time back as routine tasks are automated. Instead of spending hours on status reports, basic analysis, or rote documentation, employees can focus more on designing solutions, making decisions, and collaborating with customers and colleagues.

Agents as instruments, not co-workers

One of our most important messages though is that AI agents should be treated as instruments that extend human capability, not as synthetic co-workers to be managed like people. When AI is framed as a powerful tool in a human-led process, organisations are less likely to over-automate and more likely to invest in skills, governance, and thoughtful workflow redesign.

This mindset shift is already visible in how leaders talk about AI “co-pilots” across development, operations, and knowledge work. We predict  that as agentic AI matures, organisations that focus on measuring and improving AI–human collaboration, rather than just raw productivity, will see margin gains of up to 15% by the end of the decade.

The skills crunch: $5.5 trillion on the line

The biggest drag on this transformation is no longer the technology but the skills to use it well. Our data shows that over 90% of global enterprises will face critical skills shortages by 2026, with AI-related gaps alone putting up to $5.5 trillion of economic value at risk through delays, missed revenue, and quality issues. Yet in our Global Future of Work Decision Maker only about a third of organisations say they are fully ready for AI-driven ways of working, and just a similar share of employees report receiving any AI training in the past year.

This imbalance is already reshaping labour markets. The 2025 IDC Employee Experience survey shows that that 66% of enterprises are reducing entry-level hiring as they deploy AI, and 91% report roles being changed or partially automated. Routine-heavy junior tasks are disappearing fastest, while demand grows for roles that can design, supervise, and continuously improve AI-infused workflows.

How to ride, not resist, the wave

For leaders and professionals, the 2026 question is not “Will AI take my job?” but “How quickly can my organisation and my skills adapt to human–AI collaboration?”. Our research into AI, automation, and Future of Work points to a few practical priorities that separate frontrunners from the rest.

  • Build AI literacy for everyone, not just specialists: core skills now include prompt design, interpreting AI output, and knowing when to override or escalate decisions.
  • Redesign roles around human strengths: shift job descriptions toward judgment, creativity, relationship-building, and cross-domain problem solving, with AI handling repeatable analysis and orchestration.
  • Invest in trustworthy data and governance: companies that neglect high-quality, AI-ready data will see productivity fall behind as they struggle to scale agentic solutions.
  • Measure collaboration, not just output: by 2029, organisations that track and optimise human–AI collaboration are projected to enjoy up to 15% higher margins than those that chase automation alone.

Work has been rewired, but the most valuable node in the system is still the human at the centre of an intelligent network of tools, agents, and collaborators. In 2026, the winners will be those who treat AI not as a threat or a crutch, but as a force multiplier for distinctly human ambition.

To watch our EMEA FutureScape predictions presentation, click here.

If you have any questions, please drop them in this form.
Meike Escherich - Associate Research Director, European Future of Work - IDC

Meike Escherich is an associate research director with IDC's European Future of Work practice, based in the UK. In this role, she provides coverage of key technology trends across the Future of Work, specializing in how to enable and foster teamwork in a flexible work environment. Her research looks at how technologies influence workers' skills and behaviors, organizational culture, worker experience and how the workspace itself is enabling the future enterprise.

By 2028, 60% of enterprises will collaborate on data through private data exchanges or clean rooms, according to IDC’s 2026 FutureScapes predictions. This shift isn’t just a technical evolution—it’s a strategic one.

Why Data Collaboration Matters Even More Now

For years, we’ve called data the foundation of digital business. AI needs more and more data ‘fuel’ to train models, to ground outputs and to generate process and enterprise-specific responses. No one enterprise can create – or even independently curate – all the data it needs. It is time to lean into ecosystems (and data providers) who can expanding value through partnership. With new tooling this data is accessible securely and transparently between organizations in environments where governance is built in and privacy is preserved.

AI Demands Better Data

Generative and agentic AI systems thrive on diverse, contextual, high-quality data. Private data exchanges and clean rooms are emerging as the bridge between innovation and regulation—spaces where enterprises collaborate responsibly without exposing sensitive information. As highlighted in IDC’s Worldwide Data and Analytics 2026 Predictions, these environments are becoming essential bridges between innovation and regulation—spaces where collaboration is not only possible, but also safe.

Real-World Examples

  • Healthcare: Providers combine anonymized data sets to accelerate breakthroughs in personalized medicine.
  • Finance: Institutions partner to improve fraud detection while maintaining customer confidentiality.
  • Retail: Brands join forces to understand customers holistically, creating richer experiences without compromising trust.

A Mindset Shift

This isn’t just about technology—it’s about rethinking data strategy:

  • From owning all the data → to identifying the right data partners
  • From guarding information → to governing it
  • From isolation → to collaboration

Advances in privacy-enhancing technologies make this possible, turning fragmented information into collective intelligence.

Lead With Trust

Success in data collaboration depends on transparency, shared principles, and clear accountability. Organizations that invest now will strengthen AI outcomes and help define ethical, interoperable data standards for the next decade.

The goal isn’t just to manage data—it’s to make it meaningful.

In the agentic AI era, no organization operates alone. The future belongs to those who share wisely.

Lynne Schneider - Research Director - IDC

Lynne Schneider is Research Director leading IDC's Data Collaboration & Monetization, and Location & Geospatial Intelligence market research and advisory practices. Ms. Schneider's core research coverage in DaaS includes data sourcing and delivery services from traditional and emerging data providers along with evolving data aggregation and dissemination platforms. The breadth of coverage includes services that enable an organization to externally monetize data generated as part of the organization's ongoing operations, value-added information derived from this data, and the marketplace for combining data with other solutions. This research analyzes the supply and demand side business and technology trends of this emerging category.

In late 2025, the global semiconductor ecosystem is experiencing an unprecedented memory chip shortage with knock-on effects for the device manufacturers and end users that could persist well into 2027. DRAM prices have surged significantly as demand from AI data centers continues to outstrip supply, creating a supply/demand imbalance. 

IDC was monitoring the memory situation as we prepared our November device forecasts, and we factored them into the update. The situation, however, has become more acute since publishing, and we feel it’s important we address the situation. Although we are maintaining our official forecasts as the situation is still evolving, we will offer here two downside risk scenarios that may play out in two critical markets: Smartphones and Personal Computers. 

What’s causing the shortage? The memory market is at an unprecedented inflexion point, with demand materially outpacing supply.  For an industry that has long been characterized by boom-and-bust cycles, this time is different.  The rapid expansion of AI infrastructure and workloads is exerting significant pressure on the memory ecosystem.  These AI workloads require large amounts of memory, and the shortage, in part, is driven by a reallocation of manufacturing capacity away from consumer electronics toward high-margin memory solutions to support AI. Instead of expanding conventional DRAM and NAND used in smartphones, PCs, and other consumer electronics, major memory makers have shifted production toward memory used in AI data centers, such as high-bandwidth (HBM) and high-capacity DDR5. This has restricted the supply of general-purpose memory modules and driven up prices across the board. 

AI servers and enterprise environments require far more memory per system than consumer devices, so the AI build-out is pulling a disproportionate share of global capacity and creating shortages, as suppliers prioritize orders from hyperscalers and OEMs building AI servers. That dynamic has left less DRAM available for consumer devices, exacerbating price pressure in a tight market.  

However, this is not just a cyclical shortage driven by a mismatch in supply and demand, but a potentially permanent, strategic reallocation of the world’s silicon wafer capacity. For decades, the production of DRAM and NAND Flash for smartphones and PCs was the primary driver for production. Today, that dynamic has inverted. The voracious demand for HBM by hyperscalers, such as Microsoft, Google, Meta and Amazon, has forced the three biggest memory manufacturers (Samsung Electronics, SK Hynix, and Micron Technology) to pivot their limited cleanroom space and capital expenditure towards higher margin enterprise-grade components. This is a zero-sum game: every wafer allocated to an HBM stack for an Nvidia GPU is a wafer denied to the LPDDR5X module of a mid-range smartphone or the SSD of a consumer laptop. 

As a result, IDC expects 2026 DRAM and NAND supply growth be below historical norms at 16% year-on-year and 17% year-on-year, respectively.  

The Crisis in the Devices Market 

The result of this supply/demand imbalance is twofold: DRAM and NAND/SSD prices have risen sharply in recent months, and the availability of these components is limited, forcing device manufacturers to navigate a fluid situation. 

The Potential Smartphone Market Impact 

The global smartphone market, particularly Android manufacturers, is facing a threat in 2026. The industry’s decade-long trend of democratizing specs by bringing flagship features to affordable smartphones is reversing.  

The cost structure of a smartphone is heavily dependent on the memory used. For a mid-range device, memory can represent 15-20% of the total bill of materials (BOM), while for a high-end flagship device, it is around 10-15%. As memory prices continue to surge, OEMs will likely have to raise prices significantly, cut specifications or both.  

Different Vendors, Different Impacts 

The impact of the shortage is highly asymmetric, creating winners and losers on supply chain resilience and vertical integration. 

Manufacturers, whose business is mainly in the low end of the market, are likely to suffer significantly. The business models of vendors such as TCL, Transsion, Realme, Xiaomi, Lenovo, Oppo, Vivo, Honor or Huawei are based on thin margins. This increase in cost will hit their margins substantially, and they will have no other option but to pass the cost (or part) to end users. 

In the high end of the market, Apple and Samsung face pressure but are structurally hedged. Its cash reserves and long-term supply agreements allow it to secure memory supply 12-24 months in advance. On the other hand, new flagship models in 2026 will likely have no RAM upgrades, sticking to 12GB for Pro models rather than increasing to 16GB. It is also unlikely that current models will see the same price erosion seen after the introduction of the latest model. 

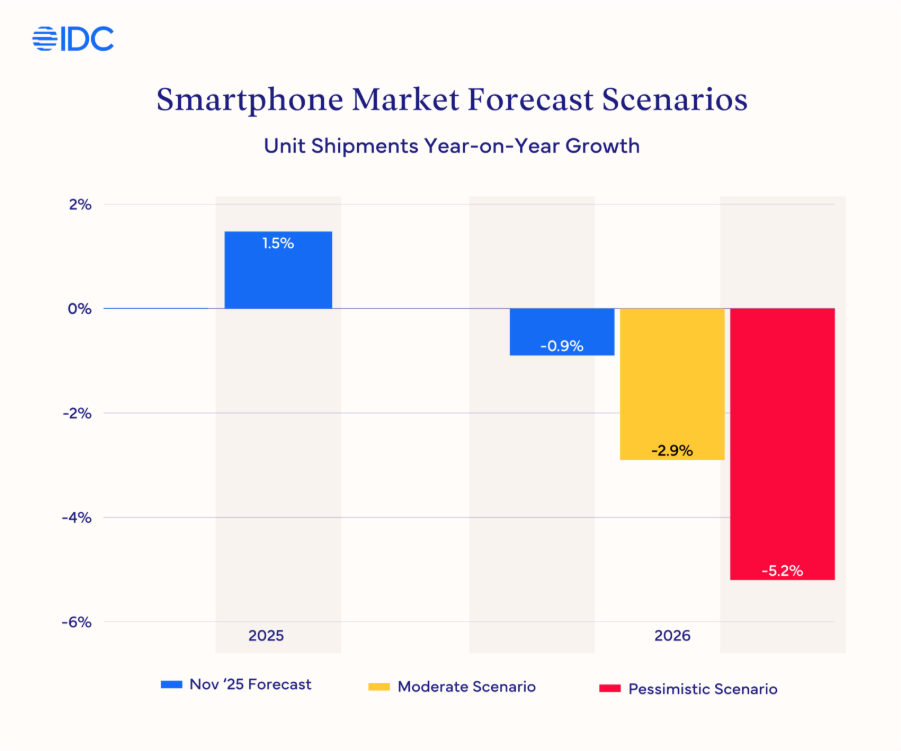
The cumulative effect of these pressures is a potential contraction in the global smartphone market alongside an increase in average selling prices (ASP). In 2026, in our moderate downside scenario, we could see the market contract by 2.9%. In our pessimistic downside scenario, it could be as bad as 5.2%. The severity of each scenario depends on how long this situation lasts. 

At the same time, smartphone ASPs could rise by 3% to 5% in the moderate scenario, or by 6% to 8% in the pessimistic scenario. These price rises will be significantly higher in the low end of the market, where margins are extremely tight, and OEMs will have to pass the cost to end users.  

But regardless of the severity of the scenario, longer replacement cycles are likely to occur in markets with rising costs causing lower purchasing power. By contrast, in more mature markets, consumers are likely to rely on financing and instalment plans to absorb higher prices. 

While there could be significant downside risk to volumes in 2026, we expect 4Q25 to outperform our earlier projections as vendors stocked channels ahead of price increases.   

Impact to the PC Market 

If the smartphone market is facing pressure, the PC market is bracing for disruption. The timing of the memory shortage creates a perfect storm for the PC industry, colliding with the Microsoft Windows 10 end-of-life refresh cycle and the AI PC marketing push.  

PC vendors are signalling broad price increases as cost pressures intensify into H2 2026. Lenovo, Dell, HP, Acer and ASUS have warned clients of tougher conditions ahead, confirming 15-20% hikes and contract resets as an industry-wide response.  

PC vendors with larger shipment volumes should be better positioned to navigate current supply constraints, enabling them to capture market share from smaller and regional brands. Regardless of how much the total market size may be impacted, we expect vendor market shares to shift in favor of the largest vendors armed with inventory and greater leverage with suppliers.  

White box as well as lower tier (often local) vendors, on the other hand, will bear the greatest burden of the shortage, and that would include DIY systems, oftentimes built by gamers. That in turn represents an opportunity for large OEMs to gain share from smaller assemblers in the gaming space by positioning pre-built systems as offering higher value.   

The Impact on AI PC 

The shortage threatens to derail the industry’s growth narrative around AI PC. IDC defines the AI PC as any PC with an NPU. Crucially, these devices tend to have more RAM (Microsoft’s Copilot+ PCs require a minimum of 16GB). As more small language models and large language models move on device, memory becomes even more important, with many higher-end systems shifting toward 32GB or higher. Just as the industry is seeing a need to add more RAM, it has become prohibitively expensive to do so, even if they can get supply. This will result in higher prices, lower margins, or a potential downmix in the amount of RAM in new systems at the worst possible time for this to occur. 

As with smartphones, IDC is not changing its official PC forecast. Here again, we offer two potential scenarios for 2026.  

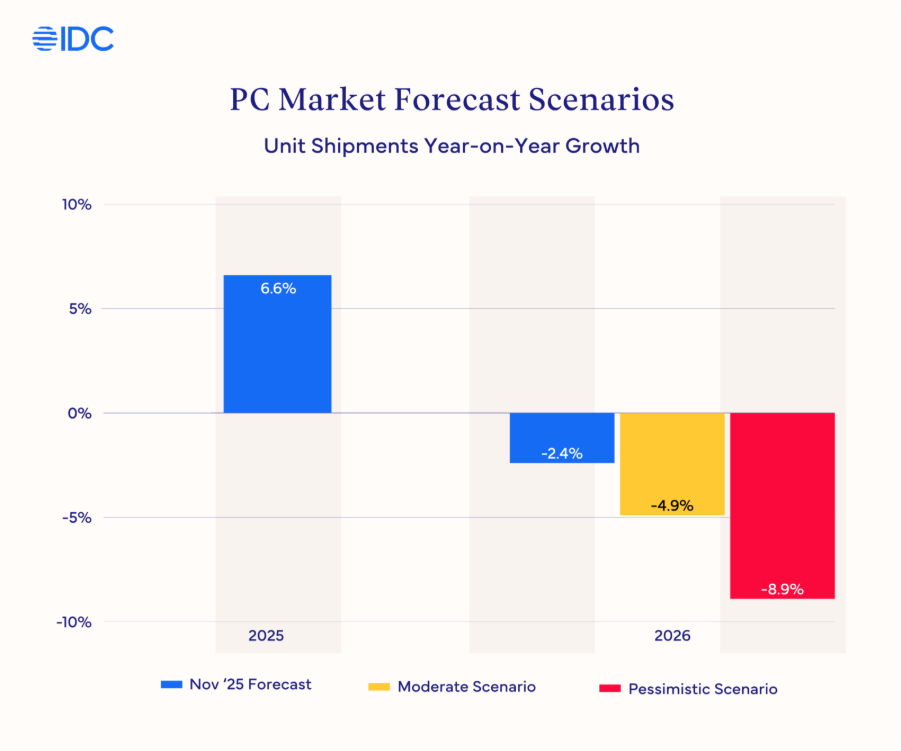
In the more moderate downside scenario, we could see the PC market contract by 4.9% compared with a 2.4% year-on-year decline in the November forecast. Under a more pessimistic scenario, the decline could deepen to 8.9%. The severity of each scenario will largely depend on how long the current supply constraints persist through 2026. 

Under these downside scenarios, PC average selling prices would likely rise, increasing by 4% to 6% in a moderate scenario, and by 6% to 8% in a pessimistic scenario.  

As with smartphones, channels are building inventory in advance to mitigate the impact of further price increases in the months ahead, which is expected to support stronger-than-expected forecast performance in Q4 2025, relative to the November outlook. 

Conclusion 

What began as an AI infrastructure boom has now rippled outward, with tightening memory supply, inflating prices, and reshaping product and pricing strategies across both consumer and enterprise devices. As the industry adjusts to this new reality, the smartphone and PC markets are bracing for a period of higher costs, altered product roadmaps, and slower volume growth. The severity and duration of the shortage will be determined by how quickly production capacity can expand and how effectively demand rebalances across segments. 

For consumers and enterprises alike, this signals the end of an era of cheap, abundant memory and storage, at least in the medium term. The year 2026 is shaping up to be one in which technology becomes more expensive, driven by supply constraints rather than demand growth. 

Francisco Jeronimo - Vice President, Data & Analytics - Devices - IDC

Francisco Jeronimo is VP for Data and Analytics at IDC EMEA. Based in London, he leads the research that covers mobile devices, personal computing devices, emerging technologies and the circular economy trends across EMEA. His team delivers data on personal computers, tablets, smartphones, wearables, PC monitors, PC gaming, enterprise Thin Client devices, smart home, augmented reality and virtual reality, and sales of used devices. He provides in-depth analysis of the strategies and performance of the key industry players.

Tom Mainelli - Group Vice President - IDC

Tom Mainelli heads the Device & Consumer Research Group, overseeing a wide array of hardware and technology categories that cater to both home and enterprise markets. His team's research spans PCs, tablets, smartphones, wearables, smart home devices, thin clients, displays, and virtual/augmented reality headsets. He also co-manages IDC's supply-side research team, which monitors display and ODM production across various categories. IDC's consumer research, anchored by the Consumer Market Model, employs regular surveys and proprietary models to forecast numerous consumer-focused activities and spending across hardware, software, and services. As Group Vice President, Tom collaborates closely with company representatives, industry contacts, and other IDC analysts to provide comprehensive insights and analysis on a diverse range of commercial and consumer topics. A frequent speaker at public events, he travels extensively, enjoying every opportunity to engage with colleagues and clients worldwide.

Bryan Ma - Vice President - IDC

Bryan Ma is Vice President of Client Devices research, covering mobile phones, tablets, PCs, AR/VR headsets, wearables, thin clients, and monitors across Asia as well as worldwide. Based in Singapore, Bryan provides insights and advisory services for both vendors and users, and coordinates his team of analysts in building IDC's core market data, analysis, and forecasts in these sectors. Bryan has been quoted in a number of publications, including The Wall Street Journal, The Economist, The Financial Times, BusinessWeek, The South China Morning Post, and The New York Times. He has been a featured speaker at numerous industry conferences and appears frequently as a guest commentator on television networks such as CNBC, Bloomberg, and the BBC.

Ryan Reith - Group Vice President, WW Device Trackers - IDC

Ryan Reith is the Group Vice President for IDC's Worldwide Device Tracker suite, which includes mobile phones, tablets, wearables, and most recently AR/VR. His teams research focuses on the quantitative aspects of the mobile device industry, including market sizing, forecasting, vendor market share analysis, and technology trends. His current responsibilities include engaging with mobile device OEMs, supply chain, distributors, and the financial industry to discuss market trends and forward looking analysis.

Jeff Janukowicz - Research Vice President, Solid State Drives and Enabling Technologies - IDC

Jeff Janukowicz is a Research Vice President at IDC where he provides insight and analysis on the SSD market for the Client PC, Enterprise Data Center, and Cloud market segments. In this role, Jeff provides expert opinion, in-depth market research, and strategic analysis on the dynamics, trends, and opportunities facing the industry. His research includes market forecasts, market share reports, and technology trends of clients, investor, suppliers, and manufacturers.

The global smart vacuum cleaner market didn’t just grow in 2025, it reorganized. Shipments reached 17.42 million units in the first three quarters of the year, up 18.7% YoY, with Q3 alone up 22.9%. Chinese brands; Roborock, Ecovacs, Dreame, Xiaomi, Narwal dominated the top five reflecting a structural shift powered by faster product cycles, ruthless price segmentation, and deep ecosystem plays. Consumers signaled what they value: AI-driven navigation, obstacle recognition, self-emptying docks, and seamless integration with voice and home platforms. Vendors that delivered those at mid-tier and entry-level prices won share while those that didn’t are now playing catch-up.

iRobot: A Pioneer That Missed the Turn

The news is unambiguous: iRobot filed for Chapter 11 and agreed to be acquired by its primary Chinese manufacturer, Shenzhen Picea Robotics, with the plan to take the company private and continue operations under Picea’s ownership. It’s an ending few expected a decade ago.

What caused the fall from grace? iRobot’s decline boils down to three things:

  • Tech posture: iRobot resisted LiDAR navigation for too long, opting for vSLAM (camera-based visual mapping) that proved less consistent in real-world homes and lighting conditions.
  • Price architecture: iRobot clung to premium pricing while rivals shipped better-specced mid/low SKUs globally.
  • Balance sheet & policy shocks: Debt refinancing and new U.S. tariffs raised costs just as competition intensified and the Amazon acquisition collapsed.

Market Implications

Innovation cadence beats incumbency – The winners executed rapid, visible upgrades such as the inclusion of LiDAR, AI, auto‑empty bases, low‑profile designs, and more. The pace of innovation sometimes led to multiple product releases a year while the laggards optimized margins and brand heritage. The market rewarded the former.

Ecosystems matter more than SKUs. Tight integration with Mi Home, Alexa, Google Assistant, regional retail, and services is now as important as suction ratings because it drives repeat purchase and lock‑in.

2026 Outlook: Five Predictions to Watch

AI Navigation Goes From ‘Specs’ to ‘Outcomes’. Expect vendors to market room‑level autonomy such as predictive pathing, dynamic no‑go zones, seasonal routines, rather than sensor acronyms. The winning KPIs will be coverage completeness, cleaning time, and failure‑free runs per week. Chinese leaders already test and iterate on these claims aggressively.

Platform Moats Deepen. Roborock/Ecovacs/Dreame will push first‑party apps and hubs into broader home control (air purifiers, mops, window cleaners). Xiaomi will double down on Mi Home stickiness. Other brands that can’t anchor a platform will lean on Amazon, Apple, and Google integrations and retail partnerships.

Design Improvements: Thin Is In — Smart vacuums are evolving to tackle real-world challenges with slimmer profiles that reach under low-clearance furniture, enhanced ability to clear taller thresholds, and AI-powered object recognition for hazards like cords, socks, and pet waste. These innovations are increasingly being brought to more affordable models, making advanced navigation and hands-off cleaning accessible to a wider audience.

Regionalization of Portfolios. MEA and parts of Europe will continue to outgrow North America, driven by tuned SKUs (tile/stone floor focus, water tank size, voltage standards) and offline retail investment. Brands that localize service and spares win loyalty.

Bottom Line (for 2026)

Expect Chinese brands to extend their lead, especially in Europe/MEA, on the back of holistic ecosystems and relentless iteration. Watch iRobot under Picea: it may emerge as a good-enough brand with improved navigation and cost structure, but it must earn back trust and relevance quickly. The consumer win continues: more capability at lower prices.

Jitesh Ubrani - Research Manager - IDC

Jitesh is a Research Manager for the Worldwide Mobile Device Trackers, including Wearables, Augmented Reality (AR), Virtual Reality (VR), Tablets, and Phones. The team focuses on the market sizing, forecasting, and analyzing trends to provide insight into the competitive landscape of the worldwide mobile industry. Prior to joining IDC in 2012, Jitesh was part of the Market Analysis and Intelligence team at Bell Mobility, one of Canada's largest telecom service providers, where his role focused on understanding smartphone adoption and usage as well as consumer purchasing behavior. Mr. Ubrani holds a bachelor of commerce degree with a major in Economics from Ryerson University and is currently based in Toronto, Canada.

After 38 years with IDC, I have decided that it’s the right time to step into the next chapter of my career. Beginning in January, I will transition out of my current role into supporting the company as a Special Advisor, where I will continue to champion IDC and the critical role we play in guiding the technology community forward. 

When I joined IDC as an associate research analyst, I could not have predicted the opportunities and experiences that would follow. I was drawn to IDC because of its unique vantage point on the technology industry, and I stayed because of two things: the constantly changing nature of technology and its impact on the world, and the opportunity to learn from some of the smartest people in the industry—across IDC, our customers, and the broader market. 

Throughout my career, I’ve had the privilege of working with exceptional colleagues and leaders who shaped IDC’s global research and data offerings. Together, we created, honed, and strengthened IDC’s position as the trusted source for technology intelligence used by organizations around the world. 

What’s next 

During my time here, IDC has evolved through multiple technology cycles—from client/server, to mobility and cloud, and now AI. With strong leadership, a talented global team, and a clear vision for what trusted tech intelligence looks like in the AI era, IDC is stronger than ever. 

To my colleagues: thank you for your dedication, your partnership, and the professionalism that defines IDC. 

And to our customers and partners: thank you for trusting us with your most important decisions and challenging us to continuously raise the bar. 

IDC’s future is bright and I am excited to support it.  
 

Crawford 

Crawford Del Prete - President - IDC

Crawford Del Prete was appointed President of IDC in February 2019. Prior to his current role, he served as IDC's Chief Operating Officer. Through his leadership, IDC has established a leading position as the world's most prominent and trusted technology market intelligence provider. Crawford joined IDC in 1989 as a research analyst. Throughout his IDC career, he has grown multiple IDC businesses to industry leadership positions. He was instrumental in creating IDC's high visibility research and data tracking products which are used daily in the IT industry for strategic planning. Crawford is a leading authority on the IT industry and has completed extensive research on the structure and evolution of the information technology industry. He advises technology and business leaders on how to adapt and change in a time when technology is changing the world. He is frequently quoted in publications such as The Wall Street Journal, The Financial Times, The New York Times and other leading media sources. He is a regular guest on Bloomberg Technology TV, offering insight and perspective on daily technology events. He was awarded The Patrick J. McGovern Award for Management Excellence in 2014. In 1995, he was awarded IDC's James Peacock Award for research excellence, IDC's highest research honor. He holds a B.A. from Michigan State University and in 2012, he was named a Distinguished Alumni of the University. Follow Crawford on Twitter @craw.

As the IDC Government Insights team developed this year’s IDC FutureScape: Worldwide Smart Cities and Communities 2026 Predictions, one trend became clear: cities of all sizes are rapidly adopting LLM-driven AI tools. As cities confront tighter budgets, rising public needs, and the accelerating pace of AI adoption, two predictions stand out: One prediction on Agentic AI and workflow orchestration, and the other on unlocking the value of government data through fine-tuned large language models (LLMs).

Together, these prediction signal a shift from technology-as-a-tool to technology-as-a-teammate (or as “a personal intern”)— where intelligent systems collaborate with humans to simplify complexity, bridge data silos, and elevate service delivery. For mayors, CIOs, and innovation officers, this is more than automation, it’s a reimagining of how government works.

Agentic AI Connects the Dots Across City Systems

By 2027, 65% of cities will deploy AI agents across systems and data to orchestrate end-to-end workflows and reduce workloads while addressing risks of misuse and overreach and “process debt.”

Local governments have long wrestled with what IDC has termed “process debt” — the accumulated workflow inefficiency of fragmented systems, redundant data entry, and manual workarounds. Agentic AI changes that equation. Unlike traditional AI models built for narrow tasks, AI agents can understand goals, coordinate across systems, and execute full workflows — from processing applications to reconciling budgets to automating permit approvals.

But this evolution demands groundwork. Before AI agents can drive real impact, state and local governments must map workflows, clean data, and redesign processes that currently constrain efficiency. As we often discuss, automating broken processes “rarely delivers better outcomes.” Instead, success depends on combining automation with human oversight, workforce readiness, and transparent governance.

Human + Machine Collaboration

Agentic AI will shift how public sector teams work — not by replacing people in the near-term, but by augmenting their capacity. Entry-level clerical roles may evolve, but new opportunities will emerge for “AI process managers,” ethics officers, and cross-agency data specialists. IDC emphasizes that HR must be a strategic partner in this transformation, guiding reskilling and maintaining morale during rapid change.

The payoff? Smarter workflows, faster decisions, and lower service delivery costs. When AI agents manage the repetitive, city staff can focus on what humans do best — strategic decisions, innovation and empathetic human interactions.

Unlocking the Hidden Value of Government Data

By 2026, 50% of state and local governments will invest in fine-tuning LLMs on data the models have never seen, unlocking value from decades of protected records and siloed systems.

Every city sits on a goldmine of data — from zoning and traffic to health, housing, and economic development. Yet much of it is trapped in systems that don’t talk to each other; not only that, this data is private and has not been used to train the LLMs that are serving up GenAI results.

The next wave of Smart City innovation will come from fine-tuning LLMs on this untapped data. Cities will begin training models on internal records — with strict governance — to capture local context and institutional knowledge. The result: AI systems that “speak government”, understand regulatory nuances, and generate insights and recommendations grounded in real municipal operations. This provides faster insights for planning decisions and actions that support mission outcomes.

From Locked Archives to Living Intelligence

Imagine an AI system trained on decades of urban planning documents, council minutes, and building permits. It could summarize past precedents for new zoning requests, detect policy inconsistencies, or surface patterns in infrastructure maintenance failures. Or consider a model fine-tuned on social services data — capable of predicting which households may need early intervention to prevent homelessness.

These capabilities hinge on one foundation: responsible data governance. IDC advises governments to invest in “AI-ready data” — standardizing formats, labeling metadata, and implementing data governance technologies to ensure security and trust. As models become more specialized, leaders must also modernize infrastructure, upgrading government clouds and integrating intelligent computing power to support large-scale inferencing.

Bringing It Together: The Convergence of Agentic AI and Data Intelligence

The two predictions are two sides of the same coin. Agentic AI depends on data liquidity; data intelligence depends on intelligent orchestration. Together, they form the digital nervous system of the future city.

As IDC’s broader FutureScape 2026 report underscores, the Smart City of the near future is not just connected — it’s context-aware. AI agents will move seamlessly across departments, drawing on fine-tuned LLMs to provide decisions informed by a city’s own history and conditions.

The FutureScape highlights key trends:

  • Agentic AI is the next leap in digital government, transforming automation into orchestration across workflows.
  • Fine-tuned government LLMs will unlock decades of hidden data, fueling more contextual and accurate decision-making.
  • Responsible governance is the foundation — without ethical frameworks, AI progress can erode rather than build trust.
  • The future is collaborative: Humans define intent and context; AI executes and optimizes — together delivering public value faster and smarter.

Guidance for City Leaders

Smart City success depends not just on adopting AI, but on designing for agility, responsibility, and inclusion. Based on Predictions 1 and 6, here are three critical actions:

  1. Modernize the Data Core
    Build secure, interoperable data platforms that connect siloed systems. Invest in metadata management, data lineage, and ethical AI governance frameworks that prepare your data for fine-tuning and automation.
  2. Pilot Agentic Workflows in High-Impact Areas
    Start small but strategic — automate processes where the value is measurable (e.g., licensing, fleet maintenance, or procurement). Use sandboxed environments to test AI agents safely before scaling.
  3. Center People in the Process
    Partner with HR to redefine job roles and develop AI literacy. Transparent communication and change management are essential to maintain public trust and employee confidence.
  4. Design for Accountability and Transparency
    Incorporate audit trails, explainable AI, and citizen feedback loops. The legitimacy of AI-driven decisions will determine long-term success more than the sophistication of the technology.

The FutureScape 2026 predictions make one thing clear —when agentic AI and data governance converge, cities can be better proactive orchestrators of well-being, equity, and sustainability.

Cities like Boston, Singapore, and Barcelona are already using AI-powered urban planning platforms to integrate policy, climate, and citizen feedback — showing how government-specific data can supercharge innovation responsibly. These early movers demonstrate what’s possible when leaders treat AI not as a black box but as a civic partner.

As Smart City leaders plan their 2026 strategies, now is the time to evaluate your readiness for agentic AI and data-driven transformation.

If your city is already advancing innovative, AI-enabled initiatives, consider submitting your project for the IDC 2026 Smart Cities and Communities North America Awards, now open for nominations.

Ruthbea Yesner - Program VP - IDC

Ruthbea Yesner is the Vice President of Government Insights at IDC. In this practice, Ms. Yesner manages the US Federal Government, Education, and the Worldwide Smart Cities and Communities Global practices. Ms. Yesner's research discusses the strategies and execution of relevant technologies and best practice areas, such as governance, innovation, partnerships and business models, essential for government and education transformation. Ms. Yesner's research includes analytics, artificial intelligence, Open data and data exchanges, digital twins, artificial intelligence, the Internet of Things, cloud computing, and mobile solutions in the areas of economic development and civic engagement, urban planning and administration, smart campus, transportation, and energy and infrastructure. Ms. Yesner contributes to consulting engagements to support K-12 and higher education institutions, state and local governments and IT vendors' overall Smart City market strategies.

AI will continue to shape the enterprise communications landscape in 2026, with organisations seeking practical value while navigating cost, governance, and deployment constraints. Interest in AI is high, but companies still face gaps around affordability, readiness, and real-world use cases. As a result, the market will progress through grounded, incremental steps, supported by stronger data foundations, evolving pricing models, and greater collaboration across ecosystems and service partners.

1. AI Adoption Will Remain Pragmatic and Focused on Clear ROI

AI will continue to gain momentum, but organisations will prioritise capabilities that deliver immediate, measurable value, such as summarisation, transcription, call insights, and automated follow-ups.

While interest in agentic AI grows, mainstream adoption will be limited by cost and narrow use-case readiness. Vendors will increasingly focus on making agentic capabilities more affordable, modular, and easier to deploy.

2. Data Foundations Will Become the Enabler for Context and Automation

As organisations look into value extraction, data quality and connectivity become essential. AI will need access to contextual, structured, and cross-functional data to deliver accurate outcomes and automate workflows.

To meet these needs, vendors will open their ecosystems, deepen integrations with CRM, ERP, and workflow tools, and begin supporting agent-to-agent orchestration (A2A/MCP) across front-, mid-, and back-office processes.

3. Pricing Models Will Evolve to Reflect AI Consumption Patterns

As AI features become more widely used, traditional subscription pricing will feel less aligned with the way organisations actually consume AI. Vendors will gradually introduce usage-based or metered models, allowing customers to scale AI adoption at their own pace.

To ensure reliability, AI will increasingly blend generative and deterministic approaches, supported by stronger AI observability to maintain accuracy and trust.

4. Verticalisation and Professional Services Will Help Close the Adoption Gap

AI adoption challenges vary significantly by industry. In 2026, more vendors will develop vertical-specific UC&C solutions that reflect distinct workflows in sectors such as healthcare, retail, financial services, and manufacturing.

Because the gap between vendor innovation and customer adoption persists, vendors will collaborate more closely with professional services providers who can translate innovation into practical transformation through guided deployment and workflow redesign.

5. Europe Prioritises Hybrid Deployment and Democratized AI for SMBs

In Europe, concerns around data sovereignty and transparency will continue to influence technology decisions, prompting sustained interest in private cloud and selective retention of on-premises components. Most organisations will move toward hybrid models that offer both innovation and control.

At the same time, European vendors will intensify their focus on SMBs, which represent the bulk of the region’s economy. 2026 will see continued efforts to democratise AI, offering simpler, lighter-weight solutions—such as AI receptionists—as well as modular capabilities that make AI adoption accessible to smaller businesses via partner-led delivery.

Conclusion

In 2026, enterprise communications will move forward through practical AI adoption, deeper data integration, flexible pricing, verticalised innovation, and hybrid deployment models. Markets like Europe will emphasise sovereignty and SMB accessibility, but globally, success will depend on vendors balancing innovation with pragmatism—offering AI that is trustworthy, affordable, and genuinely transformative for how people and organisations communicate and work.

For more information, drop your question in here.

For more predictions, watch IDC’s EMEA FutureScape predictions webcast here.

Oru Mohiuddin - Research Director - IDC

Oru Mohiuddin is a Research Director in the European Enterprise Communications and Collaboration team. Based in London, she is responsible for IDC’s coverage of Unified Communications and Collaboration in the region. Her work focuses on tracking the markets for premise-based and cloud solutions and new developments and trends, particularly in the light of changing work patterns impacting the traditional mode of enterprise communication. Prior to joining IDC, Oru worked for Euromonitor International, where she focused on Future of Work and technology in the SMB context. She also worked in New York and Bangladesh and speaks English and Bengali. Oru was awarded Chevening Scholarship by the British Foreign and Commonwealth Office to pursue her MSc in International Development from the University of Birmingham. In addition, Oru has a BA from Marymount Manhattan College in New York.

Graham Fruin - Senior Research Analyst, European Enterprise Communications and Collaboration - IDC

Graham Fruin is a senior research analyst in IDC's European Enterprise Communications and Collaboration team. Based in the U.K., his primary focus is on the voice and data connectivity markets. His work has a particular emphasis on the migration from legacy voice solutions to IP-based platforms and the way they are used in conjunction with unified communications. In addition, he analyzes the evolution of the internet access market, which includes the rapid proliferation of Fiber to the Premises (FttP) across Europe.

In 2026, the consumer technology landscape will not be defined by any single breakthrough, but by the convergence of many. Artificial intelligence, once a novelty, is becoming a companion. Agentic AI—systems that act on our behalf—will quietly weave itself into the fabric of daily life. From digital therapists to AI fashion designers, the consumer experience is evolving in ways that feel both exhilarating and uncertain.

How AI Is Reshaping the Everyday Consumer Experience

The Rise of Gaming as the New Social Platform

Let’s start with the familiar: social media and entertainment. For younger generations, gaming has surpassed traditional social platforms as the preferred means of connection. It’s not just about play; it’s about presence. Virtual worlds are becoming the new public squares, and the lines between creator and audience continue to blur. As AI-generated content continues to grow exponentially, the feed will soon feel less like a window into our friends’ lives and more like a reflection of the collective imagination: curated, algorithmically enhanced, and infinitely scalable.

AI Generated Content and the Search for Trust

But this abundance brings a new kind of scarcity: trust. When anyone can generate professional-quality content at the tap of a prompt, the question shifts from “Can I create this?” to “Can I believe this?” Consumers will increasingly gravitate toward authenticity and brands, creators, and platforms that prove what’s real. Paradoxically, the same technologies that blur the lines between truth and fiction may also help rebuild trust, as AI-driven verification and blockchain-based provenance tools become integral to the digital experience.

Emotional AI Companions and the Changing Definition of Care

Meanwhile, the definition of care is changing. Many consumers are already turning to AI companions for support and self-reflection, redefining what therapy and connection look like. This trend says as much about access and affordability as it does about comfort with machines. For some, these AI listeners will offer judgment-free emotional support; for others, they may highlight just how transactional our relationships with technology have become. The opportunity is enormous, but so is the ethical weight: How do we ensure empathy doesn’t become an illusion?

Home Cybersecurity Becomes a Daily Essential

Security, too, is being redefined. The home network, once a patchwork of passwords and devices, is fast becoming a managed ecosystem. Cybersecurity is emerging as a household utility—not an optional service, but a baseline expectation. The idea of paying a monthly fee to protect your family’s digital life will feel as natural as paying for electricity. Yet the same networks that safeguard us will also collect more behavioral data than ever before, creating a delicate balance between safety and surveillance.

AI in Fashion and the Future of Personal Identity

Elsewhere, new rituals of consumption are taking shape. In fashion, AI is learning our tastes faster than we can articulate them. Intelligent design systems are already shaping collections, anticipating preferences, and personalizing garments in real time. It’s a model that can cut waste and returns, but it also raises questions about identity and expression. When algorithms dress us, do they amplify individuality or narrow it to what the data thinks we want?

Augmented Reality and the Return of Local Connection

And then there’s augmented reality: the layer of digital context now emerging atop our physical world. Increasingly, consumers will engage with hyper-local AR experiences that blend art, culture, and commerce. The technology is no longer about novelty; it’s about connection. Imagine walking through your neighborhood and seeing local art, history, or community stories overlaid on the landscape. AR has the potential to restore a sense of place in an increasingly placeless digital age.

Deepening Human Machine Relationships

Threading through all of this is a new kind of intimacy between humans and machines. Emotional bonds with AI systems are deepening as interactions become more personal, responsive, and persistent. That reality alone should give us pause. For decades, technology has mediated our relationships with one another; now it is becoming one of those relationships. Governments and platforms alike are beginning to explore ethical and legal frameworks to protect people from exploitative or deceptive AI companionship. This is a necessary step as emotional computing becomes mainstream.

These shifts aren’t uniformly positive or negative. They reflect a world moving from transaction to immersion, from ownership to orchestration, from control to collaboration. The question for leaders across industries is not whether AI will shape consumer behavior—it already has—but whether we will shape it responsibly. The future consumer will demand more than convenience; they will demand confidence in privacy, authenticity, and purpose.

How Technology Providers Can Lead With Trust and Transparency

The crosscurrents of innovation, trust, and identity are strong. Navigating them requires clear strategy and steady ethics. Because in this next era, technology won’t just serve us—it will know us, represent us, and, increasingly, reflect who we are.

For technology vendors, the challenge is to lead with empathy and accountability. Consumers will reward brands that prioritize transparency, data stewardship, and meaningful engagement over novelty. For B2C and B2B2C innovators alike, the future belongs to those who design AI experiences that empower rather than manipulate, that personalize without intruding, and that build trust as deliberately as they build code. In a world of intelligent systems, trust will be the ultimate differentiator.

To explore these insights in greater depth, check out the IDC FutureScape: Worldwide Consumer 2026 Predictions. It offers a comprehensive view of how AI, trust, and emerging technologies are transforming the consumer landscape—and what technology vendors can do today to prepare for tomorrow.

Tom Mainelli - Group Vice President - IDC

Tom Mainelli heads the Device & Consumer Research Group, overseeing a wide array of hardware and technology categories that cater to both home and enterprise markets. His team's research spans PCs, tablets, smartphones, wearables, smart home devices, thin clients, displays, and virtual/augmented reality headsets. He also co-manages IDC's supply-side research team, which monitors display and ODM production across various categories. IDC's consumer research, anchored by the Consumer Market Model, employs regular surveys and proprietary models to forecast numerous consumer-focused activities and spending across hardware, software, and services. As Group Vice President, Tom collaborates closely with company representatives, industry contacts, and other IDC analysts to provide comprehensive insights and analysis on a diverse range of commercial and consumer topics. A frequent speaker at public events, he travels extensively, enjoying every opportunity to engage with colleagues and clients worldwide.

The linear supply chain, which was optimized solely for cost, speed, and sequential handoffs, is over. In this model, if one link breaks, the entire chain comes to a halt, as there is no built-in redundancy or networked capability to navigate around the problem. As we look toward 2030, the key characteristic of successful operations is no longer just efficiency; it is intelligence at scale. This shift to an “ecosystem” or “network” model is critical for 2026 and beyond.

The last few years have served as a brutal stress test for legacy models, exposing structural fault lines that “optimization” can no longer hide. In late 2024 and throughout 2025, we witnessed a convergence of volatility that linear chains simply could not absorb.

Three specific industry failure modes have emerged from this period, signaling why a new direction is inevitable:

  • The Tier-N Blindspot (The Visibility Gap): A major automotive manufacturer recently halted production when a climate event impacted a Tier 3 sub-component provider. Lacking multi-tier visibility, the planning team remained unaware of the risk until Tier 1 shipments ceased.
  • The “Digital Tower of Babel” (The Interoperability Gap): During recent port congestions, manual handoffs between disparate systems prevented logistics networks from adapting, causing cascading delays. Agile firms pivoted instantly using open platforms while traditional operators remained trapped by disconnected data.
  • The Expanded Attack Surface (The Security Gap): Rapidly increasing IT and OT connectivity without robust security has turned supply chain networks into prime targets for ransomware, cyber-physical attacks on IoT equipment, and AI-enabled attack vectors. Enterprises are deploying distributed, AI-driven systems to proactively neutralize risks from external partners to internal operations.

These are not isolated incidents; they are the growing pains of a sector in transition. They underscore why the next five years will not be defined by better silos, but by the dissolution of silos altogether.

These insights reflect IDC’s 2026 FutureScape: Worldwide Supply Chain and Industry Ecosystems research, which outlines the forces reshaping global operations and the capabilities leaders must prioritize. Explore the full predictions in the global report.

Emerging from this volatility are three distinct trends that will define the path to 2026 and beyond.

1. Multi-Enterprise Orchestration: Visibility That Extends Beyond Boundaries

Disruptions now emerge across extended supplier tiers, logistics partners, and regional networks. Traditional visibility approaches anchored in ERP data and Tier 1 insights are no longer sufficient.

Supply chains must evolve into multi-enterprise networks that enable:

  • Real-time visibility beyond Tier 1 suppliers
  • Shared alerts and contextual intelligence among all partners
  • Coordinated response actions across nodes

This shift moves visibility from a standalone tool to an integrated capability woven through planning, execution, and risk management.

As a result, IDC predicts(1):

By 2028, 50% of enterprise-scale supply chains will use business networks to enable n-tier visibility, serving as a key mechanism to reduce the impact of disruption and improve response speed by 25%.

Organizations that build this foundation gain faster detection, more accurate impact assessment, and greater confidence under volatility.

2. Supplier and Partner Ecosystems: Interoperability as a Performance Multiplier

The ability to work seamlessly across partner ecosystems will define future competitiveness. Interoperability, once a technology challenge, is now a strategic one.

Next-generation supply chains require platforms that:

  • Integrate supplier, logistics, and customer systems with minimal friction.
  • Support shared workflows, not just shared data.
  • Enable AI agents to operate across organizational boundaries.
  • Maintain consistent process logic, metrics, and governance across nodes.

As more partners connect to shared platforms, these networks become orchestrated ecosystems rather than loose collections of bilateral relationships.

As a result, IDC predicts:

By 2029, 45% of G2000 companies will have adopted agentic AI–driven channel management and orchestration, driving a 20% revenue uplift and a 30% improvement in partner and customer satisfaction scores.

This interoperability amplifies agility: when market conditions shift, changes cascade across partners in hours, not months.

3. Data Foundations and Distributed AI-Driven Security: Trust at Ecosystem Scale

As supply chains become more interconnected, the surface area for cyber and data risk expands dramatically. At the same time, AI’s effectiveness depends on high-quality, secure, and interoperable data.

A modern supply chain must invest in:

  • Federated data models enabling domain-level control with shared standards.
  • Governance frameworks, ensuring consistent semantics, lineage, and quality.
  • Distributed AI-driven security that continuously assesses ecosystem risk.
  • Zero-trust principles applied across suppliers, platforms, and data flows.

Trust is no longer about internal compliance. It is about ensuring safe, reliable data movement across the entire network, because partner data is now operational data.

As a result, IDC predicts:

To secure supply chains, by 2030, 60% of large enterprises will deploy distributed AI-driven cybersecurity, enabling proactive third-party risk management as AI adoption intensifies cyber risks.

These foundations ensure AI-driven decisions are grounded in secure, high-integrity data flowing consistently across partners. Trust now means ensuring safe, reliable data movement across the network—partner data is operational data.

Future Imperatives for Operations and Supply Chain Leaders

The predictions point to one conclusion: supply chains must operate as intelligent, interconnected ecosystems. To lead in this environment, COOs and CSCOs should focus on five strategic imperatives anchored in the three core themes.

1. Transform N-Tier Visibility into Operating Infrastructure

Treat your supply chain as a system of systems. Visibility must shift from periodic reporting to a live intelligence layer that detects disruptions at their source, whether in a sub-tier supplier or a regional hub. Establish shared workflows and coordinated decision-making models to reduce blind spots and shorten recovery times.

2. Architect for Interoperability to Accelerate Execution

Shift from one-off integrations to platform-based ecosystems where suppliers, carriers, and manufacturers connect with minimal friction. When systems “speak” fluently, coordination becomes orchestration, leading to fewer handoffs, lower latency, and faster alignment under stress. Select platforms that enable partners to plug in without extensive customization.

3. Treat Data Readiness as the Precursor to AI Scale

AI agents cannot scale without clean, governed, and interoperable data. Conduct a cross-functional audit of data availability and structure. Ensure that core datasets, including supplier, logistics, and product data, are aligned and secure. Data readiness is now AI readiness; without it, advanced capabilities like automated forecasting and risk sensing will fail.

4. Embed Distributed Security as a Resilience Pillar

As connectivity grows, security becomes the foundation that protects visibility and orchestration. Integrate third-party cyber assessments into supplier scorecards and deploy continuous monitoring tools. Adopt zero-trust principles across systems and data flows to detect anomalies early and maintain continuity even when threats emerge elsewhere in the network.

5. Leverage Ecosystem Intelligence for Value Beyond Productivity

Use interoperable platforms to enable new service models, dynamic capacity sharing, and sustainability-led optimization. Expand the definition of value to include resilience, customer trust, and ecosystem performance, turning the network itself into a competitive advantage.

The Leadership Mandate

Supply chains are becoming ecosystems. AI will accelerate this shift, but its value depends on network strength: visibility, interoperability, and data integrity.

Leaders must champion modernization that aligns partners, platforms, and data—core to strategic growth and operational continuity.

Investing in multi-enterprise orchestration, ecosystem interoperability, and AI-ready data foundations enables organizations to build responsive, resilient, future-ready supply chains.

Join Stephanie Krishnan for an upcoming webinar on 24 February 2026, 1:30 PM SGT on what agentic AI readiness means in Asia Pacific and how organizations can move from proof of concept to production responsibly. Register now!

Stephanie Krishnan - Associate Vice President - IDC

Stephanie Krishnan leads IDC’s Asia/Pacific research and advisory for supply chain, manufacturing, retail, and adjacent industry domains. As Associate Vice President for IDC Insights, she guides organizations through the rapid transformation toward digitally enabled, AI-driven, and highly interconnected operations. Her work centers on the future of supply chain ecosystems, operational resiliency, sustainability, and the rise of agentic and autonomous decision-making across global networks.

Announced 5th December, these increases are set to take place from the 1st July 2026 and will impact most Enterprise subscribing customers at their next major agreement renewal. Using justification for increases based on additional features, functionality and AI elements, these increases affect customers of all types in all territories and currencies. These list price increases differ from the recently announced changes to automatic entitled volume license discounts and whilst pricing is still negotiable, list price increases will ultimately influence end customer pricing.

Microsoft 365 SuiteCurrent List PriceJuly 1st 2026 List PriceIncrease %
Microsoft 365 E3$36.00$39.008%
Microsoft 365 E5$57.00$60.005%
Microsoft 365 F1$2.25$3.0033%
Microsoft 365 F3$8.00$10.0025%
Office 365 E3$23.00$26.0013%
Business Basic$6.00$7.0017%
Business Standard$12.50$14.0012%
Pricing in other currencies and territories are expected to increase by similar deltas

Of specific note are the exceptionally large increases to Frontline Worker SKU’s, typically deployed by customers with shared computer environments, providing more cost-effective options for these users than Full User licenses, with the savings delta now significantly impacted by this price increase. Customers utilizing these products should carefully plan and consider their current position and forward strategy.

Whilst these price increases impact all customers, government customers specifically will see these increases in some cases split across a two-year period. The timing of actual impact may be dependent on agreement renewal timing.

What this means

For most customers subscribing to these products governed by a current Enterprise Agreement (EA) or Enterprise Agreement Subscription (EAS), Microsoft may look to assert increases on renewals after July 1st 2026 . Until renewal customers with these agreement types will typically have agreed pricing which will be unimpacted.

Whilst some of these increases look to be close to inflationary increases (E5), many enterprise customers already have negotiated discounts, and renewing customers would almost always see cost increases at renewal through the reduction of discounts and/or the ramping of discounts during the agreement term. This is important as these new list price increases may be levied in addition to discount reductions, therefore customers should expect larger increases than perhaps previously anticipated.

IDC Sourcing Advisory Services had already observed more restrictive discounting for Frontline Worker products and customers with these can expect to see large compound increases at renewal. We note that the F5 addon product is not currently in scope of these increases, however as this is an add-on product, customers will still be impacted overall.

With the removal of entitled discounts, the path is now clear for Microsoft to assert more aggressive unit cost increases, through both these list price increases and discount reductions

Also, customers with Unified Support face a double impact through these price increases, as their Unified Enterprise Base cost is calculated on a percentage of categorized product spend, and any product cost increases will result in Unified Support increases. These cost increases may not necessarily be co-termed to the wider renewal or when the price increases impact the customer, indeed these may come at a later date. Customers should look at the impact across agreements not only to budget but also to provide leverage for future negotiations.

What can Enterprise Customers do

Notwithstanding typical Microsoft renewal actions and strategies, customers should immediately consider the following;

  • Act early & Plan now – Customers should begin assessments now, and in some cases may look to shift contractual timelines, so as to mitigate some of these cost increases in the near term
  • Pricing is Negotiable – Whilst list prices might increase, Microsoft continues to incentivize customers and pricing is always negotiable.
  • Leverage – Customers can seek to leverage many aspects of direct and indirect Microsoft investments and strategic product adoptions in order to drive optimal pricing. Collating current investments and identifying future requirements, even seemingly unrelated ones such as Azure, will help to build an overall investment growth profile and negotiation leverage
  • Strategy – As always customers should develop a renewal strategy, aligned to their technology strategies, to drive optimal product selection, rationalization, adoption and negotiations. However, customers should now take a specific view on the potential impact of these increases and how this strategy may be influenced by, or equally influence, future Microsoft commercials
  • Frontline Workers – Where customers subscribe, or plan to subscribe, to Frontline Worker SKUs, careful impact assessment and value analysis might be undertaken with a view to identifying risks and opportunities for mitigation.
  • Early Renewal – Customers may consider renewing their current agreement early, prior to 1st July 2026, to maximize price protection, however should carefully balance this on the understanding that early renewal pricing may likely increase overall costs in the immediate term.
  • Extensions – Those customers with contractual Extension options with fixed pricing might plan to utilize these in order to extend price protection durations.
  • Alternatives – Where customers are egregiously impacted by the changes, or where the full functionality of the suites is not being leveraged, customers may choose to realign their requirements and potentially look to competitive solutions. These options may provide direct cost mitigation and/or give competitive leverage when commencing renewal discussions.
  • Benchmarking – With global variance in discounts and incentive funding customers should benchmark their Microsoft investments and renewals against their peers and the market to ensure they are cost optimal and provide independent justification for decisions and change.

Summary

In summary these price increases, in tandem with potential reductions in discounts, present some clear commercial cost challenges for many Microsoft customers, in some cases significant ones. For Enterprise customers pricing remains negotiable and those customers that act early and assess the impact of these changes may identify opportunities for successful mitigation and cost optimization.

Neil Stewart - Vice President-Software Contracting Advisory (Major Vendors) - IDC

Neil Stewart, IDCs Senior Research Director for the Sourcing Advisory Service, provides expert coverage and insight into the Software Procurement and Commercial Market for Global Customers. Focusing on Major Software Vendors, Mr Stewart provides research, data and competitive intelligence helping customers to optimise their Software Investments, providing research and commercial insight on optimal pricing, contract vehicles and terms, available concessions, and proven negotiation strategies. Where Vendors might be transitioning to new product offerings, or where customer requirements are yet to be fully developed, he also provides more consultative assistance and strategic insight helping organisations both right-size software services and product requirements, but also understand their ongoing investments, entitlements and contractual responsibilities.